
 Electric Vehicle HVAC Market | 2026-2036
Electric Vehicle HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle HVAC Market Analysis
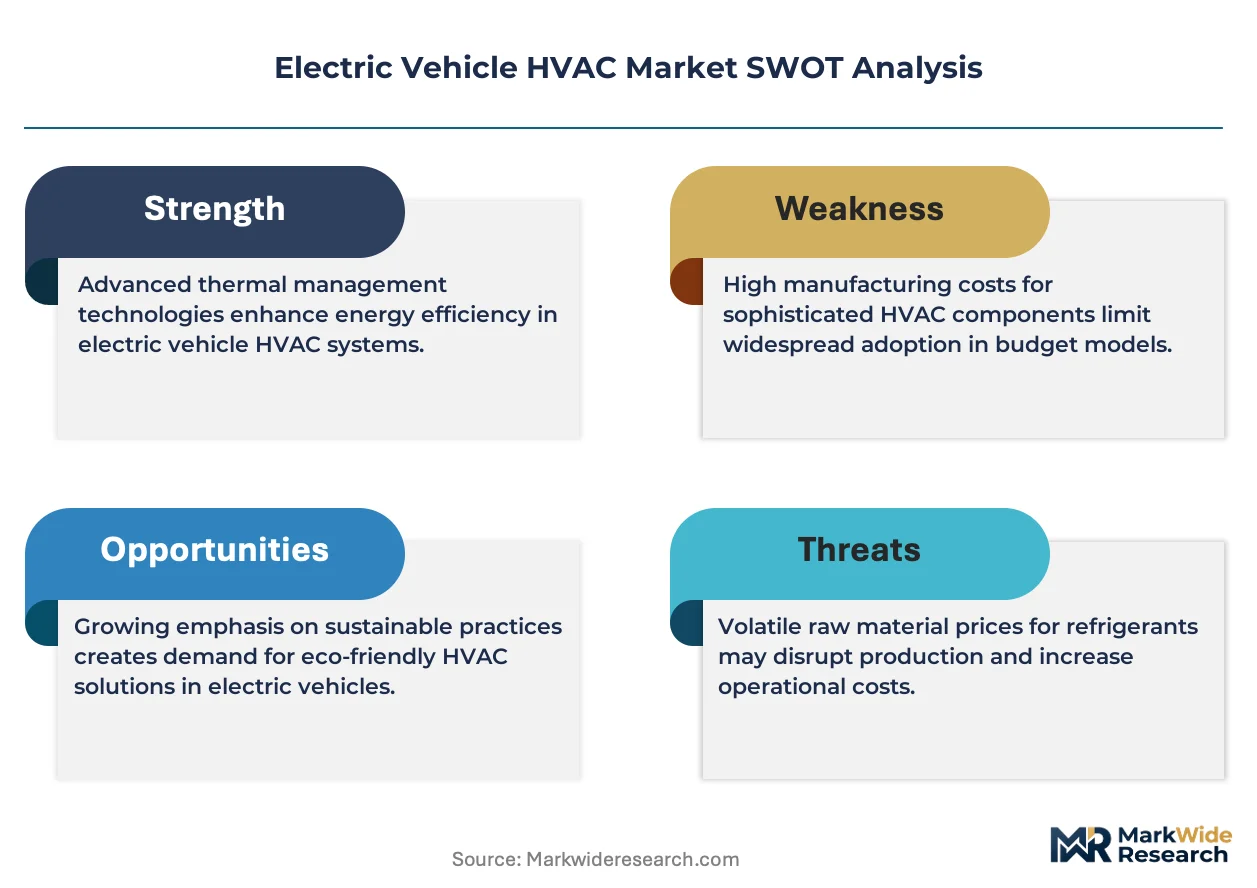
A shortage of thermal systems engineers fluent in refrigerant chemistry and electric powertrain integration is redrawing competitive boundaries across the supply base. MAHLE GmbH leverages its Stuttgart R&D campus to anchor development of integrated heat pump modules for European OEM platforms. DENSO Corporation sustains manufacturing scale through its Kariya operations, while Valeo SA differentiates via smart climate algorithms that optimize battery range in cold weather.
Electric Vehicle HVAC encompasses the complete thermal management architecture—compressors, heat exchangers, refrigerant loops, and control electronics—that regulates cabin temperature while preserving battery performance and longevity. These systems typically operate on voltages from 400V to 800V DC, with coefficient-of-performance targets above 3.0 for heat pump configurations in sub-zero conditions. Heat pump systems now lead product-type demand as OEMs abandon inefficient resistive heating, while smart HVAC technology is capturing the fastest expansion within the technology dimension through AI-driven predictive climate control. Passenger vehicles dominate the end-user category, though commercial vehicles are emerging as a concentrated margin pool where fleet operators specify uptime-critical thermal reliability.
The EPA's phasedown of HFC refrigerants under AIM Act mandates is compelling US suppliers to revalidate system architectures for A2L-class alternatives. ECHA's REACH restrictions on PFAS-containing materials are simultaneously reshaping gasket and seal specifications across European supply chains. Stakeholders must monitor how refrigerant transition timelines in California, Germany, and Japan diverge, as misaligned certification requirements threaten to fragment platform engineering and inflate validation costs for multi-region vehicle programs.
Market Dynamics
The transition from resistive heating to heat pump architectures is compressing system footprints while demanding refrigerant chemistry expertise that legacy suppliers lack.
Growth Catalysts
- AIM Act Phase-Down:The EPA's HFC refrigerant mandates are forcing OEMs to redesign thermal loops around low-GWP alternatives, opening validation contracts for qualified engineering houses.
- 800V Platform Proliferation:High-voltage architectures in premium battery electric vehicles enable more efficient compressor operation, expanding addressable system value per vehicle.
- Cold-Climate Range Anxiety:Nordic and Canadian fleet operators now specify heat pump performance at minus twenty-five degrees Celsius, creating pull-through for advanced vapor-injection designs.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger materials face commodity price swings that compress Tier 2 supplier margins during contract renegotiations.
- PFAS Supply Chain Concentration:REACH restrictions on fluorinated gasket materials are forcing European suppliers toward unproven elastomer substitutes with longer qualification timelines.
- Refrigerant Handling Certification:A2L flammability classifications require technician retraining that slows aftermarket service network expansion in rural US markets.
Strategic Opportunities
- Commercial Vehicle Thermal Reliability:Last-mile delivery fleets in Germany and California are specifying uptime-guaranteed HVAC systems with predictive maintenance telemetry.
- AI-Driven Predictive Climate Control:Smart HVAC algorithms that precondition cabins during grid charging are capturing differentiation value in Chinese premium EV platforms.
- Refrigerant Recovery Infrastructure:Japan's METI incentives for closed-loop refrigerant handling are creating service revenue pools independent of new vehicle sales.
Industry Challenges
- Cross-Disciplinary Engineering Scarcity:Systems architects fluent in both electric powertrain thermal management and refrigerant thermodynamics command premium compensation that inflates R&D overhead.
- Multi-Region Certification Fragmentation:Divergent A2L approval timelines between California's CARB, Germany's KBA, and Japan's MLIT threaten platform engineering commonality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle HVAC Market |
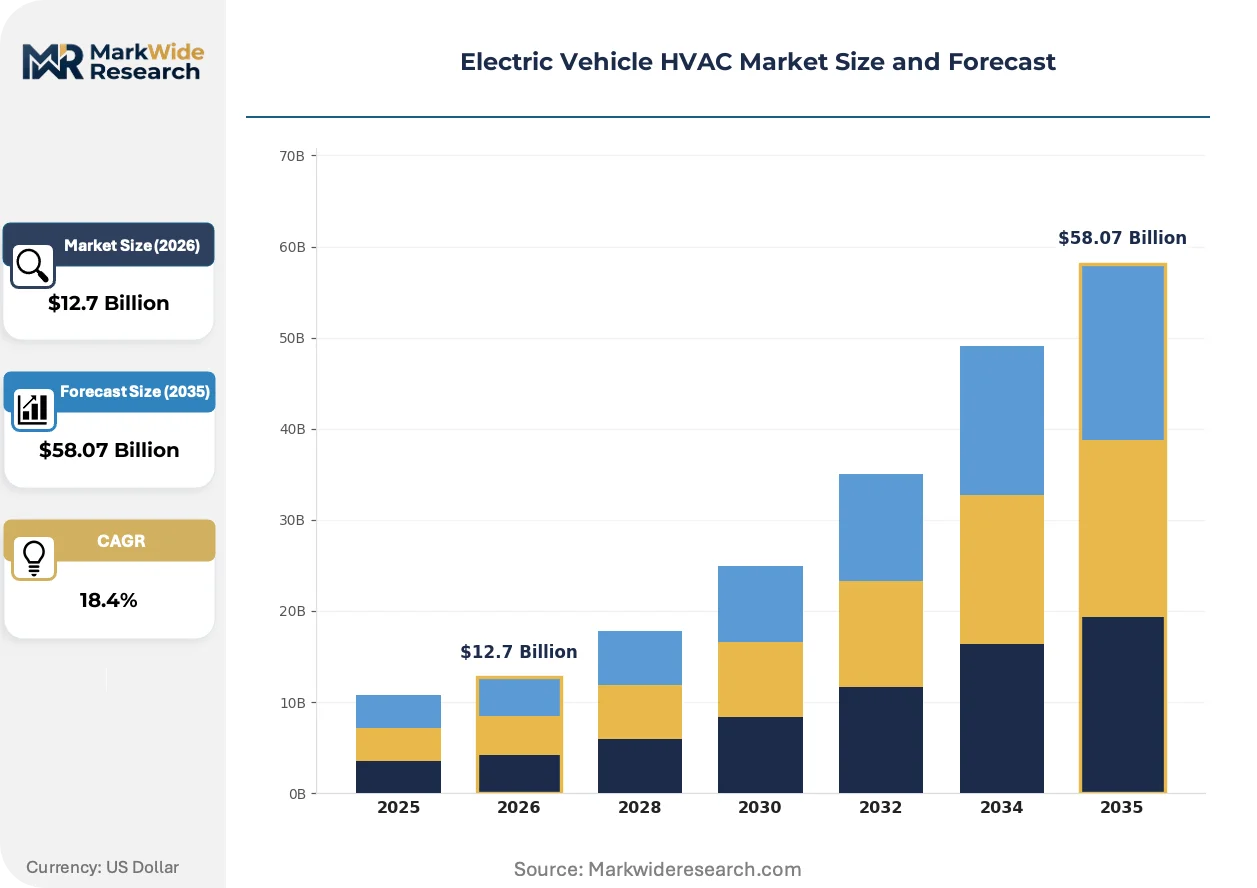
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Pump Systems, Compressors, Evaporators, Condensers Technology: Active Thermal Control, Climate Control Sensors, Smart HVAC, Refrigeration Technology End User: Passenger Vehicles, Commercial Vehicles, Buses, Two-Wheelers Delivery Mode: Integrated System, Retrofit Kit, Aftermarket Replacement, OEM Installation |
| Companies Covered | MAHLE GmbH, Sanden Corporation, DENSO Corporation, Eberspacher Group, Marelli Holdings Co., Ltd., Valeo SA, BorgWarner Inc., Air International Thermal Systems, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle HVAC Market Emerging Trajectories
Electrification of thermal management is collapsing the boundary between cabin comfort and battery preservation, forcing convergence of previously siloed engineering disciplines.
Integrated thermal modules combining the compressor, heat exchanger, and power electronics into single housings are miniaturizing underhood packaging constraints. European OEMs adopting these designs for 2026 model-year platforms are eliminating separate component sourcing relationships. This compression is miniaturizing the Tier 1 supplier footprint while raising barriers for single-product component houses.
The EPA's phasedown schedule under the AIM Act is accelerating refrigerant transition timelines beyond most suppliers' original validation roadmaps. System architectures must now accommodate A2L-class alternatives without performance degradation in desert-climate testing. US-based OEM procurement teams are responding by consolidating supplier panels to those with in-house refrigerant chemistry laboratories.
Fleet operators are unbundling HVAC service contracts from vehicle acquisition, creating standalone thermal reliability agreements with uptime penalties. This shift is disrupting traditional dealership service models in California and Germany, where direct supplier-to-fleet maintenance partnerships are capturing aftermarket revenue previously held by OEM captive networks.
Electric Vehicle HVAC Market Segmentation
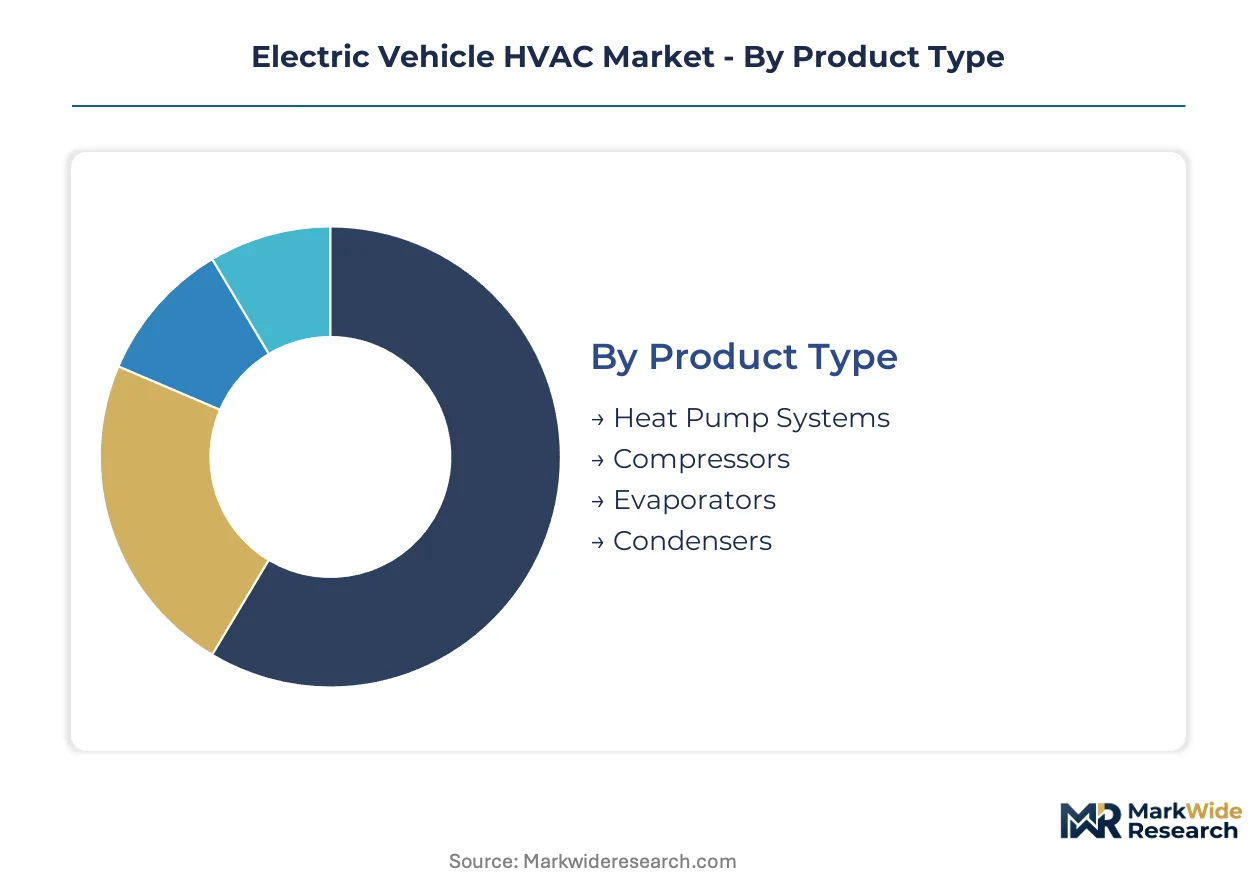
Segmentation in the Electric Vehicle HVAC Market reveals how thermal system architectures diverge across voltage platforms, vehicle duty cycles, and procurement channels. Understanding these divisions exposes where engineering investments concentrate and which customer specifications command premium pricing.
Product Type:
Margin pools concentrate in integrated thermal modules where compressor, heat exchanger, and control electronics share a single housing, compressing supplier footprints while raising technical barriers.
- Heat Pump Systems:These architectures extract ambient thermal energy for cabin heating rather than consuming battery power through resistive elements. Nordic fleet operators in Norway and Sweden now specify vapor-injection heat pumps rated to minus twenty-five degrees Celsius, pulling advanced designs into premium battery electric platforms.
- Compressors:Electric scroll and swashplate compressors operating at 400V to 800V DC represent the power consumption heart of every thermal loop. Chinese OEM procurement teams are consolidating supplier panels toward houses with in-house refrigerant chemistry laboratories as A2L validation requirements tighten.
- Evaporators:Aluminum microchannel designs optimize heat transfer surface area within constrained underhood packaging. California-based EV startups prioritize compact form factors that preserve front-trunk cargo volume.
- Condensers:Multi-flow brazed aluminum assemblies reject thermal energy to ambient air. German OEM platforms specify corrosion-resistant coatings for winter road salt exposure.
The dominant share belongs to Heat Pump Systems, while Compressors is closing the gap fastest as 800V architectures expand addressable system value per vehicle.
Technology:
Technology differentiation increasingly hinges on software-layer capabilities that anticipate thermal demand rather than merely react to cabin temperature sensors.
- Smart HVAC:AI-driven predictive algorithms precondition cabin temperature during grid charging sessions, preserving battery range. Chinese premium EV platforms capture differentiation value through occupant recognition systems that adjust climate zones automatically.
- Active Thermal Control:Real-time battery cell temperature balancing extends pack longevity while enabling faster DC charging rates. German engineering houses integrate these controls with vehicle thermal management operating systems.
- Climate Control Sensors:In-cabin infrared and humidity arrays feed closed-loop feedback to compressor inverter drives. Japanese Tier 1 suppliers lead miniaturization of multi-sensor fusion modules.
- Refrigeration Technology:A2L-class low-GWP refrigerant architectures require redesigned sealing systems and leak detection protocols. US EPA AIM Act timelines are compressing validation schedules beyond original supplier roadmaps.
Smart HVAC holds the steepest expansion trajectory, while Active Thermal Control anchors the largest installed base through its integration with battery management systems.
End User:
End-user segmentation separates consumer range anxiety from commercial uptime guarantees, with diverging specification priorities across duty cycles.
- Passenger Vehicles:Battery electric sedans and SUVs command the largest installation volumes, with cabin comfort and range preservation as dual design objectives. US and Chinese OEM platforms dominate procurement activity.
- Commercial Vehicles:Last-mile delivery vans specify thermal reliability with predictive maintenance telemetry and uptime penalty clauses. Fleet operators in Germany and California are unbundling HVAC service contracts from vehicle acquisition.
- Buses:High-occupancy transit applications demand rapid cabin conditioning with minimal energy draw from large-format battery packs. European municipal procurement emphasizes modularity for field serviceability.
- Two-Wheelers:Scooter and motorcycle thermal systems prioritize extreme miniaturization and cost compression. Indian and Southeast Asian markets drive volume through two-wheeler electrification programs.
Passenger Vehicles retains the dominant share, while Commercial Vehicles is expanding most quickly as fleet electrification accelerates and uptime-critical specifications proliferate.
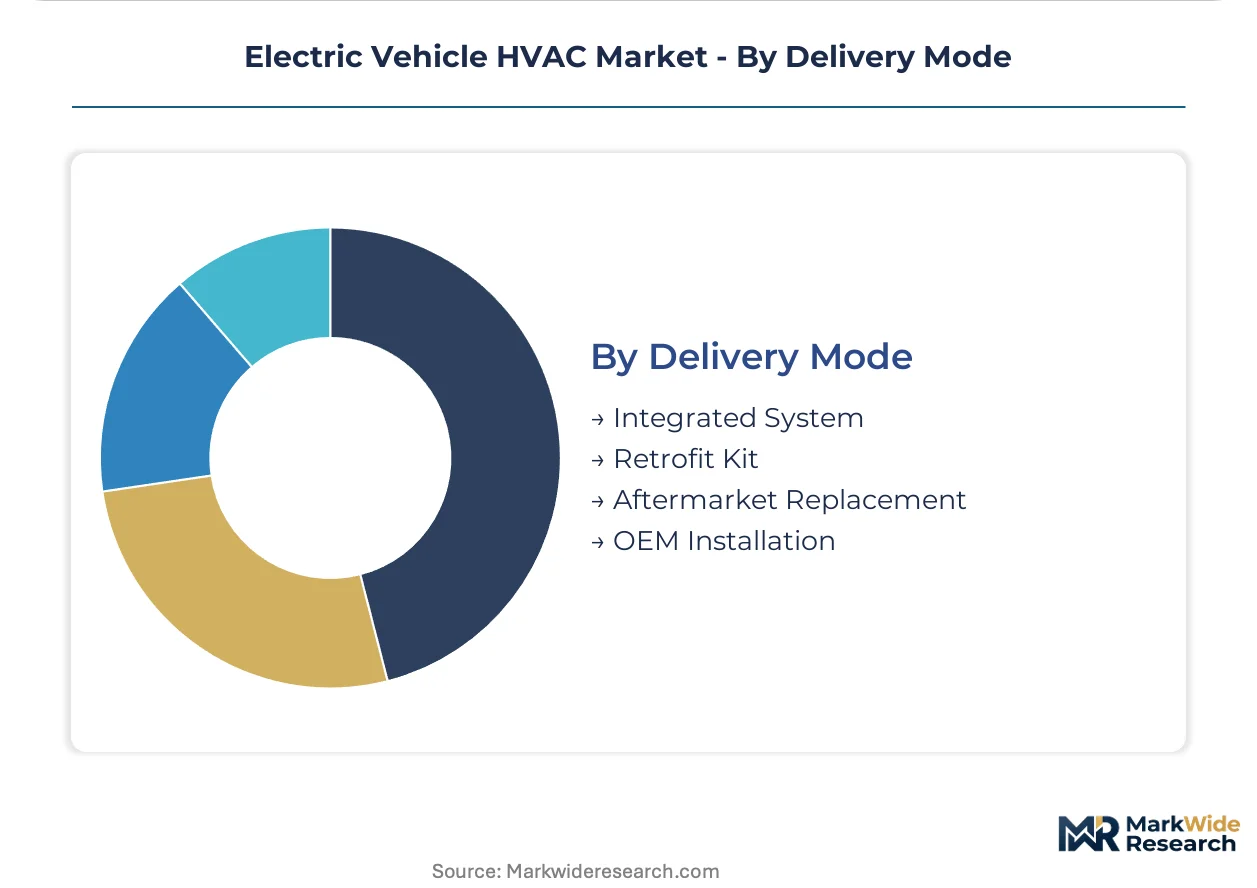
Delivery Mode:
Delivery mode segmentation tracks how thermal system value migrates between captive OEM supply chains and independent service networks.
- OEM Installation:Factory-integrated thermal modules dominate value capture, with European OEMs adopting single-housing designs that eliminate separate component sourcing relationships. Stuttgart and Munich engineering centers anchor development for 2026 model-year platforms.
- Integrated System:Pre-validated thermal modules arrive at vehicle assembly plants as complete subassemblies, reducing line-side complexity. Japanese OEMs favor this approach for quality consistency.
- Aftermarket Replacement:Service network expansion faces friction from A2L refrigerant handling certification requirements that slow technician retraining in rural US markets.
- Retrofit Kit:Limited deployment for commercial vehicle fleet upgrades where existing chassis receive electrified thermal architectures. California air quality incentives partially offset conversion costs.
OEM Installation commands the dominant share, while Aftermarket Replacement is gaining share fastest as early EV cohorts age into thermal system refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys heat pump architectures at scale for cost-efficient mass-market battery electric vehicles, while Germany and the United States concentrate procurement for premium platforms with advanced vapor-injection designs.
United States
California fleet operators unbundle HVAC service contracts from vehicle acquisition, creating standalone thermal reliability agreements. The EPA's AIM Act phasedown mandates accelerate A2L refrigerant validation timelines beyond original supplier roadmaps. Detroit-area engineering centers anchor OEM procurement consolidation toward suppliers with in-house refrigerant chemistry laboratories.
Germany
Nordic fleet specifications for minus twenty-five degrees Celsius heat pump performance pull advanced designs into premium European platforms. ECHA's REACH restrictions on PFAS-containing materials reshape gasket and seal specifications across supply chains. Stuttgart and Munich engineering clusters drive integrated thermal module development for 2026 model-year platforms.
China
Premium EV platforms capture differentiation value through AI-driven predictive climate control algorithms that precondition cabins during grid charging. MIIT dual carbon goals accelerate heat pump adoption as OEMs abandon inefficient resistive heating. Yangtze River Delta manufacturing bases concentrate compressor production scale for domestic and export markets.
Japan
METI incentives for closed-loop refrigerant handling create service revenue pools independent of new vehicle sales. Kariya operations sustain manufacturing scale for integrated thermal system production. Nagoya-area suppliers lead miniaturization of multi-sensor fusion modules for climate control feedback systems.
South Korea
Seoul Capital Area OEM procurement teams specify 800V compressor architectures for premium battery electric vehicle platforms. Domestic suppliers face technician retraining requirements for A2L flammability classifications that slow aftermarket network expansion. Busan-Ulsan industrial corridors concentrate heat exchanger aluminum microchannel production.
Electric Vehicle HVAC Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying as OEMs reduce supplier panels. Tier 1 houses with captive refrigerant chemistry capabilities capture validation contracts for A2L transitions, while component specialists face margin compression from single-housing integrated module designs. Three archetypes dominate: full-system integrators, compressor-focused technology houses, and smart climate algorithm developers. Competitive moves center on strategic partnerships for 800V platform co-development and backward integration into refrigerant handling infrastructure.
Among German-anchored full-system integrators, MAHLE GmbH exemplifies the integrated thermal module archetype, while DENSO Corporation represents Japanese scale-driven manufacturing concentration. Valeo SA occupies a position within the smart climate differentiation tier, anchoring algorithm-based competitive positioning.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Sanden Corporation |
| DENSO Corporation |
| Eberspacher Group |
| Marelli Holdings Co., Ltd. |
| Valeo SA |
| BorgWarner Inc. |
| Air International Thermal Systems |
| Hanon Systems |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between European OEMs and Yangtze River Delta compressor manufacturers lock in both aluminum microchannel supply access and price visibility for 800V platform rollouts, insulating procurement teams from copper commodity swings while committing volumes through 2026 model-year ramps.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships, with pricing stratifying across premium, standard, and economy tiers based on refrigerant chemistry certification grade and volume scale commitments. Cost compression in standard-tier heat exchangers is intensifying because Chinese suppliers are capturing aluminum microchannel scale advantages. Fleet operators in California and Germany exhibit the lowest price sensitivity due to uptime penalty clauses, while two-wheeler OEMs in India face acute margin pressure.
Supply Chain Analysis
Yangtze River Delta port congestion acts as a chokepoint that disrupts just-in-time compressor deliveries to Stuttgart and Munich assembly plants. Manufacturing concentrates in China, South Korea, and Germany, with raw material feeds drawing from Chilean copper cathode and Australian bauxite for aluminum microchannel production. Single-source vulnerability around PFAS-free gasket substitutes under ECHA REACH restrictions threatens European line stoppages. Distribution runs through captive OEM supply chains with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle HVAC Market represents a high-growth disruption propelled by the EPA's AIM Act refrigerant phasedown, which is compressing validation timelines and consolidating procurement toward suppliers with captive refrigerant chemistry capabilities.
For Market Incumbents: Consolidate supplier panels around integrated thermal module architectures that eliminate separate component sourcing relationships, while backward integration into A2L refrigerant handling infrastructure captures aftermarket revenue pools threatened by direct supplier-to-fleet maintenance partnerships in California and Germany. For New Entrants and Emerging Players: Anchor in commercial vehicle predictive maintenance telemetry where German and California fleet operators are unbundling HVAC service contracts from vehicle acquisition, targeting uptime-guaranteed thermal reliability agreements as the most penetrable white space with a direct supplier-to-fleet go-to-market model. For Investors and Strategic Acquirers: Refrigerant chemistry laboratories with OEM validation contracts offer the strongest acquisition thesis, as these capabilities command premium positioning through the A2L transition window; watch for EPA enforcement acceleration on AIM Act timelines as the inflection signal that compresses supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Laboratory Investment | Captures A2L validation contracts as EPA AIM Act timelines compress beyond original roadmaps. |
| Integrated Thermal Module Development | Eliminates separate component sourcing relationships for 2026 European OEM platform adoptions. |
| Predictive Maintenance Telemetry Partnership | Disrupts dealership service models through direct supplier-to-fleet uptime agreements in California. |
| 800V Compressor Platform Co-Development | Expands addressable system value per vehicle for Seoul Capital Area premium EV procurement. |
| Closed-Loop Refrigerant Handling Infrastructure | Creates service revenue pools independent of new vehicle sales under Japan METI incentive programs. |
Methodological Framework
Desk research of EPA AIM Act regulatory filings, ECHA REACH substance restrictions, and vehicle production databases preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers across Germany, China, and the United States. Primary fieldwork combined with secondary validation from customs records and IHS Markit registration data established bottom-up and top-down triangulation for market sizing.
Variance decomposition across vehicle class, propulsion architecture, and regional production cluster segmentation dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from modeled installation volumes and content-per-vehicle value trajectories, with heat pump adoption curves and 800V platform penetration serving as automotive-specific forecast inputs.
Material uncertainties — refrigerant transition timeline divergence between California CARB, Germany KBA, and Japan MLIT — sit outside the modeled envelope. Forecasts reflect assumptions on A2L validation completion rates and PFAS substitute qualification timelines. Revision becomes warranted when cross-regional certification fragmentation crosses thresholds that threaten platform engineering commonality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Scooter Market