
 Electric Delivery Vans Market | 2026-2036
Electric Delivery Vans Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Delivery Vans Market Insights
Fleet procurement channels is tilting away from traditional dealership networks toward direct manufacturer relationships and lease-to-own structures. Rivian Automotive leverages its Amazon partnership to sustain captive demand for purpose-built delivery platforms. Ford Motor Company anchors the North American transition with commercial-grade electric chassis designed for upfitter customization. BYD Company dominates battery cost curves through in-house cell production, extending price advantages into European logistics tenders.
Electric delivery vans are battery-electric commercial vehicles with gross vehicle weights typically ranging from 3.5 to 7.5 tonnes, engineered for urban cargo distribution with zero tailpipe emissions and regenerative braking systems. Their primary commercial purpose is replacing diesel-powered last-mile fleets in dense urban environments where air quality regulations restrict combustion engine access. Lithium-ion battery technology occupies the dominant cost position in vehicle manufacturing, while solid state chemistries attract R&D investment for future energy density breakthroughs. E-commerce end users represent the fastest-expanding demand pool as parcel volumes strain urban fulfillment networks. Depot charging infrastructure leads installed capacity since fleet operators prefer overnight base charging over public fast-charger dependency.
The EPA tailpipe standards and NHTSA fuel economy rules for commercial vehicles in the United States mandate progressively tighter CO2 limits, forcing fleet operators to electrify or pay penalties. The EU Green Deal and F-Gas Regulation compound this pressure in Europe by binding member states to phase out combustion engines in urban delivery. Stakeholders must monitor how charging infrastructure buildout pace interacts with vehicle supply constraints to determine viable fleet conversion timelines.
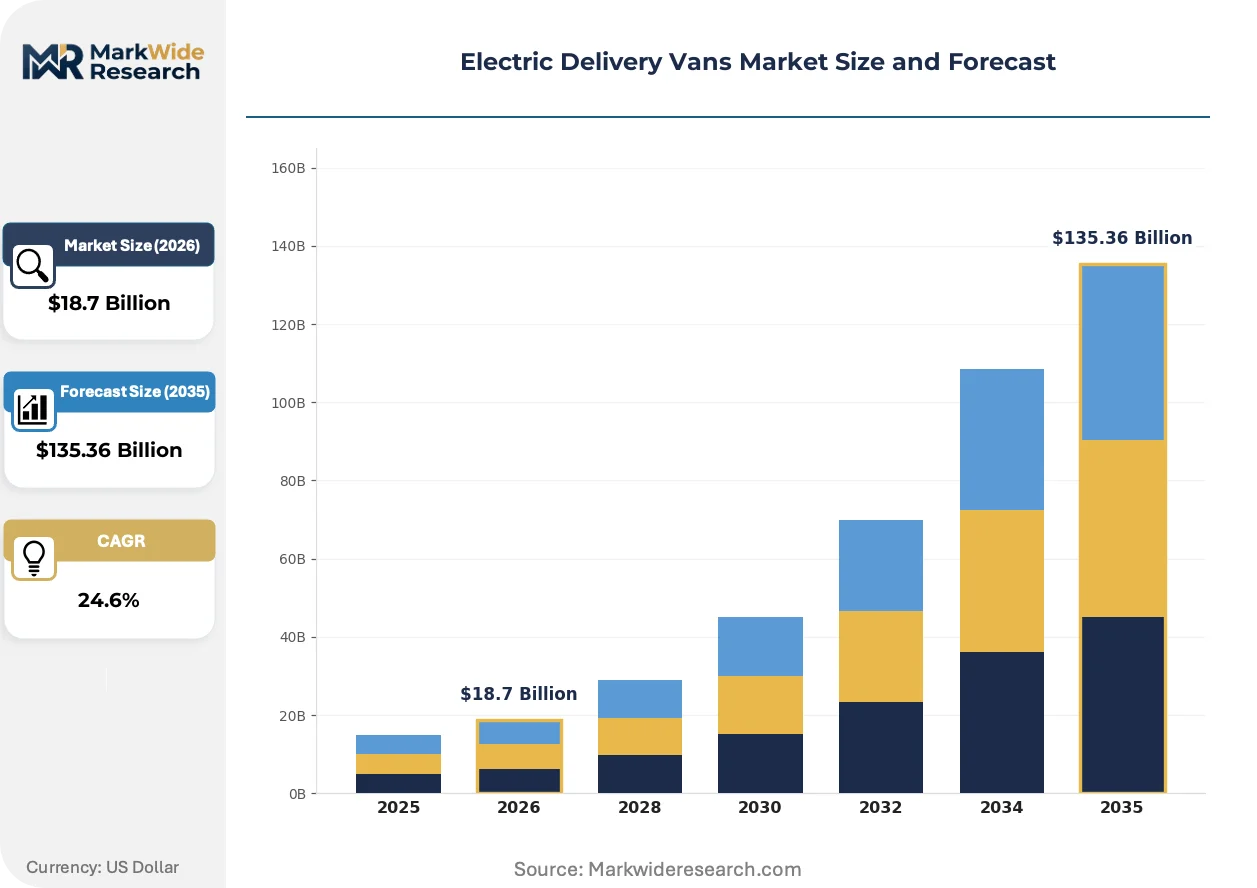
Market Dynamics
EU CO2 standards for commercial vehicles are compressing fleet conversion timelines as operators face penalties for diesel retention, while battery energy density gains are extending single-charge range enough to eliminate route anxiety for urban distribution networks.
Growth Catalysts
- EU Green Deal mandates:Member states must phase out combustion engines in urban delivery, binding procurement decisions toward zero-emission platforms.
- E-commerce parcel volumes:Dense fulfillment networks strain diesel fleet economics, accelerating electric van deployment for last-mile density.
- Battery cost curves:Lithium-ion cell manufacturing scale is compressing pack prices, narrowing total cost of ownership gaps against diesel equivalents.
Market Restraints
- Lithium supply concentration:Cathode material processing clusters in China create geopolitical exposure for European and North American fleet operators.
- Charging infrastructure gaps:Depot installation timelines lag vehicle delivery schedules, stranding capacity until electrical upgrades complete.
- Cold weather range degradation:Battery thermal management limitations reduce usable capacity in Nordic climates, forcing larger pack specifications.
Strategic Opportunities
- Lease-to-own structures:Direct manufacturer relationships bypass traditional dealership networks, capturing fleet procurement margin.
- Solid-state chemistry convergence:Next-generation cell architectures promise energy density breakthroughs for extended suburban routes.
- France low-emission zone expansion:Paris and Lyon municipal bans on combustion vans create captive demand for electric alternatives.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for battery system diagnostics and repair.
- Upfitter integration complexity:Custom body builders must recalibrate thermal loads and weight distributions for electric chassis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Delivery Vans Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Vans, Trucks, Buses, Motorcycles Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Others End User: Retailers, E-commerce, Logistics Providers, Food Delivery Charging Infrastructure: Fast Chargers, Standard Chargers, Wireless Charging, Depot Charging |
| Companies Covered | Rivian Automotive, Ford Motor Company, General Motors, Stellantis, Mercedes-Benz Group, Renault Group, Volkswagen, BYD Company, Wuling Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Delivery Vans Market Trends and Innovations
Telematics integration is digitizing route optimization and predictive maintenance, compressing operational cost structures for fleet operators while enabling real-time energy management across distributed vehicle assets.
Bidirectional charging hardware is digitizing vehicle-to-grid revenue streams, allowing fleet operators to sell stored energy back to utilities during peak demand windows. Logistics providers in Germany and the Netherlands are piloting software platforms that automate dispatch timing based on electricity price signals. This capability is digitizing fleet assets into distributed energy resources, transforming depreciation schedules into revenue-generating infrastructure.
The EPA tailpipe standards and NHTSA fuel economy rules mandate progressively tighter CO2 limits for commercial vehicles, forcing US fleet operators to electrify or absorb penalty costs. California Air Resources Board waivers extend these requirements beyond federal floors, creating a bifurcated compliance environment. Heavy-duty van segments serving urban California routes face the most compressed transition timelines.
Direct procurement from manufacturers is displacing traditional dealership networks for volume fleet accounts, unbundling vehicle supply from service contracts. Lease structures now bundle charging infrastructure, maintenance, and energy management into per-mile pricing. This shift is most visible in United Kingdom grocery and parcel delivery fleets, where total cost transparency drives contract awards.
Electric Delivery Vans Market Segmentation
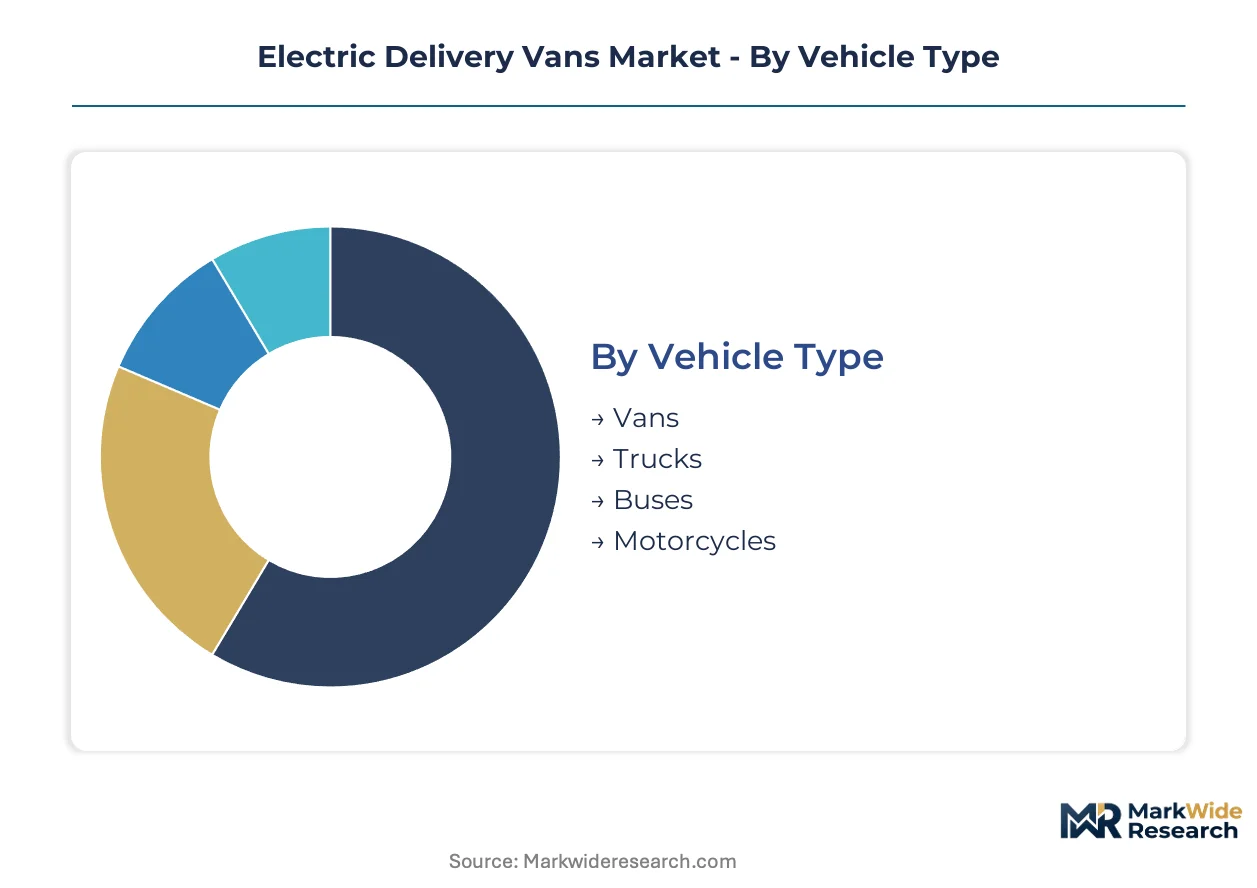
Electric delivery van procurement diverges sharply across fleet operator profiles, with battery chemistry choices and charging topology decisions locking in decade-long operational economics. Segmentation reveals how urban route density, depot real estate constraints, and parcel volume volatility reshape vehicle specification requirements.
Vehicle Type:
Urban logistics demands span cargo volumes from single-parcel motorcycles to multi-stop box trucks, with gross vehicle weight ratings determining access to low-emission zones and curb loading permissions.
- Vans:Three-and-a-half to seven-tonne platforms dominate last-mile substitution for diesel panel vans, with German parcel carriers specifying roof heights exceeding 2.2 meters for roll-cage compatibility. Retail consolidation in the Netherlands concentrates demand for mid-roof configurations serving dense Amsterdam and Rotterdam delivery zones.
- Trucks:Heavy-duty variants above seven tonnes serve hub-to-depot feeder routes and bulky goods distribution, requiring reinforced chassis for palletized freight. British grocery chains specify these for regional distribution centers serving urban dark stores.
- Buses:Converted shuttle platforms repurpose passenger compartments for high-volume parcel sorting during transit, gaining traction among French postal operators testing dynamic route optimization.
- Motorcycles:Two-wheeled electric variants navigate pedestrianized city cores and congestion-charged districts where four-wheeled access is restricted.
The dominant share belongs to Vans, while Trucks are closing the gap fastest as hub-and-spoke logistics densify around urban peripheries.
Battery Technology:
Cell chemistry selection trades energy density against thermal stability, with procurement teams weighing cycle life guarantees against pack replacement timelines.
- Lithium-ion:NMC and LFP architectures command fleet procurement through proven degradation curves and established recycling pathways. BYD's blade-cell LFP designs penetrate European tenders with cost structures below nickel-cobalt alternatives.
- Solid State:Pre-commercial prototypes promise 400+ watt-hour densities for extended suburban routes, with Toyota and QuantumScape targeting logistics validation fleets.
- Nickel-Metal Hydride:Legacy hybrid applications persist in temperature-extreme climates where lithium thermal management adds complexity.
- Others:Sodium-ion and lithium-sulfur chemistries attract R&D sponsorship from national battery institutes seeking supply chain decoupling from cobalt and nickel concentrate markets.
Lithium-ion retains procurement dominance, though Solid State is expanding most quickly in pilot fleet allocations.
End User:
Parcel volume volatility and delivery-time compression requirements fragment specification priorities across customer verticals.
- E-commerce:Amazon, Alibaba, and regional marketplace operators specify maximum cargo cube and telematics integration for real-time customer tracking, with Rivian's purpose-built EDV platform capturing Amazon's North American last-mile conversion.
- Logistics Providers:DHL, FedEx, and UPS negotiate fleet-scale service agreements bundling charging infrastructure, with depot charging specifications dominating procurement RFPs.
- Retailers:Grocery chains prioritize multi-temperature compartments and frequent stop-start durability, with British supermarkets leading refrigerated electric van deployment.
- Food Delivery:Meal-kit and quick-commerce operators optimize for curb accessibility and rapid driver egress, favoring compact vans with sliding doors on both sides.
E-commerce commands the largest procurement volumes, while Food Delivery is gaining share fastest as sub-15-minute delivery promises proliferate.
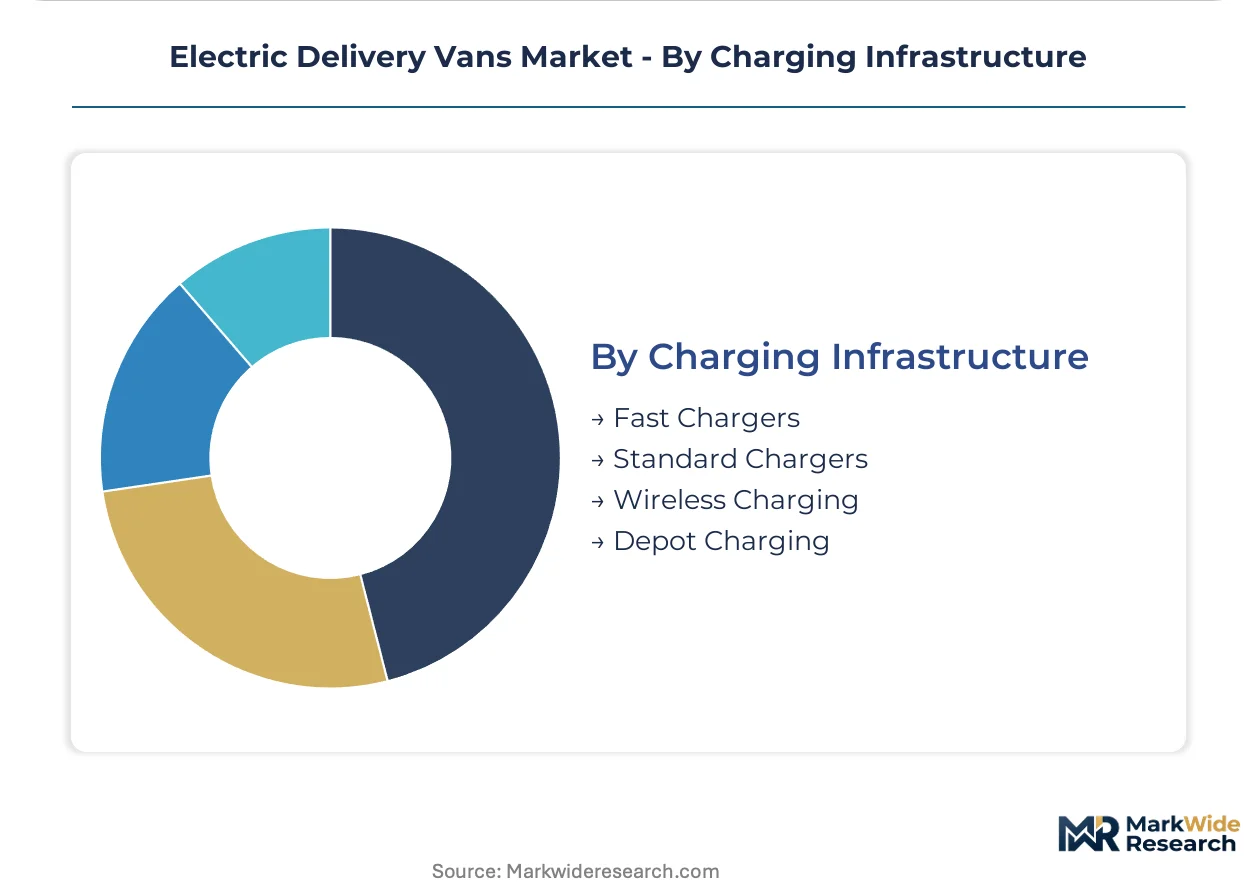
Charging Infrastructure:
Charging topology decisions determine fleet availability windows and electricity procurement strategies, with depot installations preferred for predictable scheduling.
- Depot Charging:Overnight AC charging at fleet bases dominates installed capacity, with Dutch operators leveraging time-of-use tariffs to minimize energy costs.
- Fast Chargers:DC rapid infrastructure serves opportunity charging during driver breaks and route midpoints, with German autobahn-adjacent logistics hubs piloting 350kW systems.
- Standard Chargers:Level 2 AC units supplement depot capacity for overflow parking and secondary facilities.
- Wireless Charging:Inductive pad systems eliminate connector wear and enable automated charging for autonomous delivery pilots in controlled environments.
Depot Charging holds the dominant share, while Fast Chargers are climbing the fastest as route lengths extend beyond single-shift range limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Dutch logistics dominance in European electric van deployment. Germany's autobahn network and charging corridor density anchor continental fleet conversion timelines. United Kingdom channel ports feed e-commerce fulfillment density driving London-centric procurement.
Germany
Parcel carrier fleet renewal and municipal low-emission zone expansion drive procurement. The KBA enforces EU CO2 standards with commercial vehicle penalties accelerating diesel phase-out. Berlin-Brandenburg logistics clusters concentrate depot charging infrastructure buildout for DHL and Amazon distribution networks.
United Kingdom
Grocery chain refrigerated van specifications and last-mile delivery density reshape demand. The Department for Transport mandates zero-emission van sales quotas from 2030 under the ZEV mandate framework. Midlands manufacturing corridors around Birmingham host upfitter facilities converting electric chassis for supermarket fleets.
Netherlands
Randstad urban logistics consolidation and time-of-use electricity tariffs optimize fleet economics. The RVO administers purchase subsidies through the SEEH program binding subsidy to depot charging installation. Amsterdam and Rotterdam city centers enforce combustion van bans creating captive demand for electric alternatives.
France
Postal operator fleet standardization and quick-commerce delivery proliferation expand addressable market. The DGEC implements EU Green Deal commercial vehicle standards through national decarbonization contracts. Paris and Lyon metropolitan authorities accelerate low-emission zone expansion banning pre-2011 diesel vans from 2025.
United States
Amazon's last-mile network electrification and California regulatory stringency concentrate procurement. The EPA tailpipe standards and NHTSA fuel economy rules mandate progressively tighter CO2 limits with California Air Resources Board waivers extending requirements beyond federal floors. Michigan automotive corridors and California logistics hubs anchor rival fleet conversion ecosystems.
Electric Delivery Vans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on battery and powertrain supply. The market structures around three tiers: legacy automotive conglomerates with commercial vehicle heritage, pure-play electric entrants with fleet-native architectures, and battery-integrated Asian manufacturers leveraging cell cost advantages. Competitive positioning crystallizes through direct fleet procurement relationships displacing dealership networks, and lease-to-own structures bundling charging infrastructure with vehicle supply.
Among North American platform specialists, Rivian Automotive occupies a position exemplifying fleet-captive demand architectures, while Ford Motor Company anchors the incumbent transition archetype with commercial-grade chassis programs. BYD Company represents the battery-integrated cost leadership model penetrating European tenders through in-house cell production scale.
| Leading Market Players |
|---|
| Rivian Automotive |
| Ford Motor Company |
| General Motors |
| Stellantis |
| Mercedes-Benz Group |
| Renault Group |
| Volkswagen |
| BYD Company |
| Wuling Motors |
| Others |
Pricing and Supply Chain Analysis
Ningbo's cathode material processing clusters anchor lithium-ion cell cost curves, concentrating pricing power among integrated battery manufacturers who dictate pack economics for European fleet tenders. This geographic concentration compresses margins for chassis assemblers while amplifying negotiation leverage for operators securing multi-year supply agreements.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with fleet operators above five-hundred units accessing preferential per-pack pricing unavailable to smaller logistics providers. Three-tier pricing structure across premium, standard, and economy levels separates telematics-enabled platforms from basic configurations, with cold-weather thermal management packages commanding substantial premiums. Cost compression in the economy tier is intensifying because BYD's blade-cell manufacturing scale forces nickel-cobalt alternatives toward price parity. Grocery chains exhibit highest price sensitivity due to thin refrigerated transport margins, while parcel carriers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from Chinese cathode suppliers now stretch to one hundred eighty days, straining working capital for European upfitters assembling finished vehicles. Cell manufacturing concentrates in China, South Korea, and Japan, with raw material processing drawing from Chilean lithium brine and Indonesian nickel laterite. Lithium hydroxide and cobalt sulfate constitute critical input dependencies, with single-source vulnerability in rare earth magnet supply for drive motors. Distribution runs through Rotterdam port logistics clusters serving German and Dutch fleet operators, bypassing traditional dealership networks for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
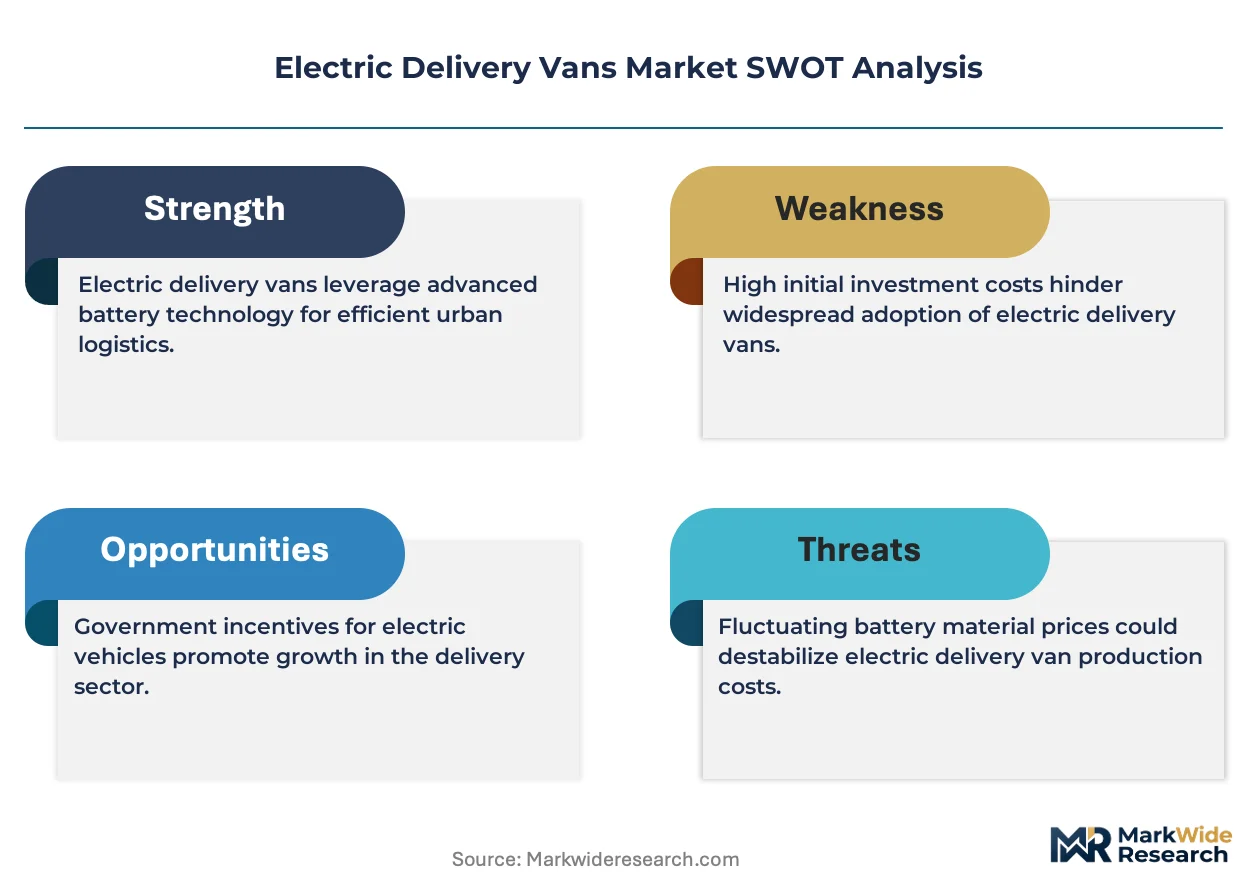
Electric delivery van penetration sits at early-cycle expansion, with EU Green Deal mandates accelerating fleet conversion timelines faster than battery cost curves alone would justify. Municipal low-emission zone enforcement creates captive demand that insulates early movers from demand volatility.
For Market Incumbents: Entrench commercial vehicle service networks by certifying high-voltage technicians before solid-state chemistry transitions disrupt maintenance competencies. Add depot charging infrastructure capacity in the Midlands manufacturing corridor to capture British grocery chain fleet renewals. Defend against pure-play entrants by bundling vehicle supply with energy management software that optimizes time-of-use tariffs. For New Entrants and Emerging Players: Pursue refrigerated van specifications for quick-commerce operators in French metropolitan zones where combustion bans tighten fastest. White-space concentrates in Nordic climate battery thermal management, where incumbent range degradation creates specification gaps. Target lease-to-own structures bypassing dealership networks, with per-mile pricing bundling charging hardware installation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors battery-integrated manufacturers with in-house cell production and captive cathode supply agreements. Five-to-ten year viability hinges on solid-state chemistry convergence timelines and charging infrastructure buildout pace. Acquisition candidates should demonstrate depot charging software platforms with utility interconnection capabilities. Watch for inflection when German KBA enforcement accelerates CO2 penalty collection beyond current compliance cost thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake contracts with Chinese processors lock in cost advantages for European tenders. |
| Depot Charging Infrastructure Partnership | Utility interconnection agreements enable time-of-use optimization for Dutch and German fleet operators. |
| Platform Standardization | Common chassis architectures reduce upfitter integration complexity for refrigerated and parcel body variants. |
| Software-Defined Vehicle Investment | Telematics platforms digitize route optimization and predictive maintenance for Amazon-scale fleet deployments. |
| Geographic Manufacturing Footprint | Midlands and Berlin-Brandenburg assembly capacity shortens delivery timelines for UK and German procurement cycles. |
Research Methodology
Operator-level perspectives from fleet procurement directors, depot charging infrastructure planners, high-voltage maintenance technicians, and municipal low-emission zone administrators anchored the qualitative base. Primary interviews triangulated with vehicle registration databases, EU CO2 compliance filings, and utility interconnection records. Secondary sources included KBA enforcement statistics, RVO subsidy disbursement data, and IEA electric vehicle outlook publications. Bottom-up fleet conversion timelines reconciled against top-down battery production capacity forecasts.
Scenario-bracketing framed projections across conservative, baseline, and accelerated electrification pathways over the projection horizon. Segmentation modeling incorporated vehicle class, battery chemistry, charging topology, and fleet operator vertical. CAGRs derived from fleet replacement cycle analysis and penalty cost absorption thresholds. Forecast inputs included lithium carbonate price trajectories and municipal low-emission zone expansion schedules.
Sensitivities concentrate around solid-state chemistry commercialization timelines and charging infrastructure installation delays. Forecasts reflect assumptions on EU CO2 standard enforcement stringency and battery pack degradation curves. Macroeconomic contraction compressing e-commerce parcel volumes, regulatory delay in low-emission zone enforcement, or breakthrough sodium-ion chemistry adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market