
 Global Chocolate Market | 2026-2036
Global Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chocolate Market Intelligence
The strategic middle ground between mass-market scale and artisanal branding is collapsing. Barry Callebaut dominates the business-to-business supply of industrial chocolate and cocoa products. Chocoladefabriken Lindt & Sprüngli AG sustains its premium positioning through controlled retail channels and brand heritage. In contrast, Mondelez International leverages its vast distribution network to compete on volume and brand recognition globally.
Chocolate is a processed food derived from Theobroma cacao seeds, which are fermented, roasted, and ground. Its fundamental composition includes cocoa solids and cocoa butter, with variations in sugar and milk content defining its primary classifications. While milk chocolate continues to hold the largest volume share, dark chocolate products are expanding rapidly due to perceived health benefits. The confectionery application remains the primary end-use, though demand for high-quality couverture chocolate in baking and desserts is notable.
The US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) enforce strict standards of identity, dictating minimum cocoa solid percentages. Concurrently, emerging regulations in Europe on deforestation-free supply chains directly impact cocoa sourcing and traceability protocols. Navigating the divergent consumer preferences for ethical sourcing versus price sensitivity remains a central strategic challenge for all market participants.
Market Dynamics
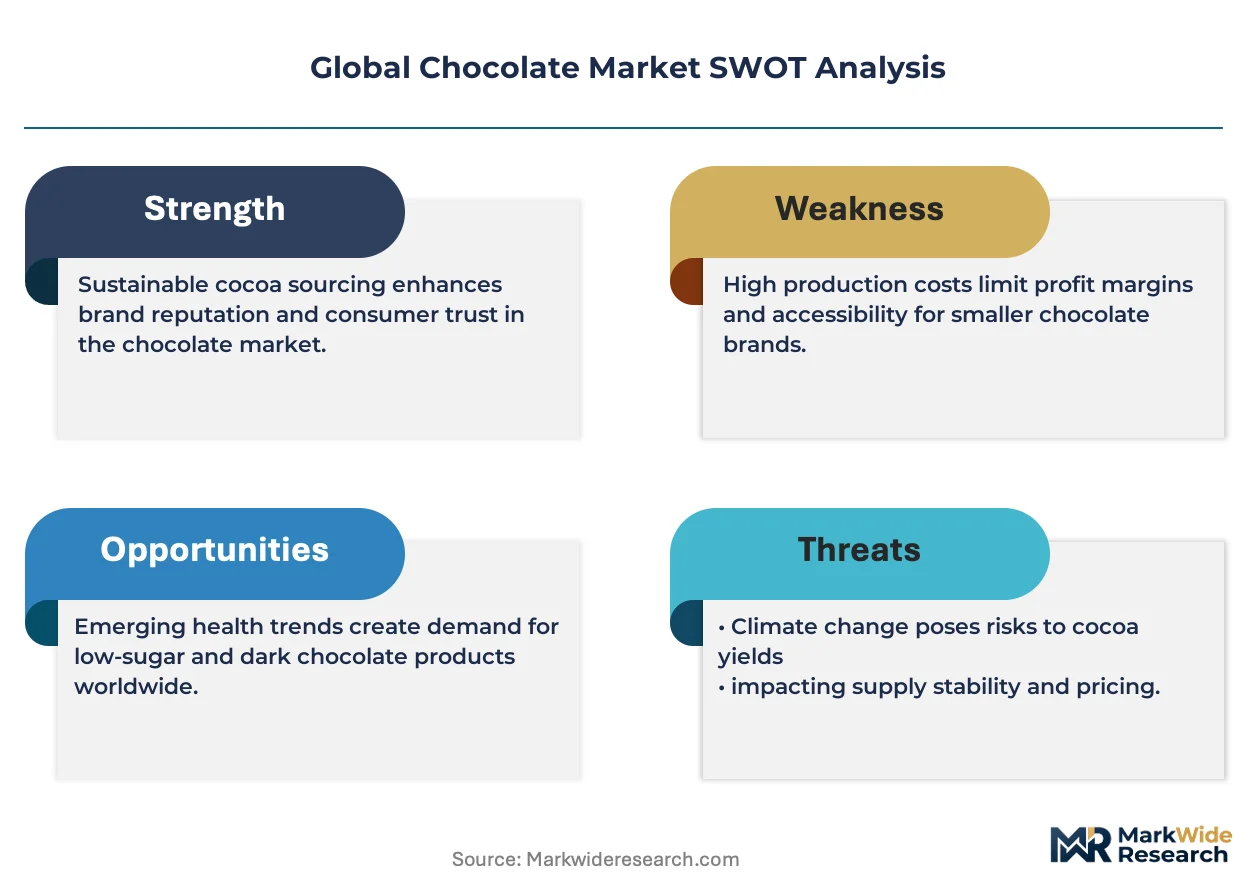
The global chocolate market's primary dynamic is the structural tension between tightening ethical sourcing mandates, such as the EU Green Deal, and persistent consumer price sensitivity in mass-market segments. This conflict shapes investment priorities, supply chain configurations, and brand positioning.
Growth Catalysts
- Premium Segment Expansion:Demand for premium and artisanal chocolate is showing significant concentration in urban centers across China, creating new growth avenues for high-value products that emphasize origin and craftsmanship.
- Health and Wellness Perception:The rising consumer association of dark chocolate, particularly high-cacao content varieties, with cardiovascular health benefits is expanding its market share beyond traditional confectionery into a wellness-adjacent category.
- Food Service Application:Increased demand for high-quality couverture chocolate from the professional baking and dessert sectors is driving volume, particularly for products with specific functional properties for pastry and confectionery arts.
Market Restraints
- Cocoa Price Volatility:The market is structurally exposed to fluctuations in Theobroma cacao seed prices, driven by climate events, crop disease in West African producing nations, and currency exchange rate instability.
- Concentrated Raw Material Sourcing:An overwhelming dependence on a few West African countries for the bulk of cocoa supply creates significant geopolitical and logistical risks, with potential for widespread disruption.
- Divergent Regulatory Standards:Differing standards of identity enforced by the US FDA and the European Food Safety Authority (EFSA) regarding minimum cocoa solids and milk content create formulation and labeling complexities for global brands.
Strategic Opportunities
- Functional Chocolate Innovation:There is a clear opportunity to develop and market chocolate products fortified with functional ingredients like probiotics, vitamins, or plant-based proteins, appealing to health-conscious consumers.
- Direct-to-Consumer Channels:Subscription-based and e-commerce platforms offer a pathway to bypass traditional retail, allowing artisanal and single-origin producers to build direct relationships with consumers and capture higher margins.
- Geographic Market Development:Untapped potential exists in developing economies across Southeast Asia and Latin America, where a growing middle class presents a new consumer base for branded chocolate products.
Industry Challenges
- Traceability System Implementation:Deploying and managing robust, end-to-end traceability systems to comply with emerging deforestation-free supply chain regulations is a significant capital and operational challenge for producers.
- Artisanal Skill Scarcity:The bean-to-bar and artisanal segments face a shortage of skilled labor, including trained chocolatiers and technicians experienced in small-batch roasting and grinding, which constrains production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chocolate Market |
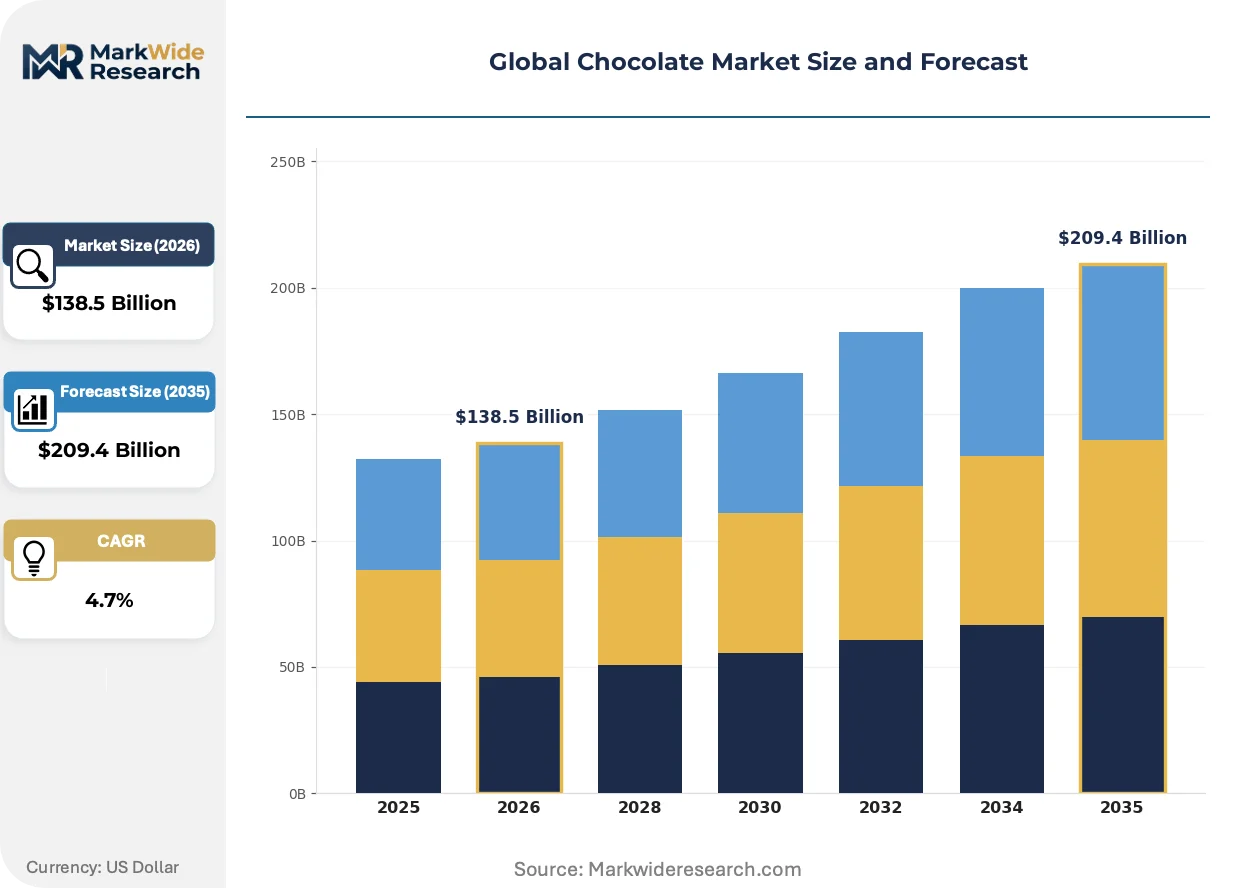
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $209.4 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate, Couverture Chocolate Application: Baking, Confectionery, Beverages, Desserts, Culinary End User: Retailers, Food Service Providers, Specialty Stores, Online Retailers, Wholesalers Packaging Type: Bars, Pouches, Boxes, Gift Wrapping, Bulk Bags |
| Companies Covered | Mars Incorporated, Ferrero International SA, Mondelez International, The Hershey Company, Chocoladefabriken Lindt & Sprüngli AG, Nestlé, Barry Callebaut, Meiji, Pladis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chocolate Market Strategic Shifts & Innovations
The industrialization of transparency and wellness is fundamentally altering product development and supply chain management. Technologies that verify ethical claims and ingredient formulations that support health narratives are shifting from niche differentiators to mainstream competitive requirements for market access.
Blockchain-based traceability platforms provide an immutable, digital ledger for tracking cocoa from the farm level through processing. Major food manufacturers and cocoa processors are adopting these systems to meet new regulatory demands. This technology is displacing traditional, paper-based sourcing records, which were often fragmented and difficult to verify across complex, multi-layered supply chains.
European Union regulations on deforestation-free products are forcing a radical overhaul of cocoa sourcing protocols. This legislation requires operators to prove their commodity imports are not linked to deforestation, placing a heavy compliance burden on supply chain managers. The cocoa industry, with its deep ties to sourcing from West Africa and Latin America, is among the most directly impacted sectors.
Consumer preference is shifting toward products featuring explicit ethical and environmental certifications on their packaging. This trend is disrupting the shelf space of conventional brands in specialty and premium grocery channels, where certifications like Fair Trade or Rainforest Alliance act as powerful purchasing signals. The behavior is most advanced in markets across Western Europe and North America.
Global Chocolate Market Segmentation
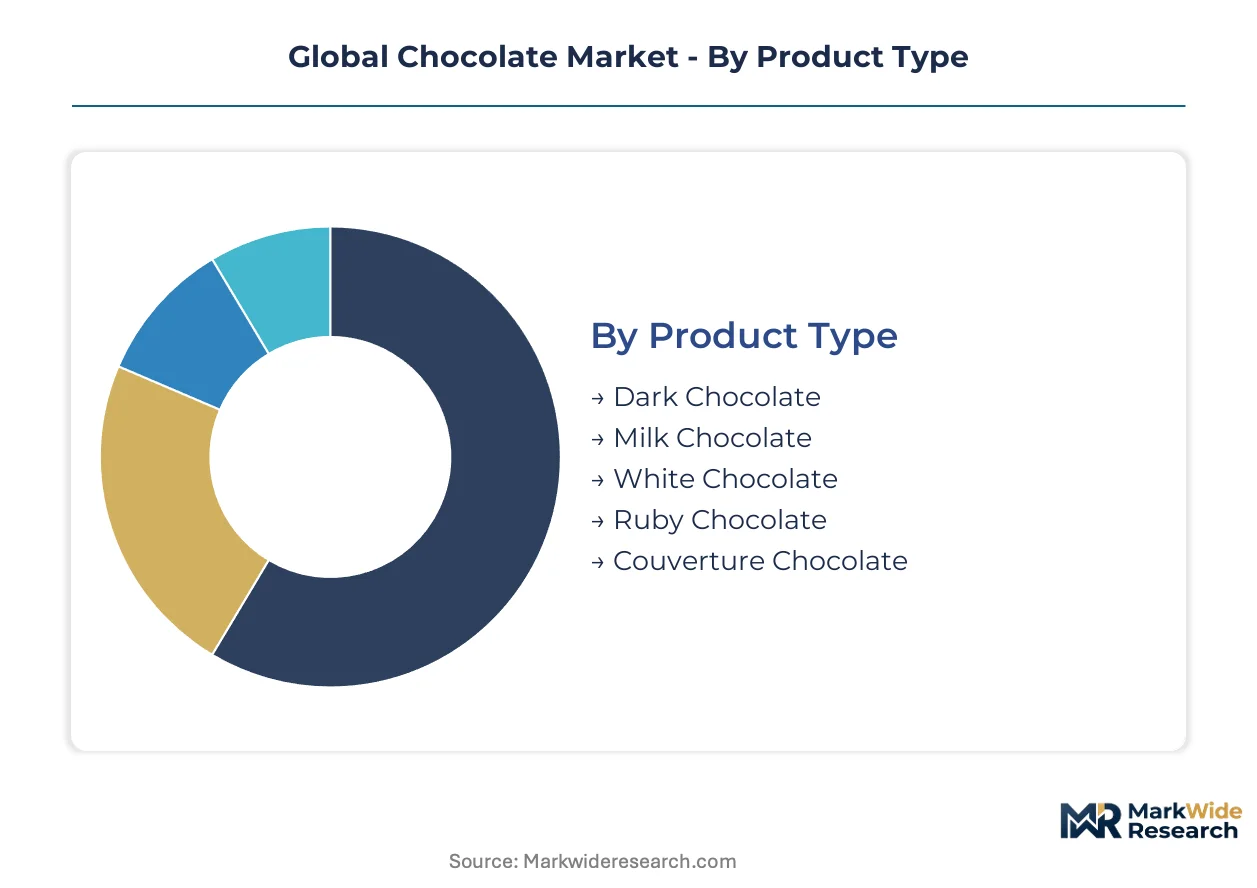
Segmentation in the chocolate market reveals distinct consumer preferences and operational requirements across its value chain. Understanding these divisions helps producers tailor product formulations, distribution strategies, and marketing efforts. Regulatory compliance and sourcing mandates also shape segment growth trajectories.
Product Type:
Regulatory frameworks, such as those from the US FDA and EFSA, significantly differentiate product types based on cocoa solid percentages, influencing market access and consumer perception.
- Dark Chocolate:Characterized by a higher percentage of cocoa solids and less sugar, this variant offers a more intense flavor and perceived health benefits. Its market share expands rapidly in urban centers, particularly in Western Europe, due to health-conscious consumer choices and gourmet appreciation.
- Milk Chocolate:This product contains cocoa solids, cocoa butter, sugar, and milk powder, offering a creamy texture and sweet flavor profile. Demand concentrates heavily in mass-market segments across Europe and North America, driven by established consumer familiarity and broad appeal.
- White Chocolate:This confection contains cocoa butter, sugar, and milk solids but no cocoa solids, appealing to consumers seeking a creamy, sweet experience.
- Ruby Chocolate:A naturally pink chocolate derived from specific cocoa beans, it offers a fruity and slightly sour taste, attracting innovation in premium confectionery.
- Couverture Chocolate:Known for its high cocoa butter content, this professional-grade chocolate is preferred by chefs for its superior melting and tempering properties in baking and patisserie.
Established volume favors Milk Chocolate; emerging adoption favors Ruby Chocolate.
Application:
Application segments are differentiated by the functional requirements and consumption occasions for chocolate, impacting formulation and distribution channels.
- Confectionery:This primary application involves chocolate bars, pralines, and truffles consumed directly as snacks or treats. Global demand remains strong across all geographies, propelled by seasonal holidays and impulse purchases.
- Baking:Professional and home bakers utilize chocolate for cakes, cookies, and pastries, requiring specific melting points and flavor profiles. Demand for high-quality couverture chocolate is notable in the food service sector across the United States.
- Beverages:Chocolate is incorporated into hot cocoa, milkshakes, and specialty coffee drinks, particularly in colder climates.
- Desserts:This segment includes chocolate mousses, puddings, and ice creams, popular in restaurants and home consumption.
- Culinary:Chefs use chocolate in savory dishes, sauces, and garnishes, particularly in high-end gastronomy.
Volume for confectionery applications remains robust; culinary uses are gaining share fastest.
End User:
End-user segments reflect distinct purchasing behaviors and distribution pathways for chocolate products, from direct consumer sales to bulk industrial procurement.
- Retailers:This segment includes supermarkets, hypermarkets, and convenience stores, serving the vast majority of consumer purchases for everyday chocolate products. Distribution networks are critical for market penetration across all urban and suburban areas.
- Food Service Providers:Restaurants, cafes, hotels, and caterers purchase chocolate for use in desserts, beverages, and culinary creations. This segment prioritizes bulk formats and specific functional properties for professional preparation in major cities.
- Specialty Stores:These outlets offer premium, artisanal, and single-origin chocolates, catering to discerning consumers in high-income urban areas.
- Online Retailers:E-commerce platforms provide convenience and access to a wider range of products, driving growth for niche and premium brands globally.
- Wholesalers:These intermediaries supply chocolate in large quantities to smaller retailers and food service businesses, facilitating broad market reach.
Retailers command the largest volume; online retailers are expanding most quickly.
Packaging Type:
Packaging types are designed to meet diverse consumer needs, preservation requirements, and gifting occasions, influencing product presentation and shelf appeal.
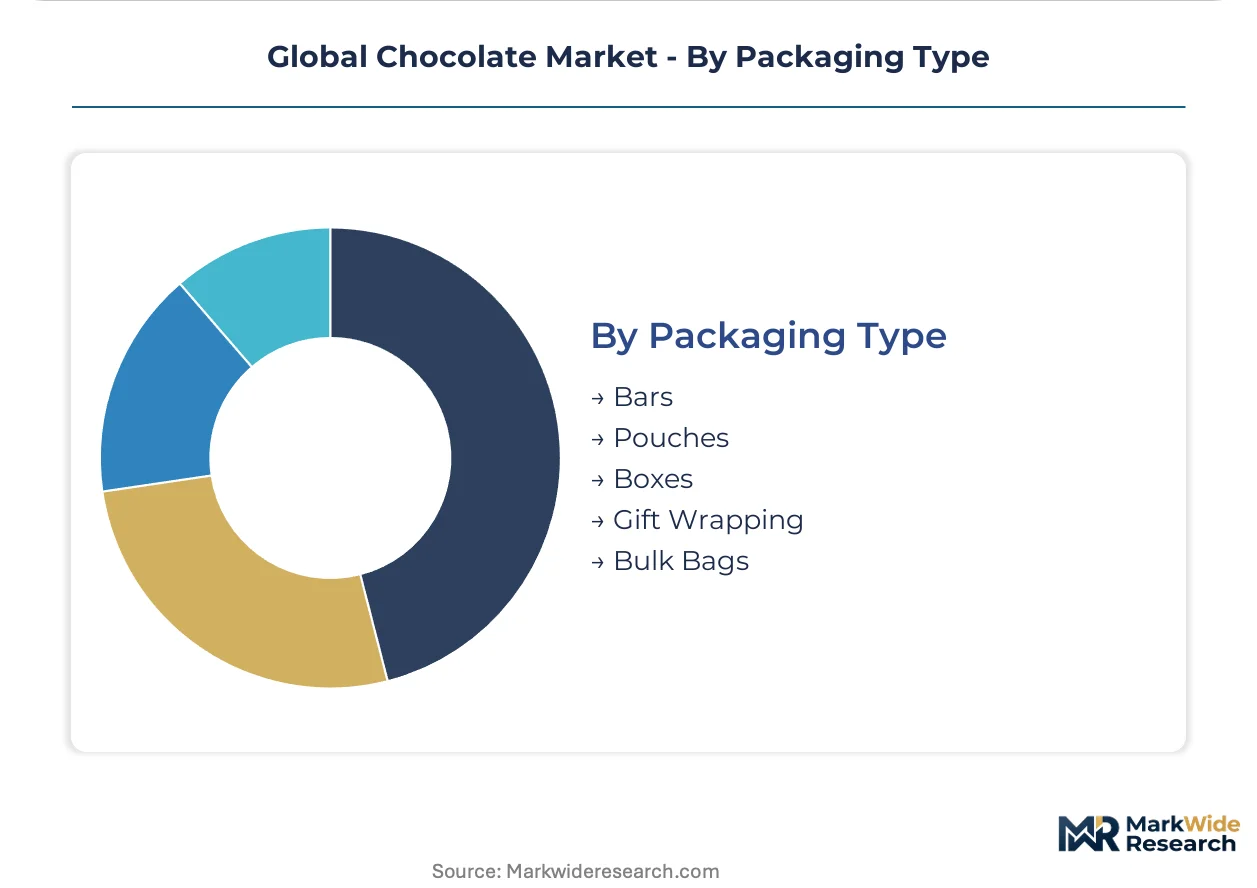
- Bars:This traditional and widely recognized format offers convenience for individual consumption and broad appeal across all price points. Bar packaging dominates impulse purchase locations in grocery stores and convenience outlets worldwide.
- Boxes:Often associated with premium chocolate assortments and gifts, boxes provide aesthetic appeal and protection for delicate products. This packaging type sees heightened demand during holiday seasons in major consumer markets like the United States and Germany.
- Pouches:Flexible and resealable, pouches are popular for chocolate snacks, bites, and smaller confectionery items, offering portability.
- Gift Wrapping:Specialized packaging enhances the perceived value of chocolate products, targeting seasonal and celebratory purchases.
- Bulk Bags:Large format bags cater to industrial users and food service providers, prioritizing cost-effectiveness and volume.
Bars maintain consistent volume; gift wrapping sees steepest expansion trajectory during peak seasons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global chocolate market exhibits a complex regional dynamic, with significant variations in import and export patterns influencing local supply chains and consumer preferences. Demand centers in developed economies drive significant imports of finished chocolate products, while cocoa-producing regions face increasing pressure to meet ethical sourcing mandates for their exports. This structural imbalance shapes trade flows and investment in processing capabilities across continents.
Germany
Demand for premium and dark chocolate varieties continues to expand in Germany, reflecting a discerning consumer base. The EU Green Deal and its deforestation-free product regulations directly impact cocoa sourcing for German manufacturers. Major confectionery hubs like Cologne and Hamburg are adapting their procurement strategies to ensure compliance and maintain product integrity.
United States
Consumer preferences in the United States lean towards both traditional milk chocolate and an expanding range of health-conscious dark chocolate options. The US Food and Drug Administration (FDA) sets specific standards of identity for chocolate products, influencing formulation. Large processing facilities in Pennsylvania and Illinois drive significant volume for both mass-market and specialty brands.
China
The Chinese market is experiencing a surge in demand for premium and artisanal chocolate, particularly within its rapidly urbanizing centers. Local policies encouraging domestic consumption and quality standards are shaping product development. Major metropolitan areas like Shanghai and Beijing are focal points for new product introductions and high-end retail experiences.
Brazil
Brazil's growing middle class is fueling increased consumption of branded chocolate products, creating a robust domestic market. National agricultural policies support local cocoa cultivation, aiming to reduce import dependency. The state of Bahia, a significant cocoa-producing region, is seeing investments in local processing to add value before export or domestic sale.
Côte d'Ivoire
Côte d'Ivoire remains the largest global supplier of cocoa beans, making it central to the chocolate market's raw material supply. New European regulations on deforestation-free supply chains are forcing significant reforms in Ivorian cocoa farming practices. Initiatives in regions like Divo and Soubré focus on farmer training and sustainable land use to meet international standards.
Global Chocolate Market Key Industry Players
Concentration sits with large multinational food conglomerates that leverage extensive distribution networks and established brand recognition. The market structure exhibits a tiered competitive environment, ranging from global mass-market producers to specialized artisanal chocolatiers. Strategic archetypes include volume-driven manufacturers, premium brand custodians, and business-to-business ingredient suppliers. Dominant competitive moves involve portfolio diversification into health-oriented segments and strategic partnerships for sustainable sourcing.
At the scale-driven end, Mars Incorporated and Mondelez International exemplify global reach, offering a broad spectrum of chocolate products across various price points. These entities focus on maintaining high volume through efficient production and vast retail presence. Chocoladefabriken Lindt & Sprüngli AG occupies a position within the premium segment, emphasizing heritage and controlled retail channels. These companies collectively shape market trends through their product development and distribution strategies.
| Leading Market Players |
|---|
| Mars Incorporated |
| Ferrero International SA |
| Mondelez International |
| The Hershey Company |
| Chocoladefabriken Lindt & Sprüngli AG |
| Nestlé |
| Barry Callebaut |
| Meiji |
| Pladis |
| Others |
Cost & Logistics Intelligence
Typical cocoa bean fermentation lead times, often spanning several days, directly influence processing schedules and raw material availability, shaping pricing power for major industrial chocolate suppliers.
Pricing Analysis
The customization-premium spread for chocolate products drives distinct pricing models. Per-unit transactional pricing dominates mass-market segments, while contract-based long-term offtake agreements secure industrial cocoa and chocolate supplies. Price differentiation stems from cocoa quality grade and ethical certifications like Fair Trade or Rainforest Alliance. Pricing pressure intensifies in mass-market segments due to persistent consumer price sensitivity, contrasting with lower price sensitivity among premium chocolate buyers for specialized products.
Supply Chain Analysis
Just-in-time inventory strategies are challenging for cocoa processors due to raw material volatility, favoring strategic stockpiles. Geographic supply concentration centers on Côte d'Ivoire, Ghana, and Brazil for Theobroma cacao seeds. The market faces structural risk from cocoa price volatility, driven by climate events, crop disease, and currency exchange rate instability in West African producing nations. Distribution runs through extensive retailer networks and specialized food service providers globally, reaching diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global chocolate market presents a significant service-attach opportunity. Demand for high-quality couverture chocolate in baking and desserts, requiring specialized technical support and formulation guidance, is expanding faster than general confectionery sales.
For Market Incumbents:Consolidate supply chain traceability systems to comply with emerging EU deforestation-free regulations. Diversify cocoa sourcing beyond West Africa to mitigate geopolitical and climate-related risks, countering supply concentration vulnerability. Invest in advanced processing technologies for functional chocolate innovation, leveraging R&D to differentiate against smaller artisanal brands. Control retail channels through strategic partnerships to maintain premium positioning.
For New Entrants and Emerging Players:Specialized technical support for bean-to-bar operations represents a service-layer gap where incumbents under-serve. Target premium and artisanal segments in urban centers across China and Southeast Asia, offering single-origin varieties. Focus on direct-to-consumer e-commerce platforms to build brand loyalty and capture higher margins. Market differentiation through unique flavor profiles and transparent ethical sourcing narratives provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from large multinational food conglomerates seeking to divest non-core chocolate brands. The market offers long-term viability, driven by sustained global demand and premiumization trends over the next decade. Acquisition archetypes include mid-sized artisanal chocolatiers with strong brand equity and specialized functional chocolate manufacturers. A signal to watch is the increasing adoption of blockchain-based traceability platforms, indicating readiness for regulatory compliance and premium market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Digitization | Implementing blockchain platforms enhances traceability and compliance with deforestation-free regulations for cocoa sourcing. |
| Functional Ingredient Integration | Developing chocolate fortified with probiotics or vitamins appeals to health-conscious consumers and expands product categories. |
| Direct-to-Consumer Channel Expansion | Building e-commerce platforms allows artisanal producers to capture higher margins and establish direct customer relationships. |
| Geographic Market Entry (Southeast Asia) | Tapping into the growing middle class in developing economies creates new consumer bases for branded chocolate products. |
| Sustainable Sourcing Partnerships | Collaborating with cocoa farmers in West Africa ensures ethical supply and meets evolving consumer and regulatory demands. |
Research Approach
Initial hypotheses were tested against primary input from cocoa farmers, chocolate manufacturers, retail buyers, and food service chefs, then refined through iterative analysis. This approach combined insights from in-depth interviews with secondary validation from EU Green Deal documents, FDA standards, EFSA guidelines, and industry association reports. Bottom-up data collection from regional markets was triangulated with top-down market sizing for comprehensive coverage.
Variance decomposition identified key drivers impacting market growth across the analysis window. The analytical framework modeled dimensions including product type, application, end user, packaging type, and cocoa origin. Compound annual growth rates were derived from historical trends and projected demand shifts. Key forecast inputs included cocoa bean price trends and evolving regulatory compliance costs.
Forecasts assume regulatory continuity in EU and US regimes; material policy shifts would require re-modeling. This study reflects current market conditions and acknowledged risk factors like major crop failures or significant changes in international trade policies. Revision becomes warranted when these conditions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
South Africa Confectionery Market
Confectionery
Caramel Market
Confectionery
Functional Confectionery Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Middle East Chocolate Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Low Calorie Treats Market
Confectionery
Low-Calorie Candy Market
Confectionery
Confectionery Fillings Market