
 United Arab Emirates Sugar Confectionery Market | 2026-2036
United Arab Emirates Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Sugar Confectionery Market Analytics
Young adult buyers is reorganizing demand patterns across the United Arab Emirates sugar confectionery landscape, pulling volume toward premium gifting formats and experiential flavors. Patchi leverages its heritage positioning to dominate the luxury chocolate gifting segment in Dubai and Abu Dhabi malls. Ferrero Group sustains share through its Kinder and Tic Tac portfolios, which anchor shelf space in modern trade channels. Mondelez International competes on manufacturing scale, with regional production supporting its Cadbury and Trident lines across Gulf Cooperation Council markets.
Sugar confectionery encompasses sweet, shelf-stable products formulated with sucrose, glucose syrups, and hydrocolloid stabilizers, manufactured through cooking, depositing, or extrusion processes to achieve defined texture profiles from hard-boiled to elastic gel structures; these products serve impulse purchase, celebratory gifting, and portion-controlled snacking occasions across retail and foodservice channels. Chocolate commands the largest value pool, though gummies are recording the fastest volume growth as gelatin-free and pectin-based formulations attract label-conscious consumers. Specialty shops capture disproportionate margin compared with supermarkets, where bulk and bag formats drive transaction frequency but compress unit economics.
MOHAP enforces food safety standards and additive limits for imported and domestically produced confectionery, while municipal authorities in Dubai and Sharjah administer halal certification requirements that govern market access for international suppliers. FSSAI-aligned importers increasingly demand dual-compliant labeling, raising compliance costs for European and Asian exporters. Stakeholders must monitor evolving sugar reduction mandates and local formulation partnerships to sustain shelf placement in a market where regulatory stringency and consumer health consciousness are tightening in parallel.
Market Dynamics
MOHAP's tightening additive disclosure mandates are compressing formulation flexibility across the United Arab Emirates sugar confectionery supply base, forcing manufacturers to revalidate recipes and accelerate clean-label transitions.
Growth Catalysts
- Halal certification standardization:Dubai and Sharjah municipal authorities are harmonizing halal requirements, reducing duplicate testing costs for Gulf Cooperation Council-bound exporters and accelerating cross-border shipment clearances.
- Private-label expansion:Hypermarket chains are broadening in-house confectionery assortments, creating captive demand for regional contract manufacturers with flexible batch capabilities.
- Gifting occasion premiumization:Young adult demographics in Abu Dhabi and Dubai are elevating per-transaction values through experiential flavor preferences and limited-edition packaging formats.
Market Restraints
- Dual-compliance labeling costs:FSSAI-aligned importers are demanding India-UAE dual-compliant packaging, raising per-SKU design and print expenses for European and Asian suppliers.
- Input cost volatility:Glucose syrup prices fluctuate with regional petrochemical feedstock markets, compressing margin predictability for hard-boiled and deposited candy categories.
- Substitution pressure:Pectin-based gummies are displacing traditional gelatin formulations, requiring capital-intensive equipment swaps for legacy manufacturers.
Strategic Opportunities
- Sharjah and Northern Emirates penetration:Retail infrastructure expansion in Ras Al Khaimah and Fujairah is opening underserved corridors for premium confectionery distribution beyond Dubai-Abu Dhabi saturation.
- Sugar reduction partnerships:MOHAP's anticipated reformulation mandates will reward early movers with reformulated product lines and preferred shelf placement in government-affiliated retail channels.
- Experiential retail formats:Mall-based specialty shops are capturing disproportionate margins through customization stations and gift-wedding services that supermarkets cannot replicate.
Industry Challenges
- Reformulation timeline compression:MOHAP's updated disclosure windows are forcing simultaneous recipe revalidation across multiple product lines, straining R&D bandwidth.
- Halal supply chain segregation:Maintaining certified ingredient streams requires dedicated storage and transport infrastructure that multiplies operational complexity for importers serving both halal and conventional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Sugar Confectionery Market |
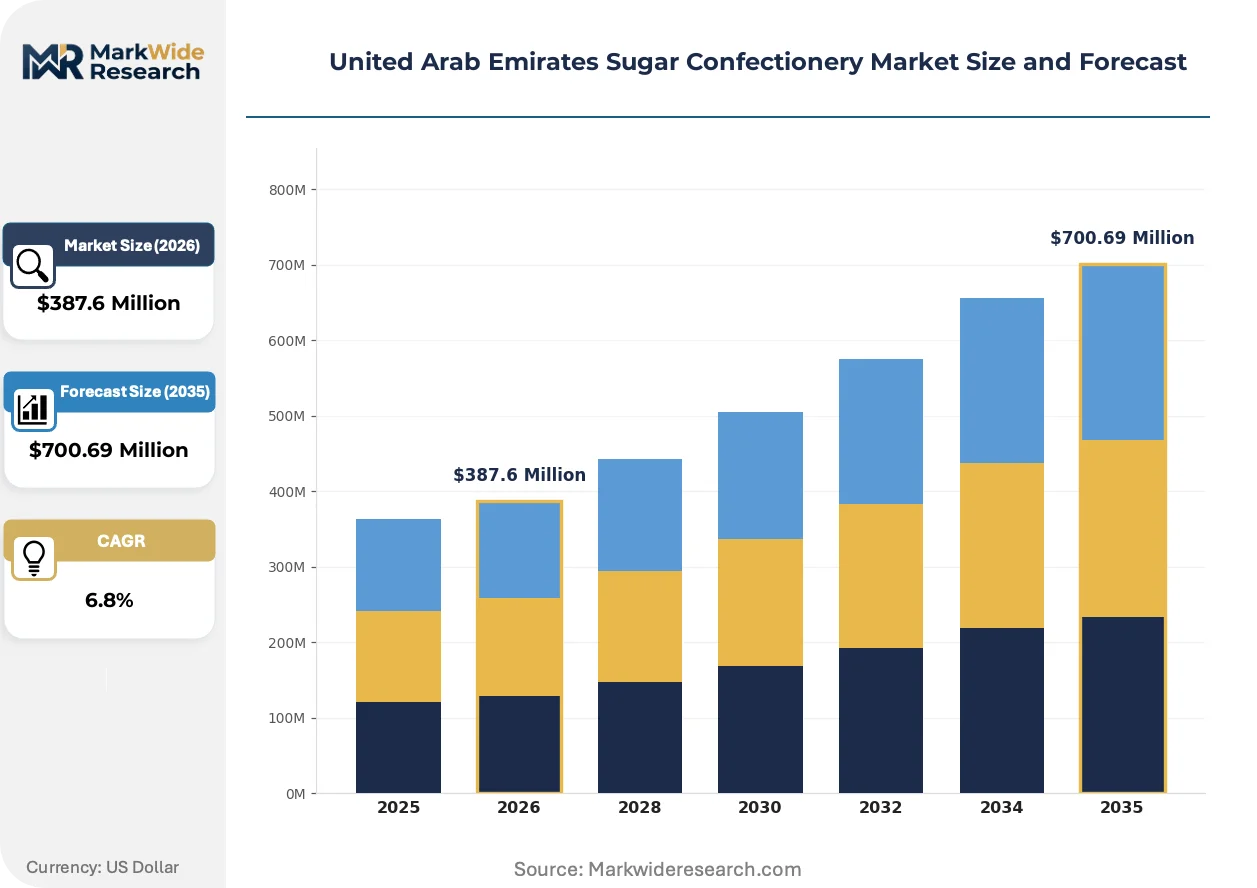
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candies, Mints Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Specialty Shops End User: Children, Adults, Retailers, Wholesale Buyers Packaging Type: Bags, Boxes, Tins, Bulk |
| Companies Covered | HARIBO GmbH & Co. KG, Ferrero Group, Mondelez International Inc., Patchi, August Storck KG, Perfetti Van Melle Group, Nestlé S.A., Gandour, Mars, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Sugar Confectionery Market Evolving Landscape
Clean-label ingredient systems and experiential consumption formats are displacing conventional commodity positioning across the United Arab Emirates sugar confectionery landscape.
Pectin-based gelling technology is miniaturizing production batch sizes for regional manufacturers, enabling rapid flavor prototyping that responds to seasonal demand spikes in Dubai mall retail. Mid-tier producers are adopting small-batch depositing lines that slash minimum order quantities from tens of thousands to hundreds of kilograms. The structural consequence is compressing lead times for private-label programs and enabling hypermarket chains to test limited editions without inventory risk.
MOHAP's updated food labeling requirements are mandating granular additive disclosure on imported and domestically produced confectionery, tightening compliance windows and raising documentation burdens for Gulf Cooperation Council exporters. Manufacturers must now submit batch-specific certificates of analysis for colorants and preservatives previously accepted under blanket approvals. Small importers lacking in-house regulatory affairs capacity are outsourcing compliance to specialized Dubai-based consultancies.
Gifting behavior is fragmenting across occasion-specific formats, with young adult buyers in Abu Dhabi prioritizing portion-controlled premium assortments over traditional bulk purchases for Ramadan and Eid celebrations. Specialty retailers are responding with curated gift-box subscriptions that replace supermarket bag formats. This rotation is most visible in Dubai's Festival City and Mall of the Emirates clusters, where experiential unboxing now drives repeat purchase intent more than price positioning.
United Arab Emirates Sugar Confectionery Market Segmentation
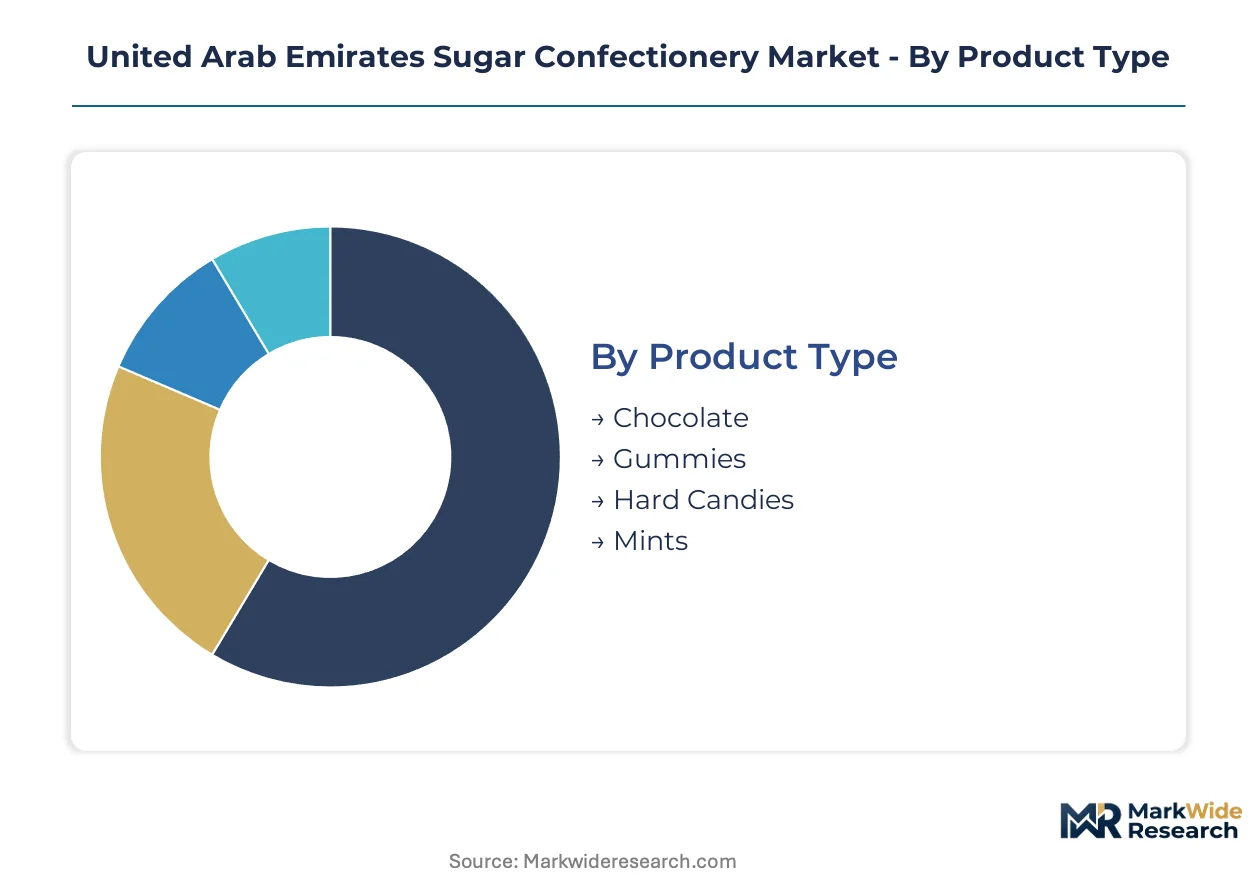
Segmentation in the United Arab Emirates sugar confectionery market reveals how regulatory pressure and gifting culture reshape product positioning across channels. Understanding these divides exposes where margin pools concentrate and where substitution threats erode legacy volume.
Product Type:
Gummies face the sharpest substitution pressure as pectin-based formulations displace gelatin alternatives, while chocolate confronts sugar reduction mandates that threaten traditional recipes.
- Chocolate:Formulated with cocoa mass, cocoa butter, and emulsifiers to achieve defined snap and melt profiles. Dubai and Abu Dhabi malls concentrate premium gifting demand, though MOHAP's anticipated sugar limits force reformulation partnerships with regional contract manufacturers.
- Gummies:Elastic gel structures built on pectin or gelatin gelling systems with acidulants for flavor release. Young adult buyers in Festival City and Mall of the Emirates clusters drive fastest adoption of gelatin-free variants, compressing lead times for flavor prototyping.
- Hard Candies:Amorphous glass matrices formed through high-temperature cooking of sucrose-glucose syrups. Ras Al Khaimah retail expansion opens volume corridors for bulk bag formats.
- Mints:Compressed tablet or deposited formats with cooling agents for breath-freshening occasions. Convenience store placement dominates impulse purchase frequency.
Chocolate anchors the volume base while gummies gain share at the steepest rate.
Distribution Channel:
Cost tier stratification separates premium experiential formats from high-frequency commodity transactions, with specialty shops capturing disproportionate margin per square meter.
- Supermarkets:Modern trade chains with centralized procurement and private-label expansion programs. Dubai hypermarket operators broaden in-house confectionery assortments, creating captive demand for flexible-batch regional manufacturers.
- Specialty Shops:Mall-based retail with customization stations and gift-wedding services. Abu Dhabi and Dubai clusters command premium pricing through experiential unboxing that supermarkets cannot replicate.
- Online Stores:E-commerce platforms with subscription gift-box capabilities. Portion-controlled assortments displace traditional bulk for Ramadan and Eid celebrations.
- Convenience Stores:High-traffic impulse locations with limited SKU breadth. Transaction frequency compensates for compressed unit economics.
Supermarkets move the highest absolute volume while specialty shops expand most quickly.
End User:
Customer type determines packaging format and price point, with young adult demographics reorganizing demand toward portion-controlled premiumization.
- Adults:Primary decision-makers for gifting occasions and label-conscious self-purchase. Experiential flavor preferences elevate per-transaction values in Dubai mall retail.
- Children:Pester-power influence on household purchase with parent-mediated quality filters. Clean-label transitions respond to health-conscious gatekeepers.
- Retailers:B2B procurement for shelf placement with MOHAP compliance documentation requirements. Batch-specific certificates of analysis raise administrative burdens.
- Wholesale Buyers:Volume procurement for foodservice and corporate gifting with minimum order quantity negotiations. Northern Emirates infrastructure expansion opens new corridor access.
Adults drive premium value creation while children sustain base volume throughput.
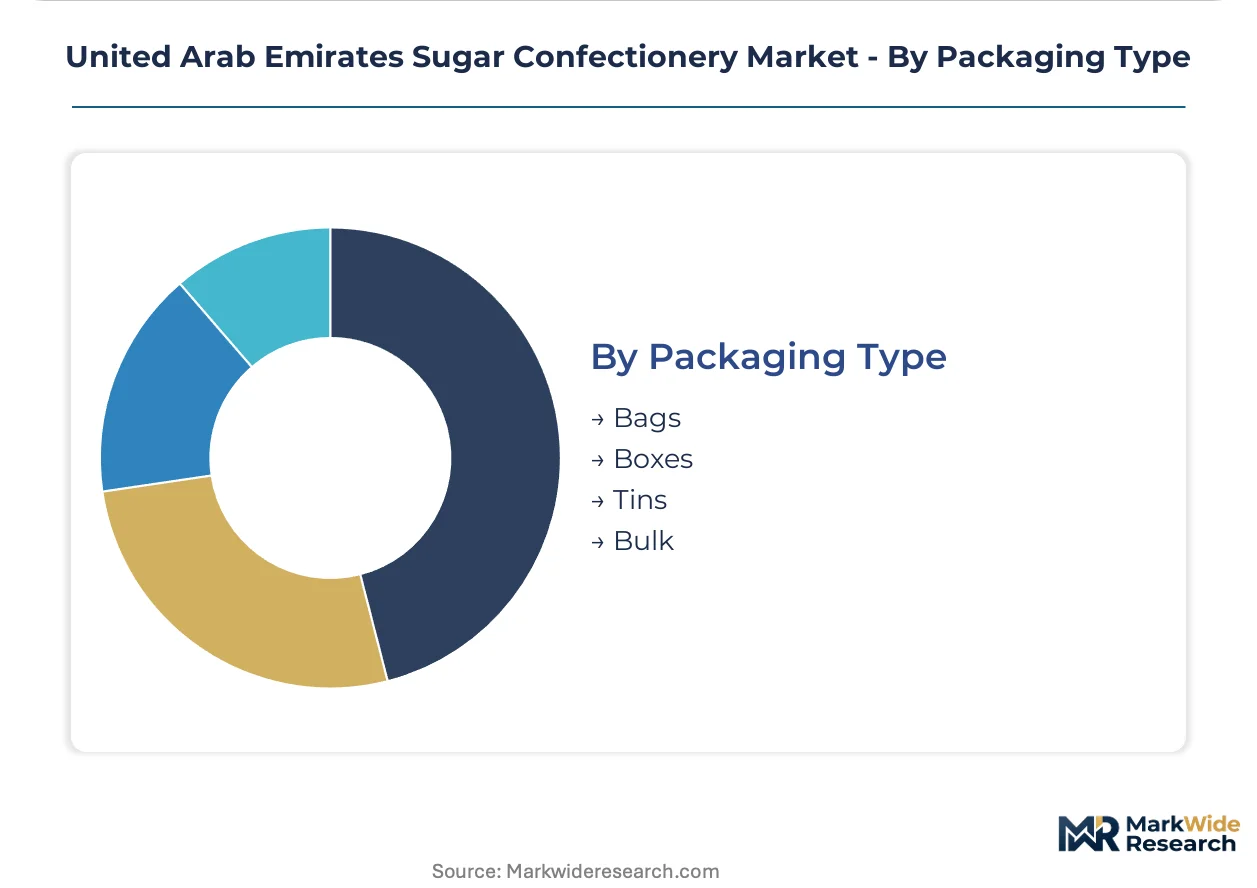
Packaging Type:
Margin structure varies sharply by format, with rigid packaging commanding shelf presence premiums against flexible alternatives.
- Boxes:Rigid board structures with magnetic closures for gifting occasions. Curated subscriptions replace supermarket formats among young adult demographics.
- Bags:Flexible film with reseal features for portion-controlled snacking. Bulk formats compress unit economics in high-frequency channels.
- Tins:Metal containers with heritage positioning for Ramadan and Eid premiumization. Collectible designs extend brand engagement.
- Bulk:Unpackaged or simple-wrap formats for foodservice and ingredient applications. Price-sensitive procurement with minimal branding.
Boxes capture the steepest margin expansion while bags maintain the broadest volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters around Dubai and Abu Dhabi, where mall-based retail infrastructure and halal certification hubs concentrate procurement power. MOHAP's regulatory framework governs formulation standards across all emirates, while municipal authorities in Sharjah administer parallel compliance requirements.
Dubai
Festival City and Mall of the Emirates anchor premium gifting demand, with young adult buyers driving experiential flavor adoption. MOHAP enforces batch-specific additive disclosure for all imported confectionery entering through Jebel Ali port. Specialty retailers in Dubai mall clusters capture disproportionate margins through customization stations and curated gift-box subscriptions.
Abu Dhabi
Yas Mall and Marina Mall concentrate high-transaction-value purchases for Ramadan and Eid celebrations. The emirate's municipal food safety authority aligns with federal MOHAP standards while maintaining separate inspection protocols. Galleria and Al Wahda retail clusters host Patchi flagship locations that dominate luxury chocolate gifting positioning.
Sharjah
Industrial zones in Sharjah host regional contract manufacturers supplying private-label programs for hypermarket chains. The emirate's halal certification body harmonizes requirements with Dubai to reduce duplicate testing costs for GCC-bound exporters. Mega Mall and City Centre Sharjah are expanding confectionery retail space as infrastructure investment flows north from Dubai saturation.
Northern Emirates
Ras Al Khaimah and Fujairah retail corridors remain underserved relative to Dubai-Abu Dhabi density, opening volume opportunities for bulk bag formats. Federal MOHAP standards apply uniformly, though enforcement bandwidth is thinner in these emirates. Al Hamra Mall and Fujairah City Centre are attracting first-mover premium brands as mall development accelerates.
United Arab Emirates Sugar Confectionery Market Competitive Landscape
Concentration sits with diversified multinational conglomerates and heritage-positioned regional specialists. The vendor base splits between scale-driven manufacturers with GCC-wide distribution networks and boutique operators focused on experiential retail formats. Two strategic archetypes dominate: global FMCG conglomerates leveraging manufacturing scale, and family-owned heritage brands commanding premium positioning through mall-based flagship presence. Competitive moves center on private-label contract manufacturing partnerships and reformulation alliances to meet MOHAP's tightening additive disclosure windows.
Within the multinational tier, Ferrero Group and Mondelez International exemplify scale-driven archetypes with Kinder, Tic Tac, Cadbury, and Trident portfolios anchoring modern trade shelf space. Patchi occupies a distinct heritage-positioned niche, leveraging decades of Dubai and Abu Dhabi mall presence to dominate luxury chocolate gifting. Among regional specialists, Gandour represents the contract-manufacturing archetype, supplying private-label programs for hypermarket chains with flexible batch capabilities.
| Leading Market Players |
|---|
| HARIBO GmbH & Co. KG |
| Ferrero Group |
| Mondelez International Inc. |
| Patchi |
| August Storck KG |
| Perfetti Van Melle Group |
| Nestlé S.A. |
| Gandour |
| Mars, Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between hypermarket chains and regional contract manufacturers lock in both glucose syrup supply access and price visibility across the United Arab Emirates sugar confectionery market, insulating procurement teams from petrochemical feedstock volatility while compressing margin flexibility for upstream suppliers.
Pricing Analysis
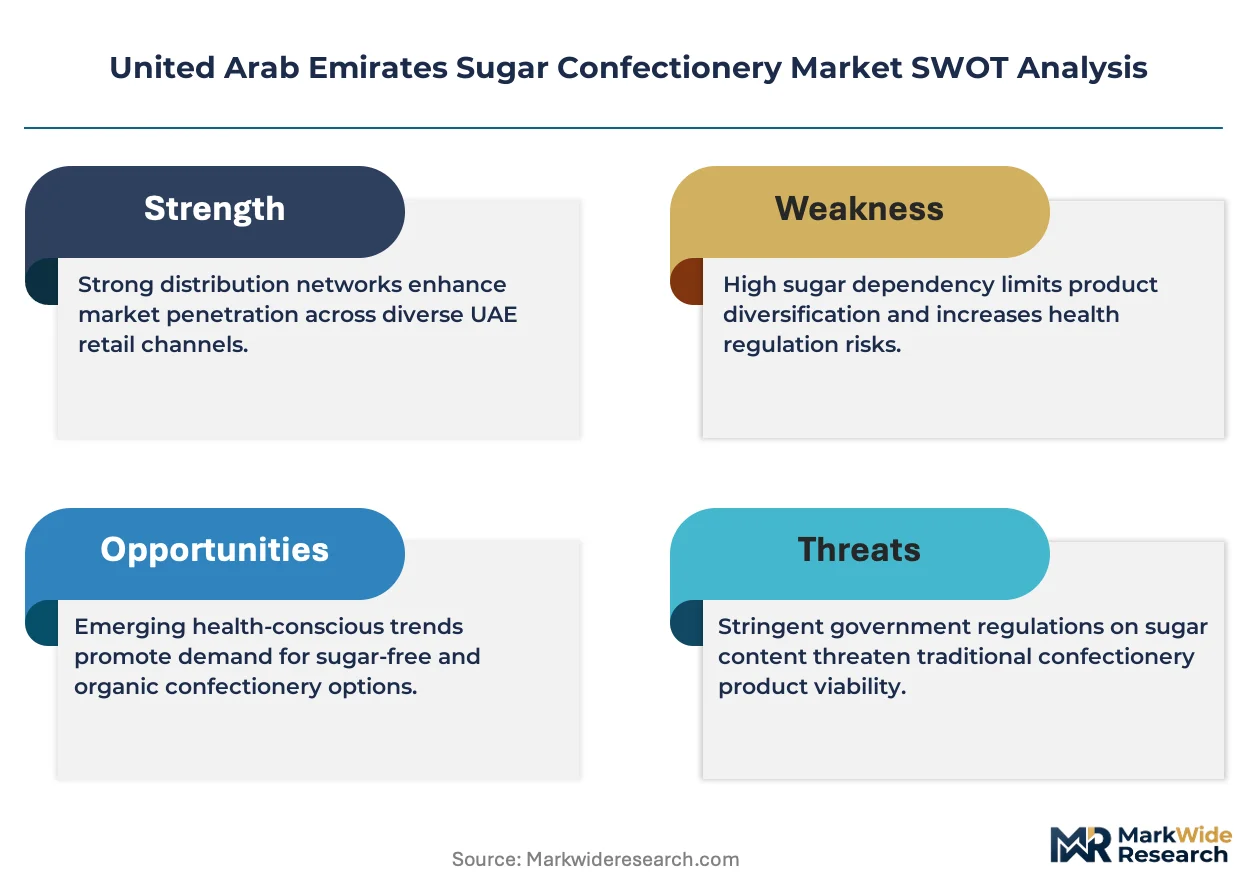
MOHAP's additive disclosure mandates dictate the pricing tier structure across the United Arab Emirates sugar confectionery market, forcing manufacturers to absorb compliance costs or pass them through to buyers. Three-tier pricing structure across premium, standard, and economy levels separates specialty shop assortments from hypermarket private-label and bulk convenience formats. Pricing pressure stems from FSSAI-aligned importers demanding dual-compliant packaging, raising per-SKU design expenses. Supermarket procurement teams exhibit highest price sensitivity, while mall-based specialty retailers maintain lowest sensitivity due to experiential unboxing premiums.
Supply Chain Analysis
Jebel Ali port clearance bottlenecks underwrite distribution velocity for imported confectionery entering the United Arab Emirates, with customs inspection bandwidth directly shaping shelf-stock timing for Ramadan and Eid demand spikes. Manufacturing draws from India, Thailand, and Turkey for pectin and gelatin inputs, while cocoa mass sources from West African origins. Single-source vulnerability concentrates in halal-certified ingredient streams requiring dedicated storage infrastructure. Distribution runs through hypermarket centralized procurement with private-label captive supply, supplemented by direct-to-retailer shipments for specialty shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Arab Emirates sugar confectionery market rewards players who command clean-label formulation expertise and halal certification infrastructure, assets that remain scarce relative to MOHAP's tightening compliance windows.
For Market Incumbents: Secure reformulation partnerships with regional contract manufacturers ahead of MOHAP's anticipated sugar reduction mandates, locking in preferred shelf placement in government-affiliated retail channels. Defend against pectin-based gummy substitution by accelerating gelatin-free line extensions through small-batch depositing investments. Vertical integration into halal-certified ingredient storage reduces cross-contamination risk and streamlines municipal inspection protocols. For New Entrants and Emerging Players: Anchor in Ras Al Khaimah and Fujairah retail corridors where mall infrastructure expansion outpaces incumbent brand saturation, capturing first-mover positioning in underserved Northern Emirates volume pools. Target bulk bag formats for hard candy categories where transaction frequency compensates for compressed unit economics. Pursue private-label manufacturing contracts with hypermarket chains seeking flexible batch capabilities for limited-edition testing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty retailers with subscription gift-box capabilities, as curated Ramadan and Eid assortments displace traditional supermarket bulk purchases. Long-term viability hinges on reformulation agility and clean-label ingredient sourcing relationships. Monitor MOHAP enforcement bandwidth expansion in Northern Emirates as an inflection signal for compliance cost redistribution across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | MOHAP's tightening disclosure windows reward early movers with preferred government-retail shelf placement. |
| Halal Certification Infrastructure Investment | Dedicated storage and transport streams reduce duplicate testing costs for GCC-bound export volumes. |
| Small-Batch Depositing Line Adoption | Pectin-based gummy prototyping compresses lead times for private-label limited editions in Dubai mall retail. |
| Northern Emirates Distribution Expansion | Ras Al Khaimah and Fujairah mall development opens volume corridors beyond Dubai-Abu Dhabi saturation. |
| Subscription Gift-Box Capability Buildout | Curated Ramadan and Eid assortments capture recurring revenue from young adult demographics prioritizing experiential unboxing. |
Research Methodology
Cross-validation between Nielsen retail audit data and customs import records anchors the qualitative findings, with primary interviews involving hypermarket category buyers, regional contract manufacturing plant managers, and MOHAP regulatory affairs specialists triangulated against secondary sources including FSSAI compliance documentation, municipal halal certification registries, and SEC filings from multinational FMCG parents. Bottom-up volume modeling from SKU-level retail tracking converges with top-down macroeconomic consumption indicators.
Sensitivity analysis across price elasticity assumptions and regulatory enforcement scenarios shapes the projection framework, with segmentation dimensions covering product type, distribution channel, end user archetype, and packaging format across the analysis window. CAGRs derive from historical trajectory fitting adjusted for structural breaks including MOHAP's updated labeling requirements and private-label expansion acceleration. Forecast inputs incorporate glucose syrup price volatility indices and mall retail space expansion timelines.
Underlying assumptions cover MOHAP enforcement uniformity across emirates and halal certification harmonization between Dubai and Sharjah municipal authorities, with deviation risk concentrated in Northern Emirates inspection bandwidth constraints and FSSAI-UAE dual-compliance cost trajectories. Practitioners should keep alternative scenarios live as sugar reduction mandate timing and petrochemical feedstock price cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Fat Candy Market
Confectionery
Bangladesh Candy Market
Confectionery
Global Candy Market
Confectionery
Africa Compound Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Confectionery Coating Market
Confectionery
South Africa Confectionery Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
India Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Functional Confectionery Market