
 Germany Chocolate Market | 2026-2036
Germany Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Chocolate Market Analysis
Confectionery engineering talent is reorganizing around precision tempering and bean-to-bar traceability systems, reshaping how mid-sized producers scale artisan quality. Mars Incorporated leverages vertical integration from cocoa sourcing to retail packaging, sustaining cost discipline across its German operations. Alfred Ritter GmbH & Co. KG anchors its competitive position through ethical sourcing credentials and regionally rooted brand identity in Waldenbuch.
Germany chocolate comprises cocoa mass, cocoa butter, sugar, and milk solids formulated through conching, tempering, and molding processes to achieve defined particle size below 20 microns and stable polymorphic crystal structures for snap, gloss, and shelf stability. Milk chocolate occupies the largest volume tier due to entrenched consumer preference, while dark chocolate leads margin expansion as cocoa percentage claims command premium positioning in specialty stores. The food service segment competes for share against retail consumers as hotel and restaurant channels rebuild post-pandemic dessert and gifting programs.
Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces cocoa content labeling and allergen declarations, while EU REACH and EFSA frameworks govern pesticide residues and food contact materials. These standards elevate compliance costs for importers but protect domestic manufacturers from price-based substitution. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their implementation timeline for mandatory geolocation traceability of cocoa origins.
Market Dynamics
EU deforestation-free supply chain regulations are forcing German chocolate manufacturers to rebuild cocoa procurement around mandatory geolocation traceability, compressing supplier relationships and elevating compliance infrastructure as a competitive differentiator.
Growth Catalysts
- Artisan bakery expansion:Specialty confectionery shops in Bavaria and North Rhine-Westphalia are scaling chocolate procurement for premium dessert programs, creating sustained demand for high-cocoa-mass formulations.
- EFSA pesticide residue frameworks:Stricter enforcement of maximum residue limits is pushing domestic manufacturers toward certified organic cocoa sourcing, insulating them from price-based import competition.
- Bean-to-bar traceability systems:Precision tempering technology adoption is enabling mid-sized producers to replicate artisan quality at scaled volumes, reshaping competitive positioning in the specialty segment.
Market Restraints
- Cocoa butter price volatility:Input costs fluctuate with West African supply disruptions and currency movements, compressing margin stability for processors lacking long-term origin contracts.
- EU REACH compliance burden:Registration, evaluation, and authorization of chemical substances elevates fixed costs for imported chocolate products, creating asymmetric disadvantage versus domestic manufacturers.
- Plant-based confectionery substitution:Oat milk and nut-based alternatives are capturing lactose-intolerant and flexitarian consumers, eroding traditional milk chocolate volume in urban demographics.
Strategic Opportunities
- Hotel and restaurant channel rebuilding:Post-pandemic dessert program expansion across German hospitality is reopening food service procurement pipelines for portion-controlled and single-origin chocolate formats.
- EU Green Deal alignment:Carbon footprint labeling and sustainable packaging mandates are creating premium positioning opportunities for manufacturers with verified supply chain decarbonization.
- Dark chocolate margin expansion:Cocoa percentage claims above seventy percent command shelf price premiums in specialty retail, rewarding producers with direct origin relationships and transparent provenance marketing.
Industry Challenges
- Confectionery engineering talent scarcity:Precision tempering and polymorphic crystal control expertise is concentrating among aging specialists, constraining quality scaling for emerging producers.
- Geolocation traceability integration:Mandatory GPS coordinate documentation for cocoa farm origins requires ERP system overhauls and supplier audit expansion, stretching mid-cap operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Chocolate Market |
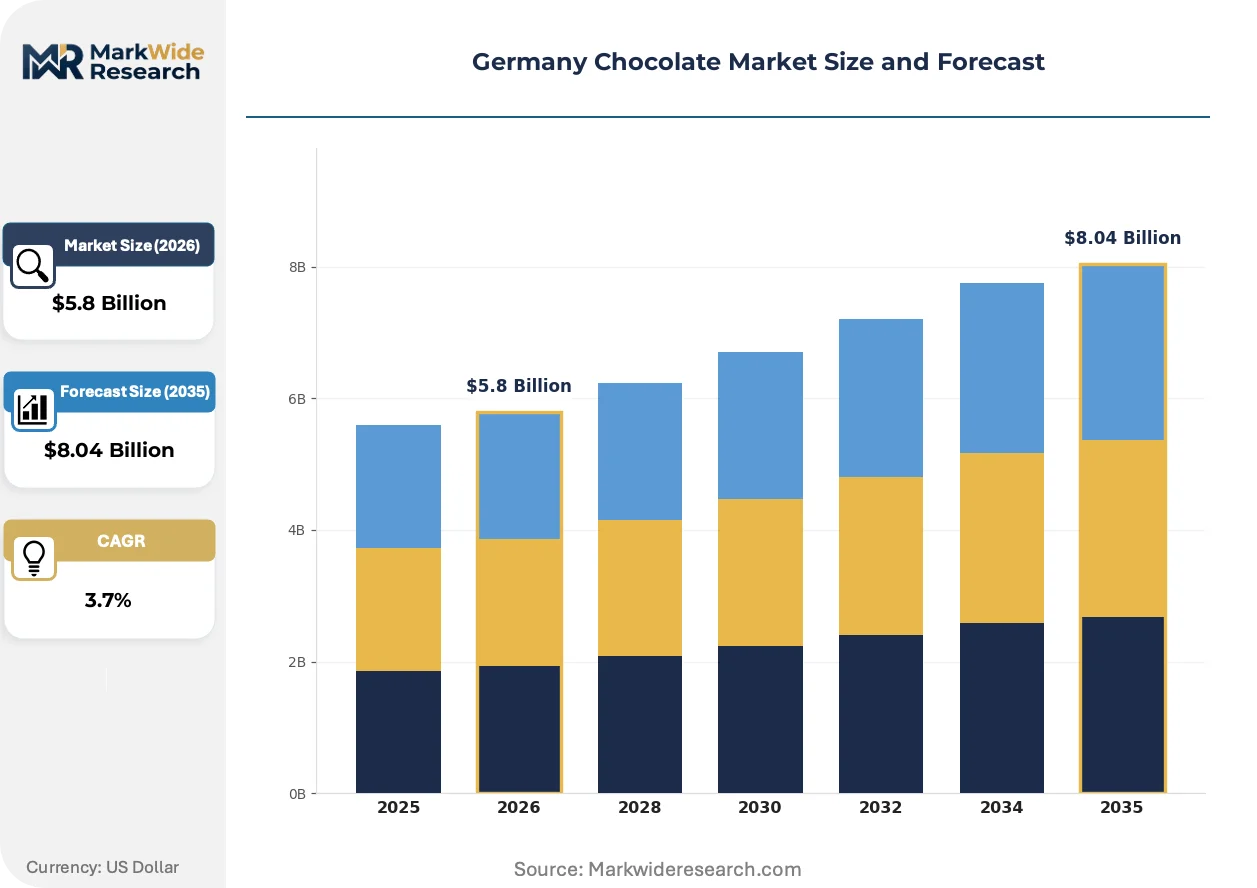
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Food Service, Confectionery Manufacturers, Bakeries Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Mars Incorporated, Nestlé SA, Ferrero International SA, Stollwerck GmbH, Alfred Ritter GmbH & Co. KG, August Storck KG, Mondelēz International Inc., Barry Callebaut Group, Chocoladefabriken Lindt & Sprüngli AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Chocolate Market Emerging Trajectories
Conching and tempering equipment is miniaturizing across German production floors, while regulatory traceability mandates and shifting procurement patterns are compressing traditional supply chain configurations.
Precision conching technology is miniaturizing. Bean-to-bar equipment manufacturers are deploying compact, continuous-flow systems that reduce particle size below twenty microns without batch-scale infrastructure. Craft producers in Stuttgart and Cologne are adopting these systems to localize production and shorten quality feedback loops. This compression is miniaturizing the capital barrier between artisan and industrial scale, fragmenting volume concentration among established processors.
EU deforestation-free regulation is reshaping cocoa sourcing. Mandatory geolocation traceability requirements will compel German importers to document farm-level GPS coordinates and deforestation risk assessments. Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement timelines are accelerating supplier audit frequency and documentation burden. Mid-sized manufacturers with existing direct-trade relationships are adapting faster than traders reliant on opaque commodity sourcing.
Dark chocolate preference is rotating procurement toward high-cocoa-origin contracts. Specialty retailers in Berlin and Hamburg are curating single-origin bars with transparent farm pricing, displacing blended commodity formulations from premium shelf space. Consumers are paying explicit premiums for percentage claims and origin storytelling, compressing brand loyalty for legacy milk chocolate portfolios. This shift is most visible in urban centers with dense specialty food retail clustering.
Germany Chocolate Market Segmentation
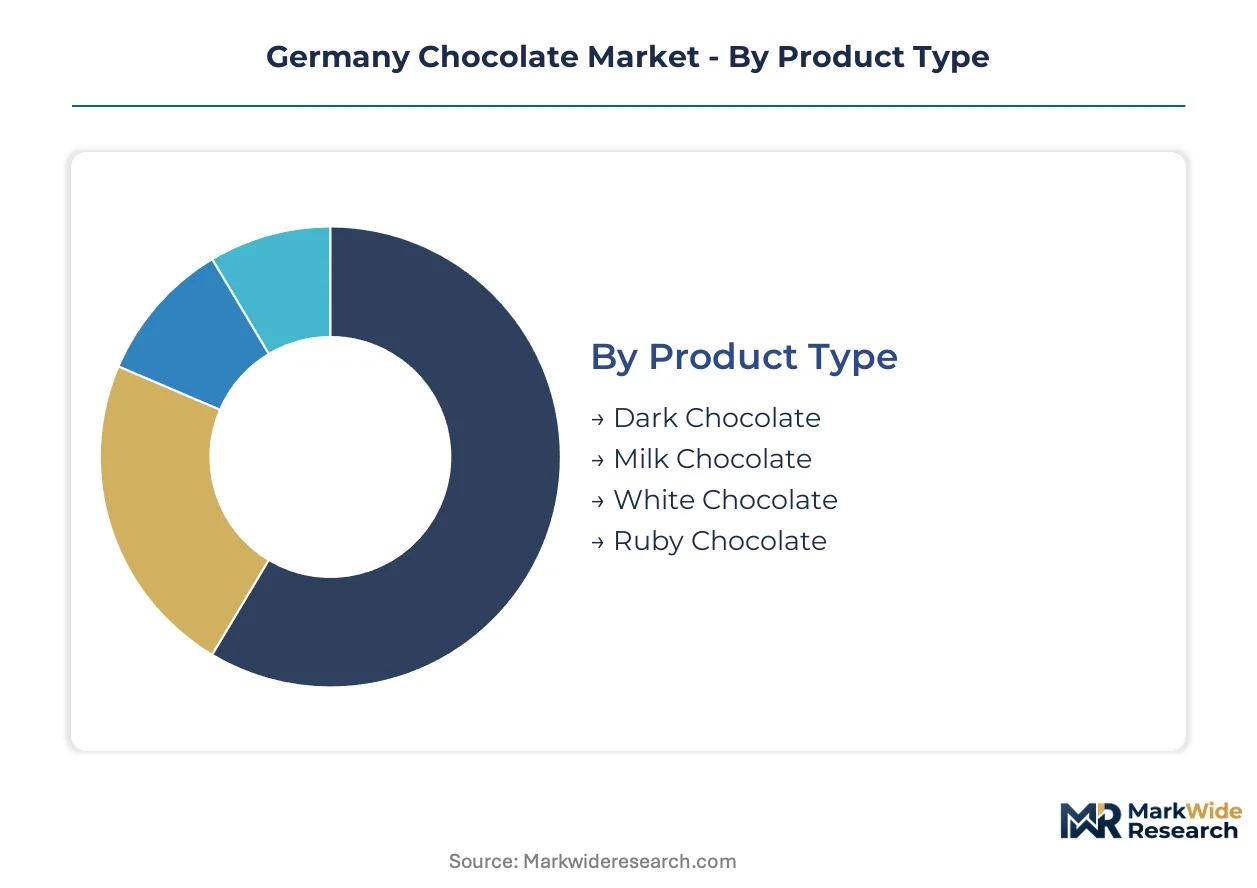
German chocolate procurement patterns fragment across four intersecting dimensions. Product formulations, end-use applications, channel structures, and price positioning each concentrate demand in distinct clusters that reward specialized supply chain configurations.
Product Type:
Plant-based and functional confectionery substitutes exert pressure most intensely on milk chocolate formulations, while high-cocoa segments defend position through provenance differentiation.
- Milk Chocolate:Formulated with cocoa butter, milk solids, and sugar through conching to sub-20 micron particle size for snap and gloss stability. Bavarian and North Rhine-Westphalian bakeries sustain procurement volume for dessert applications despite oat-milk substitution in urban flexitarian demographics. Milk chocolate retains volume leadership; dark chocolate holds the steepest expansion curve.
- Dark Chocolate:Cocoa mass exceeds fifty percent, with percentage claims above seventy commanding shelf price premiums in Berlin and Hamburg specialty retail. Direct origin relationships and transparent farm pricing enable margin expansion as consumers displace blended commodity formulations. Dark chocolate gains share fastest in urban centers with dense specialty food clustering.
- White Chocolate:Cocoa butter base without cocoa mass, regulated under EU cocoa content labeling standards enforced by Bundesamt für Verbraucherschutz und Lebensmittelsicherheit. Demand concentrates in confectionery manufacturing and premium dessert decoration.
- Ruby Chocolate:Ruby cocoa bean variety delivering natural pink coloration without artificial additives, positioned between milk and dark in cocoa intensity. Limited production scale constrains widespread food service adoption.
Dark chocolate climbs the fastest; milk chocolate defends absolute volume position.
End User:
Channel rebuilding velocity varies sharply, with hospitality recovery outpacing retail format innovation in procurement growth rates.
- Food Service:Hotels and restaurants in Munich and Frankfurt are rebuilding post-pandemic dessert programs, reopening procurement pipelines for portion-controlled and single-origin formats. Food service represents the steepest expansion trajectory; retail consumers defend volume concentration.
- Retail Consumers:Supermarket and online purchasing of tablet, praline, and seasonal gifting formats sustains baseline demand across price tiers. EFSA pesticide residue frameworks push certified organic preferences in affluent urban households.
- Confectionery Manufacturers:Industrial-scale procurement of couverture and bulk chocolate for praline, truffle, and enrobed product lines. Bean-to-bar traceability requirements compress supplier relationships toward direct-origin contracts.
- Bakeries:Artisan shops in Stuttgart and Cologne scale chocolate procurement for premium dessert programs, adopting miniaturized precision tempering equipment to localize production.
Retail consumers anchor volume; food service posts the sharpest recovery gradient.
Distribution Channel:
Channel concentration is reshaping around traceability transparency and convenience density, with specialty formats gaining margin while mass retail defends throughput.
- Specialty Stores:Curated single-origin bars with transparent farm pricing displace blended formulations from premium shelf space in Berlin and Hamburg. EU Green Deal alignment creates premium positioning for carbon footprint labeling.
- Supermarkets:Volume concentration for standard and mid-range tablets, pralines, and seasonal assortments across Edeka, Rewe, and Aldi networks. Private label expansion compresses branded margin at budget tiers.
- Online Retail:Direct-to-consumer subscription and gifting formats enable provenance storytelling and percentage claim transparency. Logistics infrastructure supports temperature-controlled shipping for high-cocoa formulations.
- Convenience Stores:Impulse-oriented single-serve and small-format positioning for immediate consumption. Limited shelf space favors established brand recognition over origin narrative.
Supermarkets retain volume leadership; specialty stores command the steepest margin expansion.
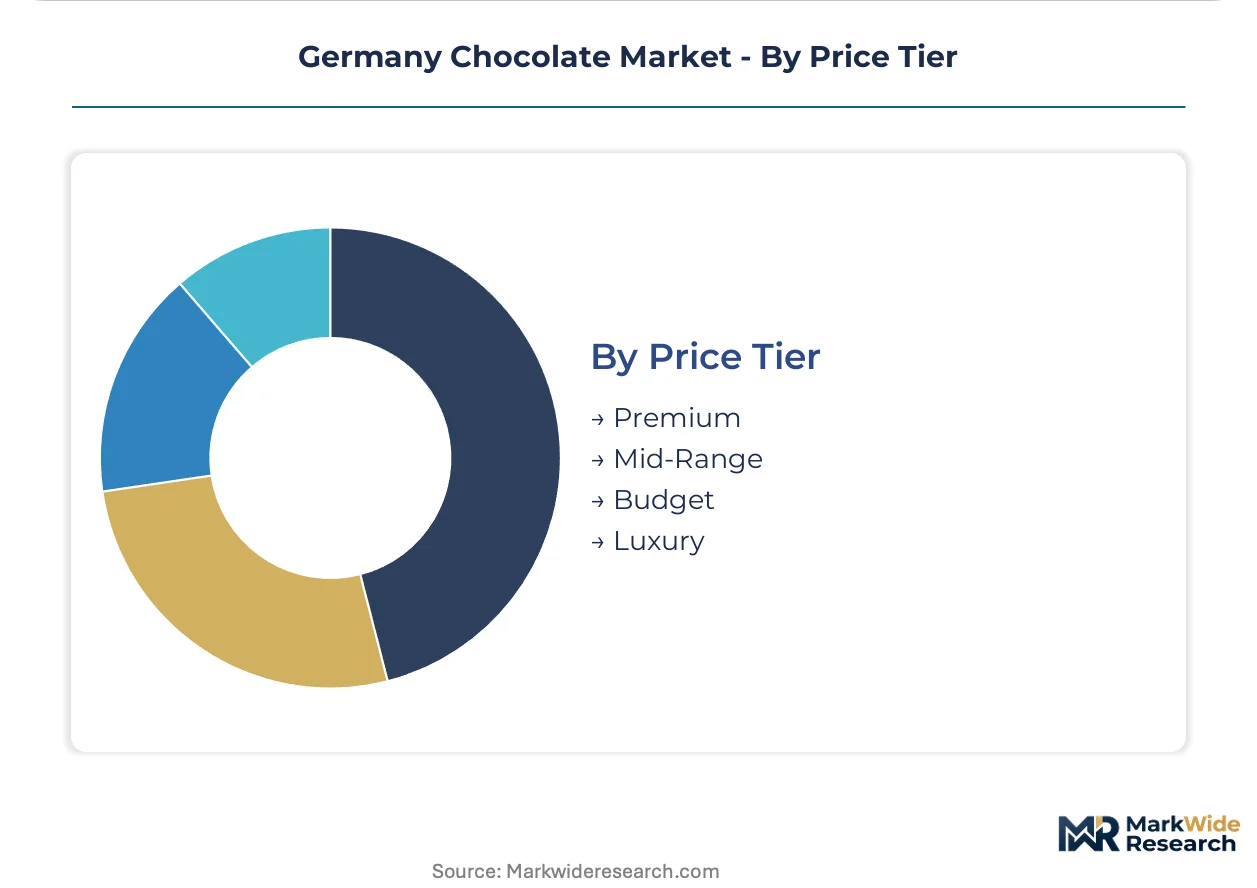
Price Tier:
Cost tier stratification concentrates margin capture at extremes, with mid-range positioning facing compression from both premium provenance and private-label efficiency.
- Premium:Cocoa percentage claims, single-origin credentials, and ethical sourcing certifications command shelf price premiums in specialty retail. Direct trade relationships and transparent farm pricing justify positioning above mass-market formulations.
- Luxury:Ultra-premium gifting and limited-edition releases with artisan production credentials and regional brand heritage. Ritter and comparable domestic manufacturers anchor positioning through Waldenbuch-rooted identity.
- Mid-Range:Branded tablet and praline formats competing on recognition and distribution density. Private-label substitution and premium tier compression constrain margin stability.
- Budget:Private-label supermarket assortments and basic couverture for industrial applications. REACH compliance burden creates asymmetric disadvantage for imported products versus domestic manufacturing.
Premium tier captures margin leadership; luxury segment posts the steepest value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate consumption patterns across Germany diverge sharply between southern artisan traditions and northern industrial concentration, with regulatory enforcement intensity varying by state-level food authority capacity.
Bavaria
Artisan bakeries in Munich and Nuremberg drive procurement of high-cocoa-mass couverture for premium dessert programs, while the Bavarian State Office for Health and Food Safety applies stringent cocoa content verification. Regional craft producers cluster around historic confectionery districts in the Alpine foothills.
North Rhine-Westphalia
Industrial chocolate processing dominates the Cologne-Düsseldorf corridor, with food service distributors rebuilding hotel and restaurant supply chains post-pandemic. The State Agency for Nature, Environment and Consumer Protection enforces EU deforestation-free documentation requirements for imported cocoa. Specialty retailers in Düsseldorf curate single-origin formats for affluent urban demographics.
Baden-Württemberg
Precision engineering heritage in Stuttgart supports adoption of miniaturized bean-to-bar tempering equipment among craft producers. The Regional Council Stuttgart coordinates with Bundesamt für Verbraucherschutz und Lebensmittelsicherheit on pesticide residue testing protocols. Artisan shops localize production to shorten quality feedback loops.
Hesse
Frankfurt's financial services sector sustains corporate gifting demand for premium chocolate assortments, while logistics hubs in the Rhine-Main region facilitate temperature-controlled distribution. The Hessian Ministry for the Environment monitors REACH compliance for food contact materials in packaging. Food service procurement pipelines for portion-controlled formats are reopening.
Hamburg
Port infrastructure enables direct cocoa bean importation for bean-to-bar processors, with specialty retailers in the Speicherstadt district commanding shelf price premiums for transparent provenance marketing. The Hamburg Authority for Health and Consumer Protection enforces allergen declaration standards. Direct-trade relationships accelerate faster here than in trader-dependent regions.
Germany Chocolate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-sized regional manufacturers defending position through ethical sourcing credentials and localized brand identity. The market structure concentrates volume among multinational processors with captive cocoa supply chains, while craft producers fragment share through provenance differentiation. Two strategic archetypes dominate: vertically integrated global processors with origin-to-retail control, and family-owned regional specialists with heritage-rooted positioning. Competitive moves center on direct-origin contract expansion and precision tempering technology licensing.
Among integrated global processors, Mars Incorporated and Mondelēz International occupy positions defined by scale-driven procurement and distribution density across German retail networks. Alfred Ritter GmbH & Co. KG anchors the family-owned specialist archetype, with its Waldenbuch-rooted identity exemplifying regionally concentrated brand loyalty. These three represent the competitive tension between volume efficiency and provenance authenticity that shapes procurement decisions across Bavarian and North Rhine-Westphalian channels.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé SA |
| Ferrero International SA |
| Stollwerck GmbH |
| Alfred Ritter GmbH & Co. KG |
| August Storck KG |
| Mondelēz International Inc. |
| Barry Callebaut Group |
| Chocoladefabriken Lindt & Sprüngli AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day cocoa bean transit from West African ports to Hamburg processing facilities compresses inventory turns and amplifies margin exposure to currency swings and freight rate spikes. This lead-time band concentrates pricing power among processors with captive origin contracts while forcing spot-dependent competitors into defensive hedging positions.
Pricing Analysis
Long-term offtake agreements with Ivorian and Ghanaian cooperatives dominate procurement for integrated processors, insulating them from spot cocoa butter volatility that erodes margins for traders lacking backward integration into origin sourcing. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa percentage certification and provenance documentation depth. Cost compression in mid-range tablet formats intensifies as private-label substitution accelerates through Aldi and Rewe networks. Budget-tier buyers exhibit acute price sensitivity, while luxury segment purchasers prioritize ethical sourcing credentials over per-kilogram cost.
Supply Chain Analysis
Abidjan and San Pedro port congestion underwrites systemic delay risk for German processors dependent on West African bean arrivals. Côte d'Ivoire, Ghana, and Cameroon anchor raw material sourcing, with Ecuador emerging as secondary origin for fine-flavor varietals. Processing draws from cocoa butter, cocoa mass, and sugar inputs, with milk powder sourcing increasingly contested by oat-based alternatives. Single-source vulnerability concentrates in West African political instability and harvest variability. Distribution runs through temperature-controlled logistics networks serving Edeka and Rewe retail systems alongside direct-to-specialty-store channels in Berlin and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German chocolate demand tracks hospitality sector recovery cyclicality, with hotel and restaurant dessert program rebuilding creating procurement inflection as corporate gifting normalizes.
For Market Incumbents: Fortify direct-origin contract coverage in Ecuador and Peru to escape commodity price volatility compressing mid-range margins, while accelerating precision tempering technology licensing to defend quality positioning against craft producer encroachment in Bavaria. EU deforestation-free geolocation mandates threaten traders lacking audit infrastructure. For New Entrants and Emerging Players: Anchor in post-pandemic food service channel rebuilding across Munich and Frankfurt, where portion-controlled single-origin formats face limited established supplier penetration. Target artisan bakery couverture procurement in Stuttgart and Cologne, leveraging miniaturized bean-to-bar equipment to localize production and shorten quality feedback loops against industrial scale competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned regional specialists with Waldenbuch-style heritage positioning but lacking capital for ERP traceability overhauls required by EU deforestation regulations. Long-term viability favors processors with verified supply chain decarbonization aligned to EU Green Deal carbon footprint labeling mandates. Monitor Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement timeline acceleration as inflection signal for compliance cost asymmetry.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Origin Contract Expansion | Secures Ivorian and Ghanaian cooperative relationships ahead of mandatory GPS traceability enforcement by BVL. |
| Precision Tempering Technology Licensing | Enables mid-sized producers to replicate artisan quality at scaled volumes in Stuttgart engineering clusters. |
| Carbon Footprint Labeling Certification | Aligns with EU Green Deal mandates creating premium positioning in Berlin and Hamburg specialty retail. |
| Food Service Channel Rebuilding | Captures post-pandemic hotel and restaurant dessert program procurement in Munich and Frankfurt. |
| ERP Traceability System Overhaul | Supports mandatory geolocation documentation for cocoa farm origins under EU deforestation-free regulations. |
Methodological Framework
Initial hypotheses were tested against primary input from confectionery engineering directors, cocoa procurement managers at integrated processors, specialty retailer buyers in Berlin and Hamburg, and Bundesamt für Verbraucherschutz und Lebensmittelsicherheit compliance officers, and refined through secondary validation against EU REACH filings, EFSA pesticide residue databases, German customs import records, and industry association production statistics. Bottom-up volume modeling triangulated against top-down value estimates derived from retail audit data.
Variance decomposition across product type, end-use application, distribution channel, and price tier segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated cocoa butter price volatility assumptions and EU deforestation regulation implementation phasing.
Decision-makers should treat outputs as directional under sustained artisan bakery expansion and hospitality recovery base assumptions; material deviation in West African supply conditions or regulatory enforcement acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal packaging mandates and plant-based substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
US Confectionery Market
Confectionery
Macarons Market
Confectionery
Premium Chocolate Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Global Compound Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Durian Chocolate Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Gummy Market
Confectionery
North America Chocolate Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Sugar Confectionery Market
Confectionery
Global Industrial Chocolate Market