
 Dunnage Trays Market | 2026-2036
Dunnage Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Dunnage Trays Market Analysis
Automotive-grade dunnage is bifurcating the Dunnage Trays landscape as OEMs enforce stricter vibration-resistance and surface-finish specifications for precision components. DS Smith leverages its European corrugated plastics expertise to supply modular returnable systems to German automakers. Sonoco Products Company anchors North American demand through its captive thermoforming capacity and direct OEM relationships. Menasha Corporation differentiates via integrated design-to-delivery services spanning structural foam engineering and closed-loop logistics management.
Dunnage trays are rigid or semi-rigid containment platforms engineered from thermoformed plastics, corrugated fiberboard, or expanded foams, typically featuring cell-dividers, nesting geometry, and stack-locating rails to immobilize parts during transit and handling. Their primary purpose centers on eliminating surface abrasion, shock damage, and contamination for high-value manufactured goods moving through multi-modal supply chains. Plastic dunnage trays dominate unit volume owing to durability across hundreds of use cycles, yet foam-insert configurations command premium positioning in electronics and pharmaceutical applications where electrostatic discharge and particulate control are critical. Custom-size fabrication represents the fastest-expanding dimension as automotive and medical device customers specify cavity layouts matched to unique component geometries, compressing design-to-production lead times.
The US EPA regulates recycled-content thresholds under Resource Conservation and Recovery Act frameworks, while the EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that reshape material selection and end-of-life collection obligations for tray suppliers. ISO 9001 and sector-specific automotive quality certifications operate as de facto market-access filters, particularly for suppliers serving tier-one automotive and pharmaceutical contract manufacturers. Stakeholders must monitor evolving state-level recycled-plastic mandates and OEM packaging-waste reduction targets to align product development and capital allocation decisions.
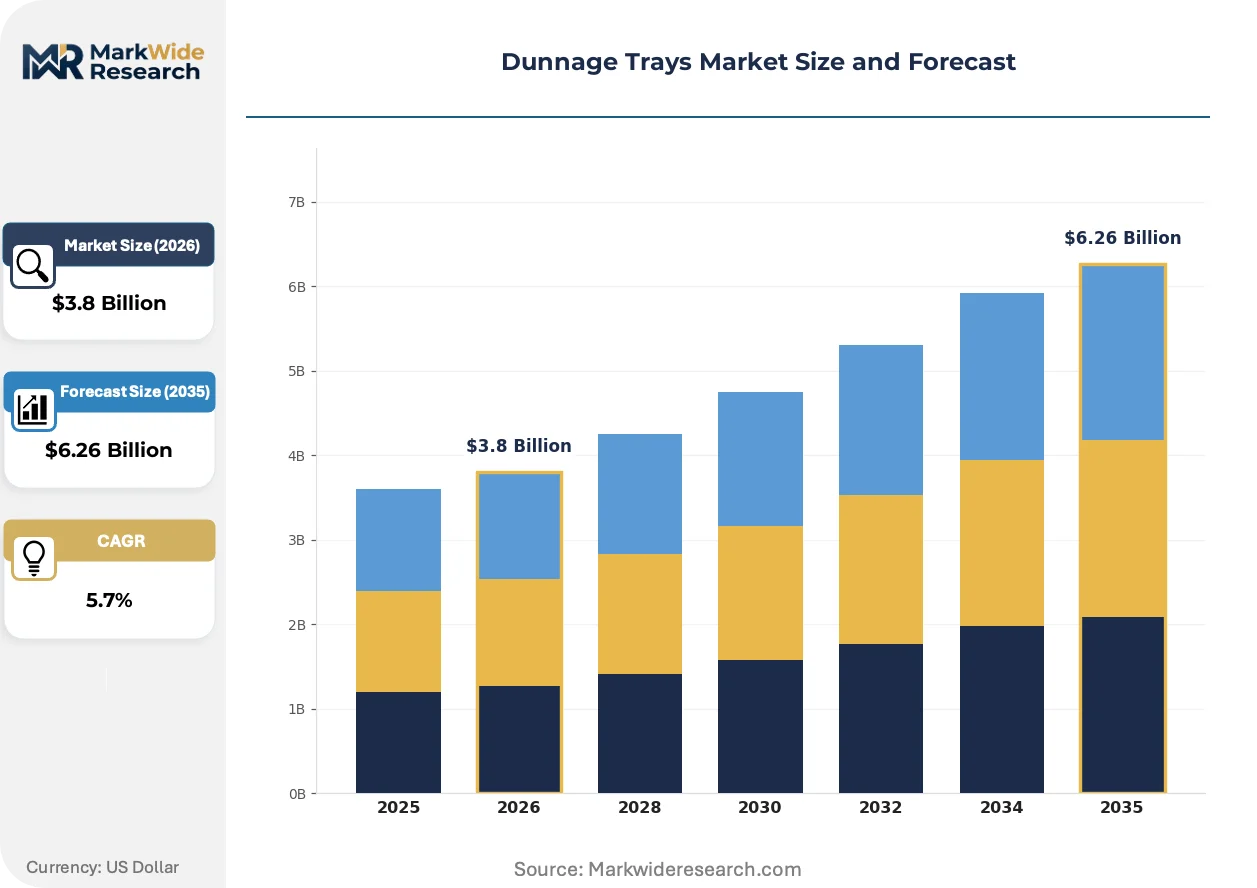
Market Dynamics
Automotive OEM consolidation around returnable packaging systems is compressing supplier margins while elevating performance specifications for vibration damping and surface protection. Tier-one suppliers now mandate multi-cycle durability testing that eliminates commodity-grade tray converters from qualification pools.
Growth Catalysts
- EPA recycled-content mandates:US state-level thresholds under Resource Conservation and Recovery Act frameworks accelerate post-consumer resin adoption across thermoformed tray production.
- Just-in-time automotive corridors:Supplier clustering around Midwest assembly plants generates concentrated demand for modular dunnage systems with rapid turnaround logistics.
- Electrostatic discharge control:Electronics manufacturers specify conductive foam-insert configurations for semiconductor and medical device handling, opening premium specification tiers.
Market Restraints
- Post-consumer resin price volatility:rPET and rPP feedstock costs fluctuate with municipal collection rates and oil-price arbitrage, squeezing converter margins on fixed-price OEM contracts.
- Tooling capex concentration:Custom thermoform mold fabrication requires six-figure capital commitments that lock smaller fabricators out of automotive qualification programs.
- Closed-loop logistics complexity:Returnable system implementation demands reverse-logistics infrastructure that many tier-two suppliers lack capital to deploy.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-validated dunnage with phase-change material integration addresses biologics distribution gaps in emerging markets.
- EU Packaging and Packaging Waste Directive:Extended producer responsibility schemes create first-mover advantage for suppliers with established take-back networks and mechanical recycling partnerships.
- Lightweighting convergence:Combination of structural foam engineering with fiber-reinforced thermoplastics enables payload optimization for electric vehicle battery component shipping.
Industry Challenges
- ISO 9001 and IATF 16949 certification timelines:Automotive quality system audits consume 12-18 months, delaying market entry for new entrants regardless of technical capability.
- CAD-to-tooling translation errors:Component cavity mismatches between digital designs and physical molds generate scrap rates that erode project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dunnage Trays Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood, Metal, Foam Size: Small, Medium, Large, Custom Application: Automotive, Electronics, Food & Beverage, Pharmaceutical Distribution Channel: Online, Retail, Direct Sales, Others |
| Companies Covered | BMG, Waveform Plastics, Sonoco Products Company, Dordan Manufacturing Company, Menasha Corporation, DS Smith, Great River Plastics, Bardes Plastics, Dunnage Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dunnage Trays Market Emerging Trajectories
Material science advances and regulatory pressure on circularity are reconfiguring competitive advantage around durability certification and end-of-life recovery infrastructure rather than unit cost alone.
Structural foam dunnage is bifurcating the protective packaging landscape as automotive and aerospace OEMs specify load-bearing trays that eliminate secondary bracing. Tier-one suppliers in Germany and Japan are adopting these configurations for powertrain component shipping. The technology is bifurcating market tiers between premium engineered-foam systems and commodity thermoformed alternatives that fail vibration-resistance protocols.
REACH substance restrictions and EU Green Deal packaging targets are eliminating certain flame-retardant additives from expanded polystyrene formulations. Converters serving European electronics manufacturers are reformulating with mineral-based alternatives that maintain UL 94 ratings. Medical device exporters to the EU face accelerated compliance deadlines that favor suppliers with pre-certified material libraries.
Automotive procurement teams now bundle dunnage supply with closed-loop logistics management, displacing spot-market tray purchases. Tier-one suppliers in the US Midwest are consolidating vendor bases to single-source providers with captive washing and inspection facilities. This consolidation concentrates contract value among integrated design-to-delivery operators while marginalizing standalone thermoformers.
Dunnage Trays Market Segmentation
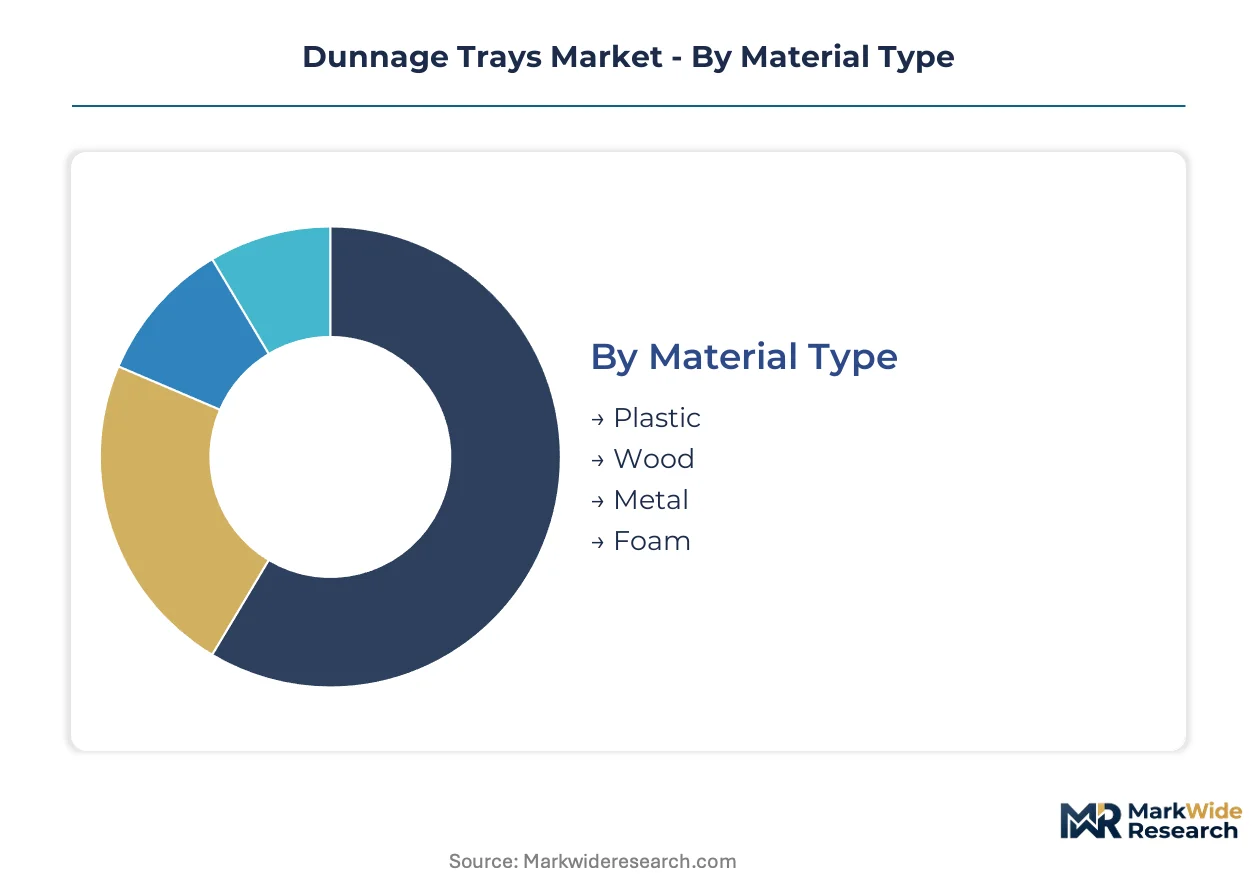
Material selection and size configuration determine cost structure and cycle life for dunnage tray deployments across automotive and electronics supply chains. Application-specific requirements around vibration resistance, electrostatic discharge, and temperature validation create divergent specification tiers that reshape supplier qualification pathways.
Material Type:
Margin pools concentrate in engineered plastic formulations where post-consumer resin premiums and multi-cycle durability certifications command price separation from commodity alternatives.
- Plastic:Thermoformed polyethylene and polypropylene formulations dominate automotive returnable packaging programs through structural rigidity across 500+ use cycles. US EPA recycled-content mandates under Resource Conservation and Recovery Act frameworks are accelerating rPET and rPP adoption among Midwest automotive suppliers seeking OEM qualification.
- Foam:Expanded polyethylene and cross-linked polyethylene configurations serve precision electronics and pharmaceutical applications requiring electrostatic discharge control and shock absorption below 50G impact thresholds. Demand clusters around semiconductor fabrication corridors in Germany, Japan, and South Korea where conductive foam specifications are mandatory for wafer transport.
- Wood:Plywood and oriented strand board dunnage persists in heavy machinery and agricultural equipment shipping where single-trip economics outweigh returnable system investments. European pallet pool operators are phasing out untreated wood due to ISPM 15 phytosanitary regulations.
- Metal:Steel and aluminum tray systems occupy aerospace and defense applications where load-bearing capacity exceeds 500kg and fire-resistance ratings are specified. Fabricators serving Boeing and Airbus tier networks maintain captive welding and powder-coating capacity.
Plastic holds installed capacity across automotive qualification pools. Foam is rotating up the share rankings in electronics and medical device handling specifications.
Size:
Volume concentration follows automotive OEM standardization programs that limit SKU proliferation through modular dimension families.
- Custom:Cavity-matched fabrication for unique component geometries commands premium positioning through design-to-production lead time compression. Automotive battery pack manufacturers specify custom cell dividers for lithium-ion module shipping as electric vehicle production scales.
- Large:Pallet-scale dunnage systems accommodate powertrain and HVAC module transport between tier-one suppliers and final assembly plants. Just-in-time corridors in Michigan, Ohio, and Ontario generate concentrated demand for 48x40 inch footprint configurations.
- Medium:Tote-compatible dimensions serve sub-assembly and sequenced parts delivery in mixed-model production environments. Japanese automotive transplants in Kentucky and Tennessee specify medium trays for door panel and interior trim sequencing.
- Small:Hand-tote formats support line-side presentation of fasteners, clips, and electronic control modules. Electronics contract manufacturers in Shenzhen and Penang utilize small dunnage for semiconductor component kitting.
Custom configurations capture expanding specification share. Large-format systems anchor contract value in automotive closed-loop programs.
Application:
End-use concentration reflects divergent performance certification requirements that filter supplier participation through sector-specific quality systems.
- Automotive:IATF 16949-mandated vibration-resistance testing and surface-finish specifications eliminate commodity converters from tier-one qualification pools. OEM consolidation around returnable packaging systems in Germany, Japan, and the United States concentrates contract value among integrated design-to-delivery operators.
- Electronics:Conductive and static-dissipative foam configurations address semiconductor and medical device handling where particulate control and electrostatic discharge protection are critical. REACH substance restrictions are eliminating legacy flame-retardant additives from expanded polystyrene formulations serving European electronics manufacturers.
- Pharmaceutical:Temperature-validated dunnage with phase-change material integration supports biologics distribution in emerging markets. EU GDP guidelines and US FDA cold-chain validation requirements are elevating specification complexity for tray suppliers.
- Food & Beverage:FDA-compliant polypropylene and polyethylene configurations serve processed food and beverage distribution where wash-down durability and chemical resistance are specified. Pooled pallet operators are expanding reusable tray fleets to displace single-use corrugated alternatives.
Automotive holds installed capacity across returnable packaging infrastructure. Electronics is climbing the fastest as semiconductor capital expenditure drives precision handling demand.
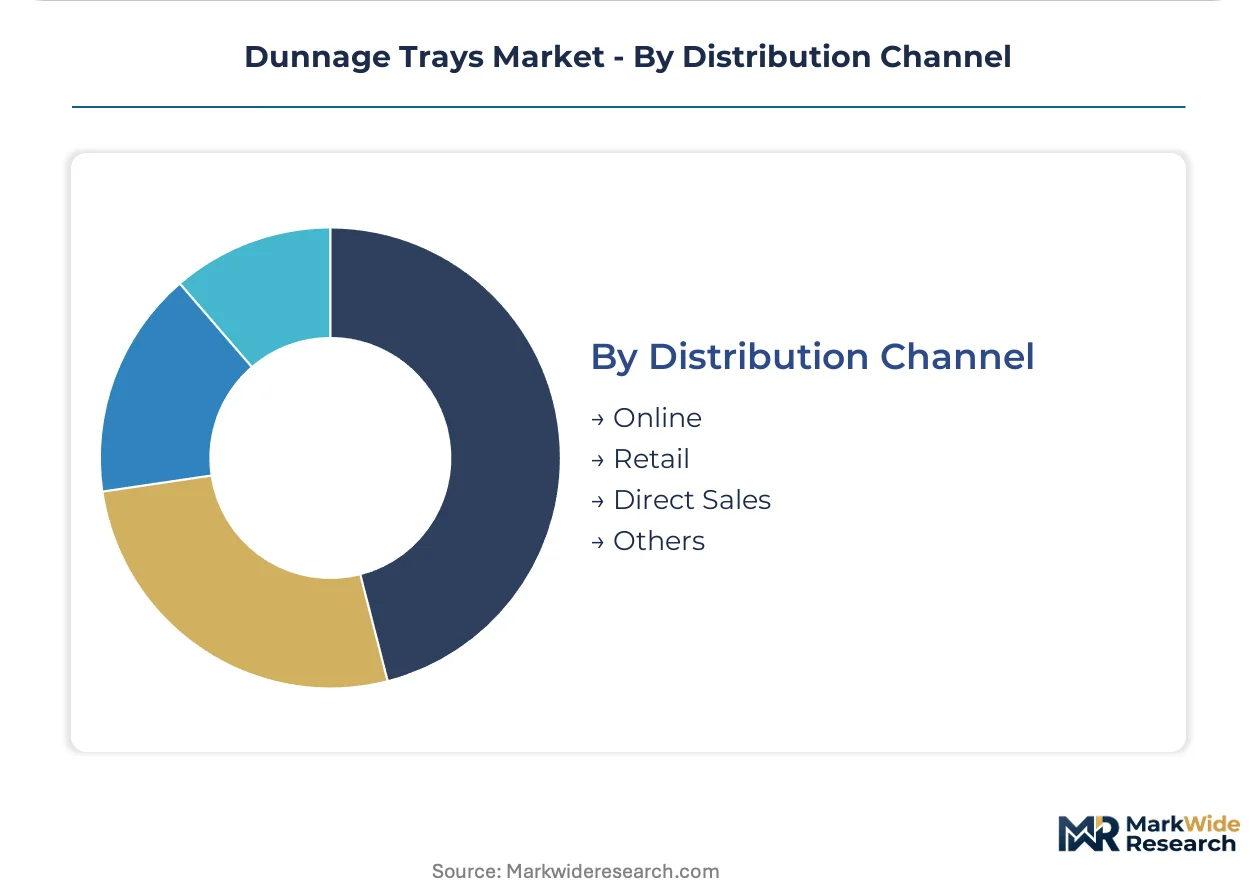
Distribution Channel:
Channel economics reflect procurement consolidation trends that favor direct supplier-OEM relationships over intermediated spot-market transactions.
- Direct Sales:Captive engineering services and closed-loop logistics management bundled with tray supply displace transactional purchasing. Tier-one automotive suppliers in the US Midwest are consolidating vendor bases to single-source providers with integrated washing and inspection facilities.
- Online:E-procurement platforms serve maintenance-repair-operations demand and spot-market replacement orders for standardized tray dimensions. Industrial distributors are expanding digital catalog coverage for small-to-medium enterprise customers.
- Retail:Big-box industrial supply chains stock commodity-grade thermoformed trays for general manufacturing and warehouse applications. Channel margins compress through price transparency and private-label competition.
- Others:Leasing and pooling operators provide tray access without capital ownership for seasonal or project-based demand patterns. Pallet and container pool networks are extending service offerings into dunnage management.
Direct sales holds installed capacity across automotive and pharmaceutical contract structures. Online channels are gaining share fastest in small enterprise and aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in dunnage trays tilt toward net manufacturing output in automotive-intensive economies while import dependency characterizes emerging pharmaceutical hubs lacking thermoforming infrastructure.
United States
Midwest automotive corridors in Michigan, Ohio, and Indiana generate concentrated demand for returnable packaging systems serving just-in-time assembly plants. EPA recycled-content mandates under Resource Conservation and Recovery Act frameworks accelerate post-consumer resin adoption among thermoformers supplying tier-one suppliers. Detroit-Windsor cross-border logistics networks sustain closed-loop dunnage pools for powertrain component circulation.
Germany
Bavarian and Baden-Württemberg automotive clusters specify vibration-resistant structural foam configurations for precision powertrain shipping. REACH substance restrictions eliminate legacy flame-retardant additives from expanded polystyrene formulations serving European electronics manufacturers. Stuttgart-area suppliers reformulate with mineral-based alternatives to maintain UL 94 ratings under accelerated compliance deadlines.
China
Yangtze River Delta electronics contract manufacturers in Shanghai and Suzhou utilize conductive foam-insert dunnage for semiconductor wafer transport. MIIT industrial standards and dual carbon goals pressure converters toward mechanical recycling partnerships and post-consumer resin integration. Shenzhen medical device exporters face EU GDP cold-chain validation requirements that elevate specification complexity for temperature-validated tray suppliers.
Japan
Chubu region automotive transplants around Nagoya specify medium-format dunnage for door panel and interior trim sequencing in mixed-model production environments. METI circular economy roadmaps reshape material selection obligations for tray suppliers serving domestic OEMs. Toyota City supplier networks maintain captive washing and inspection facilities that bundle logistics management with tray supply contracts.
South Korea
Seoul Capital Area semiconductor fabrication corridors mandate electrostatic discharge control specifications for wafer and memory component handling. MFDS pharmaceutical regulations and K-Battery strategic initiatives drive demand for temperature-validated dunnage supporting biologics and electric vehicle battery distribution. Busan-Ulsan port logistics sustain export-oriented returnable packaging pools for automotive tier suppliers.
Dunnage Trays Market Vendor Landscape
Concentration sits with integrated design-to-delivery operators possessing captive thermoforming capacity and closed-loop logistics infrastructure. The supplier base stratifies between multinational packaging conglomerates with automotive qualification pools and regional fabricators serving spot-market replacement demand. Three archetypes dominate: European corrugated plastics specialists, North American integrated packaging operators, and Asian electronics-focused foam converters. Competitive moves center on strategic partnerships for reverse-logistics infrastructure and portfolio diversification into pharmaceutical cold-chain specifications.
Among North American integrated operators, Sonoco Products Company and Menasha Corporation exemplify the design-to-delivery archetype through bundled engineering services and captive logistics management. DS Smith represents the European corrugated plastics specialist segment with modular returnable system expertise. These three anchors occupy positions across distinct geographic and specification tiers without overlapping direct competition in identical qualification pools.
| Leading Market Players |
|---|
| BMG |
| Waveform Plastics |
| Sonoco Products Company |
| Dordan Manufacturing Company |
| Menasha Corporation |
| DS Smith |
| Great River Plastics |
| Bardes Plastics |
| Dunnage Engineering |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between tier-one automotive suppliers and dunnage tray converters lock in resin supply allocations and stabilize unit pricing across multi-year OEM qualification cycles. These agreements bundle tooling amortization with per-cycle usage fees, compressing margin volatility for converters serving Michigan and Ohio assembly corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures that stratify across premium, standard, and economy tiers based on IATF 16949 certification status and closed-loop logistics bundling. Price differentiation separates ISO 9001-qualified structural foam configurations from commodity thermoformed alternatives lacking vibration-resistance validation. Cost compression in standard-grade plastic trays is intensifying because post-consumer resin premiums fluctuate with municipal collection rates and oil-price arbitrage. Tier-two suppliers exhibit highest price sensitivity, while pharmaceutical cold-chain buyers accept premium positioning for temperature-validated phase-change material integration.
Supply Chain Analysis
Tooling lead times stretching six months for custom thermoform molds create inventory buffers that strain working capital across Midwest automotive supplier networks. Manufacturing concentrates in the United States, Germany, and China where captive thermoforming capacity serves regional OEM qualification pools. Feedstock supply draws from rPET and rPP streams tethered to municipal recycling infrastructure and virgin resin arbitrage. Single-source vulnerability persists in specialized conductive foam formulations serving semiconductor fabrication corridors. Distribution runs through direct supplier-OEM relationships that displace spot-market transactions in automotive and pharmaceutical contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dunnage Trays Market sits in early-cycle expansion as electric vehicle battery component shipping drives custom cavity specification demand from lithium-ion module manufacturers.
For Market Incumbents: Compound design-to-delivery capabilities by integrating captive washing and inspection facilities that bundle logistics management with tray supply contracts. Threats from standalone thermoformers with lower overhead structures are eroding spot-market pricing; defensive consolidation of tier-two fabricators in the US Midwest secures regional capacity control. Certification investment in IATF 16949 and ISO 13485 medical device quality systems creates switching costs that protect automotive and pharmaceutical contract positions. For New Entrants and Emerging Players: IATF 16949 fast-track certification programs open qualification pathways for precision electronics and medical device handling specifications where incumbent concentration remains lower. White-space targets include temperature-validated dunnage for biologics distribution in emerging markets and conductive foam configurations for semiconductor wafer transport. The most penetrable segment is pharmaceutical cold-chain specifications where EU GDP guidelines elevate barrier-to-entry for legacy converters lacking phase-change material integration expertise. Go-to-market positioning should emphasize mechanical recycling partnerships that satisfy EU Packaging and Packaging Waste Directive extended producer responsibility schemes. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated design-to-delivery operators with captive closed-loop logistics infrastructure and multi-year OEM offtake contracts. Long-term viability across the analysis window favors suppliers with established take-back networks and post-consumer resin formulation capabilities rather than commodity-grade thermoformers dependent on spot resin purchasing. Acquisition target archetypes include regional foam converters serving semiconductor corridors with conductive specifications and untapped pharmaceutical cold-chain certifications. Signal to watch is OEM packaging-waste reduction target acceleration that forces supplier consolidation toward integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Integration | EPA recycled-content mandates under Resource Conservation and Recovery Act frameworks accelerate rPET and rPP adoption. |
| Closed-Loop Logistics Infrastructure | Captive washing and inspection facilities bundle reverse-logistics management with tray supply contracts. |
| Pharmaceutical Cold-Chain Certification | EU GDP guidelines and FDA validation requirements elevate specification complexity for temperature-validated dunnage. |
| Structural Foam Engineering | Automotive OEMs specify load-bearing configurations that eliminate secondary bracing for powertrain component shipping. |
| Mechanical Recycling Partnerships | Extended producer responsibility schemes create first-mover advantage for suppliers with established take-back networks. |
Methodological Framework
Cross-validation between primary interviews with tier-one automotive procurement managers, thermoforming plant engineers, and pharmaceutical supply chain directors and secondary validation through SEC 10-K filings, customs trade data, and EPA regulatory documentation anchors the qualitative findings. Bottom-up triangulation of converter capacity utilization rates with top-down OEM packaging spend estimates produces volume and value outputs. Stakeholder roles engaged include OEM platform engineers, tier-one supplier procurement leads, foam compound technical directors, and reverse-logistics operators.
Sensitivity analysis across material cost scenarios and OEM production volume assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled span material type, size configuration, application sector, and distribution channel structure. CAGRs derive from regression analysis of historical shipment data against automotive production indices and semiconductor capital expenditure cycles. Industry-specific forecast inputs include electric vehicle battery pack production schedules and biologics distribution infrastructure buildout rates.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive returnable packaging adoption and stable resin recycling infrastructure development; material deviation in OEM consolidation patterns or post-consumer resin availability would warrant model refresh. Specific risk factors include REACH substance restriction expansion eliminating legacy flame-retardant additives and state-level recycled-plastic mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Overpack Drum Market