
 Industrial Chemical Packaging Market | 2026-2036
Industrial Chemical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Chemical Packaging Market Foresight
Buyer concentration in the paints and coatings sector is consolidating around multinational formulators with centralized procurement functions. Greif leverages its steel drum manufacturing scale to serve bulk chemical distributors across North American industrial corridors. Amcor competes through plastic container specialization for agrochemical and specialty solvent applications. Sonoco Products Company anchors its position via fiber-based packaging for dry chemical and powder formulations where moisture barrier properties differentiate performance.
Industrial chemical packaging encompasses engineered containment systems designed to store, transport, and dispense hazardous and non-hazardous chemicals, with specifications typically ranging from five-liter pails to thousand-liter intermediate bulk containers constructed from high-density polyethylene, cold-rolled steel, or multi-layer laminated films. These systems must achieve UN-certified performance standards for dangerous goods transit while preventing permeation, leaching, and environmental contamination across multimodal supply chains. Drums and rigid containers dominate volume throughput in established chemical manufacturing regions, though flexible packaging formats are gaining share in adhesive and sealant applications where reduced tare weight cuts freight costs. Plastic material platforms lead growth in corrosive chemical segments due to enhanced acid resistance and lower lifecycle costs compared to coated metal alternatives.
EPA hazardous waste container regulations and OSHA workplace chemical handling standards shape product design mandates in the United States, while the EU CLP regulation and REACH compliance frameworks govern material composition and labeling requirements across European chemical supply chains. The EU F-Gas Regulation and evolving state-level extended producer responsibility laws in California and New York are forcing reformulation of barrier coatings and recycling infrastructure investments. Stakeholders must monitor how per- and polyfluoroalkyl substance restrictions in food-contact and industrial packaging migrate into chemical containment standards, as this regulatory boundary shift could disqualify incumbent fluoropolymer liner technologies without warning.
Market Dynamics
Corrosion-resistant bulk container procurement by specialty coatings manufacturers is reshaping supplier relationships, as integrated chemical producers in Germany's Rhine-Ruhr cluster seek standardized intermediate bulk container fleets to reduce handling complexity across multimodal supply chains.
Growth Catalysts
- EU REACH compliance mandates:Tightening material requirements for chemical contact surfaces are forcing incumbent suppliers to upgrade barrier coating formulations, creating replacement demand across existing installed bases.
- Agrochemical sector expansion:Plastic container specialization for crop protection formulations is accelerating as reduced tare weight cuts freight costs in agricultural supply chains spanning Brazil, India, and the United States.
- Rhine-Ruhr chemical cluster concentration:Integrated producers in this German hub are consolidating procurement around standardized IBC fleets, driving volume commitments to packaging vendors with regional manufacturing presence.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings for steel drum manufacturing compress margins for metal packaging specialists serving bulk chemical distributors across North American industrial corridors.
- Fluoropolymer liner dependency:Incumbent barrier technologies face disqualification risk as per- and polyfluoroalkyl substance restrictions migrate from food-contact into industrial chemical containment standards without warning timelines.
- Multi-layer film technical limitations:Flexible packaging formats struggle to achieve UN-certified performance standards for certain hazardous chemical categories, constraining share gains in regulated dangerous goods segments.
Strategic Opportunities
- India agrochemical packaging penetration:Dry chemical and powder formulation demand in this underpenetrated market creates openings for fiber-based moisture barrier solutions where existing infrastructure remains fragmented.
- California extended producer responsibility laws:Recycling infrastructure investment mandates are generating procurement opportunities for packaging vendors with closed-loop material recovery capabilities.
- Smart tracking convergence:Integration of RFID-enabled container monitoring with existing fleet management systems enables outcome-based logistics contracts for chemical distributors seeking real-time inventory visibility.
Industry Challenges
- UN certification timeline compression:Dangerous goods testing protocols for new barrier material combinations extend product development cycles, delaying revenue recognition for innovative container designs.
- Legacy ERP integration friction:Container tracking and returnable fleet management systems require substantial capex to interface with incumbent chemical producer procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Chemical Packaging Market |
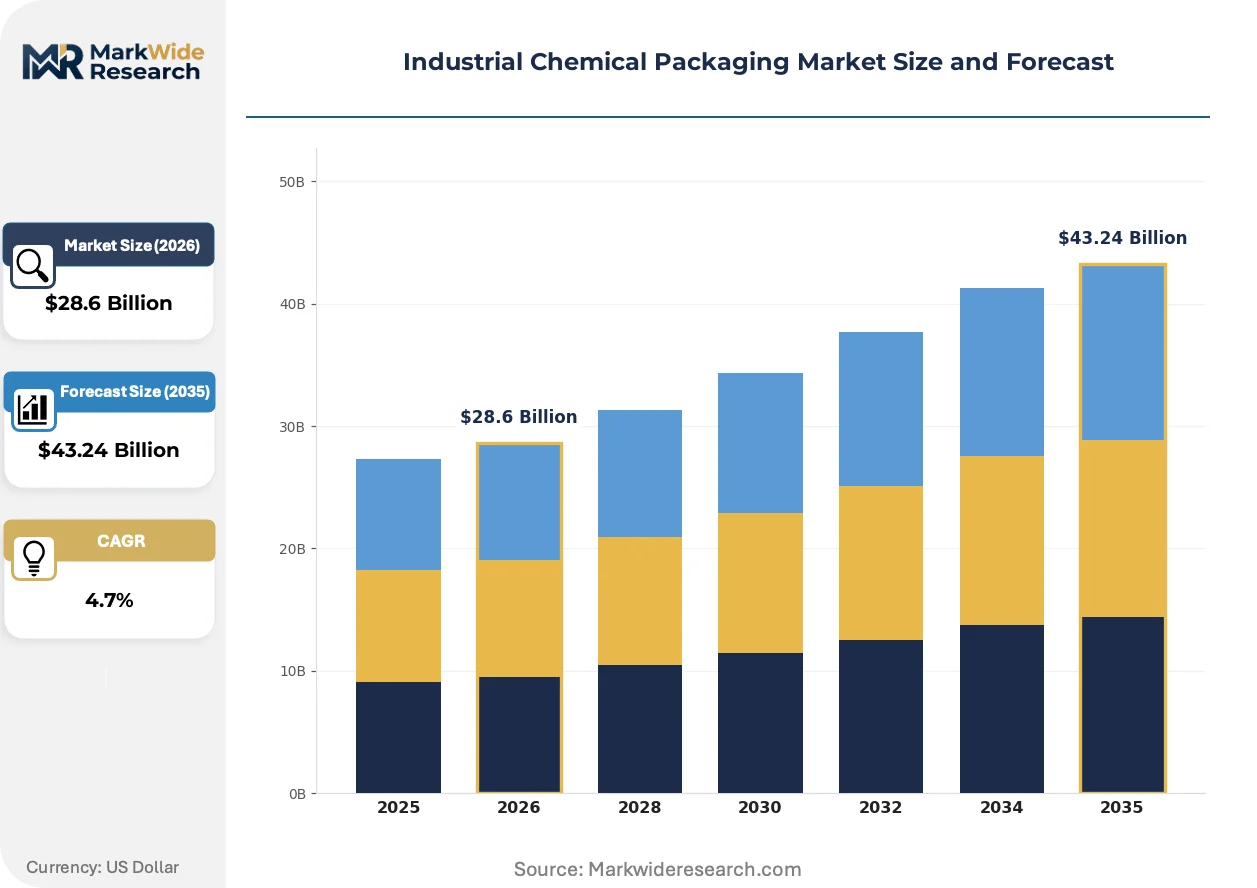
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Bags, Containers, Totes Material: Plastic, Metal, Glass, Paper End User: Paints, Adhesives, Plastics, Coatings Packaging Type: Flexible, Rigid, Bulk, Specialty |
| Companies Covered | Crown Holdings, Sonoco Products Company, WestRock, Sealed Air, Mondi, Plastipak Holdings, Amcor, Greif, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Chemical Packaging Market Shifts & Advancements
Material platform transitions and regulatory boundary shifts are compressing technology adoption cycles, as packaging vendors race to qualify next-generation barrier systems before incumbent chemistries face restriction.
High-density polyethylene formulations with enhanced acid resistance are overtaking coated steel alternatives in corrosive chemical segments. Specialty solvent manufacturers in the United States and Germany are specifying these plastic platforms for new capital projects. The shift is compressing lifecycle cost calculations and disqualifying metal drum vendors without comparable material science capabilities.
REACH material composition requirements are tightening disclosure obligations for chemical contact surfaces across European supply chains. ECHA is expanding substance restriction candidate lists faster than incumbent suppliers can reformulate barrier coatings. German and Dutch chemical distributors are accelerating supplier audits to preempt compliance gaps in their container fleets.
Centralized procurement functions at multinational paint and coatings formulators are consolidating vendor panels and demanding standardized IBC specifications across multiple production sites. Regional packaging distributors with fragmented product ranges are losing shelf position to vendors with integrated steel, plastic, and fiber-based portfolios. This concentration is most visible in North American industrial corridors where bulk chemical distributors serve as intermediaries to dispersed manufacturing locations.
Industrial Chemical Packaging Market Segmentation
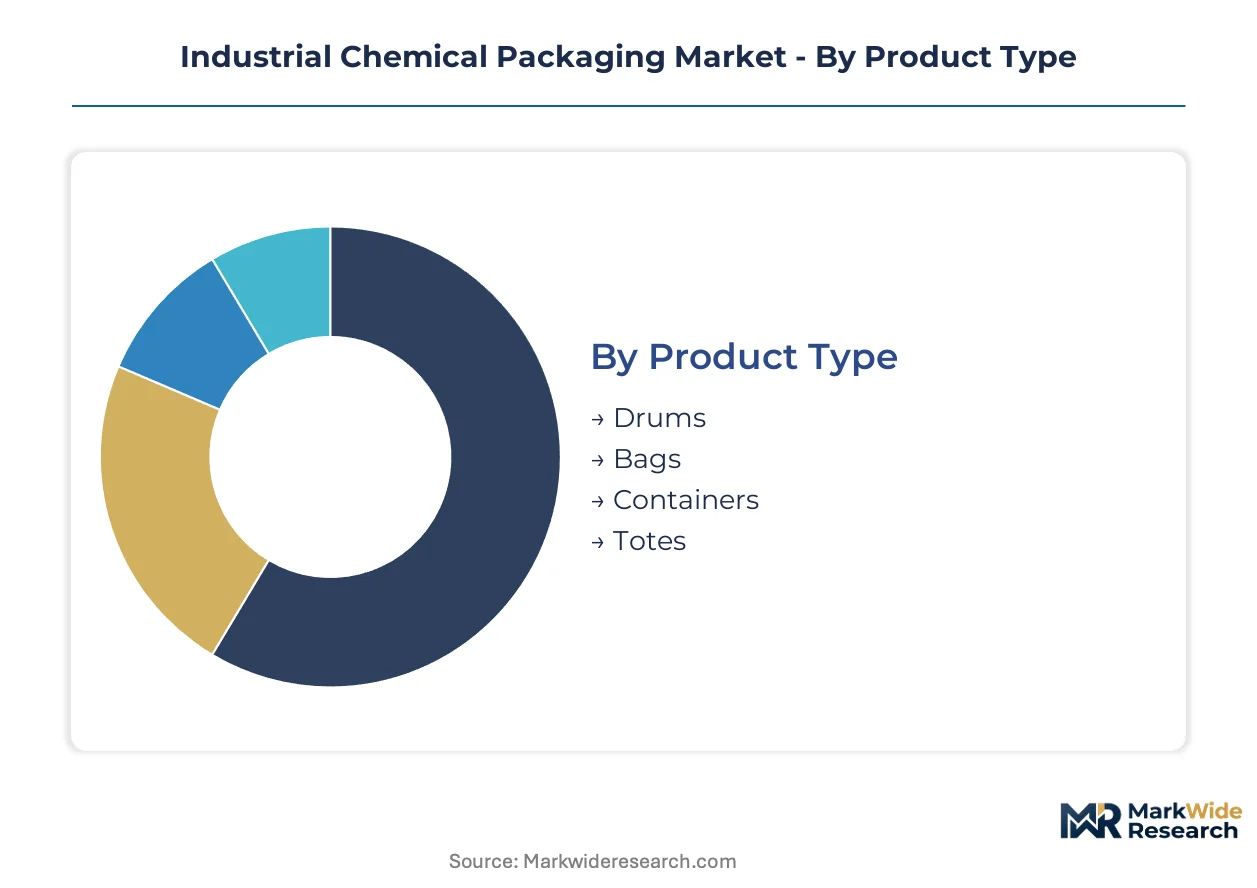
Industrial chemical packaging procurement decisions hinge on hazard classification, multimodal transit requirements, and total cost of ownership across container lifecycles. Segmentation reveals where material science investments and regulatory compliance burdens concentrate competitive advantage.
Product Type:
Buyers prioritize UN certification compatibility and handling efficiency when selecting containment formats for specific chemical hazard classes.
- Drums:Cold-rolled steel and high-density polyethylene constructions dominate bulk chemical distribution across North American industrial corridors. EPA hazardous waste container regulations and OSHA workplace standards mandate specific closure and pressure relief specifications for these standardized vessels.
- Containers:Intermediate bulk containers ranging from 200 to 1000 liters enable standardized fleet management for integrated producers in Germany's Rhine-Ruhr chemical cluster. Corrosion-resistant bulk container procurement by specialty coatings manufacturers is reshaping supplier relationships in this segment.
- Bags:Multi-layer laminated films serve dry chemical and powder formulations where moisture barrier properties differentiate performance in agricultural supply chains.
- Totes:Rectangular intermediate bulk containers optimize warehouse cube utilization and truckload density for adhesive and sealant applications.
Drums lead on scale; containers lead on momentum.
Material:
Total lifecycle cost calculations now favor material platforms with enhanced acid resistance and lower reformulation risk under tightening substance restrictions.
- Plastic:High-density polyethylene formulations with enhanced acid resistance are overtaking coated steel alternatives in corrosive chemical segments. Specialty solvent manufacturers in the United States and Germany specify these platforms for new capital projects.
- Metal:Cold-rolled steel drums face margin compression from input cost volatility while competing against plastic alternatives with superior lifecycle economics.
- Paper:Fiber-based moisture barrier solutions anchor demand for dry chemical formulations where Sonoco Products Company differentiates through barrier engineering.
- Glass:Borosilicate and soda-lime constructions retain niche positions for high-purity reagents and laboratory-scale chemical distribution.
Plastic leads on scale; paper leads on momentum.
End User:
Centralized procurement functions at multinational formulators are consolidating vendor panels and demanding standardized specifications across multiple production sites.
- Paints:Multinational formulators with centralized procurement functions are consolidating supplier relationships around vendors with integrated material portfolios.
- Coatings:Specialty coatings manufacturers are expanding procurement of corrosion-resistant bulk containers as REACH compliance mandates tighten material requirements.
- Adhesives:Reduced tare weight in flexible packaging formats cuts freight costs across dispersed manufacturing locations served by bulk chemical distributors.
- Plastics:Polymer producers require contamination-free containment for resin and additive formulations with strict purity specifications.
Paints lead on scale; coatings lead on momentum.
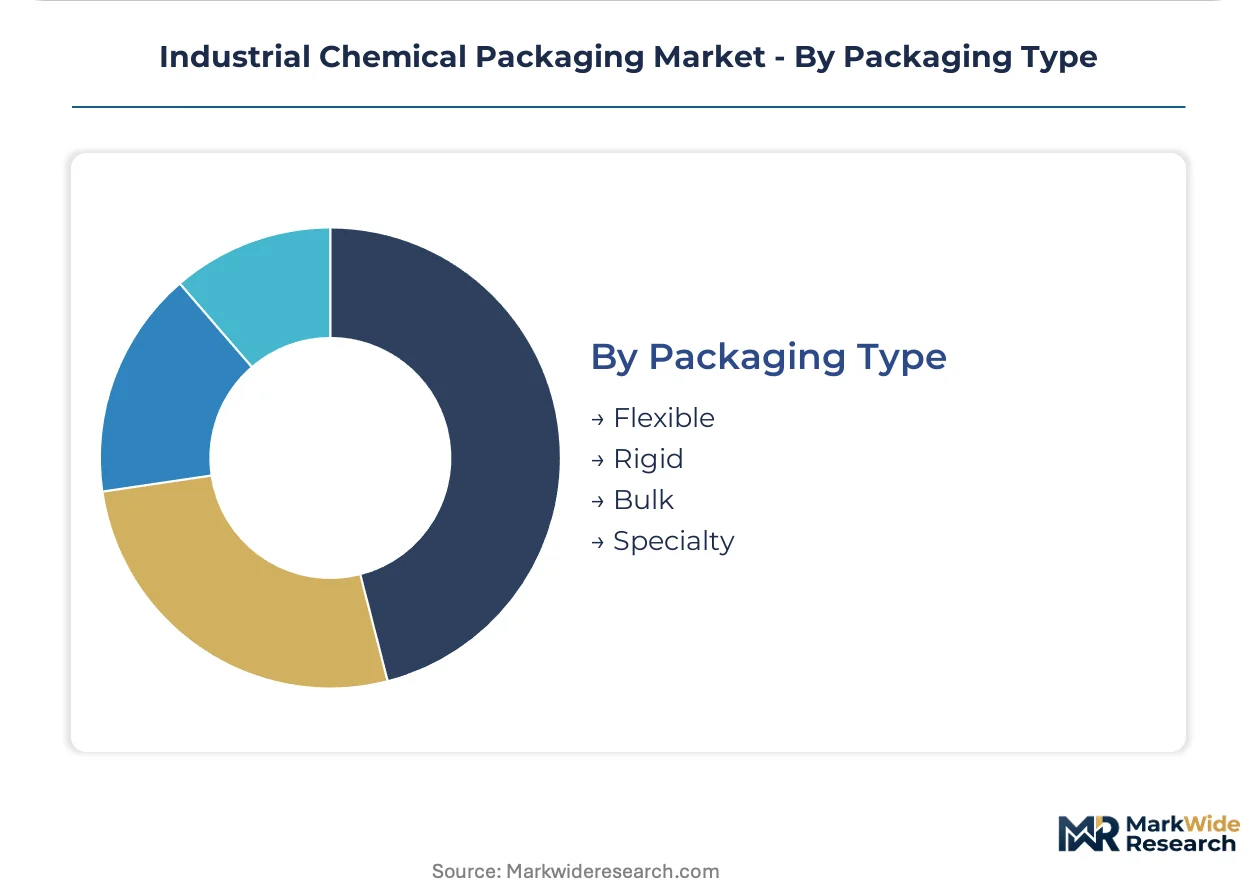
Packaging Type:
Format selection balances freight economics against UN certification performance standards for dangerous goods transit.
- Rigid:Steel and plastic drums dominate volume throughput in established chemical manufacturing regions with proven dangerous goods compliance records.
- Flexible:Multi-layer films gain share in adhesive and sealant applications where reduced tare weight cuts freight costs, though technical limitations constrain penetration in certain hazardous categories.
- Bulk:Intermediate bulk containers enable standardized fleet management for integrated chemical producers seeking handling complexity reduction.
- Specialty:Engineered containment systems address specific hazard classifications with custom barrier coatings and pressure relief configurations.
Rigid leads on scale; flexible leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr chemical cluster demands standardized container fleets, while the United States pursues corrosion-resistant plastic alternatives for specialty solvents. China enforces GB standards compliance for material contact surfaces. India's agrochemical sector drives dry chemical packaging demand. Brazil's crop protection distributors seek freight-efficient formats. Japan maintains stringent purity specifications for high-value chemical containment.
United States
Specialty solvent manufacturers specify high-density polyethylene platforms for new capital projects in Texas and Louisiana. EPA hazardous waste container regulations and OSHA workplace standards mandate specific closure specifications for dangerous goods transit. Gulf Coast petrochemical corridors concentrate procurement decisions among bulk chemical distributors serving dispersed manufacturing locations.
Germany
Integrated producers in the Rhine-Ruhr cluster consolidate procurement around standardized intermediate bulk container fleets. ECHA expands REACH substance restriction candidate lists faster than incumbent suppliers can reformulate barrier coatings. Ludwigshafen and Leverkusen chemical parks drive demand for corrosion-resistant bulk containers with centralized fleet management systems.
China
Domestic agrochemical formulators accelerate plastic container adoption as GB standards tighten material compliance requirements for chemical contact surfaces. The Ministry of Ecology and Environment enforces dual carbon goals that reshape recycling infrastructure investments. Yangtze River Delta chemical parks concentrate procurement among state-owned enterprises with standardized specifications.
India
Dry chemical and powder formulation demand creates openings for fiber-based moisture barrier solutions in Maharashtra and Gujarat. BIS certification requirements for packaging materials interact with DGFT export regulations for crop protection products. Mumbai-Pune industrial corridor distributors seek freight-efficient formats for agricultural supply chains spanning domestic and export markets.
Brazil
Reduced tare weight in flexible packaging formats cuts freight costs for crop protection distributors serving dispersed agricultural regions. ANVISA pharmaceutical packaging standards create spillover effects for industrial chemical containment specifications. São Paulo state chemical distributors consolidate vendor relationships around suppliers with integrated material portfolios.
Industrial Chemical Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material platforms and geographic footprints. The vendor base organizes around three strategic archetypes: integrated steel-plastic-fiber portfolio holders, regional metal packaging specialists with manufacturing scale, and flexible packaging innovators targeting freight cost reduction. Capacity expansion in corrosion-resistant bulk containers and strategic partnerships for closed-loop recycling infrastructure represent dominant competitive moves.
Among North American industrial packaging specialists, Greif exemplifies the steel drum manufacturing archetype with geographic scale across industrial corridors. Sonoco Products Company occupies a position within fiber-based moisture barrier solutions for dry chemical applications. Amcor represents the plastic container specialization vector for corrosive chemical segments.
| Leading Market Players |
|---|
| Crown Holdings |
| Sonoco Products Company |
| WestRock |
| Sealed Air |
| Mondi |
| Plastipak Holdings |
| Amcor |
| Greif |
| DS Smith |
| Others |
Supply & Pricing Matrix
High-density polyethylene formulation advances simultaneously compress production costs and consolidate supplier power among resin-integrated packaging converters. Cold-rolled steel drum manufacturers face margin erosion as plastic platforms capture corrosive chemical specifications, reshaping procurement leverage across North American industrial corridors and Germany's Rhine-Ruhr cluster.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for plastic container platforms serving agrochemical formulators. Contract-based long-term offtake dominates procurement relationships, with price differentiation driven by UN certification grade and volume scale commitments. Cost compression in standard-grade steel drums is intensifying because of cold-rolled steel input volatility. Bulk chemical distributors exhibit highest price sensitivity; specialty coatings manufacturers with centralized procurement functions show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German chemical distributors require multi-supplier qualification for REACH-compliant barrier coatings. Geographic supply concentrates in China, Germany, and the United States for high-density polyethylene resin and cold-rolled steel inputs. Raw material dependencies include petrochemical feedstocks, corrosion-resistant alloy coatings, and multi-layer laminated films. Single-source vulnerability looms for fluoropolymer liner technologies facing substance restriction migration. Distribution runs through bulk chemical distributors serving dispersed manufacturing locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Europe exceed GB standards enforcement costs in China, creating cost-differential opportunities for packaging vendors with dual-qualification capabilities.
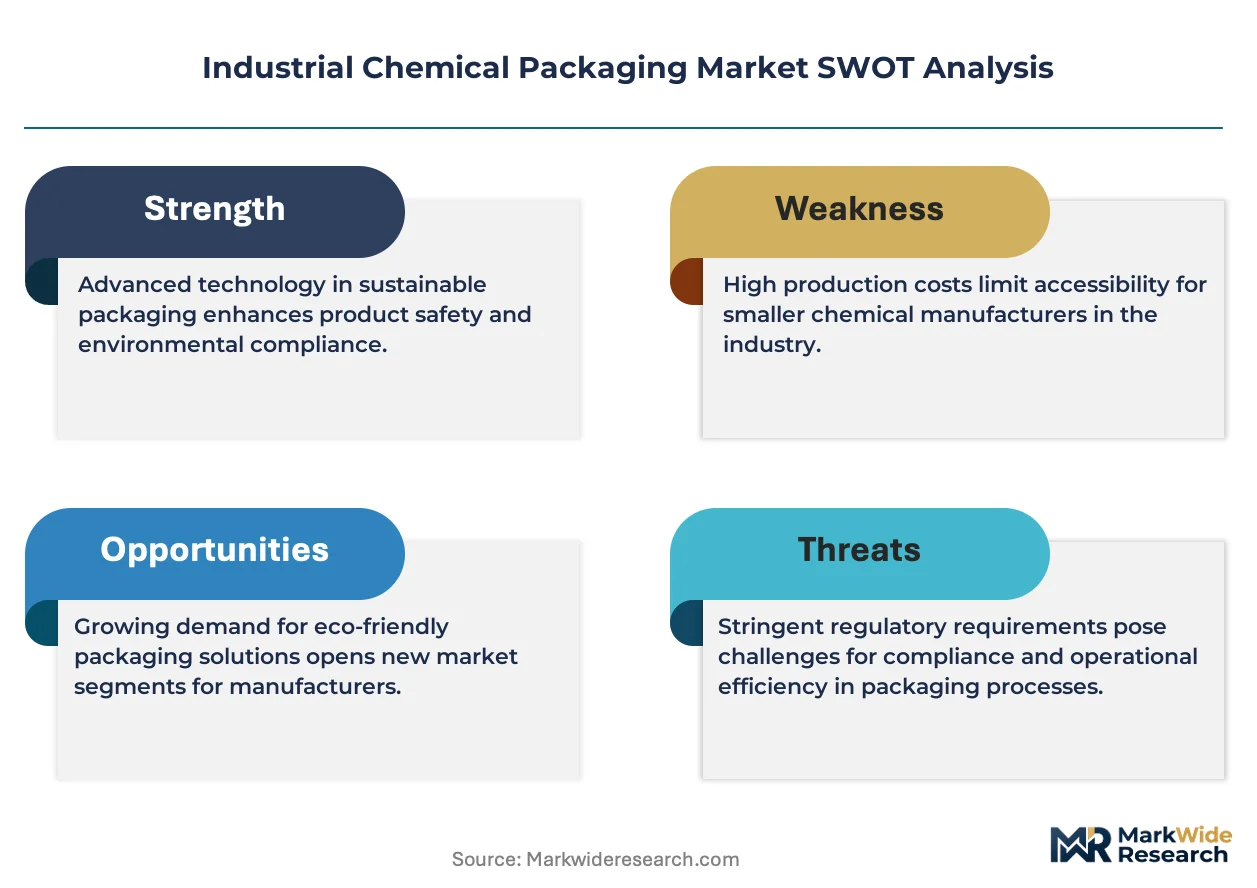
For Market Incumbents: Anticipate disqualification risk for fluoropolymer-dependent product lines as per- and polyfluoroalkyl substance restrictions expand. Defensive consolidation moves include backward integration into high-density polyethylene resin production and certification investment for next-generation barrier coatings. Capacity addition in India's Maharashtra-Gujarat corridor captures agrochemical packaging growth while regional competitors remain fragmented. For New Entrants and Emerging Players: California extended producer responsibility laws open a window for closed-loop recycling infrastructure specialists. White-space targets include fiber-based moisture barrier solutions for India's underpenetrated dry chemical market and RFID-enabled container tracking for chemical distributors seeking real-time fleet visibility. Go-to-market angle: outcome-based logistics contracts tied to inventory visibility guarantees. For Investors and Strategic Acquirers: Valuations sit cheapest among regional metal packaging specialists without plastic platform capabilities. Long-term viability favors vendors with integrated steel-plastic-fiber portfolios and regional manufacturing presence in at least two of Germany, China, and the United States. Acquisition target archetype: corrosion-resistant bulk container specialists with ECHA pre-qualification. Signal to watch: acceleration of supplier audit timelines by German and Dutch chemical distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive high-density polyethylene supply secures margin control against petrochemical volatility. |
| REACH Pre-Qualification Investment | ECHA-compliant barrier coatings preempt disqualification as substance restrictions tighten. |
| Closed-Loop Recycling Infrastructure | California extended producer responsibility laws mandate material recovery capabilities. |
| RFID Fleet Management Integration | Real-time container tracking enables outcome-based contracts with chemical distributors. |
| Regional Manufacturing Expansion | India agrochemical penetration requires local production to serve Maharashtra-Gujarat demand. |
Research Methodology
Direct dialogue with procurement leads at multinational coatings formulators, plant managers at German chemical parks, distribution channel partners in North American industrial corridors, and technical R&D directors at packaging converters grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and UN dangerous goods testing protocols. Bottom-up demand modeling and top-down supply triangulation cross-verified segment-level estimates.
Segmentation outputs across material platform, packaging format, end-use industry, and regional production hub informed the analytical framework throughout the forecast period. CAGRs were derived from installed base replacement cycles, regulatory compliance-driven upgrade timelines, and freight cost elasticity in agricultural supply chains. Industry-specific inputs included REACH substance restriction candidate list expansion rates and agrochemical sector capital expenditure patterns.
Revisions become necessary when per- and polyfluoroalkyl substance restrictions accelerate into industrial chemical containment standards, cold-rolled steel price volatility exceeds historical bands, or UN certification timelines compress beyond product development cycle capacity. Forecasts reflect assumptions about regulatory enforcement consistency and material substitution technical feasibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Insulated Drum Covers Market