
 Pallet Scales Market | 2026-2036
Pallet Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Scales Market Analytics
OEM-direct procurement is tilting toward integrated system providers as end users seek single-source accountability for calibration and connectivity. Mettler-Toledo leverages its global service network to anchor premium contracts with pharmaceutical distributors. Rice Lake Weighing Systems competes aggressively on domestic manufacturing scale and rapid custom-build turnaround for regional food processors.
Pallet scales are industrial weighing instruments designed to measure loads mounted on standard shipping pallets, typically employing load cell technology with capacities from 1,000 kg to 10,000 kg and resolutions certified for commercial trade. These devices serve as critical control points in material handling workflows, capturing weight data for freight billing, inventory management, and regulatory compliance at dock doors and production lines. Static scales retain the largest installed base across manufacturing plants, though dynamic scales are gaining share in high-throughput logistics hubs where conveyor-integrated weighing eliminates manual handling steps. Strain gauge technology dominates current shipments due to proven durability in washdown environments, while capacitive alternatives are penetrating cleanroom applications where electromagnetic interference must be minimized.
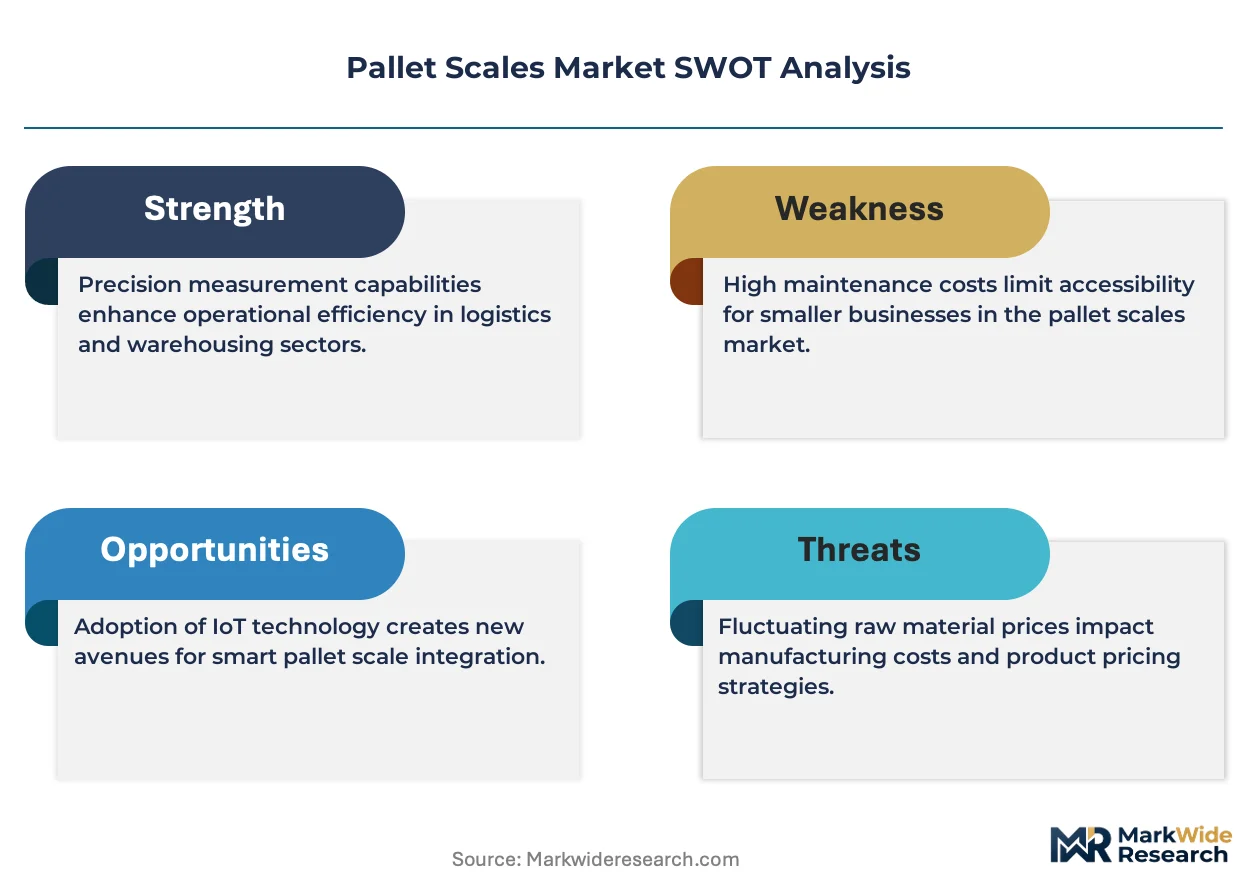
NIST Handbook 44 enforcement by US state weights and measures authorities shapes product design through mandatory traceability protocols for commercial transactions. The EU Measuring Instruments Directive and OIML R76 certification requirements govern market access across European member states, compelling manufacturers to maintain dual approval pathways. ISO 9001 quality management registration has become a baseline procurement filter for tier-one logistics contractors screening vendor pools. Stakeholders must weigh the capital efficiency of portable wireless installations against the data integrity advantages of hardwired integrated systems as facility automation deepens.
Market Dynamics
Wireless load cell integration and NIST Handbook 44 enforcement are compressing equipment replacement cycles while forcing vendors to absorb calibration service costs into hardware contracts.
Growth Catalysts
- Automotive parts distribution:German logistics hubs are retrofitting facilities with integrated pallet scale systems to meet just-in-time inventory mandates from OEM assembly plants.
- OIML R76 certification:European trade-approval standards are accelerating equipment turnover as older analog units lose legal-for-trade status across EU member states.
- Capacitive sensor technology:Cleanroom pharmaceutical operations are adopting electromagnetic-interference-free weighing platforms for active ingredient batch control.
Market Restraints
- Strain gauge supply concentration:Specialty steel alloy production for load cells clusters in East Asian foundries, exposing manufacturers to raw material volatility and extended lead times.
- Calibration infrastructure fragmentation:Third-party metrology service networks remain underdeveloped in Central and Eastern Europe, limiting aftermarket revenue capture for equipment vendors.
- Dynamic scale technical ceiling:Conveyor-integrated weighing systems face accuracy degradation above 2 meters per second belt speed, capping throughput gains in high-velocity sortation hubs.
Strategic Opportunities
- India warehousing expansion:Cold chain logistics operators in Maharashtra and Gujarat are deploying trade-certified pallet scales to comply with FSSAI traceability rules for temperature-sensitive pharmaceuticals.
- CE marking convergence:The EU Measuring Instruments Directive is creating single-approval pathways that reduce certification costs for manufacturers serving multiple European markets.
- Cloud-native platform integration:Edge computing architectures are enabling real-time weight data streaming into warehouse management systems without on-premise server infrastructure.
Industry Challenges
- Field calibration technician scarcity:Certified metrology professionals capable of NIST-traceable adjustments are concentrated in coastal US metropolitan markets, creating service gaps in inland distribution corridors.
- Legacy system protocol incompatibility:Proprietary data formats from 1990s-era scale controllers resist integration with modern IoT gateways, forcing costly middleware development or full equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Scales Market |
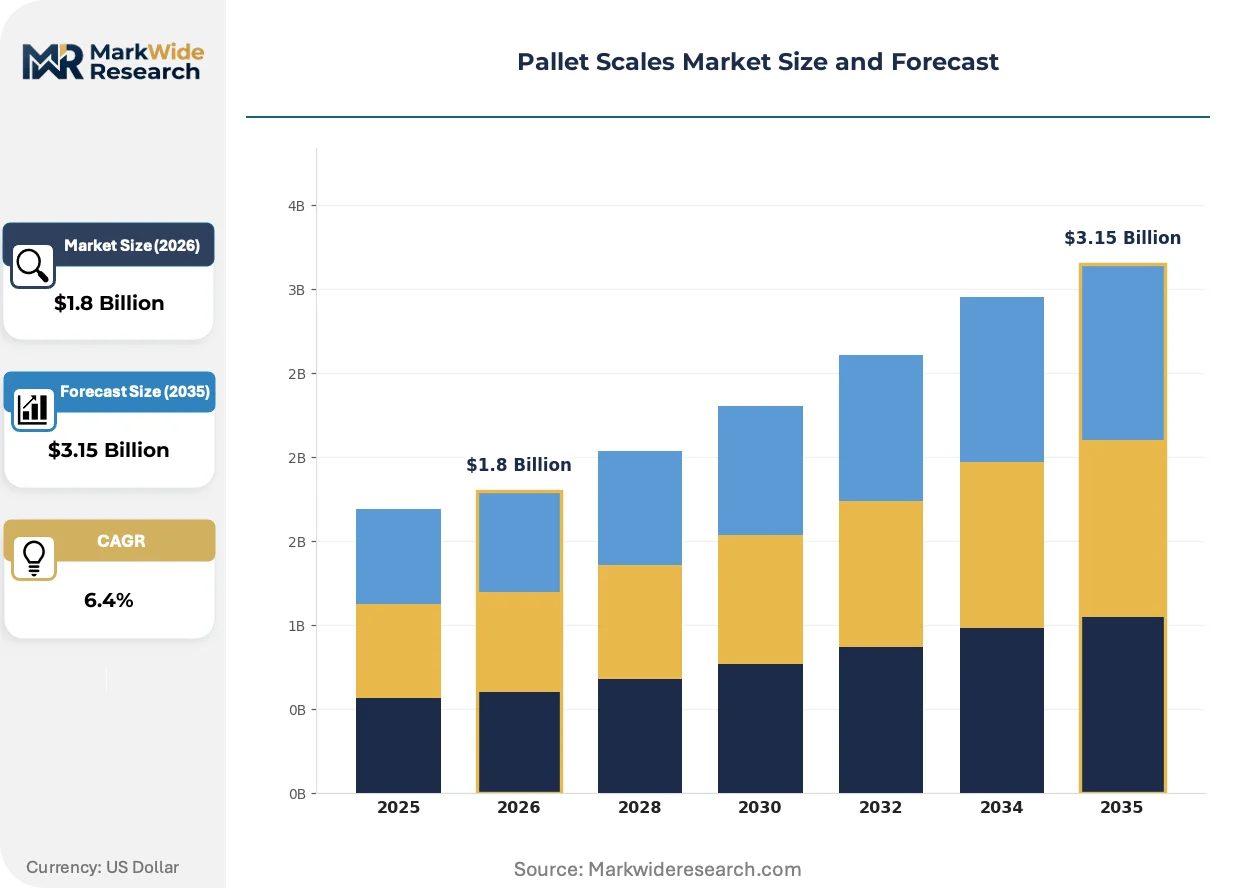
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Scales, Static Scales, Floor Scales, Bench Scales Technology: Load Cell, Strain Gauge, Capacitive, Electromagnetic End User: Logistics, Manufacturing, Retail, Warehousing Installation: Fixed, Portable, Wireless, Integrated Systems |
| Companies Covered | Mettler-Toledo, Avery Weigh-Tronix, Cardinal Scale Manufacturing, Minebea Intec, Rice Lake Weighing Systems, KERN & SOHN GmbH, Flintec Group AB, OHAUS Corporation, Fairbanks Scales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Scales Market Evolving Landscape
Digital connectivity protocols and predictive maintenance algorithms are transforming pallet scales from passive measurement devices into active nodes in automated material handling networks.
MEMS-based force sensors are digitizing weight capture at lower cost points than traditional strain gauge assemblies. Regional food processors with sub-500 kg throughput requirements are adopting these compact units for recipe batching applications. The technology is digitizing quality control workflows by embedding calibration drift detection directly into sensor firmware.
NIST Handbook 44 updates by US state weights and measures authorities are mandating encrypted audit trails for commercial transactions. Pharmaceutical distributors must now maintain tamper-evident weight records spanning seven years. This regulatory compression is forcing equipment vendors to pre-install secure data logging modules as standard rather than optional features.
Buyer consolidation among third-party logistics operators is compressing vendor qualification timelines. Tier-one contractors now demand ISO 9001 registration, on-site spare parts inventory, and sub-24-hour emergency response guarantees as baseline procurement filters. This concentration is visible most acutely in the US Southeast, where Amazon, Walmart, and Target operate competing regional fulfillment networks within overlapping 100-mile radii.
Pallet Scales Market Segmentation
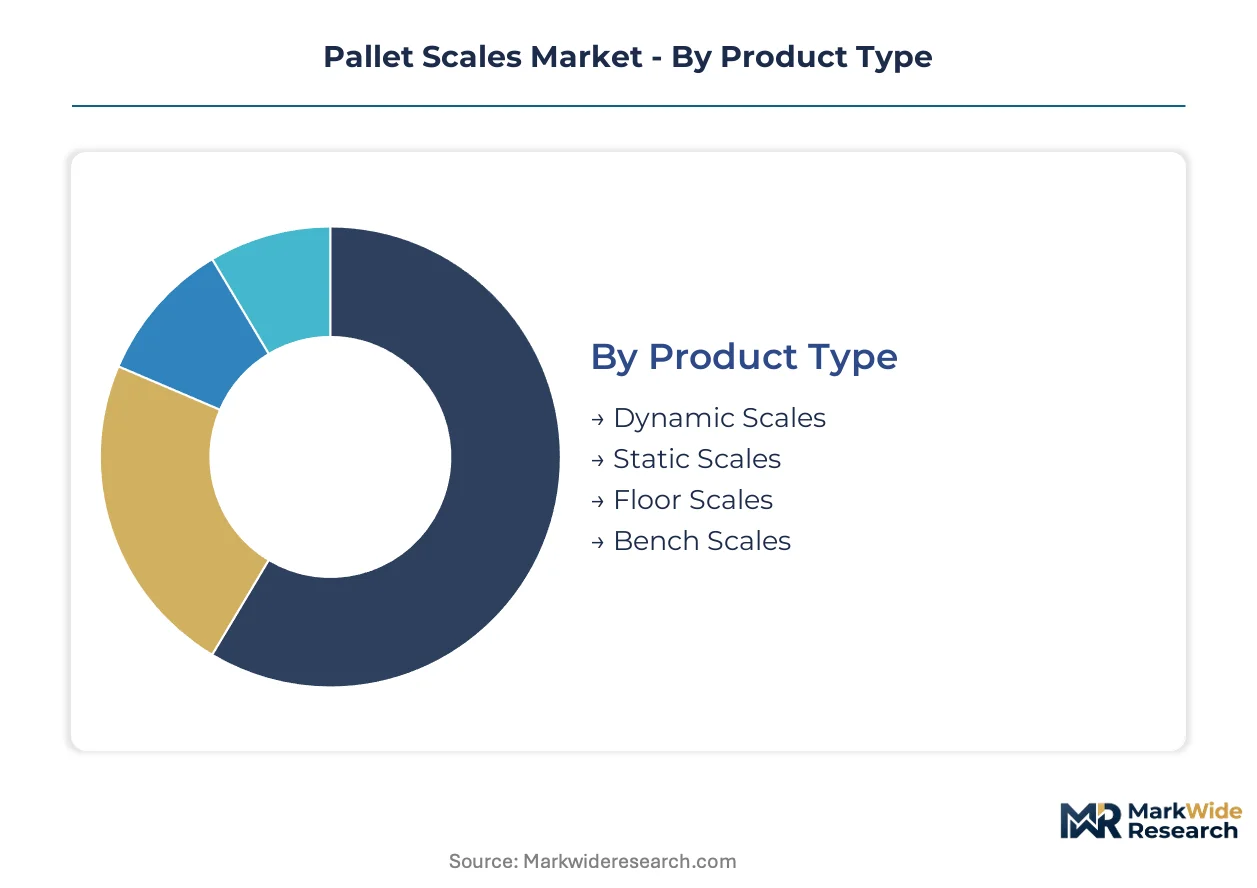
Pallet scale procurement patterns diverge sharply across operational contexts, with regulatory compliance and throughput requirements driving distinct hardware configurations. Understanding these segment boundaries reveals where capital concentrates and which technology trajectories command premium positioning.
Product Type:
Mature equipment categories dominate installed base economics while emerging formats capture expansion investment in high-velocity logistics corridors.
- Dynamic Scales:Conveyor-integrated weighing platforms capture freight data without pallet deceleration, employing load cell arrays mounted beneath roller sections. German automotive parts distributors are retrofitting these systems to meet just-in-time inventory mandates from OEM assembly plants. Accuracy degradation above two meters per second belt speed caps throughput gains in high-velocity sortation hubs.
- Static Scales:Stationary platforms with manual pallet placement retain the largest installed base across manufacturing plants, offering certified accuracy for commercial transactions at lower capital cost. US warehousing operators are expanding fleet purchases of wireless-enabled static units to eliminate cable maintenance.
- Floor Scales:Low-profile pit-mounted designs accommodate forklift traffic in food processing facilities requiring washdown-rated enclosures.
- Bench Scales:Compact tabletop units serve sub-500 kg batching applications in pharmaceutical compounding operations.
Static scales retain volume leadership; dynamic scales hold the steepest expansion curve.
Technology:
Cost tier stratification separates proven industrial workhorses from emerging alternatives targeting specialized electromagnetic environments.
- Strain Gauge:Bonded metal foil sensors measuring electrical resistance change under deformation dominate current shipments due to proven durability in washdown environments. Specialty steel alloy production for these load cells clusters in East Asian foundries, exposing manufacturers to raw material volatility.
- Capacitive:Electromagnetic-interference-free weighing platforms penetrate cleanroom pharmaceutical operations where active ingredient batch control demands signal isolation. MEMS-based force sensors are digitizing weight capture at lower cost points than traditional strain gauge assemblies.
- Load Cell:Compression and tension cell configurations serve as the foundational transduction mechanism across most industrial scale architectures.
- Electromagnetic:Force restoration technology delivers highest precision for metrology-grade applications in calibration laboratories.
Strain gauge technology anchors current revenue; capacitive alternatives are climbing the fastest.
End User:
Customer type concentration determines pricing power, with tier-one logistics contractors extracting service-level guarantees that reshape vendor economics.
- Logistics:Third-party operators demand ISO 9001 registration, on-site spare parts inventory, and sub-24-hour emergency response guarantees as baseline procurement filters. Buyer consolidation among US Southeast fulfillment networks is compressing vendor qualification timelines.
- Warehousing:Cold chain operators in Maharashtra and Gujarat deploy trade-certified equipment to comply with FSSAI traceability rules for temperature-sensitive pharmaceuticals.
- Manufacturing:Production line integration requires hardwired systems with data integrity advantages over portable wireless installations.
- Retail:Distribution centers serving omnichannel fulfillment prioritize rapid custom-build turnaround for seasonal volume spikes.
Logistics commands the largest contract values; warehousing shows the steepest expansion trajectory.
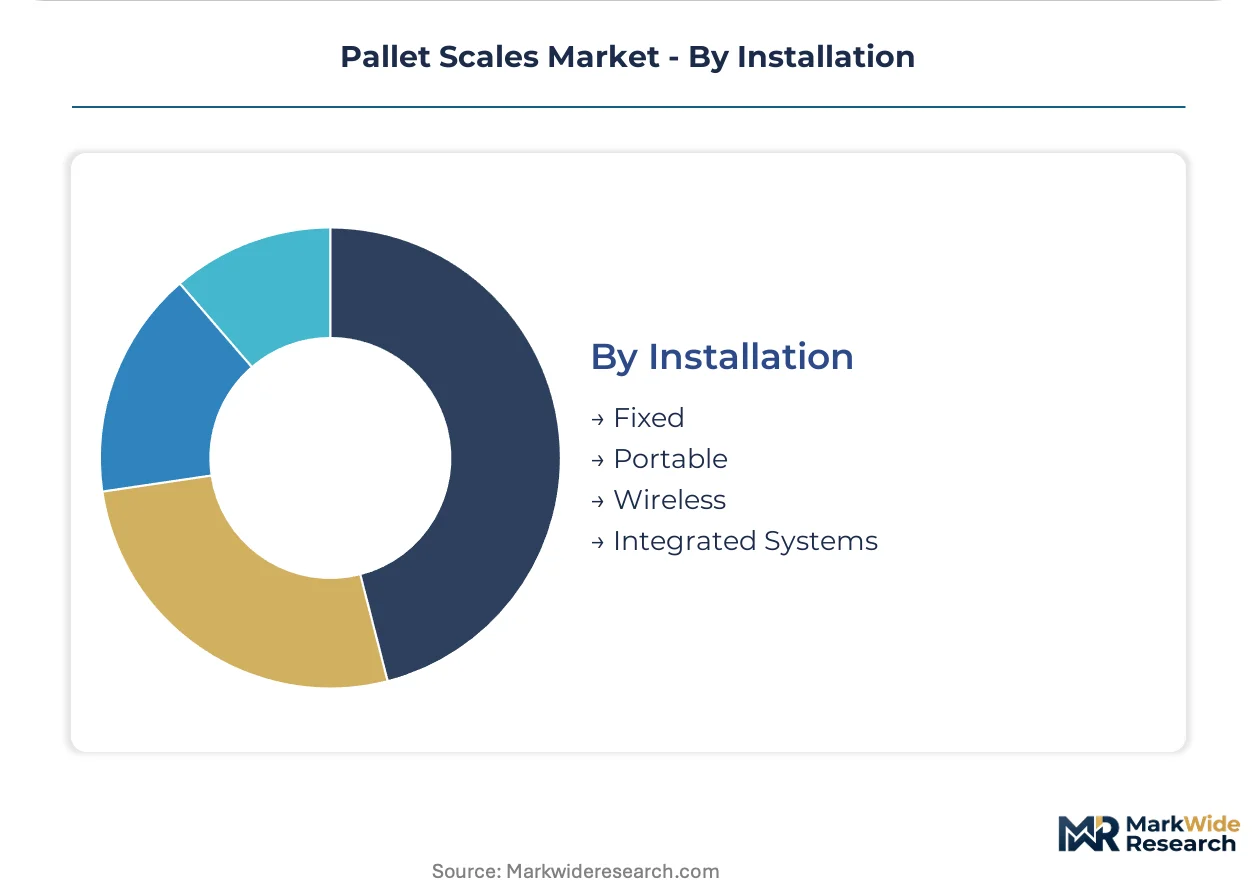
Installation:
Supply concentration in connectivity hardware is forcing equipment vendors to absorb calibration service costs into integrated system contracts.
- Integrated Systems:Hardwired platforms with embedded warehouse management system connectivity offer data integrity advantages as facility automation deepens. Proprietary data formats from 1990s-era scale controllers resist integration with modern IoT gateways.
- Wireless:Battery-powered load cell networks eliminate cable maintenance but require encrypted audit trails mandated by NIST Handbook 44 updates. US state weights and measures authorities now require tamper-evident weight records spanning seven years.
- Fixed:Permanent concrete-mounted installations serve high-throughput manufacturing lines with minimal reconfiguration needs.
- Portable:Mobile units with rechargeable power systems enable flexible deployment across seasonal demand fluctuations.
Integrated systems capture premium contract values; wireless configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST Handbook 44 enforcement by US state weights and measures authorities anchors the regulatory framework shaping equipment specifications across major demand centers. Trade-approval mandates in Germany and OIML R76 certification requirements in Europe compress replacement cycles while India's FSSAI traceability rules drive cold chain investments.
United States
Warehousing operators across Georgia and Tennessee are expanding fleet purchases of wireless-enabled static units to eliminate cable maintenance in high-velocity fulfillment corridors. State weights and measures authorities in California and Texas enforce NIST Handbook 44 traceability protocols for commercial transactions. The Southeast logistics cluster, where Amazon, Walmart, and Target operate competing regional networks within overlapping radii, compresses vendor qualification timelines.
Germany
Automotive parts distribution centers in Baden-Württemberg and Bavaria are retrofitting facilities with integrated pallet scale systems to meet just-in-time inventory mandates from OEM assembly plants. OIML R76 certification requirements accelerate equipment turnover as older analog units lose legal-for-trade status across EU member states. The Stuttgart logistics corridor anchors demand for conveyor-integrated dynamic scales in high-throughput sortation hubs.
India
Cold chain logistics operators in Maharashtra and Gujarat deploy trade-certified pallet scales to comply with FSSAI traceability rules for temperature-sensitive pharmaceuticals. BIS standards govern equipment approval pathways for commercial weighing devices in domestic trade. The Mumbai-Pune pharmaceutical belt concentrates retrofit investments as batch control requirements tighten for active ingredient handling.
China
Specialty steel alloy production for strain gauge load cells clusters in East Asian foundries, exposing manufacturers to raw material volatility and extended lead times. GB standards and SAMR oversight shape metrology equipment certification for domestic commerce. The Yangtze River Delta manufacturing belt sustains demand for washdown-rated floor scales in food processing facilities.
United Kingdom
Third-party logistics contractors in the Midlands and Southeast demand ISO 9001 registration and sub-24-hour emergency response guarantees as baseline procurement filters. CE marking convergence under the EU Measuring Instruments Directive reduces certification costs for manufacturers serving European markets. The London distribution corridor prioritizes cloud-native platform integration for real-time weight data streaming into warehouse management systems.
Pallet Scales Market Competitive Landscape
Integrated system providers and component-specialist fabricators split the market along the calibration-service boundary. Consolidation pressures concentrate contract values among tier-one logistics contractors extracting single-source accountability guarantees. Three archetypes dominate: global metrology houses with anchored service networks, regional custom-build specialists, and sensor-technology component suppliers. Competitive moves center on absorbing calibration infrastructure costs into hardware contracts and compressing custom-build turnaround timelines for seasonal volume spikes.
Among precision-instrument specialists, Mettler-Toledo and Rice Lake Weighing Systems occupy positions reflecting divergent scale strategies. Mettler-Toledo exemplifies the global service-network archetype, leveraging international coverage to anchor premium contracts. Rice Lake Weighing Systems represents domestic manufacturing-scale competitiveness. KERN & SOHN GmbH sits within the European precision-instrument tier, its German corporate structure signaling engineering-intensive positioning. Flintec Group AB anchors the Nordic sensor-technology vector.
| Leading Market Players |
|---|
| Mettler-Toledo |
| Avery Weigh-Tronix |
| Cardinal Scale Manufacturing |
| Minebea Intec |
| Rice Lake Weighing Systems |
| KERN & SOHN GmbH |
| Flintec Group AB |
| OHAUS Corporation |
| Fairbanks Scales |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor compresses logistics costs for German automotive parts distributors while simultaneously amplifying price differentiation between NIST-traceable premium units and standard commercial-grade equipment. Specialty steel alloy sourcing from East Asian foundries concentrates upstream leverage, forcing equipment vendors to absorb calibration service costs into hardware contracts while tiering offerings by certification grade and wireless connectivity.
Pricing Analysis
The customization-premium spread separates configured-to-order integrated systems from standard static platforms by roughly the cost of embedded wireless modules and seven-year encrypted audit trail compliance. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: NIST Handbook 44 and OIML R76 trade-approval tiers command substantial premiums over non-certified commercial units. Cost compression in the standard tier intensifies as regional food processors consolidate procurement volumes and extract rapid custom-build guarantees. Logistics contractors in the US Southeast demonstrate lowest price sensitivity due to single-source accountability requirements, while independent warehousing operators in Central Europe remain most responsive to unit economics.
Supply Chain Analysis
Specialty steel alloy feedstock for strain gauge load cells draws from concentrated foundry capacity in China, Japan, and South Korea, creating single-source vulnerability for manufacturers dependent on specific metallurgical specifications. Aluminum enclosure fabrication and load cell assembly hinge on precision machining clusters in Germany and the United States. Tariff exposure on Chinese steel inputs threatens margin stability for mid-tier equipment fabricators. Distribution runs through OEM-direct channels for integrated system contracts and regional distributor networks for replacement static scales, with spare parts inventory positioning becoming a competitive differentiator in vendor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet scales are transitioning from standalone measurement devices to edge-computing nodes in warehouse management system architectures, creating platform-economics value capture for vendors mastering cloud-native integration protocols and predictive maintenance algorithms.
For Market Incumbents: Harden service network density in inland US distribution corridors where certified metrology technician scarcity creates vulnerability to aftermarket disruption. Anchor premium positioning by embedding calibration drift detection directly into sensor firmware, displacing third-party metrology relationships. Defensive consolidation of wireless load cell module suppliers will secure connectivity hardware access against procurement bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in India's cold chain logistics expansion, where FSSAI traceability mandates create first-mover advantage for trade-certified equipment providers with local calibration partnerships. Target pharmaceutical compounding operations in Maharashtra and Gujarat with capacitive sensor platforms free from electromagnetic interference. A direct-to-warehouse sales model bypassing traditional distributor markups will compress vendor qualification timelines for mid-tier operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial instrumentation parents where pallet scale divisions lack standalone platform investment and cloud connectivity development. Long-term viability over the projection horizon rests on software-defined service revenue streams displacing transactional hardware margins. The signal to watch is consolidation velocity among third-party logistics operators, as buyer concentration above threshold levels will force vendor exits and create acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Edge computing architectures enable real-time weight data streaming into warehouse management systems without on-premise server infrastructure. |
| Calibration Service Bundling | Absorbing metrology infrastructure costs into hardware contracts anchors premium positioning with pharmaceutical distributors requiring NIST-traceable records. |
| MEMS Sensor Technology Adoption | Compact force sensors digitize weight capture at lower cost points than traditional strain gauge assemblies for sub-500 kg batching applications. |
| Wireless Load Cell Fleet Expansion | Battery-powered networks eliminate cable maintenance in high-velocity fulfillment corridors while complying with encrypted audit trail mandates. |
| Regional Calibration Hub Development | Third-party metrology networks in Central and Eastern Europe limit aftermarket revenue capture and create infrastructure investment opportunities. |
Research Methodology
A standing panel of warehouse operations directors, OEM procurement managers, aftermarket service heads, and state weights and measures administrators provided ongoing calibration against secondary data from NIST Handbook 44 enforcement records, OIML R76 certification databases, EU Measuring Instruments Directive filings, and SEC 10-K disclosures from precision instrument manufacturers. Bottom-up equipment shipment tracking triangulated against top-down logistics infrastructure investment flows across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and wireless adoption curves anchored the analytical framework across product type, technology tier, end-use vertical, and installation configuration dimensions. CAGRs were derived from segment-level unit economics and replacement cycle compression effects. Forecast inputs incorporated cold chain logistics expansion in India, automotive just-in-time inventory mandates in Germany, and buyer consolidation patterns among US third-party logistics operators.
Sensitivities concentrate around NIST Handbook 44 audit trail mandate enforcement timing, strain gauge alloy supply disruptions from East Asian foundries, and cloud-native platform integration adoption rates among tier-one logistics contractors. Forecasts reflect assumptions regarding regulatory harmonization under CE marking convergence and calibration infrastructure development in underserved geographies. Material shifts in OIML R76 certification requirements or FSSAI traceability rule expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Slip Sheets Market