
 Plywood Box Market | 2026-2036
Plywood Box Market Size, Share, and Industry Trends Forecast 2026-2036
Plywood Box Market Insights
Digital printing and RFID-embedded tracking is reshaping how plywood boxes integrate into automated supply chains. Greif, Inc. leverages its global manufacturing footprint to serve bulk industrial customers with standardized container programs. Mondi Group anchors European demand through sustainably certified plywood sourcing and closed-loop recovery systems. Brambles Limited competes via pool-based reusable container networks that reduce per-trip packaging costs for high-volume shippers.
A plywood box consists of engineered wood panels bonded with moisture-resistant adhesives, typically constructed from 3-ply to 7-ply birch, eucalyptus, or mixed hardwood veneers, and functions as rigid protective packaging for heavy or fragile goods during transit and storage. Shipping Boxes dominate volume demand from automotive and machinery exporters, while Collapsible packaging types capture the fastest expansion as warehouse operators prioritize return-trip space efficiency. Custom sizing commands premium positioning among precision equipment manufacturers who require exact dimensional fit for vibration-sensitive cargo.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, while the EU F-Gas Regulation and REACH framework govern adhesive chemistry and end-of-life disposal pathways for wood packaging entering European markets. ISPM 15 heat-treatment standards for international solid wood packaging create compliance gates that favor plywood alternatives in cross-border trade. Stakeholders must weigh adhesive substitution timelines against container reuse economics as regulatory pressure on petrochemical binders intensifies.
Market Dynamics
E-commerce fulfillment networks are standardizing container specifications across distribution hubs, forcing plywood box manufacturers to align product dimensions with automated sortation systems and robotic handling equipment.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates for reusable transit packaging accelerate certified plywood substitution of single-use alternatives in European supply chains.
- Electronics export manufacturing:Precision equipment shippers in India and Vietnam scale protective packaging procurement for semiconductor and automotive component shipments.
- ISPM 15 heat-treatment standards:Cross-border compliance requirements for solid wood packaging favor engineered plywood containers that bypass international phytosanitary restrictions.
Market Restraints
- Adhesive chemistry constraints:Petrochemical binder price volatility and REACH framework restrictions on formaldehyde emissions compress margin flexibility for moisture-resistant plywood construction.
- Hardwood veneer supply concentration:Birch and eucalyptus raw material sourcing clusters in Baltic and Southeast Asian regions expose manufacturers to regional harvest quotas and export licensing delays.
- Substitute material competition:Corrugated plastic and molded fiber protective packaging capture lightweight cargo segments where dimensional precision matters less than weight reduction.
Strategic Opportunities
- RFID-embedded tracking convergence:Integration of digital printing with automated inventory systems enables real-time container location monitoring for high-value machinery shipments.
- Closed-loop recovery systems:Pool-based reusable container networks reduce per-trip packaging costs for automotive and aerospace manufacturers operating fixed distribution circuits.
- Collapsible design innovation:Warehouse operators in Germany and the Netherlands prioritize return-trip space efficiency, expanding demand for fold-flat plywood containers that compress to one-fifth shipping volume.
Industry Challenges
- Adhesive substitution timeline pressure:Bio-based binder development lags behind regulatory phase-out schedules for petrochemical resins, forcing manufacturers to balance compliance costs against container reuse economics.
- Automated handling compatibility certification:Robotics integrators demand precise dimensional tolerances and weight-bearing specifications that exceed legacy plywood construction standards, requiring production line retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plywood Box Market |
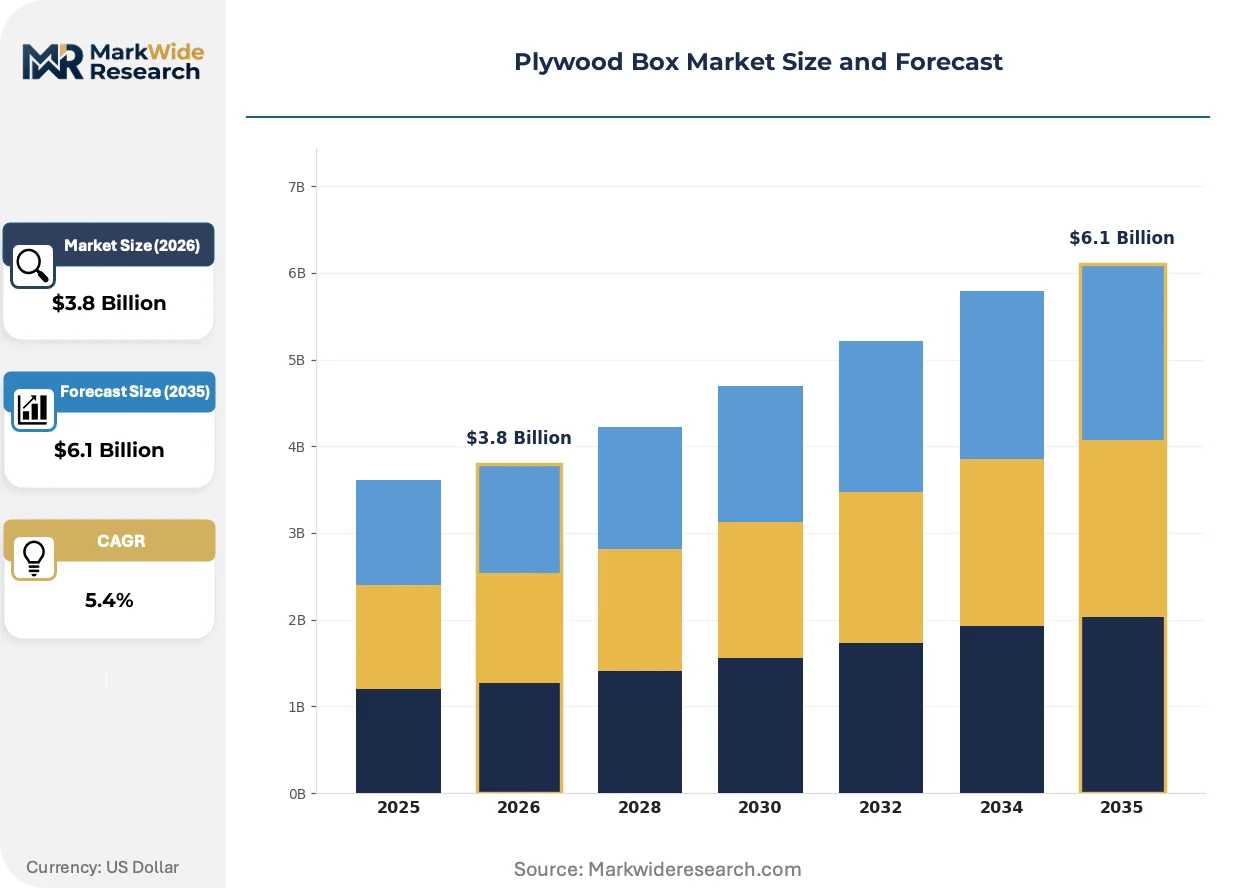
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shipping Boxes, Storage Boxes, Display Boxes, Industrial Boxes End User: Retailers, E-Commerce, Manufacturing, Agriculture Size: Small, Medium, Large, Custom Packaging Type: Flat Pack, Assembled, Collapsible, Reusable |
| Companies Covered | Brambles Limited, Greif, Inc., International Paper Company, Packaging Corporation of America, Smurfit Kappa Group, WestRock Company, Mondi Group, Nefab Group, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plywood Box Market Trends and Innovations
Digital identification technologies and sustainable material chemistry are compressing traditional procurement cycles while expanding the functional boundaries of protective packaging beyond physical containment.
RFID-embedded plywood box construction is collapsing the information gap between physical containers and warehouse management systems. Automotive parts distributors in Germany now specify RFID-tagged containers for just-in-sequence assembly line delivery, enabling automated sortation without manual barcode scanning. This convergence of packaging and data infrastructure is compressing labor requirements in high-throughput distribution centers.
REACH framework amendments governing adhesive chemistry are forcing formaldehyde emission reductions across composite wood products entering European markets. Manufacturers must reformulate moisture-resistant bonding agents or risk market exclusion under tightening ECHA substance restrictions. Birch plywood suppliers serving German machinery exporters are accelerating soy-based and lignin-derived binder pilot programs to maintain certification continuity.
Buyer consolidation among third-party logistics operators is concentrating procurement authority with fewer decision-makers who demand outcome-based container performance metrics. Large warehouse operators in the Netherlands now contract for damage-rate guarantees rather than per-unit box pricing, shifting supplier relationships toward shared-risk service models. This behavioral pivot favors plywood box manufacturers with integrated tracking capabilities and regional repair networks over commodity producers.
Plywood Box Market Segmentation
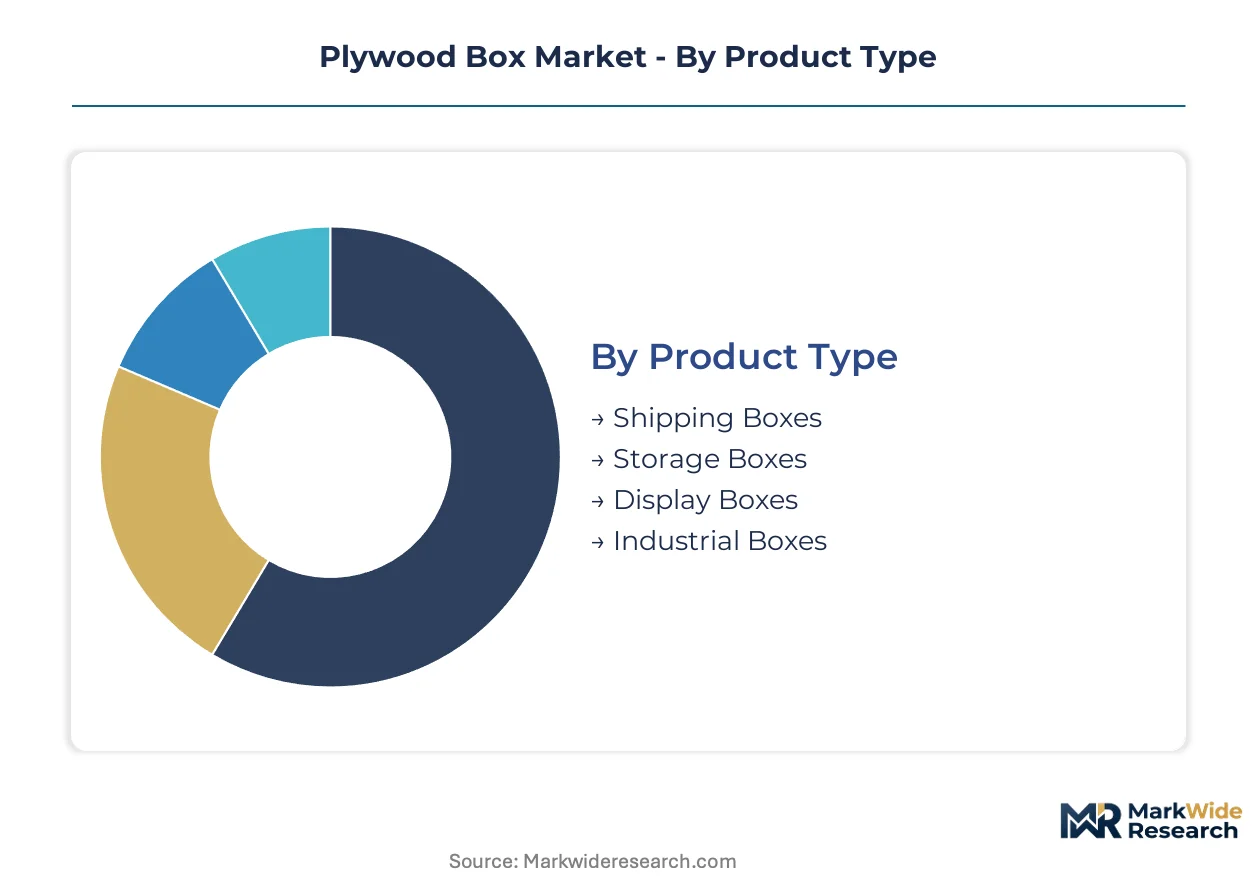
Plywood box procurement patterns diverge sharply across handling requirements and reuse economics. Manufacturers configure production lines around dimensional standardization for automated fulfillment while reserving custom capacity for precision cargo protection.
Product Type:
Container specifications align with cargo protection intensity across the handling spectrum from single-trip dispatch to multi-year industrial reuse cycles.
- Shipping Boxes:Engineered with 5-ply to 7-ply birch or eucalyptus cores and moisture-resistant phenolic bonding for ocean freight durability. Automotive and machinery exporters in Germany and Japan specify these for ISPM 15-exempt cross-border movement of heavy components.
- Storage Boxes:Constructed with lighter 3-ply poplar cores for static warehouse stacking rather than transit vibration. Third-party logistics operators in the Netherlands favor these for seasonal inventory holding where return-trip efficiency matters less than acquisition cost.
- Display Boxes:Surface-grade birch veneers with UV-cured print compatibility for retail floor presentation. Boutique electronics retailers in South Korea specify these for flagship store replenishment.
- Industrial Boxes:Reinforced corner posts and steel edge banding for foundry and aerospace component transport. Maintenance-repair-overhaul facilities in the US Gulf Coast cluster procurement here.
The dominant share belongs to Shipping Boxes, while Collapsible configurations within Industrial Boxes are closing the gap fastest.
End User:
Buyer sophistication determines whether procurement centers on unit economics or total cost of ownership across container lifecycles.
- Retailers:High-volume seasonal procurement with standardized dimensions for back-of-store consolidation. French hypermarket chains drive demand for flat-pack delivery to minimize inbound freight cube.
- E-Commerce:Automated sortation compatibility requirements from fulfillment robotics integrators. Warehouse operators in India's NCR region specify precise weight-bearing tolerances for conveyor system integration.
- Manufacturing:Just-in-sequence delivery mandates from automotive assemblers. German Tier 1 suppliers contract for RFID-embedded containers with damage-rate guarantees rather than per-unit pricing.
- Agriculture:Moisture-resistant specifications for produce export cold chains. Vietnamese dragon fruit exporters scale procurement for phytosanitary-compliant shipment to EU markets.
Manufacturing commands the largest procurement volume, yet E-Commerce is expanding most quickly as fulfillment network standardization accelerates.
Size:
Dimensional strategy splits between maximizing cube utilization and accommodating non-standard cargo geometries.
- Small:Precision component protection for semiconductor and medical device shipments. Swiss pharmaceutical distributors specify these for temperature-validated last-mile delivery.
- Medium:General merchandise handling across multi-channel retail networks. This tier captures the broadest cross-industry application.
- Large:Machinery sub-assembly and automotive powertrain module containment. Mexican maquiladora operations concentrate demand here for NAFTA-region component flow.
- Custom:Exact-fit engineering for vibration-sensitive or irregularly dimensioned cargo. German precision equipment manufacturers pay premium positioning for finite-element-validated designs.
Medium dimensions anchor volume, though Custom sizing gains share fastest as precision manufacturing outsourcing climbs.
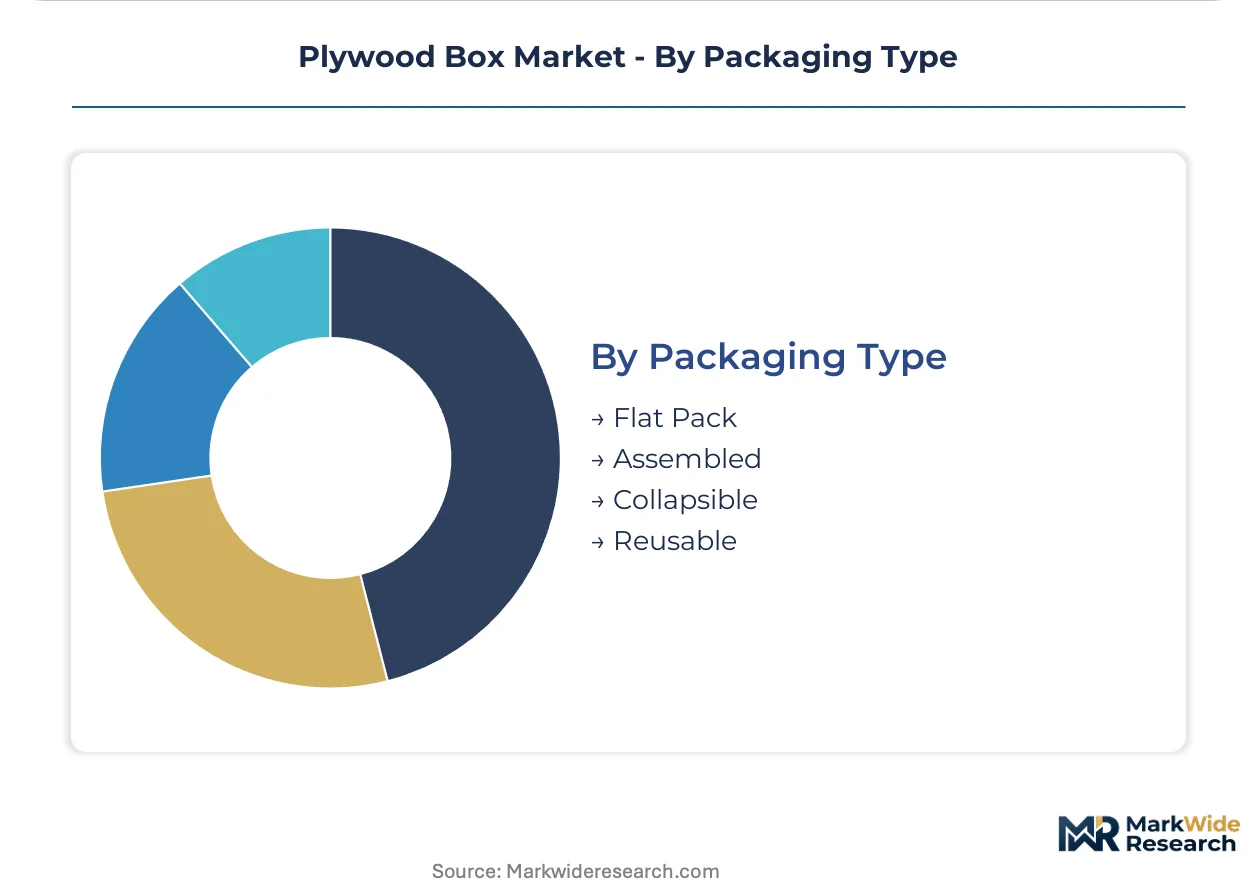
Packaging Type:
Assembly state and reuse potential determine logistics economics across inbound supply and reverse distribution legs.
- Flat Pack:Knock-down panel kits for destination assembly, compressing inbound shipping volume by 80%. IKEA-aligned furniture suppliers in Poland dominate procurement.
- Assembled:Factory-constructed containers ready for immediate loading. Traditional industrial procurement favors this for labor cost minimization at origin.
- Collapsible:Hinge-mounted designs folding to one-fifth shipping volume for return trips. Pool-based container networks in the Netherlands and Germany prioritize these for closed-loop automotive circuits.
- Reusable:Heavy-duty construction rated for 50+ use cycles with regional repair networks. Aerospace manufacturers operating fixed distribution circuits specify these under outcome-based contracts.
Assembled containers hold the dominant position, yet Collapsible designs are climbing the fastest as warehouse operators prioritize return-trip space efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision machinery to automotive assemblers across Mexico and the United States, driving container standardization for cross-Atlantic component flows. This trade corridor anchors European plywood box procurement volumes while Asian manufacturing hubs scale protective packaging for electronics exports.
United States
Aerospace maintenance-repair-overhaul facilities in the US Gulf Coast cluster demand reinforced industrial boxes for turbine component transport. EPA formaldehyde emission rules under TSCA Title VI regulate composite wood products entering domestic supply chains. Houston-area logistics operators specify steel-edge-banded containers for offshore oilfield equipment movements.
Germany
Automotive Tier 1 suppliers contract for RFID-embedded containers with damage-rate guarantees rather than per-unit pricing. EU REACH framework amendments restrict formaldehyde emissions from adhesive bonding agents. Stuttgart machinery exporters pilot soy-based binder formulations to maintain ECHA certification continuity.
China
Furniture manufacturers in the Yangtze River Delta procure flat-pack knock-down kits compressing inbound shipping volume. GB standards for wood packaging materials govern domestic and export-bound container construction. Zhejiang province fabricators align dimensions with automated sortation systems at Ningbo-Zhoushan port distribution hubs.
India
Electronics exporters in Karnataka and Tamil Nadu scale protective packaging procurement for semiconductor component shipments. BIS certification requirements for wood-based panel products create compliance thresholds for moisture-resistant construction. Bangalore precision equipment manufacturers specify custom-sized containers for vibration-sensitive cargo.
Vietnam
Dragon fruit exporters in the Mekong Delta region scale procurement for phytosanitary-compliant shipment to EU markets. ISPM 15 heat-treatment standards favor engineered plywood alternatives bypassing international solid wood restrictions. Ho Chi Minh City logistics operators prioritize collapsible designs for return-trip space efficiency.
Plywood Box Market Competitive Landscape
On the supply side, the industry is consolidating around container pooling networks and integrated packaging service providers. Three strategic archetypes dominate: asset-heavy pool operators managing reusable container fleets, vertically integrated paper and packaging conglomerates with plywood diversification, and regional specialists in custom-engineered protective solutions. Capacity expansion in Southeast Asian manufacturing zones and technology licensing for RFID-embedded tracking represent the dominant competitive vectors.
Within the asset-heavy pooling tier, Brambles Limited and Greif, Inc. exemplify network-scale operators. Mondi Group occupies a position among European-based diversified packaging conglomerates with sustainably certified sourcing capabilities. These three anchors represent contrasting strategic positions: pool-based reuse economics, global manufacturing footprint coverage, and closed-loop recovery system integration.
| Leading Market Players |
|---|
| Brambles Limited |
| Greif, Inc. |
| International Paper Company |
| Packaging Corporation of America |
| Smurfit Kappa Group |
| WestRock Company |
| Mondi Group |
| Nefab Group |
| DS Smith |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province fabricators supply the bulk of flat-pack knock-down kits to European furniture networks, concentrating capacity leverage among Yangtze River Delta exporters who dictate phenolic resin-adhesive cost pass-throughs to downstream buyers. This geographic clustering amplifies pricing power during Baltic birch veneer harvest quota cycles, forcing German machinery exporters to absorb premium surcharges or switch to eucalyptus-core alternatives.
Pricing Analysis
Current-generation RFID-embedded containers command substantial premiums over prior-generation plain plywood boxes, while next-generation bio-adhesive prototypes remain pre-commercial and unpriced. Three-tier pricing structure across premium RFID-tagged, standard ISPM 15-compliant, and economy-grade untreated containers dominates procurement. Price differentiation hinges on ECHA REACH certification grade and volume scale commitments from automotive Tier 1 suppliers. Cost compression in standard-tier boxes is intensifying because petrochemical binder volatility compresses margin flexibility. E-commerce fulfillment operators exhibit highest price sensitivity, while German precision equipment manufacturers show least sensitivity due to damage-rate guarantee contracting.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for plywood box procurement networks. Manufacturing concentrates in China, Vietnam, and Poland, with raw material draws from Baltic birch forests and Southeast Asian eucalyptus plantations. Supply chains rest on phenolic resin and moisture-resistant adhesive inputs from petrochemical suppliers. Single-source vulnerability in Baltic veneer harvesting creates periodic bottlenecks. Distribution runs through Ningbo-Zhoushan port consolidation hubs for Asia-origin containers and Rotterdam-Bremen corridors for European inland delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as buyer consolidation among third-party logistics operators fragments procurement authority across specialized regional repair networks and digital tracking capabilities.
For Market Incumbents: Build certification moats around ECHA REACH-compliant bio-adhesive formulations before regulatory phase-out deadlines tighten. Invest in backward integration into captive Baltic birch veneer sourcing to hedge harvest quota volatility. Expand RFID-embedded container fleets in Stuttgart automotive corridors to lock in damage-rate guarantee contracts against emerging pool-based competitors.
For New Entrants and Emerging Players: Pursue collapsible container specialization for Dutch and German closed-loop automotive circuits where return-trip efficiency premiums remain underexploited. Target Vietnamese electronics export corridors for phytosanitary-compliant protective packaging procurement. Deploy digital printing integration as the primary go-to-market wedge against commodity producers lacking automated inventory system compatibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pool-based reusable container network operators with regional repair infrastructure. Long-term viability favors asset-heavy models with fixed distribution circuit lock-ins over transactional box manufacturers exposed to substitute material competition. Acquisition screening should prioritize Southeast Asian fabricators with BIS certification pathways into Indian electronics export markets. Watch adhesive substitution timeline acceleration as the critical inflection signal for margin structure compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Veneer Sourcing | Baltic birch plantation control secures harvest quota immunity for German machinery exporters. |
| Bio-Adhesive Certification Investment | ECHA REACH-compliant soy-based binders maintain European market access against petrochemical restrictions. |
| RFID-Embedded Container Fleet Expansion | Automated sortation compatibility captures Stuttgart automotive Tier 1 damage-rate guarantee contracts. |
| Collapsible Design Manufacturing Scale-Up | Return-trip compression to one-fifth volume penetrates Dutch pool-based closed-loop circuits. |
| Southeast Asian Production Footprint | Vietnamese and Indian BIS certification pathways access electronics export protective packaging procurement. |
Research Methodology
A spread of perspectives from plywood box procurement managers at German automotive Tier 1 suppliers, Dutch third-party logistics operators, Yangtze River Delta fabricators, and ECHA regulatory affairs specialists converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, FSC and PEFC certification registries, SEC filings of listed packaging conglomerates, and ISPM 15 compliance databases. Bottom-up production capacity tallies and top-down demand segmentation from electronics and machinery export volumes were triangulated to establish market boundaries.
Demand-supply-balance modeling across the projection horizon anchored volume and value outputs. Segmentation dimensions included product type, end-user industry, packaging configuration, and regional production hub clustering. CAGRs were derived from elasticity-weighted growth rate synthesis across these segments. Industry-specific forecast inputs incorporated ISPM 15 compliance adoption curves and REACH framework amendment implementation timelines.
Sensitivities concentrate around adhesive chemistry substitution pace, Baltic birch harvest quota adjustments, and e-commerce fulfillment network standardization speed. Forecasts reflect documented assumptions about regulatory phase-out schedules and pool-based container reuse economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market