
 Vertical Axis Wind Turbine Market | 2026-2036
Vertical Axis Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Axis Wind Turbine Market Analysis
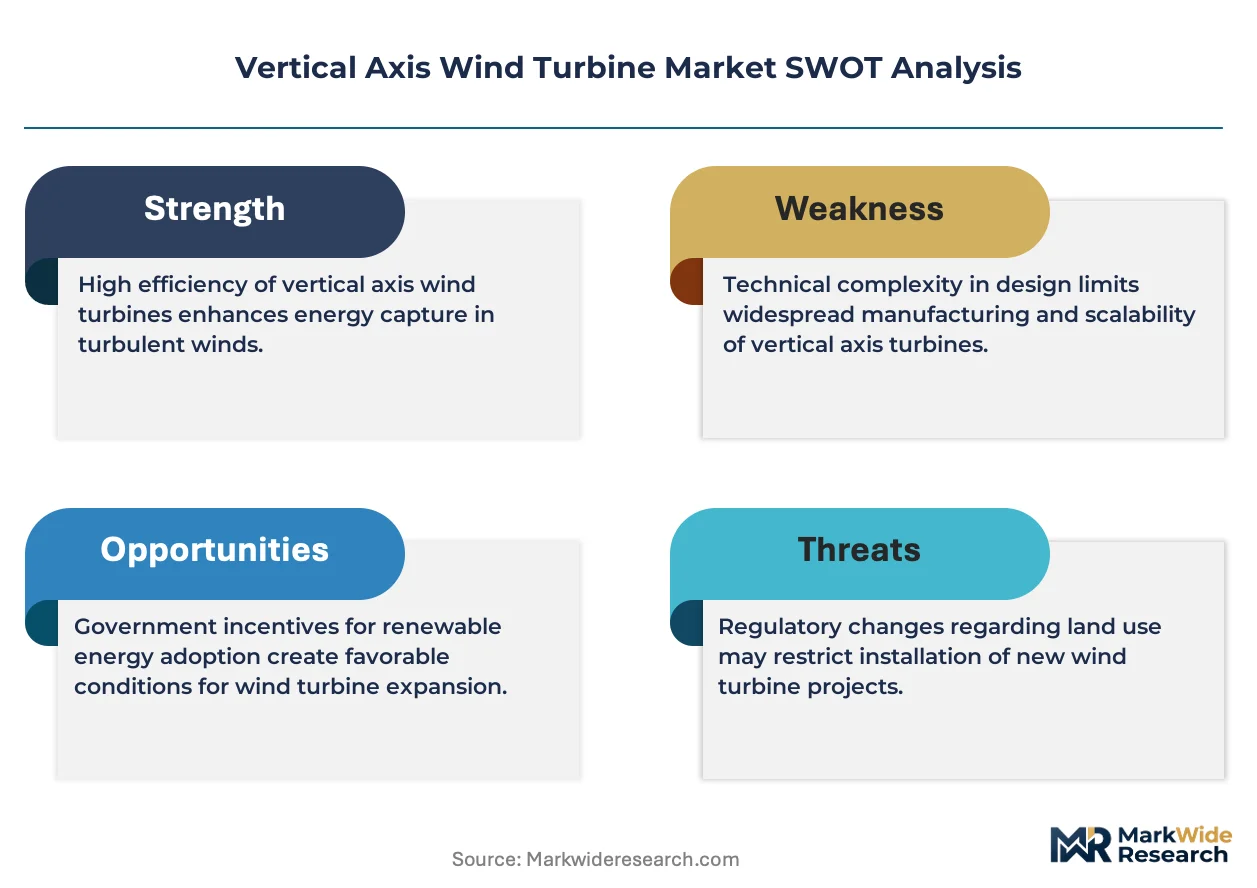
Performance-based maintenance contracts is restructuring how vendors monetize vertical axis wind turbine deployments. Urban Green Energy leverages long-term service agreements to secure recurring revenue from commercial rooftop installations. IceWind anchors its Nordic presence through specialized cold-climate servicing protocols that sustain higher annual uptime. ArborWind differentiates via remote diagnostics platforms that extend operational visibility without on-site technician visits.
A vertical axis wind turbine converts kinetic wind energy into electrical power through blades rotating around a vertical shaft, typically achieving cut-in speeds of three to four meters per second and operating efficiently in turbulent, omnidirectional wind conditions common to urban canyons and coastal zones. The technology serves distributed generation needs where horizontal-axis systems face space, noise, or avian constraints. Darrieus configurations lead in utility-scale pilot projects due to higher tip-speed ratios and improved aerodynamic efficiency, while Savonius designs occupy niche marine and agricultural applications where low-starting-torque requirements outweigh peak efficiency targets. The residential segment competes with solar-plus-storage bundles but retains advantage in northern latitudes with limited winter insolation.
The EU Green Deal and F-Gas Regulation tighten embodied-carbon thresholds for on-site generation equipment, while the EPA's renewable energy incentives and China's dual carbon goals under MEE guidance shape procurement criteria across three continents. IEC 61400-2 small wind turbine standards and ISO 19009 design requirements govern certification pathways that determine market access for new entrants. Stakeholders must monitor evolving noise ordinances and setback regulations in dense metropolitan zones where vertical axis formats hold structural advantage.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing embodied-carbon thresholds for on-site generation equipment, forcing manufacturers to reengineer blade materials and nacelle assemblies while commercial building operators accelerate distributed rooftop procurement.
Growth Catalysts
- Urban Density Mandates:The EU Green Deal tightens energy-efficiency requirements for commercial buildings in Germany, France, and the Netherlands, driving port authorities and logistics operators toward compact turbine formats.
- Dual Carbon Goals:China's MEE guidance under dual carbon targets prioritizes distributed renewables in coastal manufacturing zones where vertical axis systems tolerate turbulent wind corridors.
- Small Wind Certification:IEC 61400-2 standards unlock financing for residential and agricultural deployments by reducing technical due diligence burdens for lenders.
Market Restraints
- Neodymium Price Volatility:Permanent magnet supply concentration in Chinese processing facilities exposes generator manufacturers to rare earth cost swings.
- Tip-Speed Limitations:Darrieus configurations face aerodynamic efficiency ceilings below horizontal-axis alternatives, constraining utility-scale adoption.
- Permitting Friction:Municipal noise ordinances in dense metropolitan zones impose setback requirements that erode viable installation footprints.
Strategic Opportunities
- Nordic Cold-Climate Protocols:Specialized icing mitigation and low-temperature lubricant systems open agricultural and remote telecom applications in Norway, Sweden, and Finland.
- Marine Hybrid Arrays:Savonius designs paired with wave energy converters address off-grid coastal infrastructure in Scotland and Portugal.
- Performance Contracting:Long-term service agreements tied to uptime guarantees shift vendor revenue from equipment sales to recurring operational streams.
Industry Challenges
- Aerodynamic Modeling Talent:Computational fluid dynamics expertise for vertical axis rotor optimization remains concentrated in academic and aerospace-adjacent labor pools.
- Multi-Standard Certification:Divergent IEC, ISO 19009, and national small-wind requirements extend product validation timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Axis Wind Turbine Market |
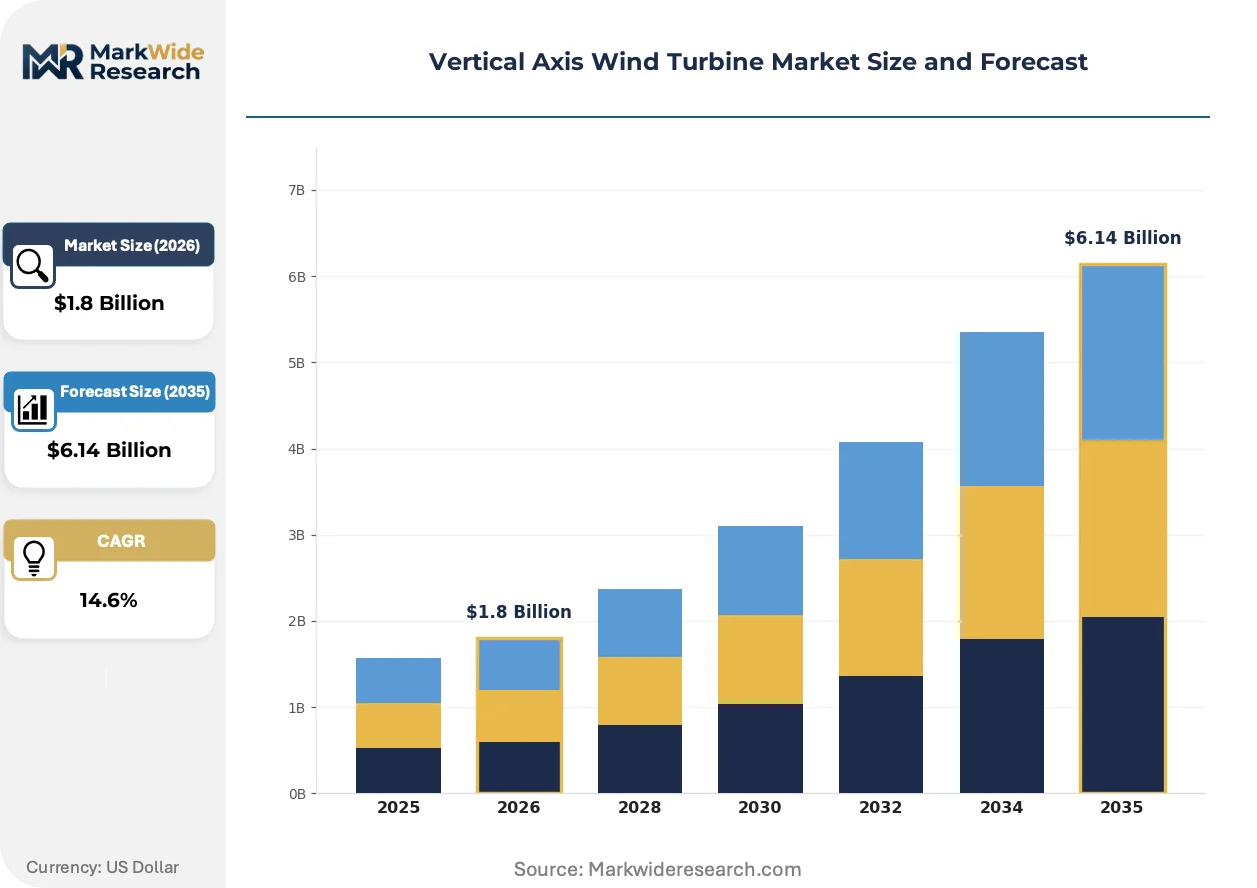
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: H-Darrieus, Darrieus, Savonius, Others Application: Residential, Industrial, Agricultural, Marine End User: Government, Commercial, Utilities, OEMs Installation Type: Onshore, Offshore, Hybrid, Ground-Mounted |
| Companies Covered | Urban Green Energy, Helix Wind, Agile Wind Power, Windspire Energy, IceWind, ArborWind, Wind Harvest International, Hi-VAWT Technology, Challenergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Axis Wind Turbine Market Emerging Trajectories
Active magnetic bearing systems and modular blade architectures are compressing maintenance intervals while expanding operational envelopes into previously marginal wind regimes.
Magnetic levitation generator technology is decentralizing drivetrain maintenance by eliminating mechanical contact surfaces that degrade in coastal salt environments. Commercial port operators in Rotterdam and Hamburg are piloting these systems for quayside power generation. The technology is decentralizing service revenue models toward predictive remote monitoring rather than scheduled technician visits.
The EPA's renewable energy incentives under the Inflation Reduction Act are restructuring project finance for distributed wind installations. Investment tax credit eligibility now requires domestic content thresholds that favor North American blade and tower fabrication. Commercial building developers in Texas and California are reconfiguring procurement criteria to capture these benefits.
Building-integrated wind systems are displacing standalone rooftop installations as architects specify aesthetic turbine cladding for mixed-use developments. The segment prioritizes Darrieus configurations with architectural finishes over bare industrial designs. This preference rotation is most visible in Copenhagen, Singapore, and Vancouver where planning authorities enforce visual impact standards.
Vertical Axis Wind Turbine Market Segmentation
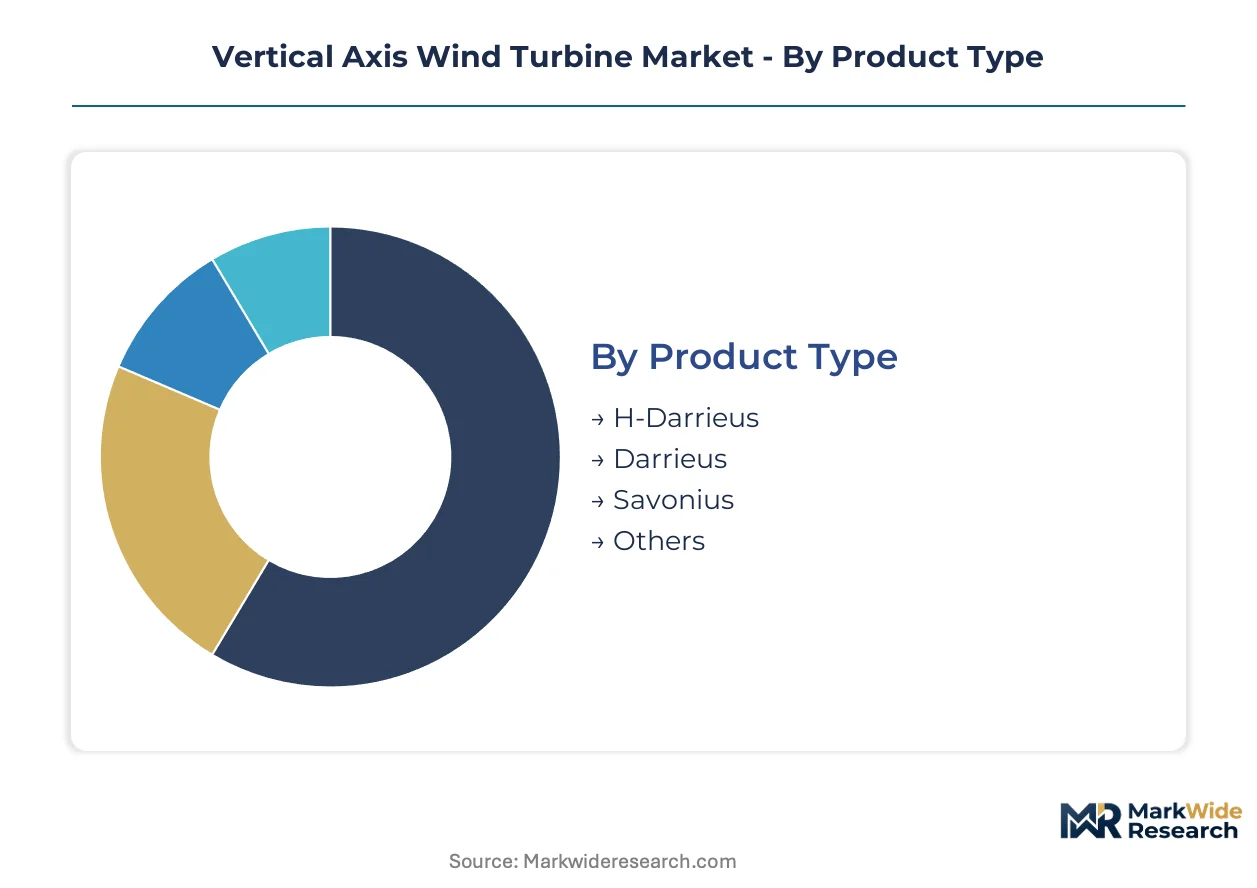
Vertical axis wind turbine procurement hinges on aerodynamic configuration, site constraints, and ownership structure. Each segmentation dimension reveals distinct buyer priorities—from efficiency metrics in product selection to regulatory risk tolerance in end-user profiles.
Product Type:
Buyers weigh tip-speed ratio against starting torque requirements when selecting rotor architectures.
- Darrieus:Curved-blade designs achieve higher tip-speed ratios than alternatives, making them the default for commercial rooftop installations in Germany and the Netherlands where space efficiency commands premium pricing. IEC 61400-2 certification pathways favor this configuration for utility-interconnected projects.
- H-Darrieus:Straight-blade variants simplify manufacturing and permit modular blade replacement, attracting port authorities in Rotterdam and Hamburg seeking standardized maintenance protocols for quayside arrays. The format sacrifices some aerodynamic efficiency for operational predictability in salt-laden environments.
- Savonius:Drag-based rotors deliver high starting torque at low wind speeds, serving marine hybrid installations off Scotland and agricultural water pumping in northern China where cut-in velocity matters more than peak output.
- Others:Giromill and helical configurations occupy niche applications including building-integrated systems in Copenhagen and Singapore where architectural envelope integration overrides pure performance metrics.
Darrieus leads on scale; H-Darrieus leads on momentum.
Application:
Site-specific wind regimes and grid access determine deployment economics across use cases.
- Industrial:Manufacturing facilities in China's coastal zones deploy turbulent-tolerant formats to meet MEE dual carbon mandates without dedicating scarce floor space. Power purchase agreement structures favor this segment for behind-the-meter generation.
- Residential:Northern European households in Norway and Sweden compensate for winter solar shortfalls through small wind systems, though solar-plus-storage bundles constrain growth in sunnier latitudes.
- Agricultural:Remote farms in Finland and Sweden integrate cold-climate turbines with diesel displacement strategies, leveraging specialized icing mitigation protocols.
- Marine:Off-grid coastal infrastructure in Portugal pairs Savonius rotors with wave energy converters, exploiting shared mooring and transmission infrastructure.
Industrial deployment dominates absolute capacity; marine applications are climbing the fastest.
End User:
Risk allocation preferences separate procurement behaviors across ownership models.
- Commercial:Building operators in Texas and California reconfigure procurement to capture IRA investment tax credits, prioritizing domestic content thresholds in vendor selection.
- Government:Municipal port authorities in Germany and the Netherlands accelerate distributed procurement under EU Green Deal efficiency mandates, accepting longer payback periods for public sustainability targets.
- Utilities:Grid operators pilot Darrieus configurations for distributed generation integration, constrained by interconnection queue delays and distribution network upgrade timelines.
- OEMs:Equipment manufacturers integrate captive turbine capacity for manufacturing facility decarbonization, particularly in China's coastal industrial zones.
Commercial buyers anchor current volume; government procurement shows steepest expansion trajectory.
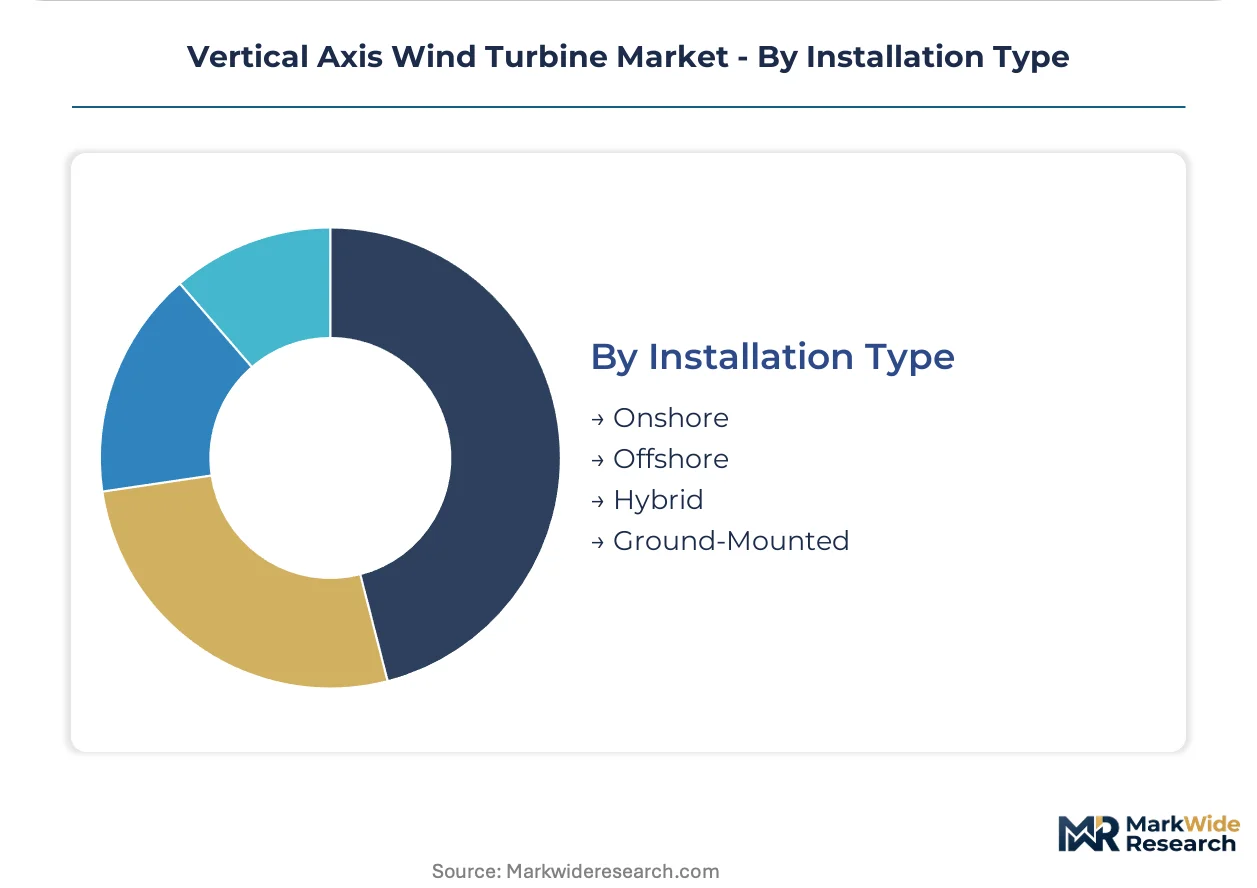
Installation Type:
Foundation and grid connection costs drive format selection more than rotor architecture.
- Onshore:Rooftop and ground-mounted systems in urban Germany and the United States face municipal setback and noise ordinance constraints that favor compact vertical axis formats over horizontal alternatives.
- Hybrid:Combined wind-solar installations in California and Texas optimize capacity factor through complementary generation profiles, requiring sophisticated inverter and storage integration.
- Offshore:Floating platform pilots in Scotland test marinized drivetrain configurations, though horizontal-axis designs retain cost advantages at utility scale.
- Ground-Mounted:Agricultural and remote telecom applications in Nordic countries prioritize cold-climate operational envelopes over urban aesthetic constraints.
Onshore deployment commands installed base; hybrid configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's port authorities deploy more vertical axis capacity than China's coastal manufacturing zones, though Beijing's dual carbon mandates are accelerating procurement faster than any European regulator.
United States
Commercial building operators in Texas and California reconfigure procurement to capture IRA investment tax credits. The EPA's domestic content thresholds favor North American blade fabrication. Developers in Houston and Los Angeles prioritize distributed rooftop formats for behind-the-meter generation.
Germany
Port authorities in Hamburg and Rotterdam accelerate quayside turbine procurement under EU Green Deal efficiency mandates. The F-Gas Regulation tightens embodied-carbon thresholds for on-site generation equipment. Industrial clusters along the Rhine corridor integrate compact formats into logistics facility retrofits.
China
Coastal manufacturing zones in Shanghai and Guangdong deploy turbulent-tolerant systems to meet MEE dual carbon targets. The country's dual carbon goals prioritize distributed renewables in dense industrial corridors. Yangtze River Delta factories integrate captive turbine capacity for facility decarbonization.
Norway
Agricultural and remote telecom operators in Trøndelag and Vestland adopt specialized cold-climate protocols for icing mitigation. National regulators enforce low-temperature operational standards for Arctic-zone equipment. Nordic engineering clusters refine lubricant systems that sustain higher annual uptime in sub-zero conditions.
United Kingdom
Marine hybrid installations off Scotland pair Savonius rotors with wave energy converters. Edinburgh and Aberdeen harbor authorities pilot shared mooring infrastructure for off-grid coastal systems. Scottish renewables clusters test marinized drivetrain configurations in North Sea pilot zones.
Vertical Axis Wind Turbine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers commanding premium positioning in commercial rooftop deployments while component fabricators serve price-sensitive agricultural applications. The vendor base organizes around three strategic archetypes: cold-climate engineering specialists, urban building-integrators, and marine hybrid developers. Consolidation pressure is accelerating through technology licensing agreements and strategic partnerships that extend geographic coverage without capital-intensive facility builds.
Among Nordic cold-climate specialists, IceWind anchors the tier through specialized servicing protocols, while ArborWind occupies a position within the remote diagnostics segment. Urban Green Energy exemplifies the building-integration archetype for commercial rooftop formats. These three represent distinct competitive vectors—climate adaptation, predictive maintenance platforms, and architectural envelope integration—that define how vendors structure recurring revenue streams away from pure equipment sales.
| Leading Market Players |
|---|
| Urban Green Energy |
| Helix Wind |
| Agile Wind Power |
| Windspire Energy |
| IceWind |
| ArborWind |
| Wind Harvest International |
| Hi-VAWT Technology |
| Challenergy |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up cold-climate specialists anchor supply discipline through captive servicing protocols, translating operational reliability into pricing premiums while compressing margins for undifferentiated equipment-only vendors.
Pricing Analysis
Capacity additions in China are reshaping price floors for generator assemblies and blade fabrications, pressuring legacy Western manufacturers. Pricing stratifies across IEC 61400-2 certified premium tiers, domestic-content compliant standard tiers, and uncertified economy imports. Cost compression in the economy tier is intensifying because Chinese coastal manufacturing zones exploit scale advantages in permanent magnet processing. Commercial building operators in Texas and California demonstrate highest price sensitivity due to IRA domestic content threshold compliance costs, while Nordic agricultural buyers prioritize cold-climate uptime guarantees over upfront expenditure.
Supply Chain Analysis
Dual-sourcing mandates from German port authorities and Dutch logistics operators require qualified suppliers in both China and Germany for critical drivetrain components. Rare earth processing concentrates in Chinese facilities, generator manufacturing clusters in Germany and China, and blade fabrication in the United States and Denmark. Permanent magnet supply rests on neodymium-dysprosium extraction, carbon fiber composite blades, and marinized bearing assemblies. Single-source vulnerability in Chinese rare earth processing exposes generator manufacturers to cost volatility. Distribution runs through EPC contractors for utility-scale pilots and direct-to-installer channels for residential and agricultural deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical axis wind turbine market compounds steadily through embedded regulatory mandates that harden distributed generation requirements across commercial building stock.
For Market Incumbents: Anchor defensive positioning through backward integration into permanent magnet supply chains and certification investment in cold-climate protocols. IceWind's specialized servicing model demonstrates how operational reliability contracts neutralize price competition from Chinese equipment imports. Capacity addition in German port zones threatens margin compression for undifferentiated vendors lacking predictive maintenance platforms. For New Entrants and Emerging Players: Enter via marine hybrid installations off Scotland and Portugal, where Savonius-wave energy convergence remains underpenetrated by established vendors. Agricultural water pumping in northern China offers a second white-space target where low-wind-starting requirements outweigh peak efficiency metrics. A performance-contracting go-to-market angle shifts revenue recognition from equipment sale to recurring uptime guarantees, reducing customer capital commitment friction. For Investors and Strategic Acquirers: Building-integrated wind specialists are the most active acquirer in this space, seeking architectural envelope capabilities for mixed-use developments in Copenhagen and Singapore. The five-to-ten-year viability window favors vendors with recurring revenue streams over pure equipment manufacturers. Acquisition target archetypes include remote diagnostics platform developers and cold-climate engineering boutiques. Monitor interconnection queue clearance velocity in Texas and California as the signal to watch for distributed generation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Certification Program | Unlocks Nordic agricultural and telecom applications through IEC 61400-2 compliance with icing mitigation protocols. |
| Performance Contracting Transition | Shifts Urban Green Energy and ArborWind revenue from equipment sales to recurring service agreements with uptime guarantees. |
| Domestic Content Compliance | Captures IRA investment tax credits for Texas and California commercial building operators sourcing North American blades. |
| Marine Hybrid Array Development | Combines Savonius rotors with wave energy converters for Scottish and Portuguese off-grid coastal infrastructure. |
| Predictive Diagnostics Platform | Extends operational visibility without technician visits, differentiating vendors in Rotterdam and Hamburg port deployments. |
Methodological Framework
Direct dialogue with EPC contractors, port authority planning officers, commercial building facility managers, and agricultural equipment distributors grounded qualitative assessment, cross-referenced with customs trade data, IEC certification registries, FERC interconnection filings, and EU Green Deal implementation reports. Bottom-up installation tracking and top-down regulatory mandate sizing were triangulated for coherence.
Market size outputs and growth trajectories were derived through multi-segment modeling across aerodynamic configuration, application use case, end-user ownership structure, and installation type dimensions. CAGRs were computed from annual capacity addition curves and average selling price evolution across the projection horizon. Forecast inputs incorporated MEE dual carbon implementation timelines, IRA domestic content phase-in schedules, and municipal noise ordinance adoption patterns.
Inputs from EPC contractors and port authorities were available through the study window; gaps in proprietary performance data from private turbine operators introduce uncertainty bands around capacity factor assumptions. Forecasts reflect documented regulatory trajectories and technology cost curves. Deviation in rare earth export licensing from Chinese processing facilities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market