
 United States Wind Energy Market | 2026-2036
United States Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wind Energy Market Analytics
Corporate offtakers are reorganizing procurement strategies, displacing traditional utility buyers as the fastest-growing demand archetype in the United States wind energy market. NextEra Energy leverages its vertically integrated development pipeline to capture utility-scale contracts across the Great Plains. Invenergy anchors its position through direct corporate power purchase agreements with technology and manufacturing buyers. GE Vernova competes on turbine platform specialization, sustaining manufacturing scale advantages in onshore installations.
United States wind energy encompasses the generation of electricity from kinetic airflow converted via aerodynamic rotor blades driving generator systems, with modern onshore turbines typically rated between 2.5 MW and 3.5 MW and hub heights exceeding 80 meters to maximize capacity factors. The primary commercial purpose is grid-connected bulk power supply and behind-the-meter corporate renewable energy procurement. Onshore turbines dominate installed capacity, though offshore turbines represent the fastest-expanding technology segment as floating foundation designs mature. Utility-scale installations command the largest revenue pool, while distributed generation and community wind configurations address rural cooperative and municipal buyer segments where transmission access constraints limit centralized development.
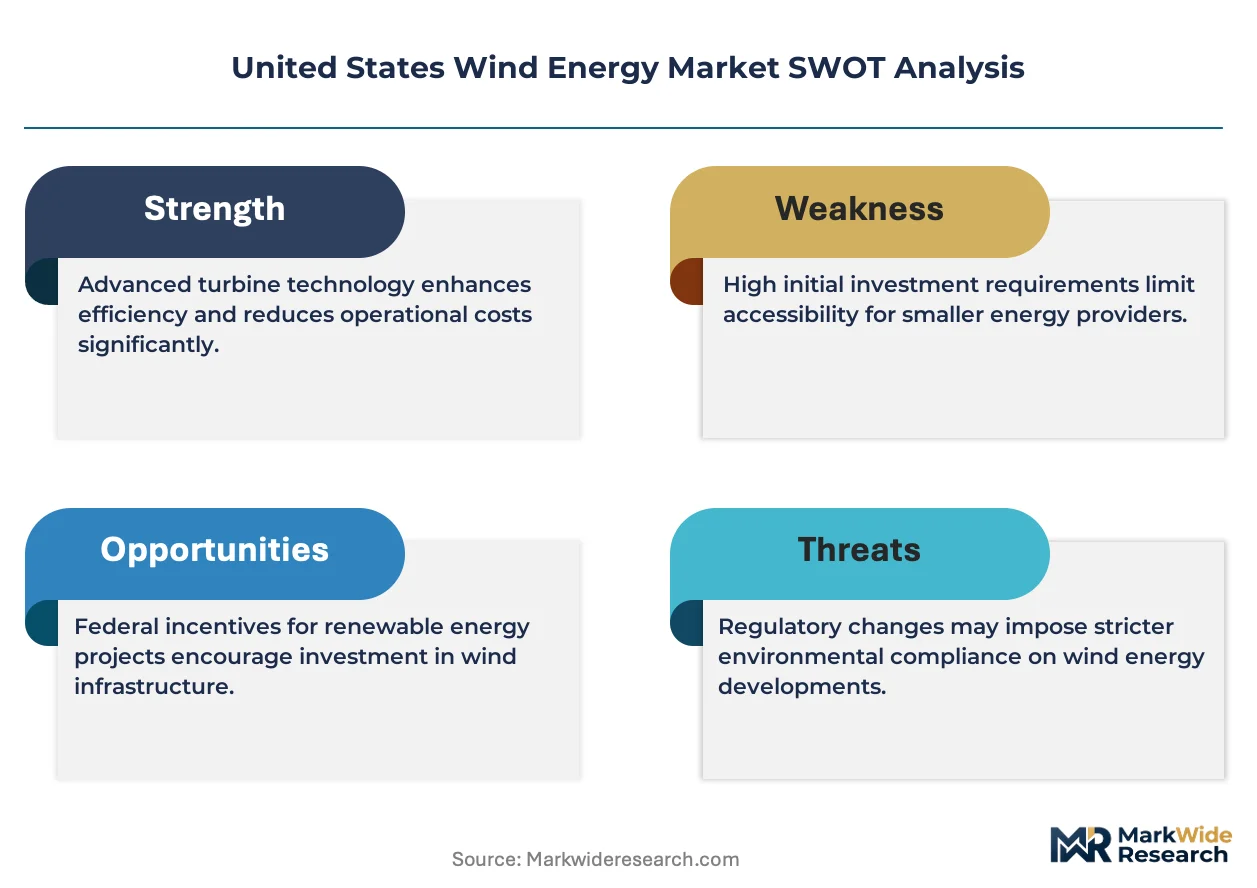
The Federal Energy Regulatory Commission governs interstate transmission access and wholesale market participation, while the Internal Revenue Service administers production and investment tax credit eligibility under the Inflation Reduction Act. The Department of Energy sets technical standards through its national laboratory network, influencing turbine certification and grid interconnection requirements. State public utility commissions in Texas, California, and New York layer additional siting and renewable portfolio obligations that shape regional deployment patterns. Stakeholders must monitor interconnection queue reform and offshore lease auction timing as decisive variables for capital allocation.
Market Dynamics
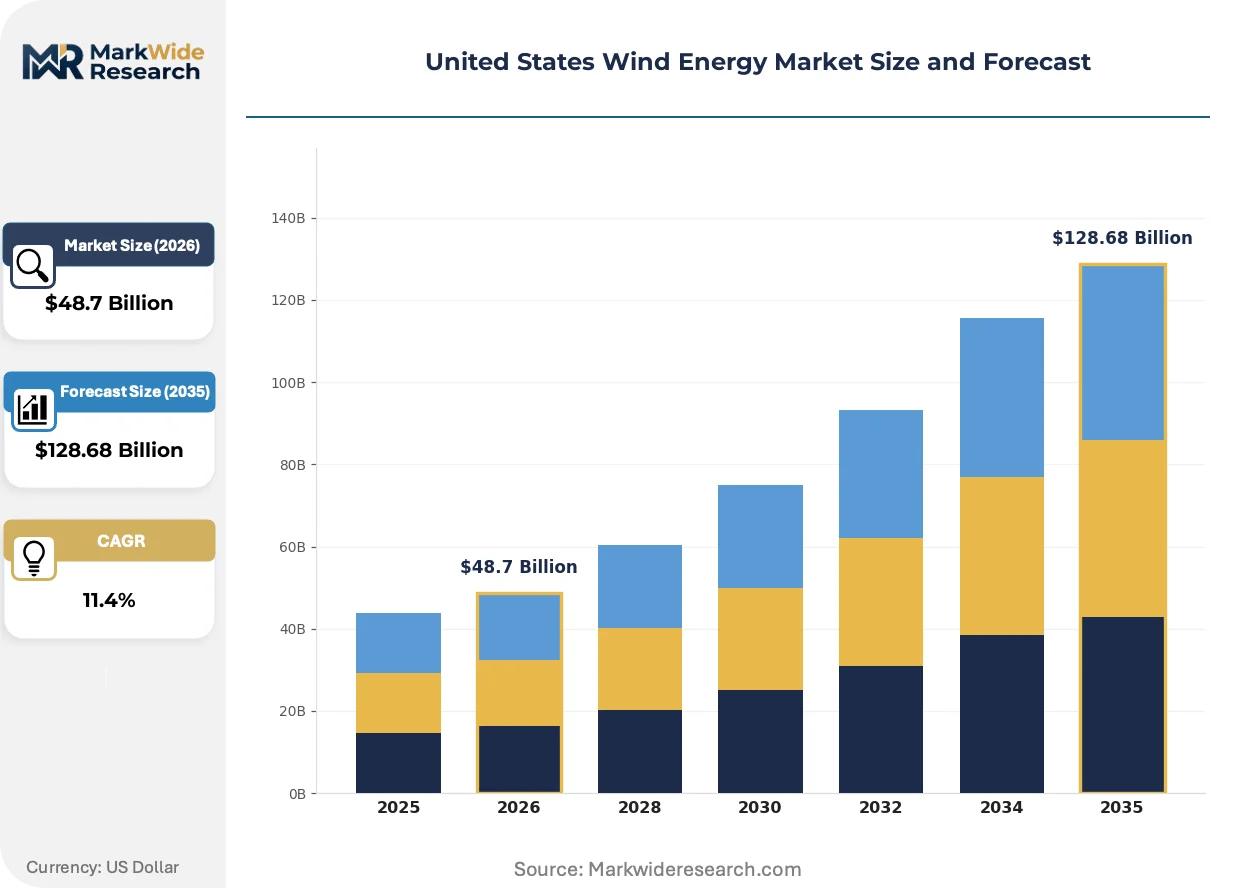
The Inflation Reduction Act production tax credits are compressing project development timelines and redrawing competitive positioning across the United States wind energy market.
Growth Catalysts
- IRA Production Tax Credits:The 10-year credit extension under the Inflation Reduction Act improves project IRRs and accelerates procurement commitments from utility-scale offtakers.
- Corporate Renewable Energy Procurement:Data center operators and semiconductor manufacturers are contracting directly with wind developers to meet Scope 2 emissions targets.
- Great Plains Wind Resource Concentration:Texas, Iowa, and Oklahoma corridors offer capacity factors exceeding 45 percent, lowering levelized cost of energy versus other US regions.
Market Restraints
- Steel and Rare Earth Input Volatility:Turbine tower steel and permanent magnet rare earths face price swings tied to Chinese export quotas and US tariff regimes.
- Interconnection Queue Congestion:FERC Order 2023 reforms have not cleared backlog delays averaging three to five years for grid access in PJM and MISO territories.
- Natural Gas Baseload Competition:Combined-cycle gas turbines in the Permian and Appalachian basins undercut wind dispatch economics during low-demand periods.
Strategic Opportunities
- Floating Offshore Foundation Deployment:California and Oregon lease areas in water depths exceeding 60 meters require floating substructure technology absent from current US supply chains.
- Behind-the-Meter Industrial C&I:Midwest manufacturing facilities with 24/7 load profiles are installing on-site wind coupled with battery storage to hedge volatile wholesale electricity rates.
- Community Wind Cooperative Structures:Rural electric cooperatives in Nebraska and Kansas are aggregating member equity to bypass traditional utility procurement channels.
Industry Challenges
- Specialized Technician Labor Scarcity:Blade repair and high-voltage substation maintenance require certifications that community colleges and trade programs have not scaled to match deployment velocity.
- Permitting Timeline Uncertainty:NEPA environmental review durations for federal lands and avian impact assessments create development schedule risk that financing institutions price into term sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wind Energy Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore Turbines, Onshore Turbines Market Type: Utility-Scale, Distributed Generation, Community Wind, Hybrid Systems End User: Power Utilities, Independent Power Producers, Corporations, Government Agencies Installation Type: Ground-Mounted, Rooftop, Floating, Integrated Projects |
| Companies Covered | NextEra Energy, Invenergy, Clearway Energy Group, Duke Energy Corporation, GE Vernova, Siemens Gamesa Renewable Energy, Orsted, Acciona Energia, Enel Green Power North America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wind Energy Market Evolving Landscape
Technology specialization and procurement model diversification are compressing incumbent advantages and opening entry points for new developer archetypes across the United States wind energy market.
Blade aerodynamics and control systems are fragmenting into platform-specific configurations. GE Vernova, Siemens Gamesa, and Vestas are each deploying distinct pitch control algorithms and segmented blade designs optimized for their respective drivetrain architectures. Utility-scale buyers are increasingly specifying turbine technology within RFPs rather than accepting developer-proposed equipment, forcing independent power producers to align procurement with EPC partner capabilities.
FERC Order 2023 interconnection reforms are mandating cluster study processes and cost allocation transparency for transmission network upgrades. The rule compresses study timelines from five years to three years for projects entering modified queues. Texas ERCOT and Southwest Power Pool regions are seeing the fastest queue reformation as these markets operate outside traditional FERC-jurisdictional cost allocation disputes.
Direct corporate power purchase agreements are displacing traditional utility-sponsored green tariff programs as the dominant procurement channel for large-load C&I buyers. Technology companies with data center expansion plans in Ohio and Virginia are contracting directly with wind developers for 10-15 year fixed-price structures. This shift concentrates creditworthy offtaker demand among a narrow set of investment-grade buyers, compressing developer margin structures for mid-market industrial accounts.
United States Wind Energy Market Segmentation
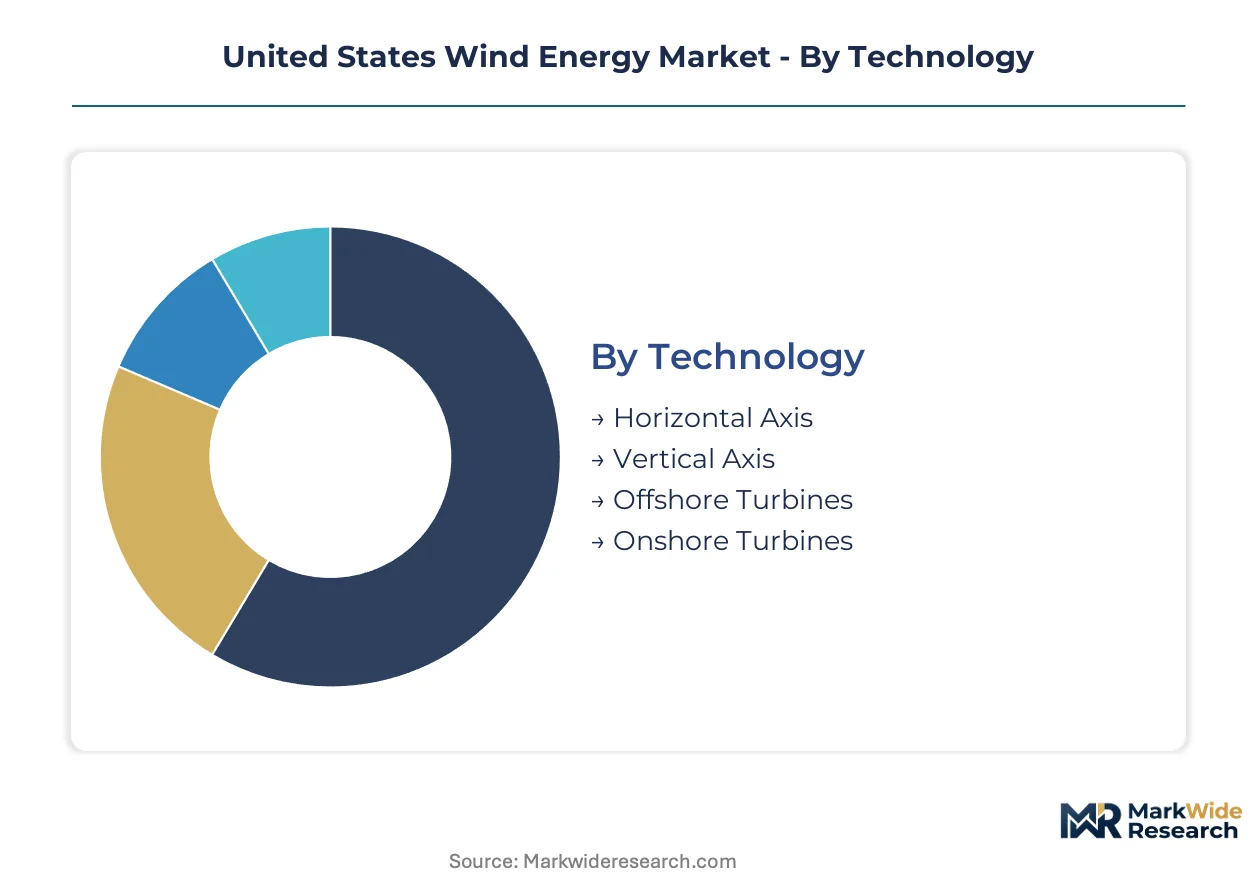
Wind energy segmentation in the United States reflects distinct capital intensity profiles and regulatory exposure across technology platforms. Each category channels investment toward specific offtaker risk profiles and grid interconnection constraints.
Technology:
Domestic manufacturing capacity concentrates on onshore platforms, while offshore turbine supply chains remain import-dependent from European and Asian suppliers.
- Horizontal Axis:Aerodynamic rotor configurations with three blades mounted on upwind nacelles dominate commercial installations. Texas and Iowa project pipelines favor these designs for their proven capacity factors above 45 percent in Great Plains wind corridors.
- Onshore Turbines:Land-based installations rated between 2.5 MW and 3.5 MW with hub heights exceeding 80 meters anchor current deployment. ERCOT and Southwest Power Pool interconnection queues show the densest concentration of these projects seeking grid access.
- Vertical Axis:Darrieus and Savonius configurations serve niche distributed applications where omni-directional wind capture offsets lower efficiency ratings.
- Offshore Turbines:Fixed-bottom and floating foundation designs target California and Oregon lease areas in water depths exceeding 60 meters.
Onshore turbines command the established base. The steepest expansion runs through offshore turbines.
Market Type:
Procurement scale determines financing structures, with utility-scale projects accessing investment-grade capital pools unavailable to smaller configurations.
- Utility-Scale:Grid-connected bulk power facilities exceeding 100 MW capacity serve regional transmission organizations. PJM and MISO territories host the deepest project backlogs despite interconnection queue delays averaging three to five years.
- Corporate Procurement:Direct power purchase agreements with technology and manufacturing buyers displace traditional utility-sponsored green tariffs. Data center operators in Ohio and Virginia contract for 10-15 year fixed-price structures.
- Distributed Generation:Behind-the-meter installations address municipal and rural cooperative demand where transmission access constraints limit centralized development.
- Community Wind:Member-owned cooperative structures in Nebraska and Kansas aggregate local equity to bypass traditional utility procurement channels.
- Hybrid Systems:Wind-plus-battery configurations hedge volatile wholesale electricity rates for Midwest manufacturing facilities with 24/7 load profiles.
Utility-scale installations anchor revenue concentration. Corporate procurement channels are climbing the fastest.
End User:
Creditworthiness tiers segment capital access, with investment-grade offtakers commanding preferential developer margins.
- Power Utilities:Investor-owned and public utilities procure under state renewable portfolio obligations. Texas, California, and New York public utility commissions layer additional siting requirements that shape regional deployment patterns.
- Corporations:Scope 2 emissions targets drive direct contracting with developers. Semiconductor manufacturers and data center operators represent the fastest-growing demand archetype as traditional utility buyers reorganize procurement priorities.
- Independent Power Producers:Non-utility developers compete for interconnection capacity and offtaker contracts without captive ratepayer bases.
- Government Agencies:Federal and state procurement programs leverage Inflation Reduction Act production tax credits to improve project IRRs.
Power utilities retain the installed base. Corporations are gaining share fastest.
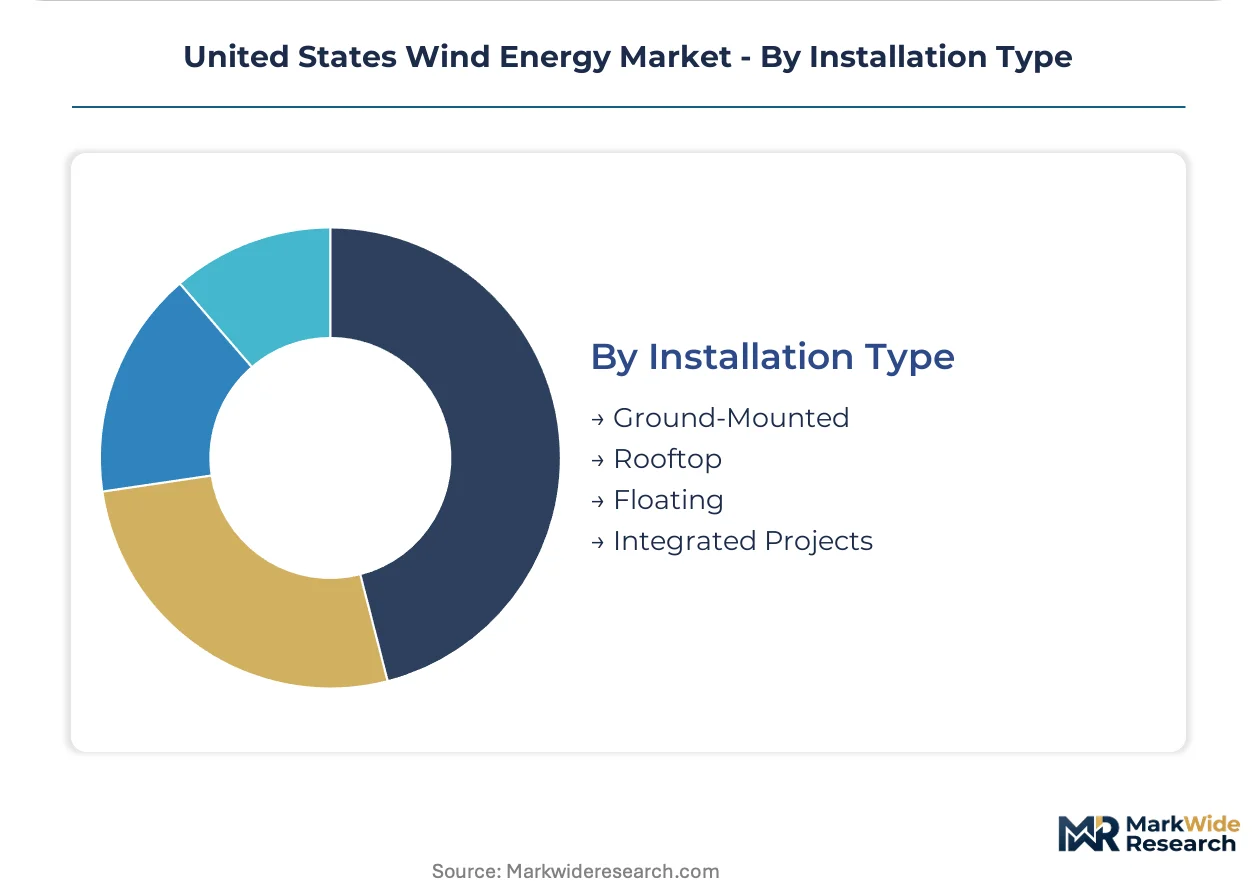
Installation Type:
Foundation engineering and grid integration complexity separate capital requirements across deployment configurations.
- Ground-Mounted:Tubular steel towers anchored in concrete foundations support the vast majority of domestic capacity. Great Plains soil conditions minimize geotechnical costs relative to rocky Appalachian terrain.
- Floating:Semi-submersible and tension-leg platforms enable deployment in water depths exceeding 60 meters. California lease areas require floating substructure technology absent from current US supply chains.
- Rooftop:Small-scale urban installations face height restrictions and wind resource limitations that constrain economic viability.
- Integrated Projects:Co-located generation and storage or industrial load configurations optimize transmission utilization.
Ground-mounted installations dominate the existing fleet. Floating platforms show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbine supply chains and project development pipelines concentrate disproportionately across distinct US sub-regions, each shaped by wind resource profiles, transmission access, and state-level policy frameworks. ERCOT and Southwest Power Pool territories anchor onshore deployment velocity. California and Atlantic seaboard states drive offshore lease activation.
Texas
ERCOT grid independence and abundant Great Plains wind resources sustain the nation's densest project pipeline. The Public Utility Commission of Texas streamlines transmission line approvals under Competitive Renewable Energy Zone protocols. West Texas wind corridors host gigawatt-scale development clusters around Sweetwater and Abilene where capacity factors exceed 45 percent.
Iowa
Rural electric cooperatives and corporate offtakers anchor demand from data center and agricultural processing loads. The Iowa Utilities Board administers renewable portfolio standards that exceed 100 percent clean electricity targets. The state's north-central counties concentrate turbine manufacturing and blade assembly operations near Fort Dodge.
California
Floating offshore foundation requirements and aggressive decarbonization mandates reshape procurement structures. The California Public Utilities Commission enforces resource adequacy obligations that favor long-duration renewable contracts. Humboldt and Morro Bay lease areas require substructure technologies absent from domestic supply chains.
Oklahoma
Southwest Power Pool market participation and low-cost land access attract utility-scale developers. The Oklahoma Corporation Commission regulates interconnection standards for merchant wind facilities. The western Oklahoma Panhandle delivers consistent wind resources that support capacity factors competitive with Texas benchmarks.
New York
Offshore lease auctions and state-led procurement programs activate Atlantic coast development. The New York State Energy Research and Development Authority administers offshore wind solicitations with local content requirements. Long Island and Hudson Valley transmission constraints drive interest in co-located storage configurations.
United States Wind Energy Market Competitive Landscape
Concentration sits with vertically integrated utilities and independent power producers that control development pipelines and interconnection queue positions. The competitive structure tiers across three archetypes: captive utility developers with ratepayer-backed balance sheets, independent power producers reliant on tax equity partnerships, and equipment OEMs competing on turbine platform performance. Dominant competitive moves include backward integration into development origination and strategic alliances with corporate offtakers seeking direct contracting structures.
Within the utility-developer tier, NextEra Energy anchors market presence through its Florida-based regulated utility footprint and unregulated development arm. Invenergy exemplifies the independent power producer archetype with project origination capabilities across multiple ISO territories. GE Vernova occupies a position as the incumbent turbine OEM with manufacturing scale advantages in onshore platform deployment.
| Leading Market Players |
|---|
| NextEra Energy |
| Invenergy |
| Clearway Energy Group |
| Duke Energy Corporation |
| GE Vernova |
| Siemens Gamesa Renewable Energy |
| Orsted |
| Acciona Energia |
| Enel Green Power North America |
| Others |
Value Network & Pricing Analysis
Turbine manufacturing scale at GE Vernova and Vestas anchors price floors across the United States wind energy market, concentrating supply power among three OEMs and compressing margins for independent power producers unable to match volume procurement terms. This scale dynamic channels developer procurement toward long-term offtake contracts that lock in equipment pricing before steel and rare earth volatility feeds through to tower and nacelle costs.
Pricing Analysis
Volume-discount tiering structures separate utility-scale developers procuring 100-plus turbine orders from mid-market independent power producers sourcing smaller project clusters. Pricing stratifies across premium OEM performance guarantees, standard merchant equipment terms, and economy refurbished turbine tiers, with differentiation resting on hub height specifications and capacity factor warranties. Cost compression in the standard tier is intensifying because Chinese steel dumping investigations and Section 201 tariff adjustments are forcing developers to absorb margin pressure. Corporate offtakers with investment-grade credit profiles exhibit the lowest price sensitivity, while rural electric cooperatives negotiating community wind structures face the tightest capital constraints.
Supply Chain Analysis
Inbound logistics costs through the Port of Houston and Long Beach container terminals are elevating landed costs for European and Asian turbine components, with floating foundation substructures for California offshore projects facing 60-day transit windows from Spanish and Danish fabrication yards. Domestic supply concentration rests on Germany, Denmark, and China for permanent magnet rare earths, specialized blade resins, and power converter electronics. Draws from single-source Chinese neodymium processing creates tariff exposure under ongoing Section 301 review expansions. Distribution runs through EPC contractor-led turnkey arrangements that bundle turbine delivery with installation and grid interconnection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with the corporate procurement channel displacing traditional utility buyers, as data center operators and semiconductor manufacturers create niche contracting structures outside standardized green tariff programs.
For Market Incumbents: Shield interconnection queue positions through accelerated cluster study submissions under FERC Order 2023 reforms, while securing captive rare earth supply via offtake agreements with Australian and Canadian mining ventures to offset Chinese export quota volatility. Vertical integration into blade repair technician training programs addresses labor scarcity threatening project completion timelines. For New Entrants and Emerging Players: Differentiate on floating offshore foundation engineering capabilities for California and Oregon lease areas where domestic supply chains remain absent. Target community wind cooperative structures in Nebraska and Kansas aggregating member equity outside traditional utility procurement channels. Lead with direct corporate power purchase agreement origination rather than competing for utility-scale RFP slots dominated by established IPPs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with 10-15 year corporate offtake contracts featuring fixed-price escalators and investment-grade counterparty credit. Long-term viability across the projection horizon favors acquisition targets controlling interconnection queue positions in ERCOT and Southwest Power Pool territories with cleared transmission access. Monitor FERC Order 2023 implementation velocity as the decisive inflection signal for queue reformation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Direct corporate contracting with data center operators in Ohio and Virginia displaces utility green tariffs. |
| Backward Integration into Rare Earth Supply | Captive neodymium sourcing from Australian mining ventures hedges Chinese export quota volatility. |
| Floating Foundation Technology Licensing | European semi-submersible designs unlock California lease areas in water depths exceeding 60 meters. |
| Technician Certification Program Development | Community college partnerships in Iowa and Texas address blade repair labor scarcity constraining deployment velocity. |
| Hybrid Wind-Plus-Storage Configuration | Co-located battery systems hedge ERCOT price volatility for Midwest manufacturing facilities with 24/7 load profiles. |
Research Methodology
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided ongoing calibration across the primary research phase, with secondary validation drawing from EIA generation capacity databases, FERC interconnection queue filings, IEA renewable energy outlooks, and project development tracking services. Bottom-up capacity addition modeling triangulated against top-down investment flow analysis from tax equity partnership disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework segmentation by technology platform, procurement channel, and regional grid type. CAGRs were derived from deployment pipeline velocity adjusted for interconnection queue clearance rates and production tax credit capture efficiency. Forecast inputs incorporated steel price futures, rare earth export quota schedules, and FERC Order 2023 implementation timelines.
Material uncertainties — interconnection reform delays, tariff regime adjustments, and avian impact litigation outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding IRA credit permanence and state renewable portfolio standard trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Global Offshore Wind Market