
 Saddle Plate Market | 2026-2036
Saddle Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Saddle Plate Market Analytics
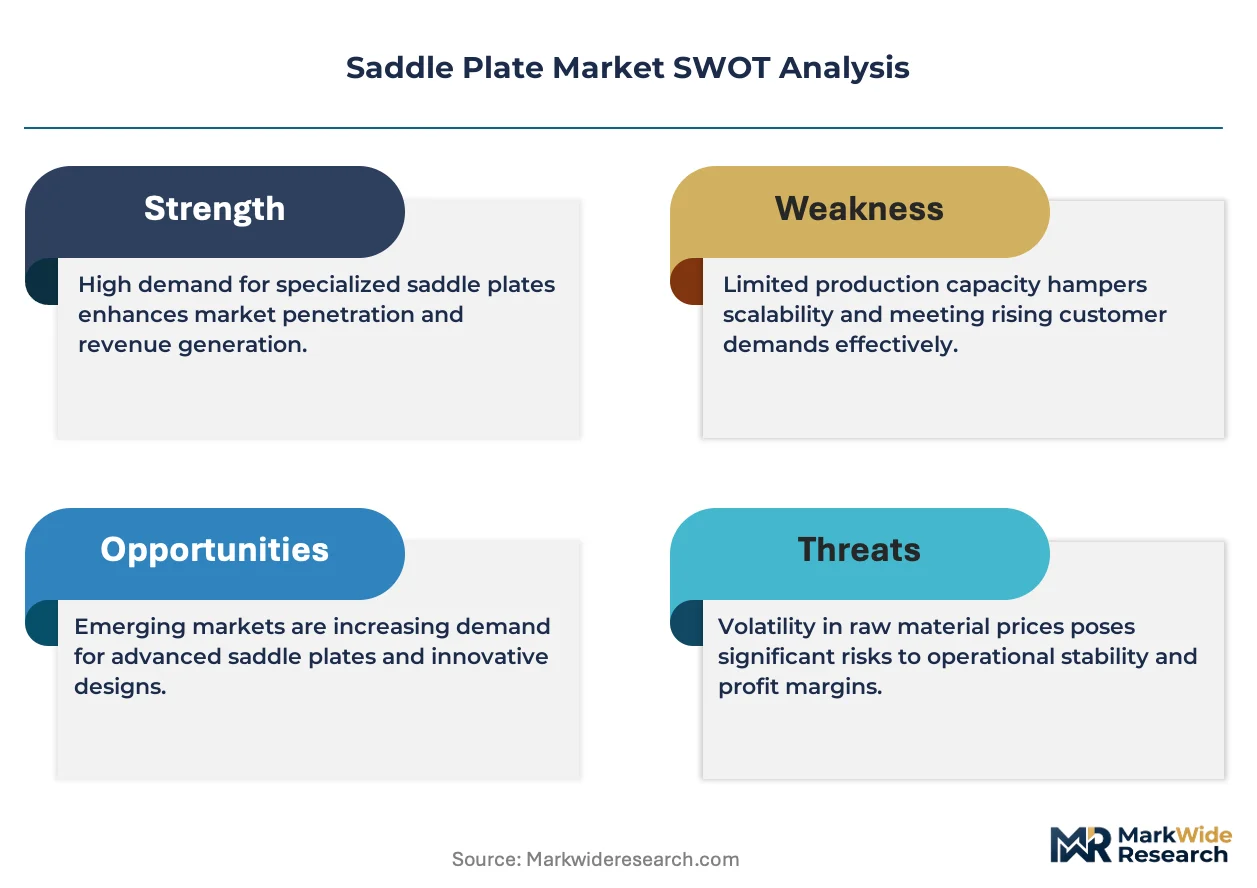
Aftermarket service revenue for saddle plate alignment and refurbishment is fragmenting across regional service networks as OEMs and independent shops compete for maintenance contracts. Losmandy leverages its precision machining heritage to dominate high-end telescope mounting applications. Baader Planetarium sustains brand loyalty through rigorous German engineering standards and specialized astronomy channel control. William Optics differentiates via lightweight carbon fiber composite designs that appeal to mobile observatory operators.
A saddle plate is a structural mounting component, typically machined from aluminum, stainless steel, or titanium alloys with dimensional tolerances of ±0.05 mm, designed to secure cylindrical or irregular loads to support frameworks in industrial, transportation, and astronomical equipment. Its primary function distributes compressive and shear forces across mating surfaces while enabling rapid assembly and positional adjustment. Aluminum fixed saddle plates currently anchor the largest volume pool due to cost efficiency in construction and heavy machinery sectors, while titanium quick-release variants command premium margins in aerospace equipment installation where mass reduction intersects with cyclic loading requirements. Carbon steel structural support applications face margin compression from substitution by corrosion-resistant alloys in marine environments.
The EPA enforces emissions standards on domestic foundries producing carbon steel and aluminum saddle plate castings, raising compliance costs for suppliers serving construction and transportation end users. OSHA mandates govern workplace exposure limits during machining and welding operations, directly affecting production economics for manufacturers operating in the United States. ASTM International and ISO 9001 quality certifications function as de facto market access requirements for aerospace and marine procurement channels. Stakeholders must monitor evolving alloy sustainability certifications and foundry energy intensity standards as procurement criteria harden across European and North American buyer specifications.
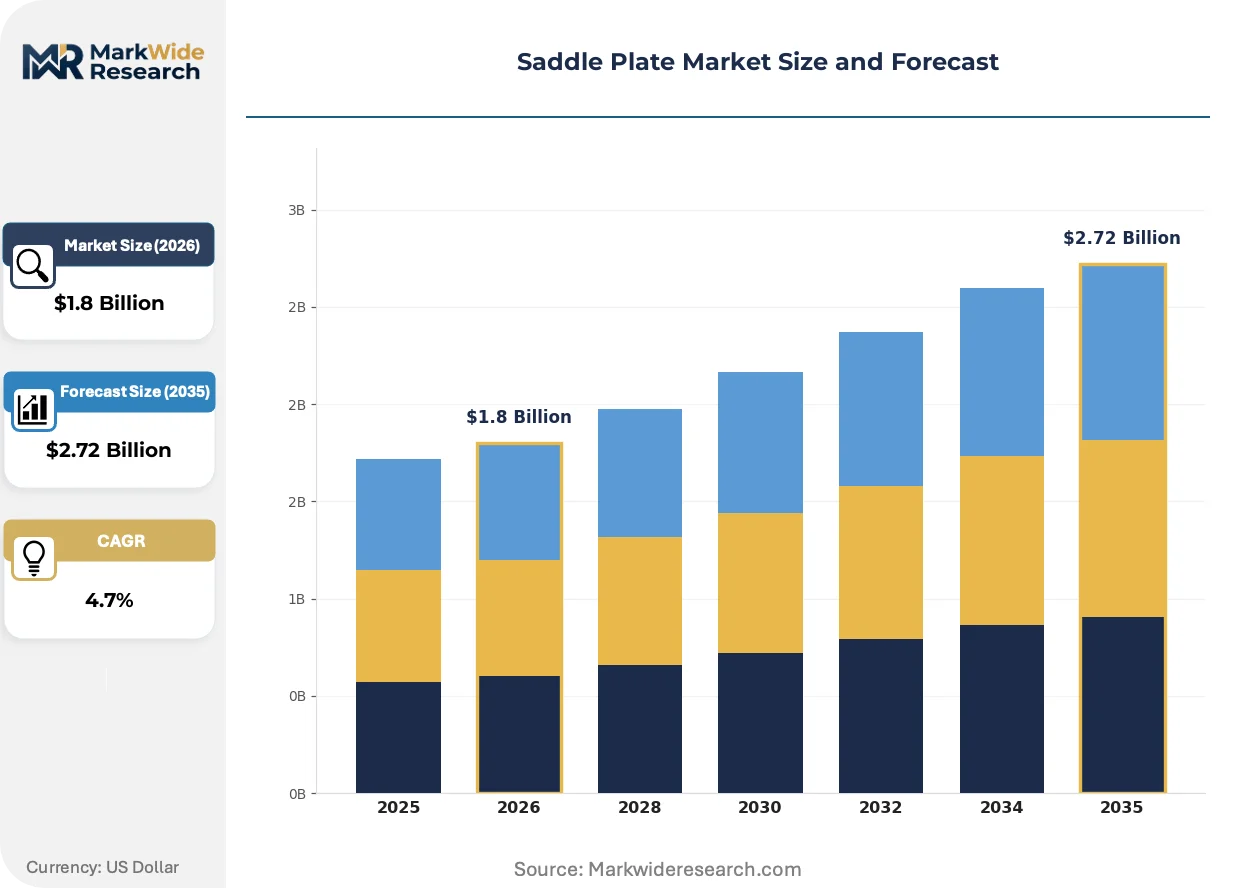
Market Dynamics
The EU Green Deal and REACH compliance requirements are compressing foundry margins while accelerating titanium alloy substitution in aerospace procurement channels. German precision engineering clusters around Munich and Stuttgart are absorbing disproportionate demand concentration as OEMs consolidate supplier bases.
Growth Catalysts
- REACH low-carbon mandates:European foundries are retooling aluminum production lines to meet ECHA emissions thresholds, creating certified supply scarcity that commands premium pricing from construction and marine buyers.
- Titanium airframe integration:Aerospace manufacturers are expanding procurement of titanium saddle plates for cyclic loading applications where mass reduction intersects with fatigue resistance requirements.
- Precision engineering cluster concentration:Demand is concentrating in Germany's Bavaria and Baden-Württemberg regions, where machining heritage and ISO 9001 certification density reduce buyer search costs.
Market Restraints
- Aluminum input cost volatility:Smelter energy intensity requirements under EU carbon border adjustments are transmitting electricity price spikes into raw material cost structures for construction-grade fixed saddle plates.
- Supply concentration risk:Titanium sponge production concentrates in a limited geography, exposing aerospace quick-release variant manufacturers to geopolitical disruption in upstream feedstock channels.
- Carbon steel substitution pressure:Corrosion-resistant alloys are displacing carbon steel structural support applications in marine environments, compressing margins for legacy foundry equipment and welding operations.
Strategic Opportunities
- Aftermarket service unbundling:OEMs and independent shops are competing for saddle plate alignment and refurbishment contracts, fragmenting regional service networks and creating channel arbitrage possibilities.
- Lightweight composite convergence:Carbon fiber composite designs are hybridizing with precision-machined metal interfaces to serve mobile observatory operators requiring transportable mounting systems.
- Alloy sustainability certification:European and North American procurement criteria are hardening around foundry energy intensity standards, rewarding early adopters with preferred supplier status.
Industry Challenges
- Multi-standard certification timelines:Manufacturers must simultaneously navigate ASTM International, ISO 9001, and emerging alloy sustainability certifications to maintain aerospace and marine market access.
- Precision machining skill scarcity:Dimensional tolerances of ±0.05 mm require specialized CNC programming expertise that outpaces vocational training pipeline output in mature manufacturing economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saddle Plate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Aluminum, Titanium, Carbon Steel Product Type: Fixed Saddle Plates, Adjustable Saddle Plates, Quick-Release Saddle Plates, Lightweight Saddle Plates End User: Construction, Automotive, Aerospace, Marine Application: Heavy Machinery, Transportation, Structural Support, Equipment Installation |
| Companies Covered | Altair, Losmandy, Akron, Astro Physics, Geoptik, William Optics, Baader Planetarium, ADM, Ioptron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saddle Plate Market Evolving Landscape
Material science advances are converging with regulatory pressure to reshape competitive positioning across aerospace, marine, and precision instrumentation verticals. Three distinct vectors are currently restructuring how saddle plates are specified, sourced, and serviced.
Additive manufacturing is hybridizing with subtractive finishing operations to produce topology-optimized titanium saddle plates for satellite mounting applications. Spacecraft integrators are adopting these hybrid-process components to reduce launch mass while maintaining structural qualification margins. The approach is compressing traditional forging-to-machining lead times for low-volume, high-complexity aerospace contracts.
EPA emissions enforcement on domestic foundries is raising compliance costs for carbon steel and aluminum casting operations serving construction and transportation end users. OSHA workplace exposure mandates during machining and welding are further affecting production economics for United States-based manufacturers. Aerospace and marine procurement channels are responding by tightening ASTM International and ISO 9001 certification requirements as de facto market access filters.
Buyer concentration among telescope equipment manufacturers is compressing switching cycles and demanding vendor-managed inventory arrangements. Losmandy, Baader Planetarium, and William Optics are unbundling after-sales service from hardware sales, creating recurring revenue streams through alignment and refurbishment contracts. This behavioral shift is most visible in German and North American astronomy equipment distribution channels where precision engineering standards dominate specification processes.
Saddle Plate Market Segmentation
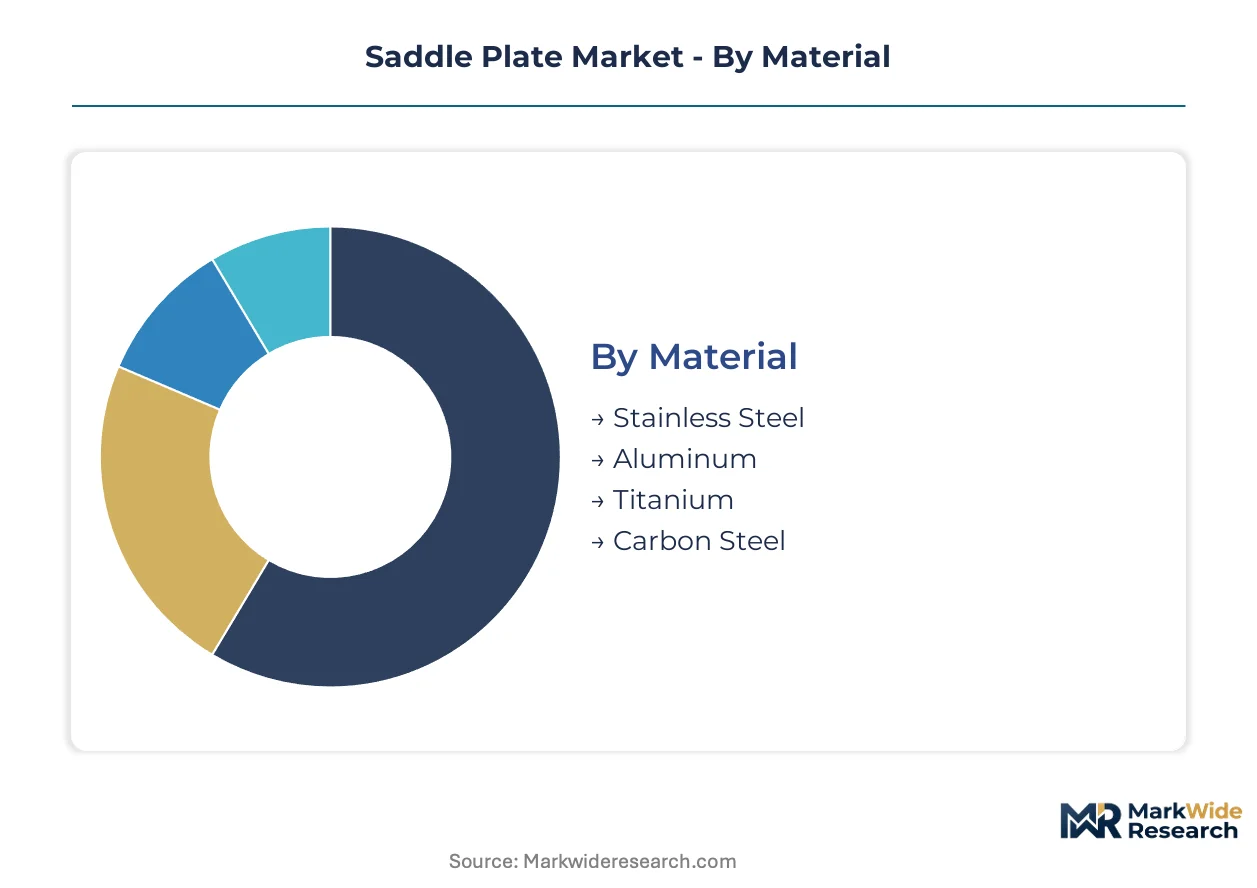
Saddle plate specifications diverge sharply across end-use environments, from marine corrosion resistance to aerospace mass constraints. Procurement criteria harden around material certifications and dimensional tolerances that vary by application severity.
Material:
Cost tier determines raw material selection, with foundry energy intensity and alloy scarcity transmitting directly into procurement budgets.
- Aluminum:Cast and machined grades dominate construction and heavy machinery procurement due to favorable strength-to-weight ratios and established recycling infrastructure. German foundries around Munich and Stuttgart command premium positioning through ISO 9001 certification density and REACH-compliant low-carbon production methods.
- Titanium:Aerospace-grade sponge-derived alloys serve cyclic loading applications where fatigue resistance intersects with mass reduction imperatives. Supply concentrates geographically, exposing quick-release variant manufacturers to upstream geopolitical disruption in sponge production channels.
- Stainless Steel:Marine environments specify molybdenum-enhanced grades for chloride corrosion resistance.
- Carbon Steel:Structural support applications face margin compression from corrosion-resistant alloy substitution in coastal installations.
Aluminum holds installed capacity. Titanium is rotating up the share rankings.
Product Type:
Application severity drives specification divergence between permanent installations and repositionable mounting systems.
- Fixed Saddle Plates:Permanent installations in construction and heavy machinery anchor volume demand through cost-optimized aluminum castings. EPA emissions enforcement on domestic foundries is raising compliance costs for carbon steel and aluminum variants serving transportation end users.
- Quick-Release Saddle Plates:Aerospace equipment installation demands rapid assembly interfaces with maintained structural qualification margins. Satellite integrators specify these variants for launch mass reduction combined with orbital repositioning capability.
- Adjustable Saddle Plates:Precision alignment applications in telescope mounting and optical equipment require micro-positioning capability.
- Lightweight Saddle Plates:Mobile observatory operators specify carbon fiber composite hybrids for transportable mounting systems.
Fixed variants dominate unit economics. Quick-release configurations are climbing the fastest.
End User:
Customer type dictates certification requirements, with aerospace and marine procurement channels hardening quality thresholds.
- Aerospace:Airframe assembly contracts specify titanium saddle plates with ±0.05 mm dimensional tolerances and full material traceability. ASTM International and ISO 9001 certifications function as de facto market access requirements for tier-one supplier qualification.
- Marine:Offshore platforms and vessel construction specify corrosion-resistant alloys under ECHA emissions thresholds and EU Green Deal procurement criteria.
- Construction:Heavy machinery mounting accepts aluminum fixed variants with lower certification burdens.
- Automotive:Transportation equipment installation requires OSHA-compliant machining and welding operations for United States-based supply.
Aerospace commands premium positioning. Marine is gaining share fastest through regulatory-driven alloy substitution.
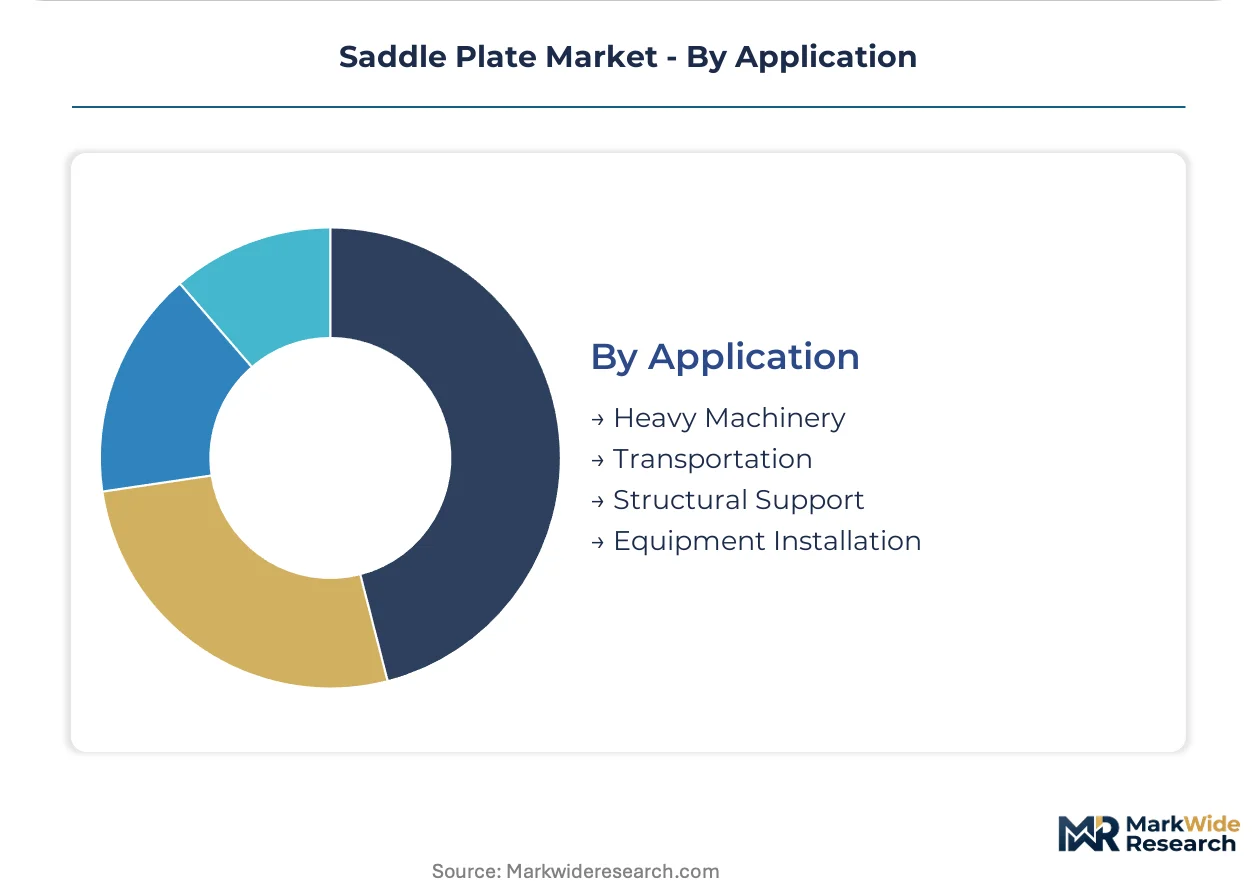
Application:
Volume scale separates commodity structural support from precision equipment installation with specialized tolerance requirements.
- Heavy Machinery:Construction and mining equipment mounting absorbs aluminum fixed saddle plates at scale, with German precision engineering clusters consolidating supplier relationships around Munich and Stuttgart machining heritage.
- Equipment Installation:Telescope mounting and optical instrumentation demands sub-millimeter positional accuracy and vendor-managed inventory arrangements from Losmandy, Baader Planetarium, and William Optics.
- Transportation:Rail and commercial vehicle applications specify fatigue-rated variants under NHTSA and FAA structural guidelines.
- Structural Support:Building and infrastructure projects specify carbon steel or aluminum based on environmental exposure severity.
Heavy machinery anchors volume throughput. Equipment installation is expanding most quickly through precision instrumentation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German precision engineering clusters absorb aerospace-grade titanium demand, while US construction markets prioritize aluminum fixed variants under EPA emissions enforcement. Chinese foundries and Indian heavy machinery sectors anchor volume throughput with cost-optimized specifications.
United States
Aerospace manufacturers in California and Washington State specify titanium saddle plates for airframe assembly with FAA-mandated material traceability. EPA emissions standards on domestic foundries raise compliance costs for carbon steel and aluminum casting operations. Machining heritage concentrates in the Pacific Northwest and Greater Boston corridors where ISO 9001 certification density supports tier-one supplier qualification.
Germany
REACH low-carbon mandates and EU Green Deal procurement criteria compress foundry margins while accelerating certified aluminum supply scarcity. ECHA emissions thresholds drive retooling investments across Bavaria and Baden-Württemberg production facilities. The Munich-Stuttgart precision engineering cluster consolidates OEM supplier relationships through machining heritage and dimensional tolerance expertise.
China
Heavy machinery and construction equipment manufacturers absorb aluminum fixed saddle plates at scale for domestic infrastructure deployment. MEE environmental enforcement and dual carbon goals intensify smelter energy intensity requirements. Production gravity concentrates in Yangtze River Delta foundries serving rail and commercial vehicle OEMs with fatigue-rated variants.
Japan
Optical instrumentation and telescope equipment manufacturers demand sub-millimeter positional accuracy for precision mounting applications. METI industrial standards and JIS certification requirements govern material specifications for domestic procurement channels. Kanto and Kansai manufacturing belts sustain vendor-managed inventory arrangements with astronomy equipment distributors.
India
Construction and mining equipment installation drives aluminum fixed saddle plate demand across heavy machinery sectors. BIS quality certification and PLI scheme incentives for domestic manufacturing reshape supplier qualification criteria. Maharashtra and Gujarat industrial corridors absorb disproportionate volume as OEMs consolidate machining partnerships around Pune and Ahmedabad clusters.
Saddle Plate Market Competitive Landscape
Capability concentration sits with precision-machining specialists; scale advantage sits with diversified metal fabricators. The vendor base separates into three functional tiers: aerospace-certified titanium processors, astronomy equipment specialists, and construction-grade aluminum foundries. Consolidation pressure intensifies as OEMs reduce approved supplier lists to manage certification burden. Dominant competitive moves include backward integration into titanium sponge sourcing and geographic expansion through precision engineering cluster proximity.
Within the astronomy equipment specialist tier, Losmandy and Baader Planetarium exemplify divergent geographic anchoring strategies, while William Optics occupies a position emphasizing lightweight material convergence. These three entities represent how vendor-managed inventory arrangements and after-sales service unbundling reshape competitive positioning in precision instrumentation channels. Their collective presence illustrates the premium-tier fragmentation that contrasts with consolidated aerospace procurement structures.
| Leading Market Players |
|---|
| Altair |
| Losmandy |
| Akron |
| Astro Physics |
| Geoptik |
| William Optics |
| Baader Planetarium |
| ADM |
| Ioptron |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese aluminum smelting compresses spot pricing for construction-grade fixed saddle plates while German foundry undercapacity around Munich and Stuttgart tightens premium positioning for REACH-certified variants. This utilization divergence rewards early certification adopters with pricing power while forcing undifferentiated suppliers into volume-driven margin erosion.
Pricing Analysis
Long-term offtake contracts dominate aerospace titanium procurement, insulating qualified suppliers from aluminum spot volatility while construction buyers face project-based spot exposure. Price differentiation separates ISO 9001-certified precision grades from commodity foundry output, with REACH compliance adding a certification premium. Cost compression in carbon steel structural tiers intensifies as corrosion-resistant alloys displace legacy specifications. Construction and heavy machinery segments exhibit highest price sensitivity; aerospace integrators prioritize qualification over unit cost.
Supply Chain Analysis
Extended payment terms from German precision engineering clusters strain working capital for tier-two machining subcontractors serving the Munich-Stuttgart corridor. Raw material supply draws from Chinese aluminum smelters, Russian and Ukrainian titanium sponge channels, and domestic US carbon steel foundries under EPA emissions enforcement. Single-source vulnerability concentrates in titanium sponge geography, exposing quick-release variant manufacturers to geopolitical disruption. Distribution runs through OEM direct procurement for aerospace, regional distributor networks for construction, and vendor-managed inventory arrangements for telescope equipment specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among aerospace OEMs consolidating approved supplier lists, while astronomy equipment procurement fragments across Losmandy, Baader Planetarium, and William Optics channel competition.
For Market Incumbents: Build certification moats around dual ISO 9001 and emerging alloy sustainability credentials to defend against titanium substitution pressure from additive manufacturing entrants. Deepen backward integration into titanium sponge sourcing to reduce single-feedstock exposure. Expand precision machining capacity in Bavaria and Baden-Württemberg to capture ECHA-compliant supply scarcity premiums. For New Entrants and Emerging Players: Establish a beachhead in carbon fiber composite lightweight saddle plates for mobile observatory operators, where William Optics has proven transportable mounting demand. Target aftermarket alignment and refurbishment services where OEM-independent shop competition fragments regional networks. Pursue direct-to-astronomer digital channels to bypass incumbent distributor control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telescope equipment specialists unbundling after-sales service from hardware sales. Five-to-ten year viability favors precision-machining assets with aerospace qualification heritage over commodity foundry exposure. Monitor EU carbon border adjustment implementation as inflection signal for certified aluminum supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Reduces geopolitical feedstock risk for aerospace quick-release variant manufacturers. |
| REACH-Certified Low-Carbon Aluminum Transition | Captures premium positioning as EU Green Deal procurement criteria harden. |
| Aftermarket Service Unbundling | Creates recurring revenue streams through alignment and refurbishment contracts. |
| Carbon Fiber Composite Hybrid Development | Serves mobile observatory operators requiring transportable precision mounting systems. |
| Precision Engineering Cluster Proximity Expansion | Reduces buyer search costs around Munich and Stuttgart machining heritage. |
Research Methodology
Initial hypotheses were tested against primary input from aerospace procurement managers, foundry operations directors, telescope equipment distributors, and precision machining subcontractors and refined through secondary validation. Sources included customs trade data for aluminum and titanium shipments, EPA emissions enforcement records, ECHA REACH compliance databases, and SEC filings from diversified metal fabricators. Bottom-up volume estimates from end-use application analysis were triangulated against top-down market sizing from raw material flow tracking.
Demand-supply balance modeling across the analysis window incorporated material grade tier, end-use industry severity, product type configuration, and regional regulatory cluster segmentation. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across certified and non-certified supply tiers. Forecast inputs included aerospace airframe assembly schedules, EU carbon border adjustment implementation timelines, and precision machining skill pipeline output from German vocational training institutions.
Stress conditions across titanium sponge supply disruption, aluminum electricity cost spikes, and REACH compliance acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM supplier consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Building Vibration Isolation Market