
 Dry Cooking Sauces Market | 2026-2036
Dry Cooking Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cooking Sauces Market Analysis
Private-label seasoning mix revenue is reshaping margin distribution between branded incumbents and retail-controlled portfolios. McCormick Corporation leverages its spice sourcing infrastructure to sustain premium positioning across North American grocery channels. The Kraft Heinz Company anchors volume through mass-market distribution density in conventional retail. Unilever Group differentiates via its Knorr brand's global formulation consistency and emerging-market penetration.
Dry cooking sauces comprise dehydrated blends of herbs, spices, salt, flavor enhancers, and anti-caking agents, manufactured through spray-drying, freeze-drying, or blending processes to achieve shelf-stable flavor delivery in home and foodservice environments. Seasoning mixes occupy the largest volume position due to their versatility across protein and vegetable applications, while marinades represent the fastest-expanding category as consumers seek simplified protein preparation. Pouch packaging is capturing share from rigid jars in online retail channels, where shipping weight and breakage reduction drive format preference.
The US FDA enforces nutrition labeling standards that directly influence sodium reduction timelines and clean-label claim permissibility for dry sauce products sold in American commerce. The EU's EFSA evaluates health claim substantiation for herb and spice functional benefits, shaping how European manufacturers position turmeric, ginger, and garlic blends. India's FSSAI mandates additive disclosure and maximum residue limits for spice contaminants, creating compliance thresholds for imported and domestic seasoning producers. Stakeholders must monitor regulatory divergence on natural flavor definitions and sodium thresholds as these determine which formulations can cross borders without reformulation costs.
Market Dynamics
Reformulation pressure from sodium disclosure mandates is compressing legacy formulation cycles while triggering R&D redeployment toward clean-label architectures across branded and private-label portfolios.
Growth Catalysts
- Quick-service restaurant chain procurement:Chains are standardizing dry sauce formats to reduce kitchen labor and inventory complexity. This procurement consolidation favors suppliers with scale manufacturing capabilities.
- FSSAI additive disclosure mandates:India's tightening contaminant limits for spice imports are accelerating domestic production investments. Local manufacturers are capturing share from import-dependent competitors.
- Spray-drying efficiency gains:Equipment upgrades in flavor encapsulation are lowering unit costs for mid-tier producers. Technology diffusion is widening the competitive field beyond legacy capital-intensive players.
Market Restraints
- Raw spice price volatility:Turmeric and chili pepper harvest fluctuations in India and Vietnam are creating margin compression for unhedged processors. Price pass-through mechanisms remain underdeveloped in contract structures.
- Single-source supply concentration:Critical anti-caking agents rely on Chinese phosphate processors. Geopolitical friction is elevating procurement risk for European and North American blenders.
- Freeze-drying throughput ceilings:Batch processing constraints limit capacity expansion for premium herb blends. Capital requirements for continuous systems exceed mid-market balance sheet capacity.
Strategic Opportunities
- Urban Indian household penetration:Branded seasoning mix adoption remains below 35 percent in tier-two and tier-three cities. Distribution infrastructure gaps create first-mover advantages for organized players.
- Plant-based protein marinades:Dry rub formats for seitan and textured vegetable protein are underserved. Formulation expertise from meat applications transfers with sensory mapping adjustments.
- Pouch packaging automation:Vertical form-fill-seal equipment adapted for spice density is reducing per-unit packaging costs. E-commerce fulfillment economics favor lightweight flexible formats over glass jars.
Industry Challenges
- Flavor chemist talent scarcity:Reformulation timelines for sodium reduction require specialized expertise in salt replacer synergy. Compensation inflation for experienced professionals is elevating R&D overhead.
- Legacy ERP integration:Batch record systems for spray-drying operations lack API connectivity with modern traceability platforms. Custom middleware development is delaying compliance certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cooking Sauces Market |
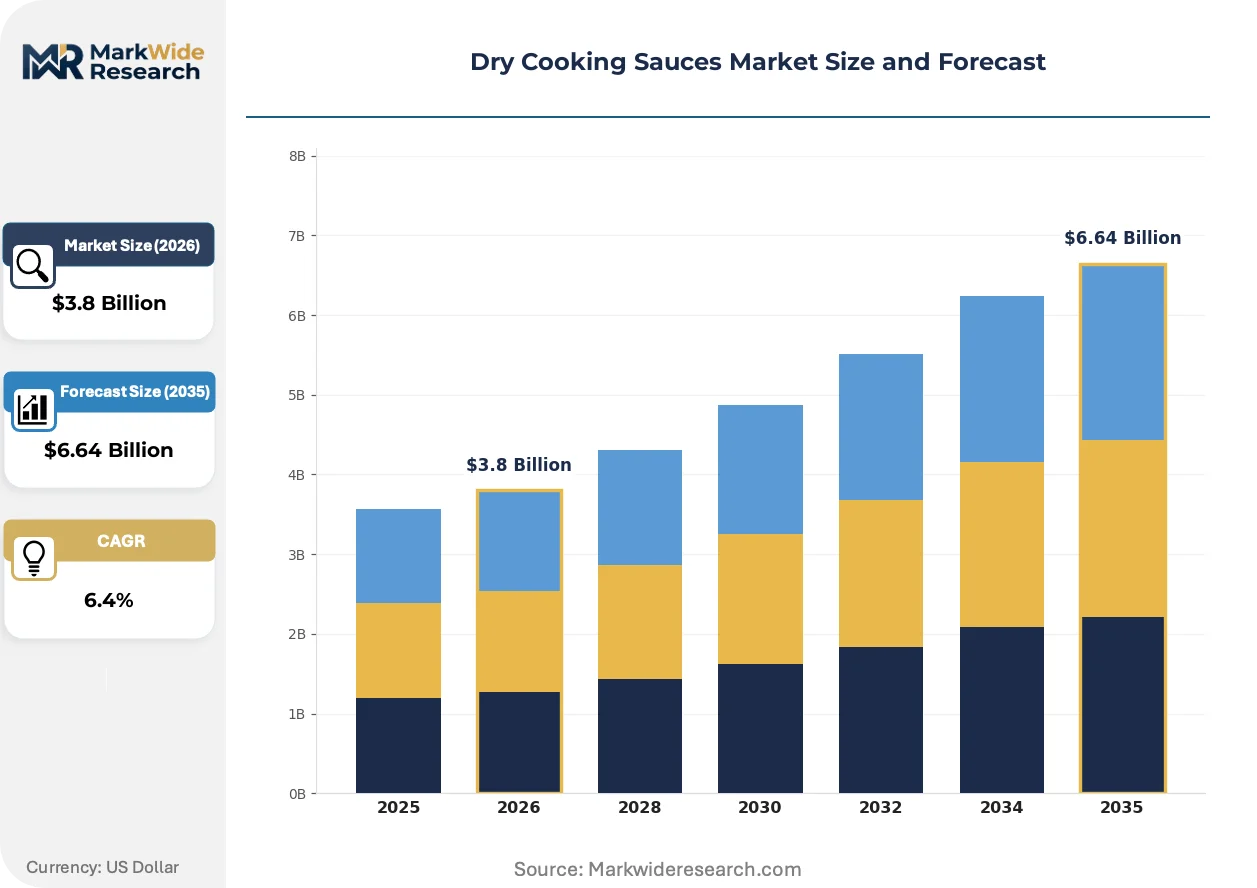
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasoning Mixes, Marinades, Spice Blends, Rubs Ingredient Type: Herbs, Spices, Salt, Flavor Enhancers Packaging Type: Sachets, Jars, Pouches, Bulk Containers Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | McCormick Corporation, The Kraft Heinz Company, Nestlé, Conagra Brands, General Mills, Kikkoman Corporation, Unilever Group, Del Monte, Tasmanian Gourmet Sauce Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cooking Sauces Market Emerging Trajectories
Manufacturing process convergence with packaging automation is collapsing traditional cost structures. Formulation science is advancing alongside regulatory disclosure requirements.
Encapsulation technology is hybridizing spray-dried and freeze-dried matrices to preserve volatile aromatic compounds through extended shelf life. Mid-tier seasoning producers in India and Southeast Asia are adopting hybrid systems at accelerating rates. Equipment suppliers are compressing delivery timelines from 18 months to 8 months for standardized configurations.
EFSA health claim substantiation protocols for herb and spice functional benefits are constraining marketing vocabulary for turmeric and ginger blends. European manufacturers are redirecting positioning toward culinary authenticity rather than physiological claims. Premium private-label suppliers in Germany and France are investing in clinical study partnerships to rebuild compliant claim architectures.
Home cooking enthusiasts are consolidating pantry purchases through subscription replenishment models. Direct-to-consumer channels are displacing conventional grocery discovery for experimental flavor profiles. This behavioral shift concentrates most visibly in US coastal metropolitan markets where meal-kit fatigue is driving autonomous recipe experimentation.
Dry Cooking Sauces Market Segmentation
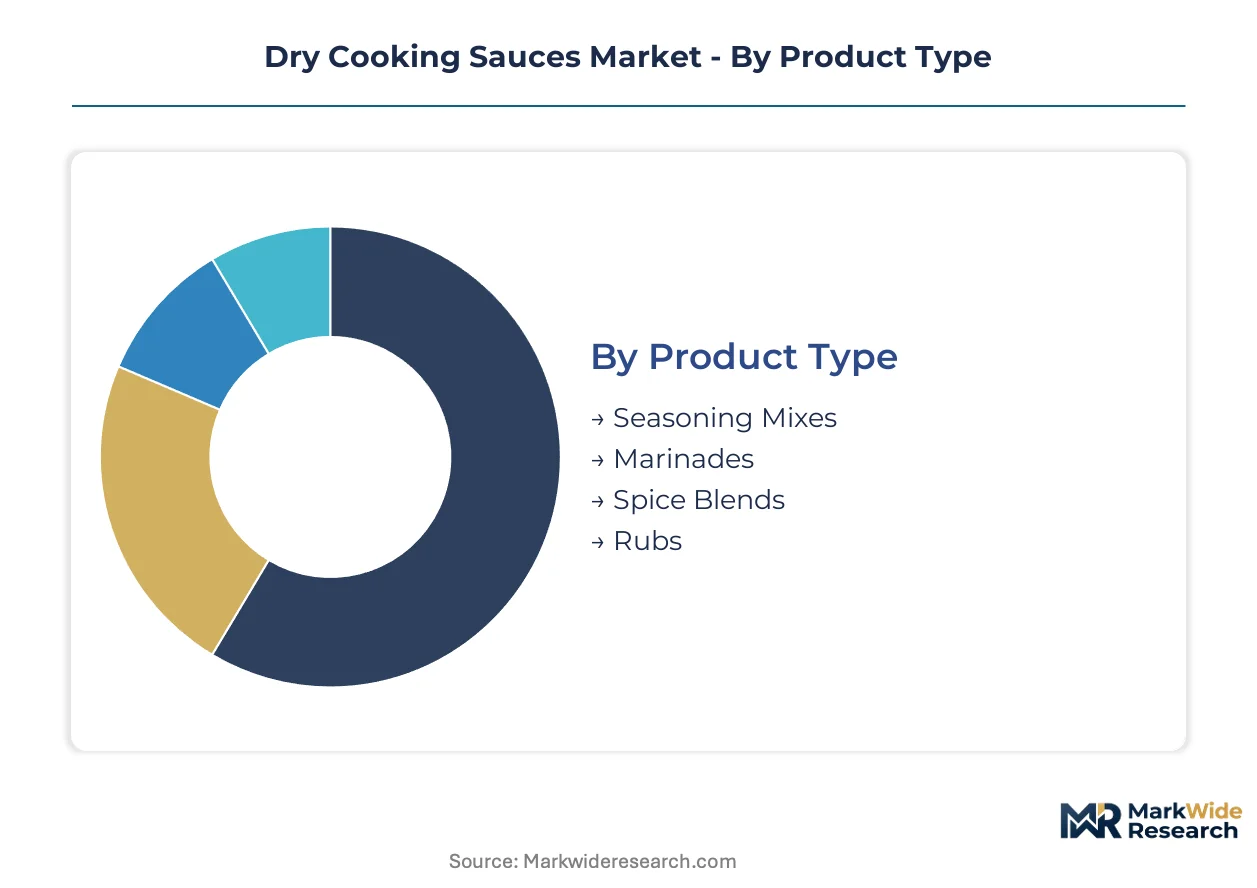
Dry cooking sauces segment across formulation architecture, physical format, and route-to-market dimensions. Each category exhibits distinct velocity profiles that reshape inventory planning and margin capture strategies for blenders and distributors.
Product Type:
Seasoning mixes turn inventory fastest through versatile protein and vegetable applications, while marinades move slower due to specialized use-case constraints.
- Seasoning Mixes:Dehydrated herb-spice-salt matrices manufactured via spray-drying for universal kitchen deployment. Quick-service restaurant chains in the United States standardize these formats to compress kitchen labor costs and simplify procurement.
- Marinades:Acidified or enzyme-active dry blends requiring reconstitution for protein tenderization. Demand concentrates in Indian urban households seeking branded alternatives to homemade preparations, though usage frequency trails seasoning formats.
- Spice Blends:Region-specific formulations (garam masala, Cajun, five-spice) targeting ethnic cuisine authenticity.
- Rubs:Coarse-grind applications for grilling and smoking segments, with seasonal demand spikes in North American barbecue markets.
Seasoning mixes anchor the volume base while marinades gain share at the steepest rate.
Ingredient Type:
Cost tier stratification separates commodity salt and flavor enhancers from premium herb and spice inputs that command formulation expertise premiums.
- Herbs:Freeze-dried leafy materials (oregano, basil, cilantro) preserving volatile aromatic compounds through encapsulated matrix technology. European manufacturers under EFSA jurisdiction redirect positioning toward culinary authenticity as physiological health claims face substantiation barriers.
- Spices:Seed, bark, and root materials (turmeric, cumin, cinnamon) requiring contaminant monitoring under India's FSSAI residue limits. Domestic Indian producers capture share from import-dependent competitors as enforcement tightens.
- Salt:Sodium chloride base material facing reformulation pressure from FDA disclosure mandates in US commerce.
- Flavor Enhancers:Monosodium glutamate, yeast extracts, and nucleotide blends delivering umami amplification at reduced sodium levels.
Spices concentrate the highest margin contribution while salt dominates volume throughput.
Packaging Type:
Weight and breakage economics drive format migration, with lightweight flexible structures displacing rigid glass in e-commerce channels.
- Sachets:Single-serve foil laminates for foodservice portion control and trial-size consumer sampling.
- Jars:Glass containers with moisture-barrier closures retaining share in conventional retail where shelf visibility matters.
- Pouches:Vertical form-fill-seal flexible formats capturing online retail preference through shipping cost reduction and damage elimination. Equipment automation is compressing per-unit packaging costs for mid-tier Indian and Southeast Asian producers.
- Bulk Containers:Industrial-scale fiber drums and supersacks for quick-service restaurant chain procurement and co-manufacturing supply.
Jars retain the installed base while pouches expand most quickly in digital commerce.
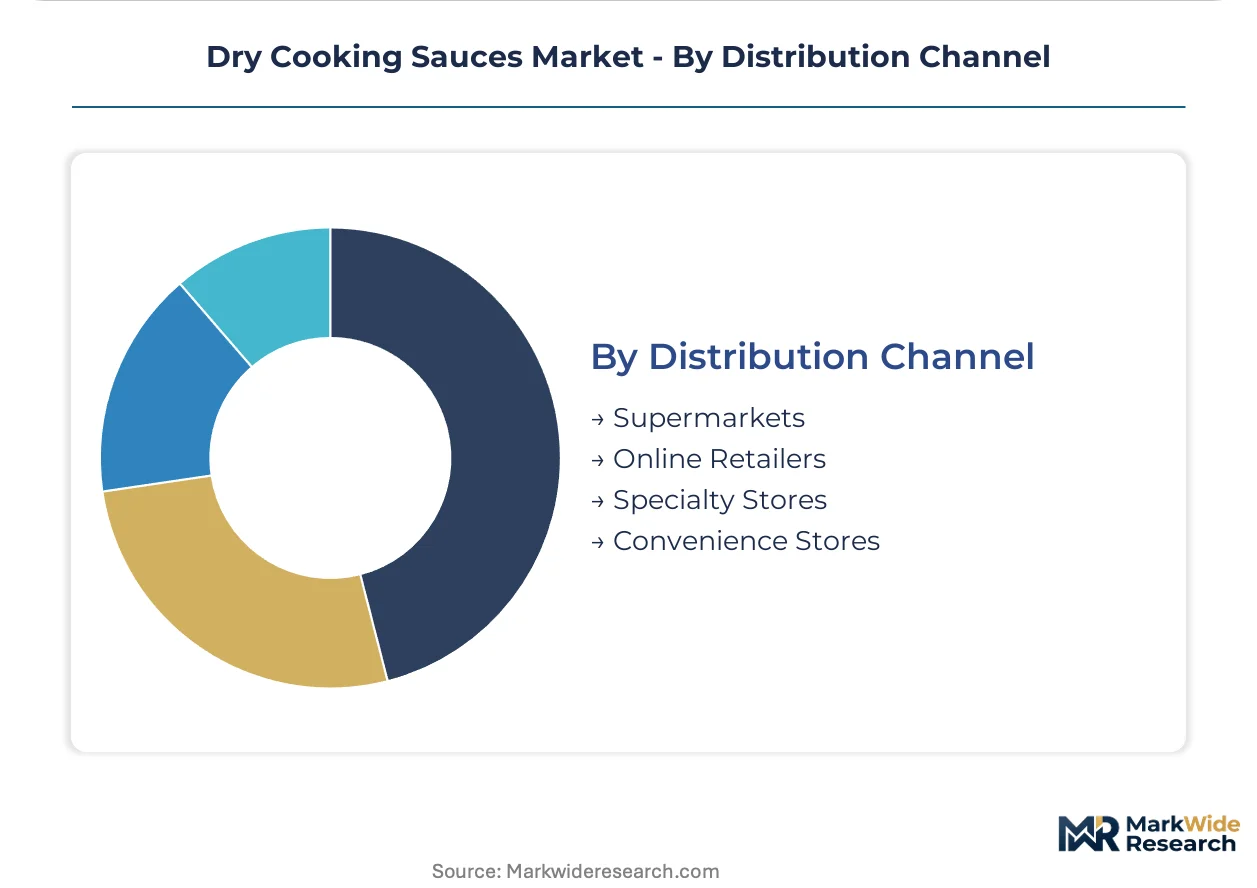
Distribution Channel:
Customer type fragmentation separates high-frequency supermarket replenishment from low-frequency specialty discovery and automated online subscription.
- Supermarkets:Mass-market retail density anchoring volume for Kraft Heinz and similar conventional grocery players.
- Online Retailers:Direct-to-consumer and marketplace platforms displacing conventional discovery for experimental flavor profiles. Subscription replenishment models concentrate in US coastal metropolitan markets where meal-kit fatigue drives autonomous recipe experimentation.
- Specialty Stores:Ethnic grocers and gourmet retailers curating premium and import positioning.
- Convenience Stores:Emergency replenishment and travel-size formats with limited SKU depth.
Supermarkets defend the volume core while online retailers climb the fastest as discovery behavior digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban Indian households deploy dry cooking sauces as branded convenience substitutes for homemade masala preparations, while North American consumers treat seasoning mixes as pantry staples for protein variety rather than cultural cuisine adherence.
United States
Quick-service restaurant chains standardize dry sauce formats to compress kitchen labor costs and simplify procurement workflows. The FDA enforces updated sodium disclosure mandates that compress legacy formulation cycles and trigger R&D redeployment toward clean-label architectures. Chicago and Dallas-Fort Worth anchor procurement consolidation for chain restaurant supply.
India
Tier-two and tier-three cities exhibit branded seasoning mix adoption below 35 percent, creating first-mover advantages for organized players with distribution infrastructure. The FSSAI mandates additive disclosure and maximum residue limits for spice contaminants, accelerating domestic production investments. Mumbai-Pune and Delhi-NCR concentrate spray-drying capacity upgrades for mid-tier producers.
Germany
Premium private-label suppliers invest in clinical study partnerships to rebuild compliant claim architectures for herb and spice functional benefits. The EFSA evaluates health claim substantiation for turmeric, ginger, and garlic blends, constraining marketing vocabulary. Hamburg and Frankfurt anchor equipment automation for pouch packaging formats.
China
Geopolitical friction elevates procurement risk for European and North American blenders dependent on Chinese phosphate processors for critical anti-caking agents. The SAMR monitors natural flavor definitions and additive thresholds that determine cross-border formulation compatibility. Shanghai and Guangzhou concentrate flavor encapsulation technology diffusion.
Vietnam
Raw spice price volatility from turmeric and chili pepper harvest fluctuations creates margin compression for unhedged processors across Southeast Asian supply chains. The country's national food safety authority tightens contaminant monitoring for export-bound spice shipments. Ho Chi Minh City anchors spray-drying equipment upgrades for regional seasoning producers.
Dry Cooking Sauces Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Branded incumbents leverage spice sourcing infrastructure and global formulation consistency to sustain premium positioning, while private-label specialists capture margin through retail-controlled portfolio density. Three archetypes dominate: vertically integrated spice processors, mass-market distribution anchors, and regional formulation specialists. Competitive moves concentrate on pouch packaging automation and sodium-reduction R&D partnerships.
Within the branded seasoning tier, McCormick Corporation and The Kraft Heinz Company exemplify divergent scale strategies. McCormick represents the vertically integrated archetype with captive spice sourcing infrastructure. Kraft Heinz occupies the mass-market distribution anchor position through conventional retail density. Unilever Group sits within the global formulation consistency tier via its Knorr brand's emerging-market penetration architecture.
| Leading Market Players |
|---|
| McCormick Corporation |
| The Kraft Heinz Company |
| Nestlé |
| Conagra Brands |
| General Mills |
| Kikkoman Corporation |
| Unilever Group |
| Del Monte |
| Tasmanian Gourmet Sauce Company |
| Others |
Supply Flow & Price Mechanics
Indian turmeric and Vietnamese chili pepper harvests concentrate raw material sourcing for global seasoning blenders, anchoring margin pools with processors who maintain long-term grower contracts and captive drying infrastructure. This upstream geographic lock-in translates directly to pricing power asymmetries between hedged incumbents and spot-market-dependent mid-tier competitors.
Pricing Analysis
Long-term offtake agreements with Indian spice cooperatives dominate procurement structures for North American and European blenders, insulating against harvest volatility while spot-market exposure persists for smaller Southeast Asian processors. Price differentiation rests on organic certification tiers and FSSAI residue compliance grades, with premium positioning commanding formulation expertise premiums. Cost compression in economy-tier seasoning mixes intensifies as private-label retail contracts squeeze per-unit margins. Quick-service restaurant chains exhibit lowest price sensitivity due to procurement consolidation benefits, while independent foodservice operators remain most exposed to raw material pass-through.
Supply Chain Analysis
Extended payment terms from European and North American blenders to Indian spice processors have become standard, with supply-chain finance facilities emerging to bridge working capital gaps for mid-tier growers. Raw material sourcing draws from India, Vietnam, and Indonesia for turmeric, chili, and black pepper respectively, while anti-caking agent supply rests on Chinese phosphate processor concentration. Single-source vulnerability in critical additive inputs elevates procurement risk amid geopolitical friction. Distribution runs through mass-market retail density for conventional grocery, with direct-to-consumer channels displacing discovery for experimental flavor profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying efficiency gains and pouch packaging automation are collapsing traditional cost structures, while FDA sodium disclosure mandates and FSSAI contaminant enforcement are accelerating reformulation cycles. This technological-regulatory inflection creates asymmetric opportunity for players with R&D scale and regulatory compliance infrastructure.
For Market Incumbents: Build formulation moats through captive spice sourcing infrastructure in Indian growing regions and sodium-reduction R&D partnerships with flavor chemistry specialists. Consolidate procurement relationships with quick-service restaurant chains before mid-tier competitors achieve spray-drying scale. Defend against private-label erosion by anchoring premium positioning through organic certification tiers and clean-label claim architectures. For New Entrants and Emerging Players: Build out plant-based protein marinade formulations for underserved seitan and textured vegetable protein applications, transferring sensory mapping expertise from conventional meat rubs. Target tier-two and tier-three Indian cities where branded seasoning mix penetration remains below thirty-five percent and distribution infrastructure gaps favor first-mover investment. Pursue vertical form-fill-seal equipment partnerships to compress per-unit packaging costs against jar-dependent incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated spice processors with Indian growing-region presence and established FSSAI compliance infrastructure, positioned for five-to-ten-year horizon consolidation. Monitor spray-drying equipment delivery timeline compression as inflection signal for mid-tier competitive field expansion. Watch for clinical study partnership announcements from European private-label suppliers seeking EFSA-compliant health claim repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Reduction R&D Partnership | McCormick and Kraft Heinz reformulation timelines compress legacy formulation cycles under FDA disclosure mandates. |
| Pouch Packaging Automation | Vertical form-fill-seal equipment upgrades in India reduce per-unit costs and displace glass jar formats in e-commerce. |
| Domestic Indian Production Investment | FSSAI contaminant enforcement accelerates local manufacturing capture from import-dependent seasoning competitors. |
| Plant-Based Protein Marinade Development | Formulation expertise from meat applications transfers to seitan and TVP with sensory mapping adjustments. |
| Clinical Study Partnership for EFSA Claims | German and French private-label suppliers rebuild compliant turmeric and ginger positioning under health claim constraints. |
Methodological Framework
Cross-validation between primary interviews with seasoning blend plant managers, quick-service restaurant procurement directors, and Indian spice cooperative representatives and secondary validation through FSSAI additive disclosure filings, FDA sodium labeling guidance documents, and customs trade data anchors the qualitative findings. Bottom-up triangulation across spray-drying equipment supplier disclosures and top-down reconciliation with retail channel shipment data ensures dimensional consistency.
Calibration against historical volume trajectories in seasoning mix and marinade categories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, ingredient cost tier stratification, packaging format weight economics, and distribution channel velocity profiles. CAGRs derive from regression analysis against quick-service restaurant chain procurement expansion and urban Indian household branded adoption curves, with spray-drying capacity utilization and pouch packaging automation diffusion as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by private-label retail-controlled portfolios or accelerated sodium-reduction timelines by reformulation leaders would shift outcomes. Macroeconomic deviation in raw spice harvests, regulatory divergence on natural flavor definitions, or technological breakthrough in continuous freeze-drying systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Hot Sauce Powder Market