
 Barbeque Sauce Market | 2026-2036
Barbeque Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Barbeque Sauce Market Outlook
Flavor-subscription and direct-to-consumer replenishment programs is consolidating recurring revenue streams around pantry staples previously sold through intermittent retail trips. The Kraft Heinz Company leverages its retail shelf-space dominance to sustain volume leadership across mass-market channels. Sweet Baby Ray's anchors its position through sports-venue and foodservice partnerships that bypass traditional grocery competition. McCormick & Company differentiates via premium spice-forward formulations that command higher per-unit margins in specialty retail.
Barbeque sauce comprises a viscous condiment typically manufactured through reduction of tomato paste, vinegar, sweeteners, and smoke flavoring, with pH levels controlled below 4.6 for shelf stability and thermal processing ensuring commercial sterility. Its primary purpose centers on flavor enhancement of grilled, smoked, or roasted proteins across foodservice and home preparation settings. Tomato-based formulations occupy the largest volume share due to consumer familiarity and versatile application across protein types. Pouch packaging represents the fastest-growing structural segment, driven by foodservice portion-control requirements and reduced shipping weight relative to glass containers.
The FDA governs acidified food regulations and nutrition labeling disclosures that directly impact ingredient declarations and serving-size definitions for barbeque sauce products. The USDA's Food Safety and Inspection Service coordinates with FDA on dual-jurisdiction products containing meat flavorings, creating compliance complexity for cross-category formulations. Stakeholders must monitor evolving clean-label enforcement thresholds and state-level sodium warning requirements that could trigger regional formulation divergence.
Market Dynamics
Flavor-subscription models and direct-to-consumer replenishment programs are consolidating recurring revenue streams around pantry staples previously sold through intermittent retail trips, compressing traditional grocery channel dependence.
Growth Catalysts
- Quick-service restaurant expansion:Fast-casual dining chains are broadening sauce customization programs, creating dedicated SKU demand that bypasses conventional retail shelf competition.
- FDA sodium reduction guidelines:Reformulation timelines pressured by updated Nutrition Facts labeling requirements are accelerating clean-label innovation cycles among mid-tier manufacturers.
- Southern United States demand concentration:Regional flavor preferences sustain premium pricing for craft and small-batch varieties, anchoring margin expansion in heritage formulations.
Market Restraints
- Tomato paste input volatility:Concentrated tomato supply disruptions in California processing regions create formulation cost instability for volume producers.
- Glass container shipping weight:Traditional packaging formats impose freight cost penalties that disadvantage long-haul distribution to non-core markets.
- Dual-jurisdiction compliance friction:USDA Food Safety and Inspection Service coordination with FDA on meat-flavored formulations creates regulatory complexity for cross-category product development.
Strategic Opportunities
- Pouch packaging adoption:Foodservice portion-control requirements and reduced shipping weight relative to glass containers represent structural share capture potential.
- State-level sodium warning thresholds:Evolving clean-label enforcement creates first-mover positioning for reformulated low-sodium heritage recipes in preemptive compliance markets.
- Spice-forward premium positioning:Specialty retail channels reward higher per-unit margin formulations that emphasize artisanal ingredient provenance over mass-market familiarity.
Industry Challenges
- pH control technical specialization:Acidified food processing expertise required for shelf-stable formulations below 4.6 pH constrains contract manufacturing capacity expansion.
- Thermal processing equipment capex:Commercial sterility validation systems demand significant capital deployment that fragments production scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barbeque Sauce Market |
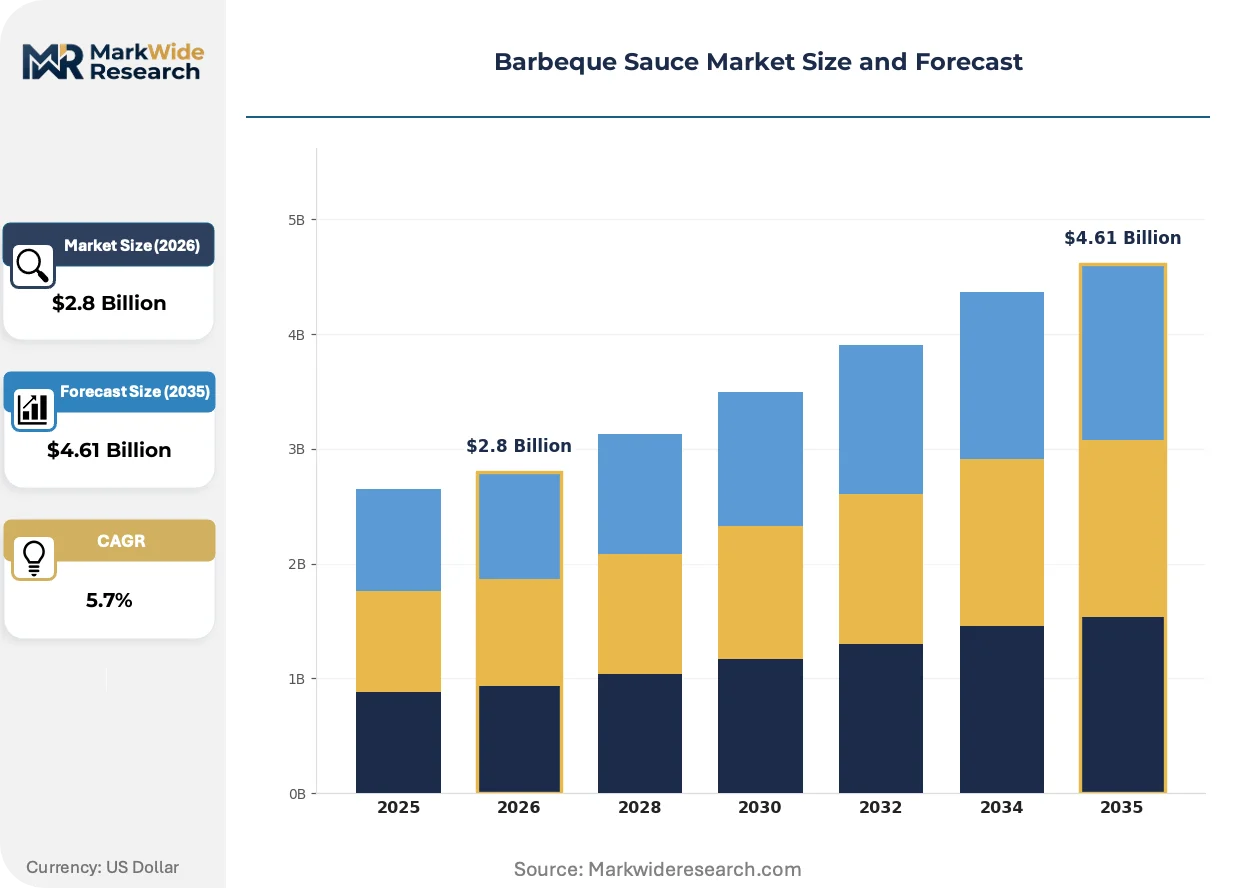
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomato-Based, Vinegar-Based, Mustard-Based, Fruit-Based Flavor Profile: Sweet, Smoky, Spicy, Tangy Packaging Type: Bottles, Jars, Pouches, Cans Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | The Kraft Heinz Company, Conagra Brands, Sweet Baby Ray's, KC Masterpiece, Stubb's, Renfro Foods, McCormick & Company, B&G Foods, Stonewall Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barbeque Sauce Market Strategic Shifts
Processing technology and packaging format evolution are compressing traditional supply chain configurations while regulatory disclosure requirements reshape competitive positioning around transparency claims.
High-pressure processing (HPP) technology is modularizing clean-label production pathways by eliminating thermal degradation of volatile spice compounds. Mid-size regional manufacturers are adopting HPP lines at accelerating cadence to support refrigerated premium SKUs without artificial preservatives. This capability expansion is modularizing the barrier between shelf-stable mass market and chilled premium segments.
REACH chemical disclosure requirements in Europe are extending supply chain visibility mandates to natural smoke flavoring sourcing, forcing reformulation documentation for imported tomato-based sauces. Manufacturers serving EU markets must now validate pyroligneous acid and wood-smoke extract provenance through certified supplier audits. The compliance burden falls most heavily on private-label exporters lacking captive flavoring production.
Pantry replenishment automation through smart-home inventory systems is redirecting purchase initiation from retail browsing to algorithmic consumption tracking. Subscription-integrated brands are capturing household-level preference data that grocery loyalty programs cannot replicate. This behavioral shift concentrates most visibly in suburban US markets with above-average connected-appliance penetration.
Barbeque Sauce Market Segmentation
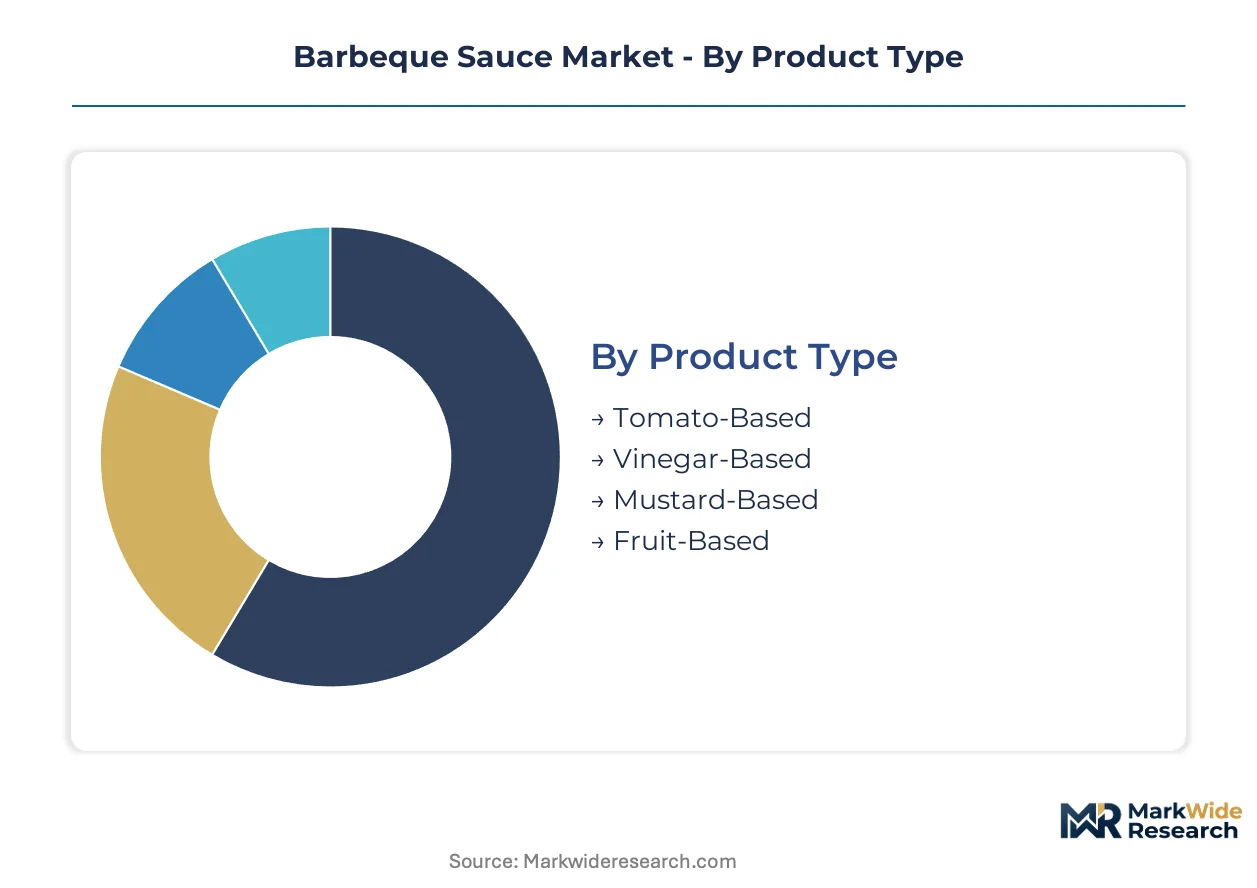
Barbeque sauce segmentation reveals distinct technical and commercial boundaries between shelf-stable mass formulations and refrigerated premium alternatives. Category boundaries increasingly blur as high-pressure processing enables cleaner labels across traditional format divides.
Product Type:
Integration depth varies sharply: tomato-based formulations function as standalone pantry staples with universal protein pairing, while fruit-based variants embed within specialty retail and foodservice limited-time offerings.
- Tomato-Based:Reduction of tomato paste, vinegar, and sweeteners with pH controlled below 4.6 for shelf stability. Southern United States households sustain premium pricing for heritage recipes with molasses-forward profiles. FDA acidified food regulations govern thermal processing requirements for commercial sterility.
- Vinegar-Based:Eastern North Carolina-style formulations emphasizing apple cider or white vinegar reduction with minimal sweetener. Regional QSR chains in the Carolinas and Virginia embed these as signature condiments, creating dedicated SKU demand outside grocery competition.
- Mustard-Based:South Carolina heritage style combining yellow mustard base with vinegar and brown sugar. Concentrated demand in coastal Georgia and South Carolina foodservice accounts.
- Fruit-Based:Peach, apple, or berry purees integrated for seasonal limited releases. Chains like fast-casual smokehouses in Texas and Kansas deploy these for menu differentiation.
Tomato-based leads volumes today; fruit-based is gaining share fastest.
Flavor Profile:
Cost tier stratification separates commodity sweet profiles from premium spice-forward positioning commanding per-unit margin premiums.
- Sweet:High-fructose corn syrup or molasses-dominant formulations targeting mass-market family households. Supermarket channel concentration in suburban Midwest and Southeast markets.
- Smoky:Natural hickory or mesquite smoke flavoring, with REACH chemical disclosure requirements in Europe forcing supplier audit documentation for pyroligneous acid provenance.
- Spicy:Capsicum-derived heat levels calibrated through Scoville-targeted pepper mash addition. Fastest-climbing trajectory in Texas, New Mexico, and Arizona foodservice customization programs.
- Tangy:Elevated vinegar and citrus notes targeting health-positioned consumers. Sodium-reduced formulations align with FDA updated labeling requirements.
Sweet dominates shelf turnover; spicy climbs the fastest in foodservice velocity.
Packaging Type:
Volume economics and shipping weight create divergent supply chain configurations between glass-heavy retail and pouch-optimized foodservice.
- Bottles:PET and HDPE containers dominating supermarket shelf presence with squeeze-dispensing functionality. California and Florida manufacturing clusters supply national retail networks.
- Jars:Glass containers preserving heritage positioning for premium small-batch producers. Freight cost penalties disadvantage long-haul distribution to non-core markets.
- Pouches:Flexible film structures reducing shipping weight and enabling precise portion control. QSR back-of-house adoption accelerating in national fast-casual chains.
- Cans:Steel containers for institutional foodservice and military procurement specifications. USDA Food Safety and Inspection Service coordination applies to meat-flavored canned variants.
Bottles anchor retail volumes; pouches show steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates pantry replenishment automation from impulse-driven convenience purchasing.
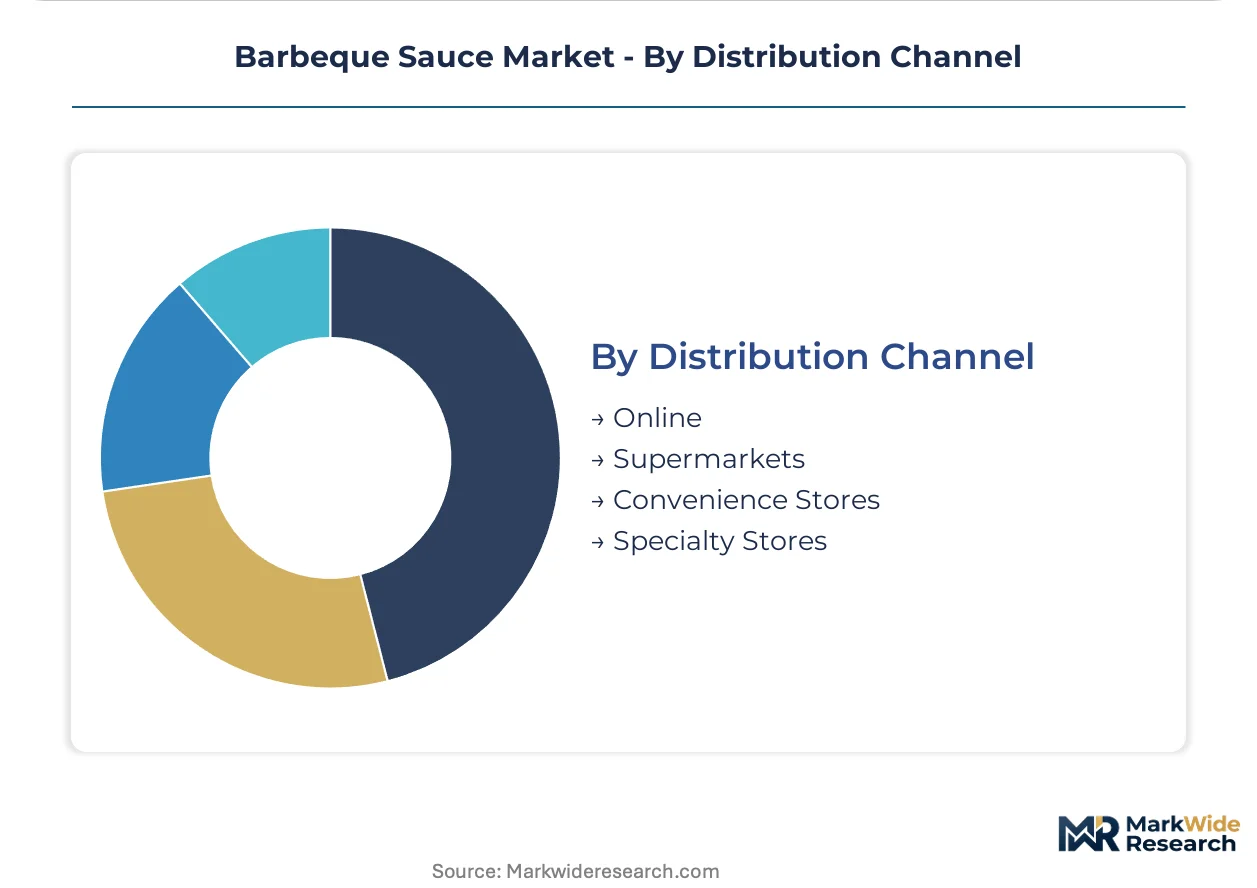
- Online:Direct-to-consumer subscription models capturing household preference data unavailable to grocery loyalty programs. Smart-home inventory integration concentrates in suburban markets with above-average connected-appliance penetration.
- Supermarkets:Shelf-space competition dominated by Kraft Heinz retail network leverage. Mass-market velocity depends on end-cap placement and seasonal grilling promotions.
- Convenience Stores:Single-serve and travel-size formats for immediate consumption. Limited SKU depth favors sweet and smoky profiles with broad appeal.
- Specialty Stores:Spice-forward artisanal formulations with ingredient provenance transparency. McCormick premium positioning commands higher per-unit margins in this channel.
Supermarkets retain volume leadership; online is expanding most quickly through subscription consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States demonstrate divergent demand profiles for barbeque sauce, with German consumers gravitating toward premium spice-forward formulations while American households sustain volume leadership through mass-market heritage brands.
United States
Southern states anchor domestic demand through molasses-forward heritage recipes and craft small-batch production. The FDA's updated Nutrition Facts labeling requirements and sodium reduction guidelines pressure reformulation timelines across mid-tier manufacturers. California's Central Valley tomato processing clusters supply concentrated paste inputs to national volume producers.
Germany
German consumers drive premium-tier demand for artisanal formulations with transparent ingredient provenance. ECHA's REACH chemical disclosure requirements extend supply chain visibility mandates to natural smoke flavoring sourcing, forcing certified supplier audits. Bavaria's specialty food retail networks concentrate distribution for spice-forward imported and domestic variants.
United Kingdom
British foodservice channels expand sauce customization programs through fast-casual dining chain partnerships. The Food Standards Agency coordinates with EU-retained REACH regulations on pyroligneous acid documentation for wood-smoke extracts. Greater London's restaurant density supports premium SKU velocity for limited-release fruit-based formulations.
Canada
Canadian households show above-average adoption of smart-home pantry replenishment systems in suburban Ontario and British Columbia markets. Health Canada's updated nutrition labeling regulations align with FDA sodium disclosure thresholds, streamlining North American formulation strategies. Toronto's foodservice distribution hubs facilitate cross-border supply chain integration for pouch-packaged institutional formats.
Australia
Australian consumers demonstrate growing preference for tangy vinegar-forward profiles targeting health-positioned segments. The Therapeutic Goods Administration's parallel jurisdiction with Food Standards Australia New Zealand creates compliance complexity for functional ingredient claims. Sydney and Melbourne's fast-casual smokehouse chains drive seasonal limited-release demand for fruit-based variants.
Barbeque Sauce Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage consumer packaged goods names dominating supermarket shelf space while regional craft producers capture specialty retail premiums. The vendor base concentrates around three strategic archetypes: diversified condiment conglomerates leveraging retail network density, heritage craft specialists anchored in regional flavor traditions, and private-label contract manufacturers serving foodservice institutional accounts. Competitive moves center on pouch packaging capacity expansion for QSR back-of-house adoption and direct-to-consumer subscription platform development to bypass traditional grocery intermediation.
Within the heritage craft tier, Sweet Baby Ray's and Stubb's exemplify positioning built on regional authenticity and sports-venue foodservice penetration rather than retail shelf competition. McCormick & Company occupies the spice-forward premium archetype, commanding higher per-unit margins through specialty retail channel concentration. These three names represent divergent competitive vectors—mass-market accessibility, regional heritage credibility, and artisanal ingredient provenance—without direct segment overlap.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands |
| Sweet Baby Ray's |
| KC Masterpiece |
| Stubb's |
| Renfro Foods |
| McCormick & Company |
| B&G Foods |
| Stonewall Kitchen |
| Others |
Value Chain & Pricing Dynamics
Premium-molasses heritage formulations command shelf-stable price premiums three to four times above commodity sweet profiles, with that tier divergence manifesting in California tomato paste sourcing for mass producers versus small-batch vinegar reduction in Carolinas craft kitchens. FDA acidified food compliance costs and glass container freight penalties further stratify supply chain configurations between national retail networks and regional foodservice penetration.
Pricing Analysis
Capacity additions in pouch packaging lines are reshaping price floors for foodservice institutional accounts as reduced shipping weight offsets glass freight penalties. Three-tier pricing structure across premium craft, standard heritage, and economy private-label levels separates McCormick spice-forward positioning from Kraft Heinz mass-market velocity. Cost compression in sweet tomato-based tiers intensifies because California processing region input volatility feeds through to formulation economics. Quick-service restaurant procurement teams show highest price sensitivity, while specialty retail buyers absorb premium per-unit margins for artisanal provenance.
Supply Chain Analysis
Single-source vulnerability sits with California Central Valley tomato paste concentration, where drought and processing capacity constraints ripple through national volume producer cost structures. Raw material dependencies draw from Mexican vinegar imports, Chinese natural smoke flavoring extracts, and domestic molasses supply. Tariff exposure on imported glass containers creates formulation packaging trade-offs for long-haul distribution. Distribution runs through California-Florida manufacturing clusters supplying supermarket retail, with emerging pouch capacity in Texas and Georgia serving QSR back-of-house adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage positioning favors pouch packaging investment in Texas and Georgia to exploit lower freight costs versus California glass-heavy production, leveraging FDA sodium disclosure alignment with Health Canada thresholds for streamlined North American formulation strategies.
For Market Incumbents: Anticipate pouch packaging capacity expansion by fast-casual chain captive suppliers threatening foodservice institutional share. Defend position by deepening backward integration into California tomato paste processing and accelerating clean-label reformulation ahead of state-level sodium warning thresholds. Channel control through direct-to-consumer subscription platforms offers preference data capture unavailable to grocery intermediaries. For New Entrants and Emerging Players: A mid-tier price-point gap between Stubb's heritage positioning and private-label economy tiers offers white-space entry through spice-forward formulations targeting specialty retail velocity. The most penetrable segment sits in fruit-based limited releases for fast-casual smokehouse seasonal menus. Go-to-market execution should leverage smart-home pantry replenishment integration in suburban Ontario and British Columbia markets with above-average connected-appliance penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where pH control technical specialization and thermal processing equipment capex fragment production scale economics. Long-term viability favors acquisition targets with HPP-enabled refrigerated premium capability bridging shelf-stable mass and chilled artisanal segments. The signal to watch is QSR back-of-house pouch adoption rates as inflection indicator for structural packaging shift.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Packaging Capacity Expansion | Reduces freight weight penalties and captures QSR portion-control demand away from glass. |
| Direct-to-Consumer Subscription Launch | Circumvents Kraft Heinz retail shelf-space dominance through algorithmic replenishment data capture. |
| Clean-Label Reformulation Investment | Preempts FDA sodium reduction enforcement and state-level warning threshold divergence. |
| Heritage Recipe Premium Tier Introduction | Commands molasses-forward pricing premiums in Southern United States regional markets. |
| High-Pressure Processing Technology Adoption | Enables spice-forward refrigerated SKUs without artificial preservative degradation. |
Study Parameters
Multiple input streams — executive interviews with condiment brand managers, procurement leads at national QSR chains, and specialty retail category buyers, alongside Nielsen retail audit data, FDA acidified food filing records, and customs trade documentation — were reconciled through bottom-up volume modeling and top-down value triangulation across the analysis window.
Data-stream reconciliation applied segmentation dimensions spanning product type, flavor profile, packaging format, and distribution channel to derive expansion trajectories throughout the forecast period. CAGRs emerged from historical velocity patterns projected against quick-service restaurant expansion cadence and smart-home appliance penetration curves. Industry-specific inputs incorporated California tomato processing capacity utilization and REACH chemical disclosure compliance cost estimates for EU-bound exports.
Caveats apply where California drought recurrence, ECHA smoke flavoring audit enforcement, or QSR menu customization program cancellation could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Culinary Sauces Market