
 Seitan Powder Market | 2026-2036
Seitan Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Seitan Powder Market Analytics
USDA Organic certification is bifurcating the competitive landscape for seitan powder suppliers, separating qualified producers from commodity-grade entrants. Kikkoman Corporation leverages its fermentation expertise to sustain premium positioning in Asian and North American channels. Bob's Red Mill anchors the natural-foods segment through direct-to-retailer relationships and heritage brand recognition. Archer Daniels Midland Company competes on manufacturing scale, operating integrated wheat-processing infrastructure that controls input costs across multiple protein categories.
Seitan powder consists of dried vital wheat gluten, typically containing 75-80% protein by weight, produced through washing wheat flour dough to isolate gluten protein before dehydration and milling into fine powder for reconstitution. Food manufacturers represent the dominant end-user category, absorbing bulk volumes for plant-based meat analog production where textured seitan delivers fibrous mouthfeel comparable to animal muscle tissue. Organic seitan commands margin premiums through certified supply chains, while instant seitan formats are expanding fastest among meal kit providers seeking reduced preparation time. Powder form leads industrial procurement due to shelf stability and precise dosing in automated manufacturing lines.
FDA labeling requirements for gluten content and USDA organic standards govern product claims and market access in the United States, while the EU Green Deal and REACH frameworks shape European sourcing and chemical disclosure obligations for imported wheat proteins. EFSA allergen thresholds influence formulation decisions for cross-border product development. Stakeholders must monitor evolving protein-content verification protocols and certification reciprocity agreements between major producing and consuming regions to secure uninterrupted channel access.
Market Dynamics
Plant-based meat manufacturers are consolidating wheat-protein procurement around certified organic supply chains, compressing lead times and forcing processors to choose between heritage artisan methods and automated vital-gluten extraction systems.
Growth Catalysts
- EU Green Deal procurement mandates:European food manufacturers must source low-carbon ingredients, redirecting volume toward domestic wheat-gluten processors with verified carbon footprints.
- Meal-kit format expansion:Instant seitan powders reduce rehydration time from hours to minutes, matching the operational tempo of subscription food services.
- Textured protein technology:High-moisture extrusion advances enable fibrous seitan structures that replicate chicken and beef muscle alignment.
Market Restraints
- Wheat price volatility:Input costs for vital gluten fluctuate with drought cycles in North American and Black Sea growing regions.
- Allergen labeling friction:FDA gluten disclosure rules and EFSA threshold debates create formulation barriers for cross-border product lines.
- Pea and soy protein substitution:Alternative plant proteins compete on cost and allergen-free positioning in school and healthcare feeding programs.
Strategic Opportunities
- Indian foodservice penetration:Traditional wheat-based mock meat dishes in Gujarat and Maharashtra create ready demand for standardized seitan inputs.
- USDA Organic certification arbitrage:Processors bridging EU and North American organic standards capture premium pricing in dual-certified product lines.
- Fermentation-convergent processing:Koji and lactic acid pre-treatments modify gluten structure for novel texture profiles in specialty applications.
Industry Challenges
- Skilled extrusion technician scarcity:High-moisture texturizing equipment requires operators trained in rheology and thermal profiling.
- Organic certification timeline compression:Three-year transition periods for conventional wheat acreage delay supply expansion.
- Legacy mixing system incompatibility:Older vital-gluten hydration lines cannot achieve the protein density ratios demanded by modern analog-meat formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seitan Powder Market |
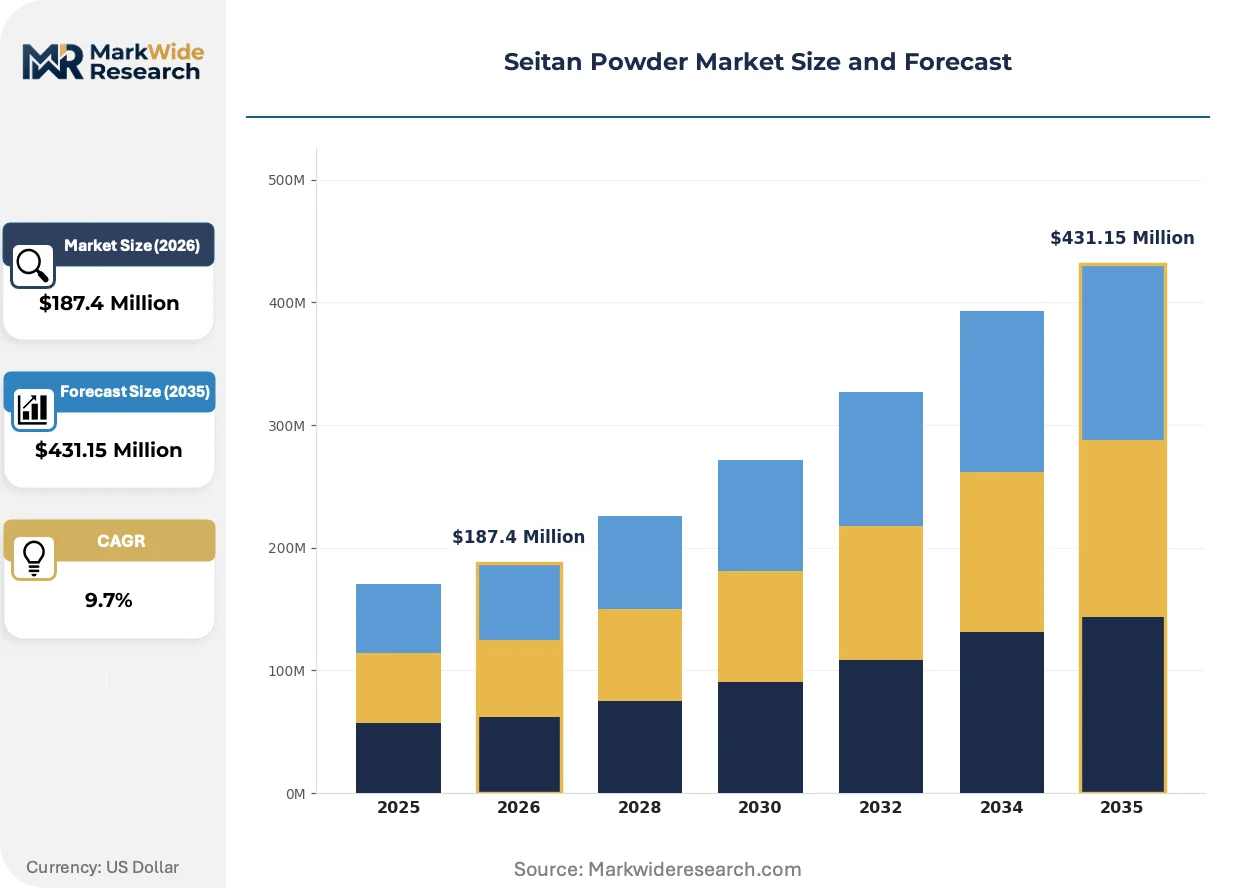
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Seitan, Instant Seitan, Textured Seitan, Seasoned Seitan Form: Powder, Chunk, Cubes, Granules End User: Food Manufacturers, Retail Consumers, Restaurants, Meal Kit Providers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Kikkoman Corporation, Bob's Red Mill, Archer Daniels Midland Company, Cargill, Inc., Amy's Kitchen, Inc., Garden Protein International, Inc., LIMA, Wheat Montana, WestSoy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seitan Powder Market Evolving Landscape
Processing equipment and ingredient formats are converging to serve two divergent buyer segments: industrial-scale meat-analog manufacturers seeking throughput, and artisan foodservice operators prioritizing heritage texture control.
High-moisture extrusion systems are miniaturizing. These units previously required factory-floor footprints exceeding 200 square meters. Mid-sized co-manufacturers in the Netherlands and California now deploy compact extrusion lines for regional meat-analog production. The technology is miniaturizing capital barriers, enabling distributed seitan-texturing capacity closer to end-formulation sites.
REACH chemical disclosure expansions are tightening wheat-protein import protocols. ECHA substance registration requirements now capture processing aids used in vital-gluten washing and dehydration. European ingredient buyers are demanding full supply-chain chemical inventories from North American and Asian processors, reshaping sourcing qualification timelines.
Direct-procurement relationships between seitan powder mills and plant-based meat brands are displacing traditional ingredient distributors. Large-format buyers in Germany and the United States negotiate multi-year volume contracts with wheat-gluten processors, securing price stability and custom protein specifications. This channel compression is most visible in refrigerated meat-analog categories where margin pressure demands input cost predictability.
Seitan Powder Market Segmentation
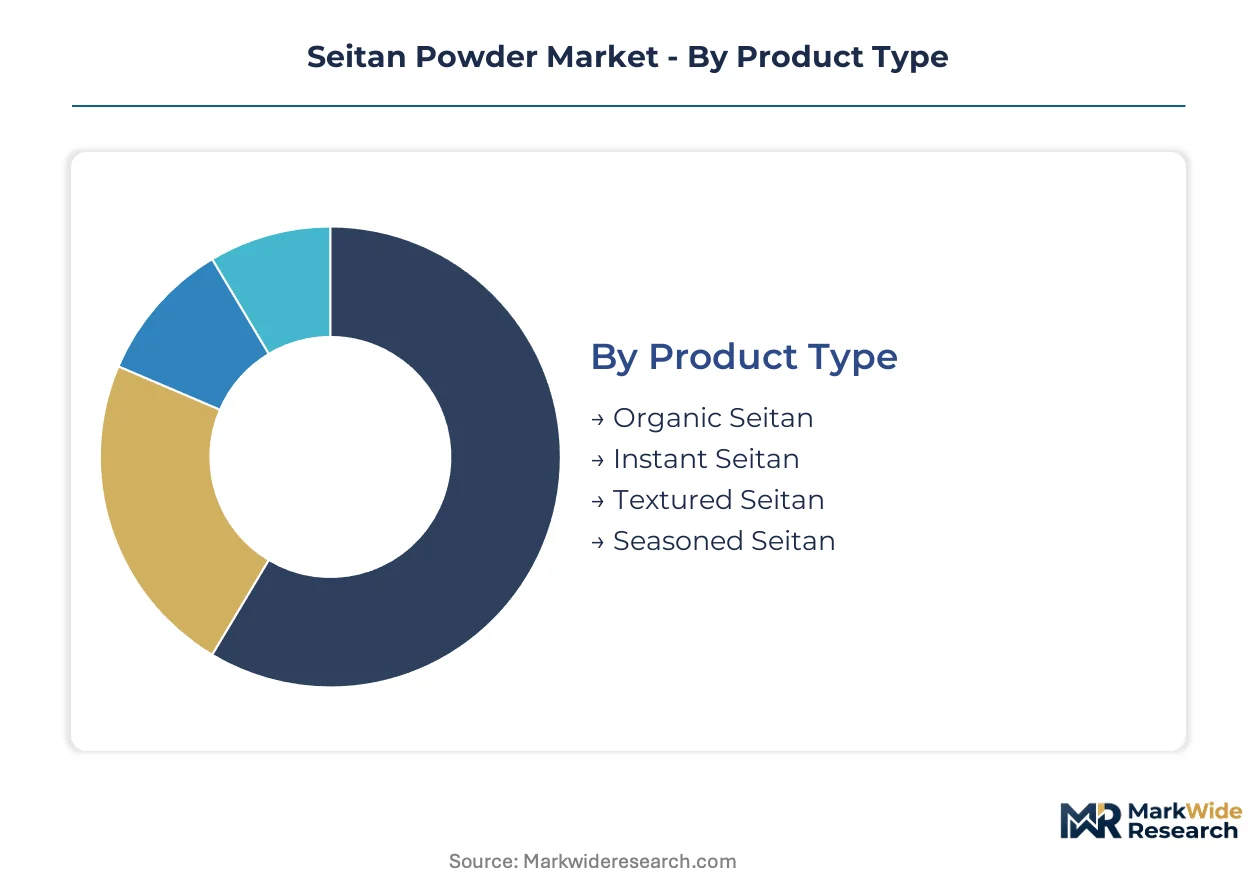
Seitan powder segments diverge sharply in their vulnerability to protein substitution. Food manufacturers prioritize functional performance while retail channels emphasize clean-label positioning, creating distinct competitive battlegrounds across each dimension.
Product Type:
Organic seitan faces the most acute substitution pressure from pea and soy isolates in premium positioning, forcing certified suppliers to defend margin through supply-chain exclusivity.
- Organic Seitan:USDA-certified vital wheat gluten commanding price premiums through three-year transition protocols and audited carbon footprints. German and Dutch food manufacturers absorb bulk volumes for EU Green Deal-compliant meat analogs where organic certification satisfies procurement mandates.
- Instant Seitan:Pre-hydrated powder formats reduce reconstitution time from hours to minutes. Meal kit providers in the United States and United Kingdom concentrate orders here, matching subscription-service operational tempo where speed determines provider selection.
- Textured Seitan:High-moisture extruded structures replicate muscle fiber alignment for chicken and beef analogs.
- Seasoned Seitan:Pre-flavored powders targeting foodservice operators seeking reduced kitchen labor.
Organic seitan anchors the volume base while instant seitan gains share at the steepest rate.
Form:
Form selection tracks customer scale and equipment sophistication, with industrial buyers dominating powder procurement while foodservice gravitates toward ready-to-use geometries.
- Powder:Fine-milled vital wheat gluten at 75-80% protein density, packaged for automated dosing in extrusion lines. Food manufacturers in Germany and California standardize on powder for high-throughput meat-analog production where precise hydration ratios control texture outcomes.
- Chunk:Rehydrated and formed pieces for direct culinary application. Independent restaurants in India and Thailand source chunks for traditional wheat-based mock meat preparations where heritage recipes specify particular bite resistance.
- Cubes:Uniform geometry for skewer and stir-fry applications in Asian foodservice.
- Granules:Intermediate particle size for stuffing and ground-meat simulations.
Powder form captures the dominant procurement share while chunk form climbs fastest among foodservice distributors.
End User:
End-user concentration determines pricing leverage, with food manufacturers extracting volume discounts while meal kit providers pay premiums for format innovation.
- Food Manufacturers:Industrial-scale buyers operating high-moisture extrusion lines for refrigerated and frozen meat analogs. Direct procurement relationships with wheat-gluten mills in the United States and Germany secure multi-year contracts with custom protein specifications.
- Meal Kit Providers:Subscription services demanding instant formats with sub-ten-minute rehydration. Operational tempo requirements in United States and United Kingdom markets drive specification sheets emphasizing speed over heritage texture profiles.
- Retail Consumers:Natural-foods shoppers purchasing through health food stores and online channels.
- Restaurants:Foodservice operators seeking consistent portion control and reduced prep labor.
Food manufacturers anchor the volume base while meal kit providers expand most quickly.
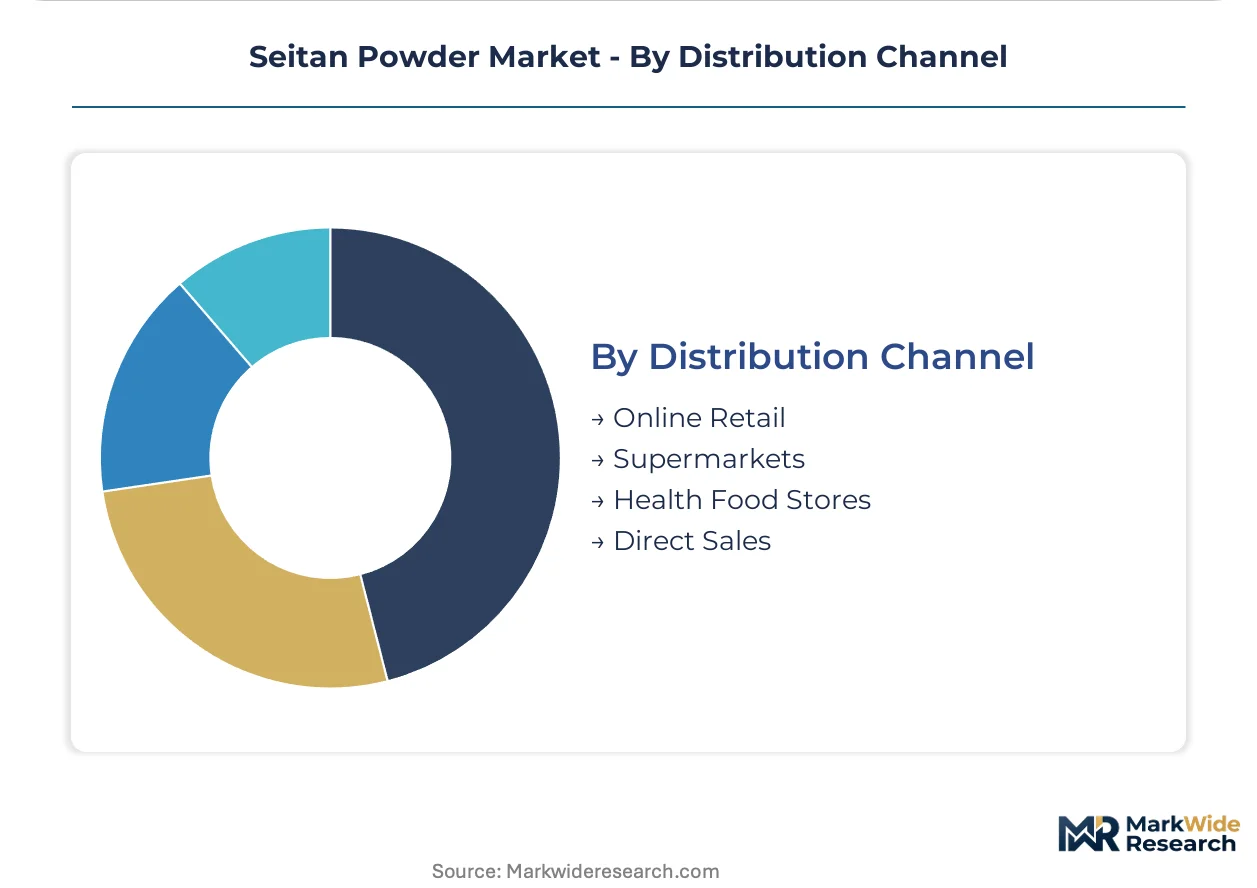
Distribution Channel:
Channel structure reflects buyer scale and certification requirements, with direct sales capturing industrial volume while online retail fragments among specialty shoppers.
- Direct Sales:Mill-to-manufacturer contracts bypassing traditional ingredient distributors. Large-format buyers in Germany and the United States negotiate price stability and custom protein density ratios for refrigerated meat-analog categories where margin pressure demands input cost predictability.
- Online Retail:E-commerce platforms serving retail consumers and small foodservice operators. Bob's Red Mill and comparable heritage brands dominate this channel through direct-to-consumer fulfillment where subscription models lock in recurring revenue.
- Supermarkets:Mass-market retail placement for established natural-foods brands.
- Health Food Stores:Specialty retail emphasizing USDA Organic and non-GMO verification.
Direct sales anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's low-carbon procurement mandates are redirecting wheat-protein sourcing toward domestic European processors with verified carbon footprints, while meal-kit adoption in North America accelerates demand for instant formats. Germany's traditional wheat-gluten clusters and India's heritage mock-meat cuisine anchor regional supply and demand poles.
Germany
Food manufacturers operating high-moisture extrusion lines for refrigerated meat analogs absorb bulk organic seitan volumes to satisfy EU Green Deal compliance requirements. The F-Gas Regulation tightens chemical disclosure obligations for imported wheat proteins, favoring domestic processors. The Rhine-Ruhr and Baden-Württemberg regions host specialized vital-gluten extraction facilities serving pan-European plant-based meat brands.
United States
Meal kit providers in California and New York Metro concentrate procurement of instant seitan powders demanding sub-ten-minute rehydration times. FDA labeling requirements for gluten content and USDA organic standards govern product claims and channel access. The Pacific Northwest and Midwest wheat belts supply raw material to integrated processors operating automated vital-gluten extraction systems.
India
Traditional wheat-based mock meat dishes in Gujarat and Maharashtra create ready demand for standardized seitan inputs among foodservice distributors. FSSAI food safety standards and DGFT import protocols shape cross-border ingredient qualification timelines. Mumbai and Ahmedabad clusters connect heritage vegetarian cuisine with industrial-scale wheat-gluten processing infrastructure.
Netherlands
Mid-sized co-manufacturers deploy compact high-moisture extrusion lines for regional meat-analog production, miniaturizing capital barriers. REACH chemical disclosure expansions through ECHA now capture processing aids used in vital-gluten washing, extending sourcing qualification timelines. The Eindhoven Region and Randstad host distributed seitan-texturing capacity closer to European formulation sites.
United Kingdom
Subscription food services concentrate orders for instant formats matching operational tempo requirements where speed determines provider selection. EFSA allergen thresholds influence formulation decisions for cross-border product development with EU markets. London and Southeast England distribution hubs connect imported wheat proteins with domestic meal-kit fulfillment networks.
Seitan Powder Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive wheat-processing infrastructure and heritage natural-foods specialists commanding retail channel access. The vendor base separates into three strategic archetypes: fermentation-technology multinationals, heritage mill-to-retail brands, and commodity-scale grain processors. Dominant competitive moves include direct-procurement relationship formation between powder mills and plant-based meat brands, and multi-year volume contracting with custom protein specifications.
Among fermentation-technology multinationals, Kikkoman Corporation leverages brewing and fermentation expertise to sustain premium positioning across Asian and North American channels. Heritage mill-to-retail specialists Bob's Red Mill occupy a position anchoring the natural-foods segment through direct-to-retailer relationships and subscription-based consumer fulfillment. At the commodity-scale end, Archer Daniels Midland Company exemplifies integrated agribusiness architecture controlling input costs across multiple protein categories through captive wheat-processing infrastructure.
| Leading Market Players |
|---|
| Kikkoman Corporation |
| Bob's Red Mill |
| Archer Daniels Midland Company |
| Cargill, Inc. |
| Amy's Kitchen, Inc. |
| Garden Protein International, Inc. |
| LIMA |
| Wheat Montana |
| WestSoy |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for organic-certified vital wheat gluten compress pricing power toward processors with verified EU Green Deal carbon footprints, while conventional-grade inventories face margin erosion from spot-market wheat volatility. Food manufacturers with direct mill contracts secure price stability through multi-year offtake agreements, whereas meal kit providers absorbing instant-format premiums lack comparable leverage.
Pricing Analysis
Certification level creates the primary spread, with USDA Organic and EU organic tiers commanding substantial premiums over commodity-grade vital gluten through audited supply-chain verification. Three-tier pricing structure across premium organic, standard food-grade, and economy feed-grade levels reflects protein density differentials and carbon-footprint documentation. Pricing pressure stems from pea and soy protein substitution in school and healthcare feeding programs where allergen-free positioning outweighs functional performance. Food manufacturers operating high-moisture extrusion lines exhibit lowest price sensitivity due to volume scale and direct procurement relationships, while independent restaurants sourcing chunk formats face highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and Rhine-Ruhr barge congestion shape inbound logistics costs for wheat-protein processors dependent on Black Sea and North American grain flows. Supply concentrates in Germany, the United States, and India, with German processors serving EU Green Deal mandates through domestic wheat-gluten clusters and Indian facilities feeding heritage foodservice demand in Gujarat and Maharashtra. Raw material dependencies center on hard red winter wheat, processing aids for gluten washing, and dehydration energy inputs. Single-source vulnerability runs through concentrated organic wheat acreage requiring three-year transition periods. Distribution runs through direct mill-to-manufacturer contracts displacing traditional ingredient distributors, with online retail fragments serving heritage brand consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward food manufacturers consolidating procurement around certified organic supply chains, compressing lead times and forcing processors into direct-contract relationships that bypass traditional distribution tiers.
For Market Incumbents: Compound defensive positioning through captive organic wheat acreage and backward integration into regional high-moisture extrusion capacity. Secure multi-year volume contracts with plant-based meat brands before meal kit providers expand procurement scale. Threat from pea protein substitution intensifies in institutional feeding channels where allergen labeling friction favors alternative isolates. For New Entrants and Emerging Players: Differentiate on fermentation-convergent processing using koji and lactic acid pre-treatments for novel texture profiles that escape commodity pricing. Target Indian foodservice penetration where standardized seitan inputs for traditional wheat-based mock meat dishes remain underdeveloped. Go-to-market angle should emphasize heritage recipe compatibility with industrial consistency. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-mandate play because EU Green Deal procurement mandates and REACH chemical disclosure expansions structurally favor processors with verified low-carbon footprints and full supply-chain transparency. Acquisition target archetype: mid-sized European wheat-gluten processors with existing organic certification and proximity to Dutch co-manufacturer networks. Signal to watch is FSSAI import protocol harmonization enabling standardized Indian foodservice expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA Organic and EU organic tiers unlock EU Green Deal procurement mandates and premium pricing. |
| High-Moisture Extrusion Capacity Addition | Compact extrusion lines in the Netherlands and California enable distributed regional meat-analog production. |
| Direct Mill-to-Manufacturer Contracting | Bypassing traditional distributors secures price stability and custom protein specifications for refrigerated analog categories. |
| Fermentation-Convergent Processing Development | Koji and lactic acid pre-treatments create novel texture profiles escaping commodity vital gluten pricing. |
| Indian Foodservice Supply Agreement | Mumbai and Ahmedabad clusters connect heritage vegetarian cuisine with industrial-scale wheat-gluten processing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance, EFSA allergen threshold documentation, EU Green Deal procurement mandates, and REACH chemical disclosure protocols. Interviews with wheat-gluten processing plant managers, procurement leads at plant-based meat manufacturers, organic certification auditors, and meal kit supply chain directors informed demand-side validation. Secondary sources include USDA organic certification databases, ECHA substance registration records, FSSAI food safety standards, customs trade data for vital wheat gluten flows, and SEC filings from integrated agribusiness conglomerates. Bottom-up volume estimates from processor capacity and top-down demand segmentation from end-use procurement patterns were cross-validated.
Segmentation dimensions modeled include certification tier, product format, end-user category, and distribution channel across the projection horizon. Protein content verification protocols and certification reciprocity agreements between major producing and consuming regions shaped regional growth assumptions. CAGRs were derived from volume trajectory analysis against EU Green Deal compliance deadlines and meal kit format expansion rates. Industry-specific inputs include organic wheat acreage transition timelines, high-moisture extrusion equipment deployment patterns, and F-Gas Regulation chemical disclosure compliance costs.
Forecasts assume regulatory continuity in USDA organic standards, EU Green Deal procurement mandates, and FSSAI import protocols; material policy shifts would require re-modeling. Wheat price volatility from drought cycles in North American and Black Sea growing regions, EFSA allergen threshold revisions, and REACH processing aid disclosure expansions represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Allulose for Food Market