
 Asia-Pacific Condiments Market | 2026-2036
Asia-Pacific Condiments Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Condiments Market Insights
Southeast Asian sauce manufacturers is pivoting toward automated fermentation and blending lines to meet rising foodservice orders. Foshan Haitian Flavoring & Food Co., Ltd. anchors its position through captive soy sauce fermentation capacity in Guangdong Province. Kikkoman Corporation leverages its centuries-old koji-mold expertise to sustain premium positioning across Japanese and export channels. Masan Group competes aggressively in Vietnamese retail through deep distribution networks in provincial cities.
Condiments encompass preserved flavor-enhancing preparations—typically with acidity below pH 4.6, salt content exceeding 5%, or fermented substrates—that extend shelf stability while intensifying taste perception in finished dishes. Soy sauce dominates volume through liquid fermentation of soy-wheat blends with Aspergillus oryzae, while hot sauce segments gain velocity from chili-pepper mash aging in oak or steel. Sachet packaging captures the fastest-growing format as single-serve portions penetrate Southeast Asian street-vendor channels, whereas jar formats retain margin concentration in premium umami and savory retail lines.
China's SAMR enforces GB standards on condiment labeling and additive limits, while India's FSSAI mandates fortification disclosures for iron-enriched sauces. Japan's METI oversees JIS-compliant manufacturing equipment standards that constrain small-batch entrants. Stakeholders must monitor diverging sodium-reduction mandates across these jurisdictions to align R&D pipelines with compliance thresholds.
Market Dynamics
China's SAMR enforcement of GB 2760 additive limits and sodium-reduction mandates is compressing formulation margins while accelerating clean-label R&D investment across soy sauce and fermented paste categories. This regulatory pressure cascades through supply chains, forcing manufacturers to revalidate entire ingredient portfolios.
Growth Catalysts
- Urban Premiumization:Tier-one Indian households in Mumbai and Delhi are trading up to imported and artisanal sauces, expanding addressable wallet share in the region's fastest-growing condiment segment.
- Foodservice Automation:Southeast Asian street-vendor channels are adopting sachet-format single-serve portions, driving volume throughput for fermented chili and fish sauce producers.
- FSSAI Fortification Mandates:India's iron-enrichment disclosure requirements for sauces are creating compliant product differentiation that commands retail shelf preference.
Market Restraints
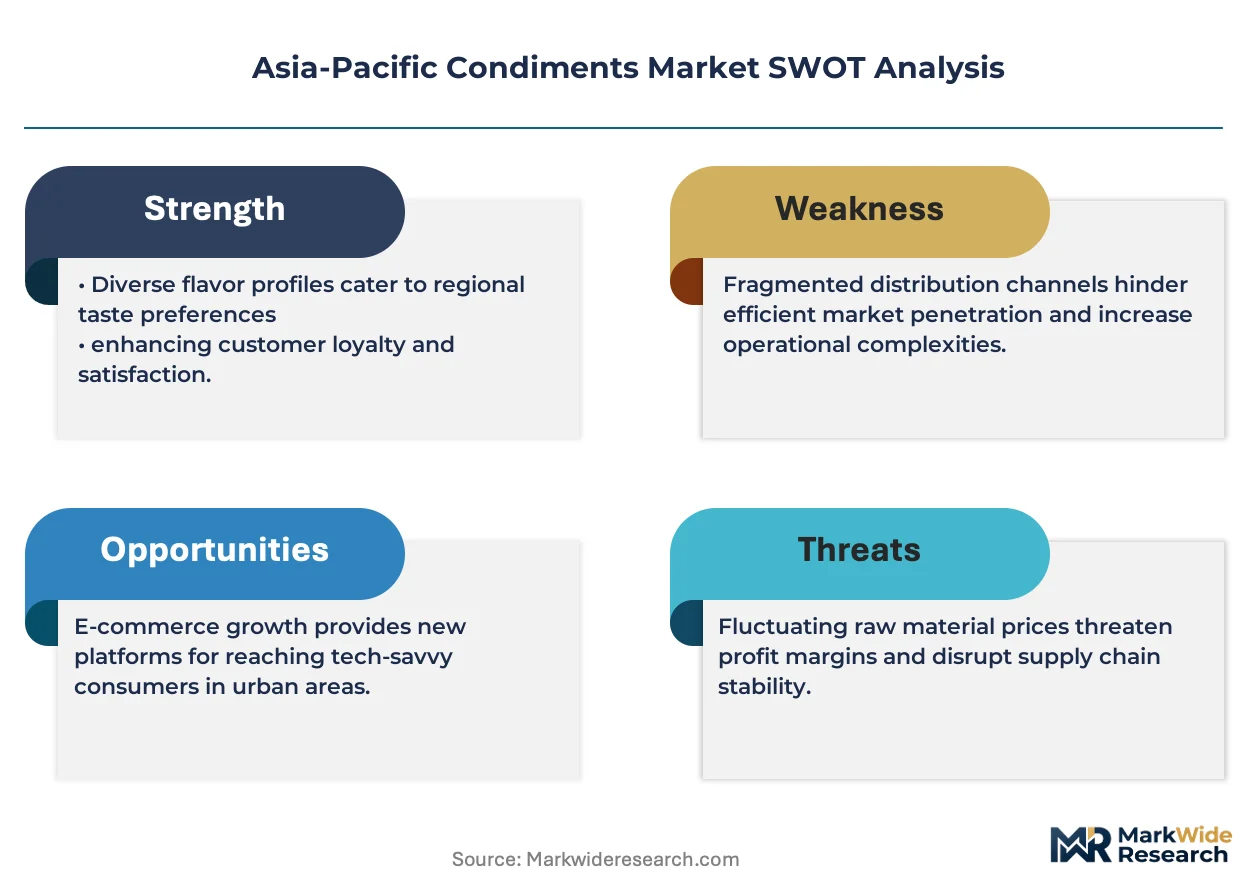
- Soybean Input Volatility:Argentine and Brazilian soybean price swings transmit directly into soy sauce COGS, compressing gross margins for liquid-fermentation operators.
- Guangdong Supply Concentration:Captive fermentation capacity clusters in China's Pearl River Delta, creating geographic vulnerability to flooding and power-rationing disruptions.
- Technical Fermentation Barriers:Aspergillus oryzae koji-mold cultivation requires 90-day maturation cycles that block rapid SKU expansion for new market entrants.
Strategic Opportunities
- Vietnamese Provincial Penetration:Masan Group's distribution template demonstrates scalable reach into secondary cities like Can Tho and Da Nang for premium sauce categories.
- Clean-Label Convergence:Sodium-reduction technologies are unifying with natural umami extraction from kombu and shiitake, enabling compliance without flavor sacrifice.
- E-Commerce Direct Channels:Tmall and Lazada flagship stores bypass traditional wholesale markups, capturing margin recovery in tier-two Chinese and Indonesian markets.
Industry Challenges
- Microbiological Contamination Risk:Aflatoxin control in chili-pepper mash aging requires HACCP retrofit investments that strain mid-tier processor balance sheets.
- Cross-Border Label Harmonization:Divergent sodium disclosure thresholds between China's GB standards and Japan's METI guidelines force dual-SKU inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Condiments Market |
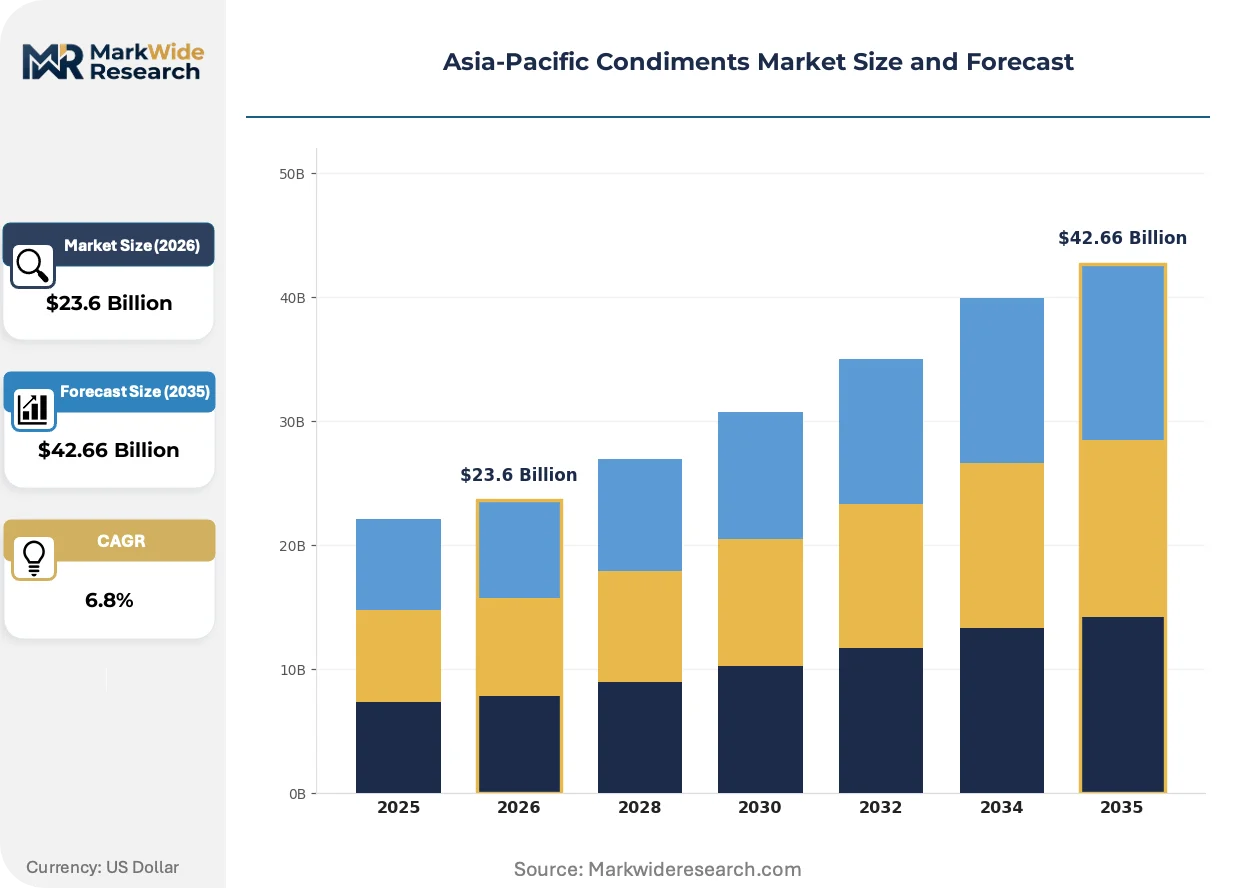
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Soy Sauce, Mustard, Hot Sauce End User: Households, Restaurants, Foodservice, Retail Packaging Type: Bottles, Jars, Sachets, Tubs Flavor Profile: Sweet, Spicy, Savory, Umami |
| Companies Covered | The Kraft Heinz Company, Unilever PLC, McCormick & Company, Inc., Nestlé S.A., Kikkoman Corporation, Lee Kum Kee, Foshan Haitian Flavoring & Food Co., Ltd., Conagra Brands, Inc., Masan Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Condiments Market Trends and Innovations
Fermentation science and packaging automation are converging to reshape condiment production economics. Three developments are compressing legacy cost structures while opening premium positioning vectors.
Continuous stirred-tank fermentation systems are unifying temperature, pH, and oxygen control into single-vessel operations that slash soy sauce maturation from 180 days to 30 days. Thai and Indonesian foodservice distributors are adopting these systems at pilot scale. The technology is compressing working-capital cycles and enabling just-in-time production for private-label contracts.
Japan's METI has tightened JIS-compliant manufacturing equipment standards for small-batch fermentation vessels, raising capital barriers for artisanal entrants. The regulation forces domestic producers to consolidate into shared-facility cooperatives or exit entirely. Premium umami retail lines face the steepest compliance cost escalation.
Street-vendor procurement in Bangkok and Jakarta is fragmenting toward mobile-app ordering platforms that disintermediate traditional wet-market wholesalers. Chili-pepper mash suppliers are responding with 4-hour delivery guarantees and QR-code traceability. This behavioral shift is most visible in Vietnam's Ho Chi Minh City vendor corridors.
Asia-Pacific Condiments Market Segmentation
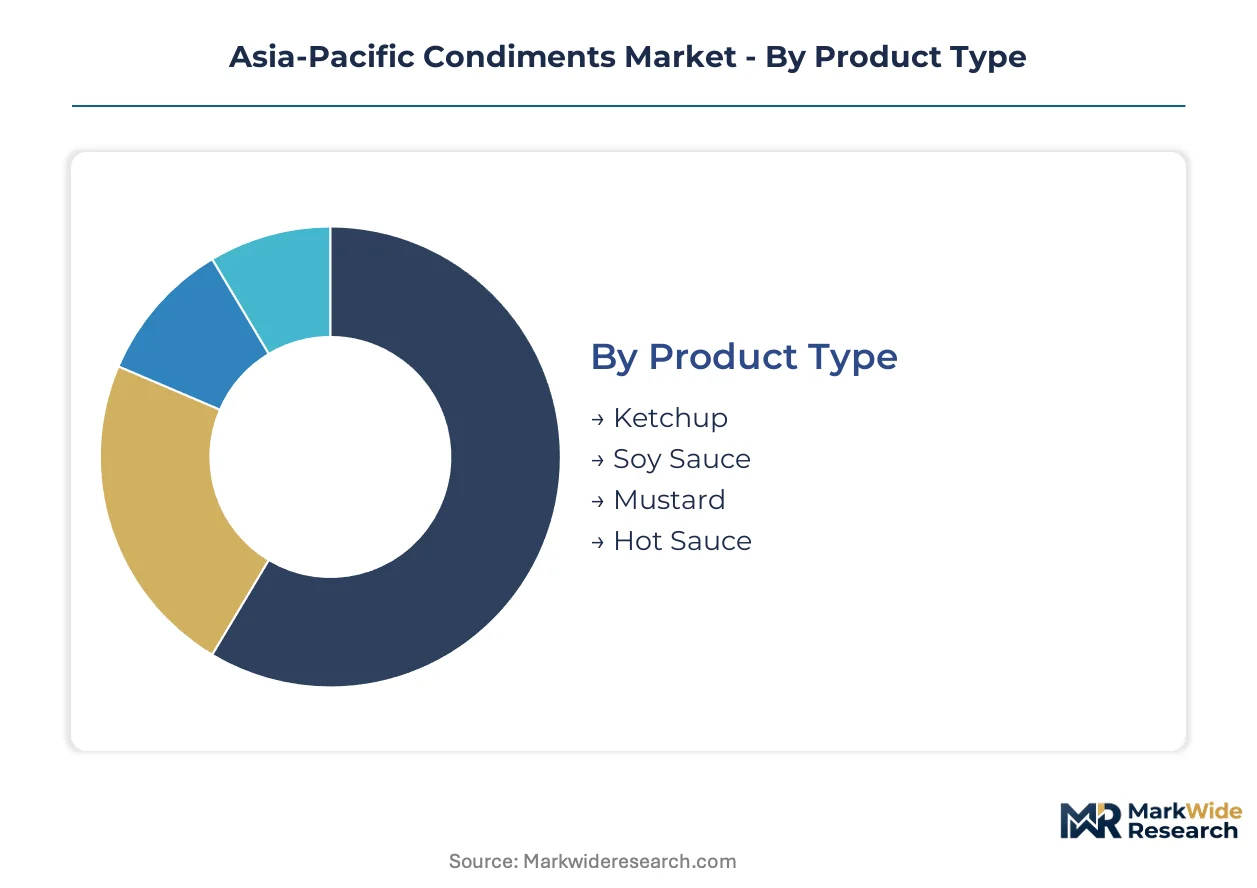
Condiment purchasing decisions in Asia-Pacific diverge sharply between institutional procurement and household selection, with formulation requirements and packaging formats driving entirely different supplier relationships. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume throughput dominates.
Product Type:
Buyer priorities split between fermented complexity for foodservice operators and convenience-driven familiarity for retail households.
- Soy Sauce:Liquid fermentation of soy-wheat substrates with Aspergillus oryzae koji-mold produces the foundational umami base for East Asian cooking. Foodservice accounts in Guangdong Province and Ho Chi Minh City absorb bulk drum shipments for commercial kitchens, though 90-day maturation cycles constrain rapid SKU expansion for new entrants.
- Hot Sauce:Chili-pepper mash aging in oak or steel vessels builds capsaicin complexity and shelf stability. Street-vendor channels across Bangkok and Jakarta are driving sachet-format adoption for single-serve portions, with aflatoxin control requirements forcing HACCP retrofits on mid-tier processors.
- Ketchup:Tomato-based formulations with vinegar and sugar balance appeal across generational preferences in Indian and Australian retail.
- Mustard:Seed-based pastes and prepared yellow varieties serve niche premium positioning in Japanese and South Korean import channels.
Soy sauce leads on scale; hot sauce leads on momentum.
End User:
Volume concentration tracks urbanization density and away-from-home eating frequency across the region's major metropolitan corridors.
- Foodservice:Commercial kitchens, institutional caterers, and chain restaurants procure in bulk formats with specification-grade consistency requirements. Tier-one Chinese cities and Mumbai's hotel sector are driving premium sauce adoption with documented supplier audits.
- Restaurants:Independent dining establishments balance cost control with differentiation through signature house-made blends or imported specialty lines. Vietnam's provincial cities like Can Tho and Da Nang are expanding addressable reach through distributor network deepening.
- Households:Urban nuclear families in Delhi and Jakarta trade up to smaller-format premium offerings with clean-label positioning.
- Retail:Supermarket and hypermarket channels manage shelf space allocation between private-label economy tiers and branded premium positioning.
Foodservice commands absolute volume; restaurants are climbing fastest on outlet expansion.
Packaging Type:
Format selection directly determines distribution channel compatibility and margin capture potential.
- Sachets:Single-serve foil or laminate pouches dominate Southeast Asian street-vendor procurement with sub-10 gram portions. Mobile-app ordering platforms in Ho Chi Minh City are fragmenting procurement away from wet-market wholesalers toward 4-hour delivery guarantees with QR-code traceability.
- Bottles:PET and glass containers retain household penetration for high-frequency use categories with established brand loyalty.
- Jars:Premium umami and savory retail lines concentrate margin in Japanese and South Korean specialty channels.
- Tubs:Foodservice bulk formats serve institutional procurement with pump-dispense compatibility and portion control.
Sachets dominate transaction frequency; jars concentrate margin per unit.
Flavor Profile:
Regional palate preferences and health positioning are reshaping formulation investment priorities.
- Umami:Glutamate-rich profiles from fermentation or natural extraction satisfy the foundational taste dimension across East Asian cuisines. Sodium-reduction technologies are converging with kombu and shiitake natural extraction to maintain intensity under tightening SAMR and FSSAI compliance thresholds.
- Spicy:Capsaicin-forward formulations gain velocity from chili-pepper mash aging traditions in Thailand, Vietnam, and Indonesia.
- Savory:Balanced salt and fermented depth serves broad household penetration without polarizing intensity.
- Sweet:Sugar-forward profiles appeal to younger demographics and fusion cuisine experimentation in Australian and urban Indian markets.
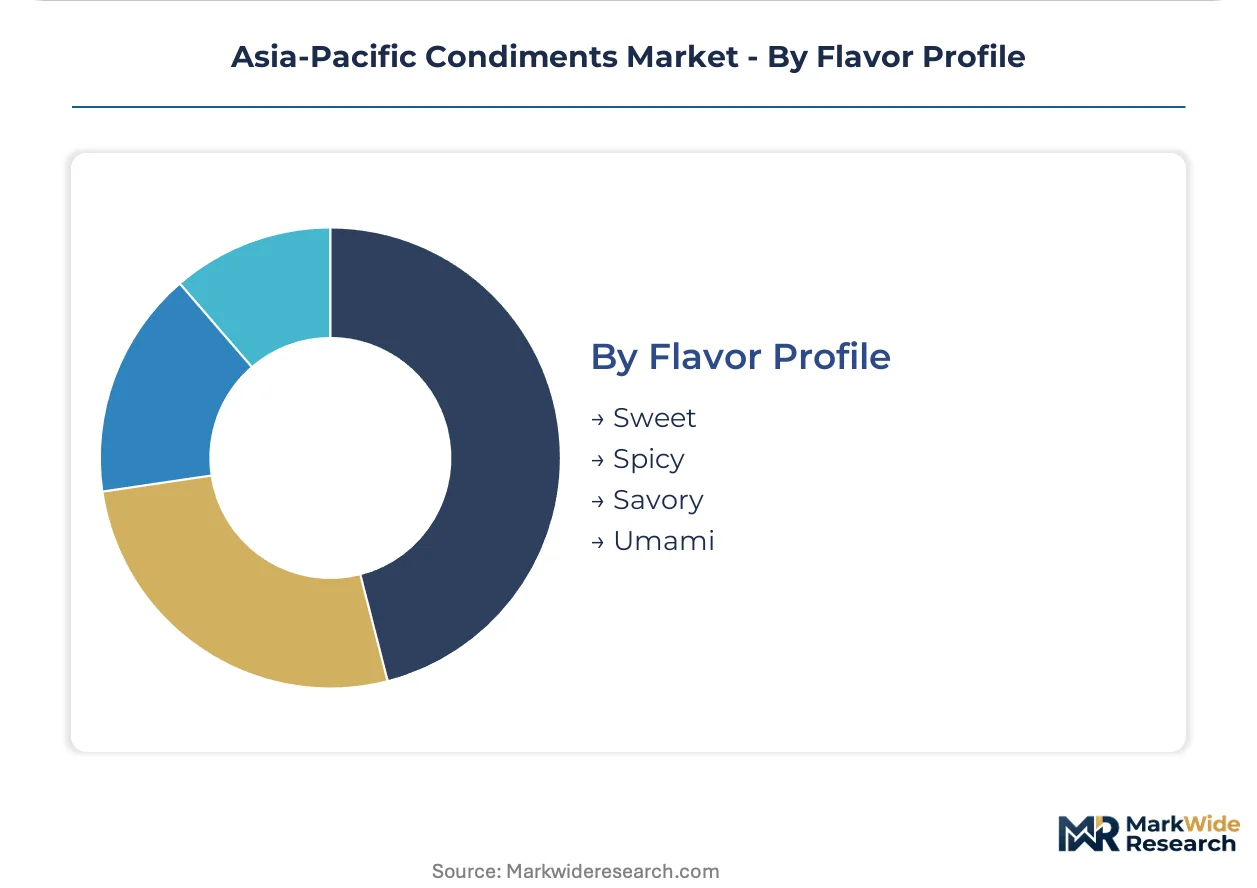
Umami anchors volume baseline; spicy profiles are expanding most quickly on export and cross-regional adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fermentation capacity dwarfs India's nascent premiumization, yet both markets are tightening regulatory scrutiny over sodium content and additive disclosure. Southeast Asian street-vendor channels are fragmenting procurement patterns across Bangkok, Jakarta, and Ho Chi Minh City.
China
Guangdong Province hosts captive soy sauce fermentation clusters serving foodservice bulk demand. SAMR enforces GB 2760 additive limits and sodium-reduction mandates that compress formulation margins. Pearl River Delta manufacturers are retrofitting HACCP systems to meet tightening microbiological standards.
India
Mumbai and Delhi tier-one households are trading up to imported and artisanal sauces, expanding premium wallet share. FSSAI mandates iron-enrichment disclosures for sauces, creating compliant product differentiation. Maharashtra and Karnataka urban corridors are driving retail format experimentation in sachet and jar packaging.
Japan
Kikkoman's centuries-old koji-mold expertise sustains premium positioning across domestic and export channels. METI tightened JIS-compliant manufacturing equipment standards, raising capital barriers for small-batch entrants. Kanto and Kansai industrial zones are consolidating into shared-facility cooperatives to absorb compliance costs.
Vietnam
Provincial cities like Can Tho and Da Nang are expanding addressable reach for premium sauce categories through distributor network deepening. Mobile-app ordering platforms in Ho Chi Minh City are fragmenting street-vendor procurement toward 4-hour delivery guarantees. Mekong Delta chili-pepper mash suppliers are adopting QR-code traceability systems.
Indonesia
Jakarta's foodservice automation is driving sachet-format adoption for fermented chili and fish sauce producers. Continuous stirred-tank fermentation systems are slashing maturation cycles at pilot scale in Thai and Indonesian facilities. Java-based processors are capturing working-capital efficiency gains for private-label contracts.
Asia-Pacific Condiments Market Competitive Landscape
Chinese producers anchor one tier through captive fermentation capacity and scale-driven cost structures; Japanese specialists hold premium positioning through proprietary koji-mold expertise and extended maturation protocols. The vendor base splits between consolidated fermentation giants with integrated supply chains and fragmented regional sauce blenders serving localized taste preferences. Two strategic archetypes dominate: vertically integrated fermentation operators controlling soybean-to-bottle workflows, and distribution-heavy conglomerates penetrating provincial retail through deep wholesale relationships. Competitive moves concentrate on clean-label R&D investment to meet tightening sodium regulations and e-commerce direct-channel expansion to bypass traditional wholesale markups.
Within the fermentation-integrated tier, Foshan Haitian Flavoring & Food Co., Ltd. exemplifies the Chinese scale archetype through its Guangdong-based captive capacity. Kikkoman Corporation occupies a position representing centuries-old koji-mold cultivation expertise that sustains premium pricing across export channels. Masan Group sits within the distribution-intensive archetype, demonstrating how Vietnamese market penetration into secondary cities can scale premium sauce adoption. These three entities collectively illustrate the geographic and strategic segmentation defining competitive positioning in the Asia-Pacific condiments market.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever PLC |
| McCormick & Company, Inc. |
| Nestlé S.A. |
| Kikkoman Corporation |
| Lee Kum Kee |
| Foshan Haitian Flavoring & Food Co., Ltd. |
| Conagra Brands, Inc. |
| Masan Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned fermentation specialists across Guangdong and Jiangsu provinces anchor supply-side discipline through multi-generational soybean procurement relationships and captive koji-mold cultivation, translating upstream control into pricing power that resists commodity volatility. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling patient capacity planning that shapes regional price floors.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for mid-tier soy sauce and chili sauce categories. Three-tier pricing structure across premium, standard, and economy levels separates Kikkoman-grade artisanal positioning from mass-market sachet formats, with brand heritage and fermentation duration as primary differentiation drivers. Cost compression in economy tiers is intensifying because Argentine soybean price swings transmit directly into liquid-fermentation COGS. Street-vendor procurement channels exhibit highest price sensitivity, while Japanese specialty retail maintains lowest elasticity.
Supply Chain Analysis
Domestic-content mandates under China's SAMR and India's FSSAI are reshaping sourcing patterns for fermentation substrates and additive inputs. Supply concentrates in China, Vietnam, and Thailand for soy-wheat fermentation capacity and chili-pepper mash processing. Raw material dependencies center on Argentine and Brazilian soybeans, Mekong Delta chili harvests, and domestic wheat supplies. Single-source vulnerability runs through Pearl River Delta fermentation clusters exposed to flooding and power-rationing disruptions. Distribution runs through foodservice wholesale networks in tier-one cities and mobile-app platforms penetrating Southeast Asian street-vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where sodium-reduction mandates and fortification disclosure requirements under SAMR and FSSAI are accelerating clean-label R&D investment and reshaping competitive positioning.
For Market Incumbents: To counter microbiological contamination risks in chili-pepper mash aging, retrofit HACCP systems across Vietnamese and Indonesian processing facilities while deepening backward integration into captive soybean crushing capacity in Guangdong. Channel control through Tmall and Lazada flagship stores captures margin recovery lost to traditional wholesale markups. For New Entrants and Emerging Players: Begin with Vietnamese provincial cities like Can Tho and Da Nang where Masan Group's distribution template demonstrates scalable premium sauce adoption with limited incumbent saturation. Target iron-fortified sauce categories under FSSAI compliance as the most penetrable segment, leveraging mobile-app procurement platforms for direct street-vendor access without legacy wholesaler relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fermentation operators with underutilized capacity in Thailand and Indonesia. Long-term viability over the analysis window hinges on clean-label technology acquisition and sodium-reduction patent portfolios. Watch for METI enforcement actions against small-batch Japanese producers as forced-exit inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Thai and Indonesian pilot facilities compress 180-day maturation to 30 days, unlocking working-capital efficiency. |
| Sodium-Reduction R&D Investment | Kombu and shiitake natural umami extraction enables SAMR compliance without flavor degradation in premium lines. |
| E-Commerce Direct Channel Expansion | Tmall and Lazada flagship stores bypass traditional wholesale markups in tier-two Chinese and Indonesian markets. |
| Provincial Distribution Network Deepening | Masan Group's Can Tho and Da Nang penetration demonstrates scalable secondary-city premium sauce adoption. |
| HACCP System Retrofit | Aflatoxin control investments strain mid-tier processor balance sheets but create compliant product differentiation. |
Research Methodology
Direct dialogue with fermentation plant managers, FSSAI compliance officers, foodservice procurement heads at Guangdong hotel chains, and mobile-app platform operators in Ho Chi Minh City grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, FSSAI fortification disclosure records, Indonesian customs trade data, and Nielsen retail audit coverage of Mumbai and Delhi sauce categories. Bottom-up volume estimates triangulated against top-down category spending projections.
Segmented outputs across product type, end-user channel, packaging format, and flavor profile dimensions fed into the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of urban household premiumization in Indian tier-one cities and foodservice automation penetration across Southeast Asian street-vendor channels. Soybean input price volatility and regulatory compliance cost trajectories served as key forecast sensitivity inputs.
Caveats apply where SAMR enforcement intensity, Argentine drought cycles, or METI small-batch producer consolidation could materially shift the outlook. Forecasts reflect documented assumptions about fermentation technology adoption curves and mobile-platform procurement penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Horseradish Sauce Market