
 Egg-Free Mayonnaise Market | 2026-2036
Egg-Free Mayonnaise Market Size, Share, and Industry Trends Forecast 2026-2036
Egg-Free Mayonnaise Market Intelligence
Buyer concentration in the food service channel is shifting as regional restaurant chains and institutional caterers fragment procurement across multiple suppliers rather than consolidating with single vendors. Unilever Group leverages its refrigerated distribution network to sustain shelf presence in European retail. Kraft Heinz Company anchors North American mass-market penetration through conventional grocery slotting. Follow Your Heart Inc. differentiates via clean-label formulations that compete in the premium natural channel.
Egg-free mayonnaise is an oil-in-water emulsion stabilized by plant-derived hydrocolloids or modified starches, typically containing 60-80% vegetable oil and achieving viscosity comparable to egg-based equivalents through shear-processing or high-pressure homogenization. The product serves commercial food manufacturing and food service operations requiring allergen-free, vegan-certified binding and moisture-retention functionality. Regular formulations dominate volume through food service and retail commodity positioning, while organic variants command margin premiums in health food stores and specialty grocers. Online distribution channels represent the fastest-growing access point, particularly for direct-to-consumer flavored and spicy sub-lines targeting younger household segments.
FDA allergen labeling requirements and EU Regulation 1169/2011 on food information to consumers compel manufacturers to declare egg content explicitly, accelerating reformulation toward egg-free alternatives in export-bound production. BIS standards in India and FSSAI vegan certification protocols are creating parallel compliance pathways for domestic and imported brands. Stakeholders must monitor evolving plant protein supply contracts and regional clean-label enforcement intensity to calibrate formulation investments and geographic prioritization.
Market Dynamics
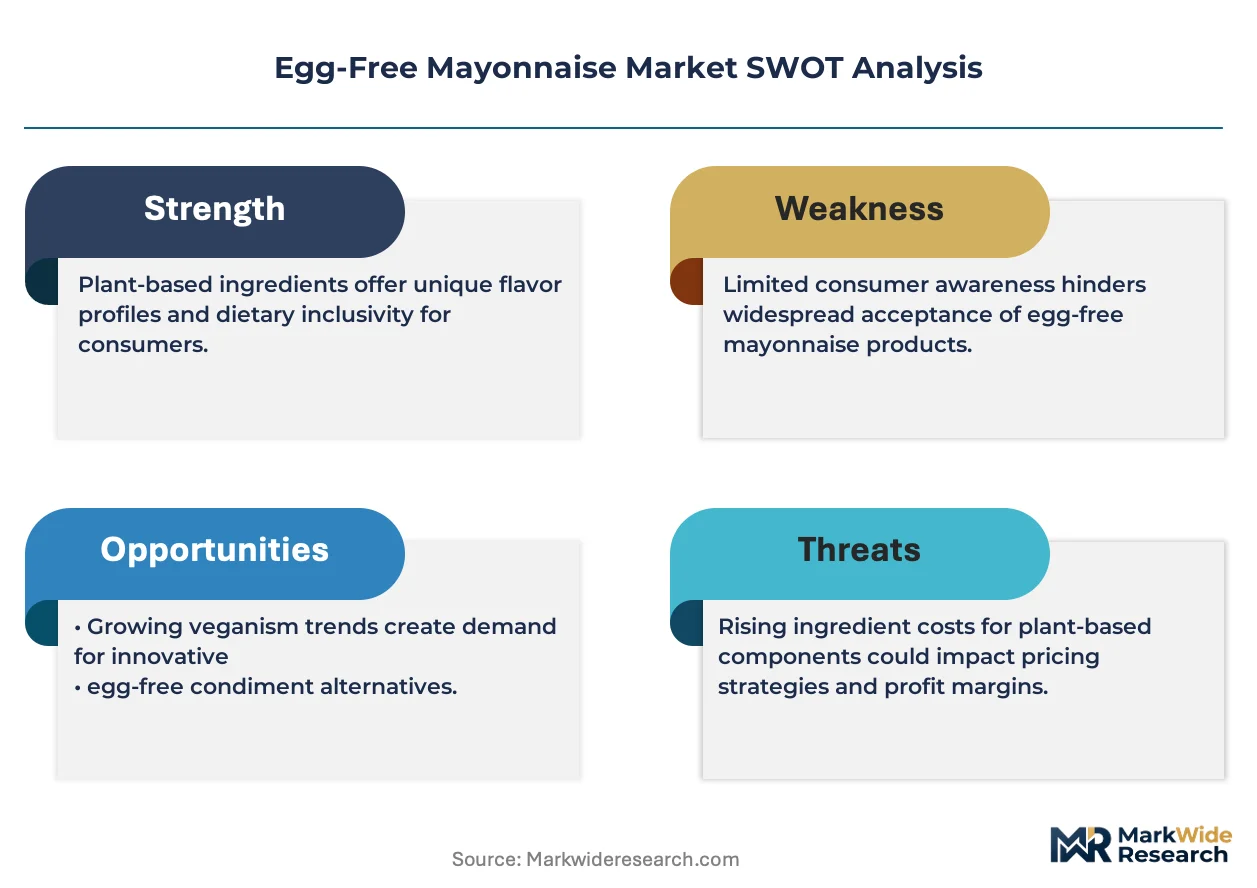
Plant protein emulsion technologies are consolidating commercial production standards as aquafaba and pea protein displace lecithin stabilizers, tightening allergen compliance while reshaping supplier qualification requirements across food manufacturing.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory egg content declaration on food labels accelerates reformulation toward vegan-certified alternatives in export-bound European production.
- Aquafaba stabilization:Chickpea-derived emulsion technology achieves viscosity parity with egg-based equivalents at lower ingredient cost, driving adoption in commercial food service operations.
- Institutional catering:K-12 schools and hospital systems in the United States expand allergen-free menu mandates, creating dedicated procurement channels for egg-free binding agents.
Market Restraints
- Pea protein supply concentration:Processing capacity clusters in Canada and northern Europe, exposing manufacturers to regional crop yield volatility and contract renewal risk.
- Modified starch cost structure:Corn and tapioca-derived hydrocolloids face input price pressure from biofuel demand and climate-driven harvest variability.
- Emulsion stability limits:Plant-based formulations exhibit shorter shelf life under ambient distribution, constraining penetration in unrefrigerated retail channels.
Strategic Opportunities
- FSSAI vegan certification:India's formalized plant-based labeling protocol opens compliance pathways for imported brands targeting domestic retail expansion.
- Direct-to-consumer spicy sub-lines:E-commerce platforms enable flavor innovation targeting younger household segments without conventional grocery slotting barriers.
- High-pressure homogenization convergence:Shear-processing equipment upgrades allow co-manufacturers to pivot existing lines between dairy and plant-based emulsions.
Industry Challenges
- Clean-label enforcement calibration:Divergent regional definitions of "natural" and "processed" complicate single-formulation strategies across export markets.
- Shear-processing talent gap:Equipment operation and maintenance expertise concentrates with legacy dairy technicians, slowing workforce scaling for plant-dedicated facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg-Free Mayonnaise Market |
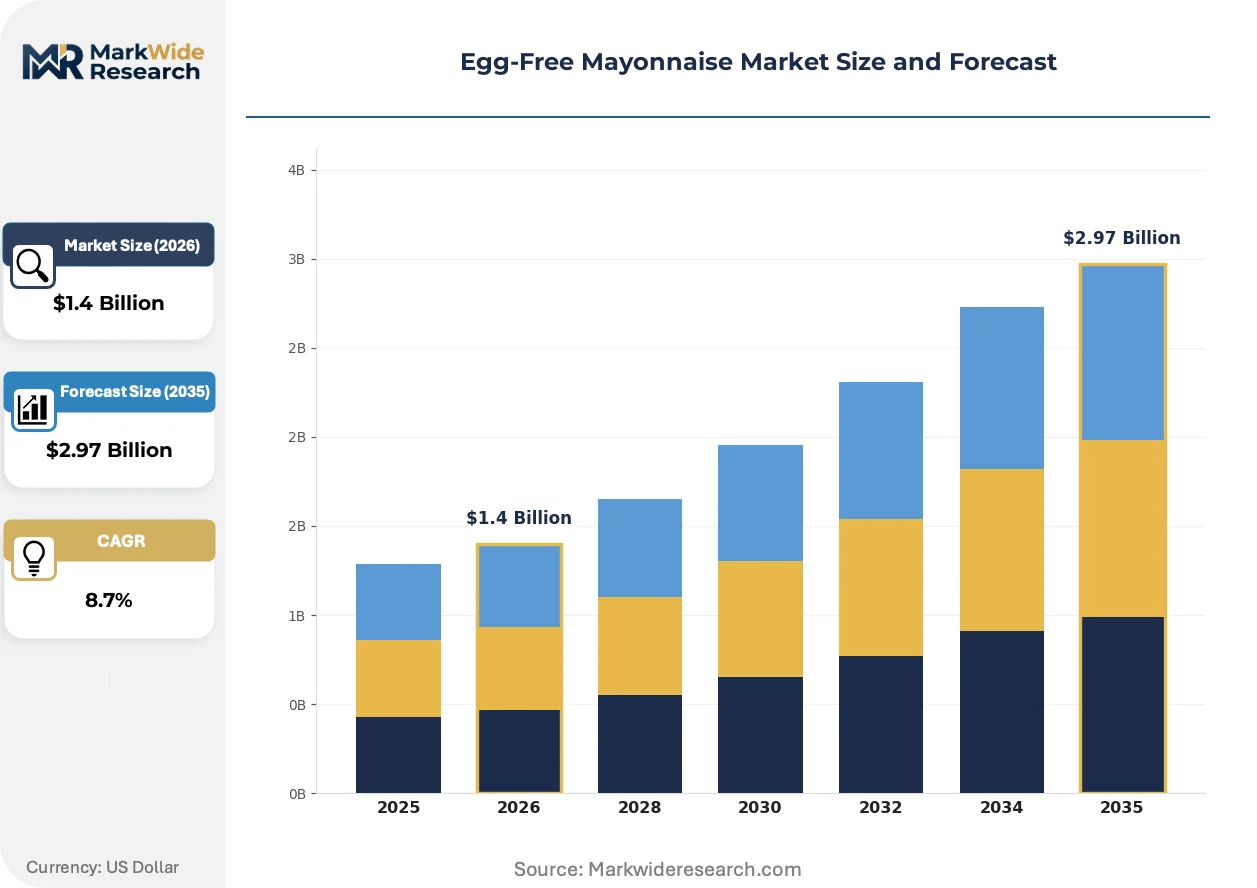
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Organic, Flavored, Spicy Distribution Channel: Online, Supermarkets, Health Food Stores, Restaurants End User: Households, Food Services, Catering, Food Manufacturers Packaging Type: Glass Jars, Plastic Bottles, Pouches, Tubes |
| Companies Covered | Follow Your Heart Inc., Veeba Food Services Private Limited, Unilever Group, Kraft Heinz Company, Del Monte Foods Inc., Conagra Brands Inc., Eat Just Inc., Cremica Food Industries Ltd., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg-Free Mayonnaise Market Strategic Shifts & Innovations
Emulsion science and distribution infrastructure are converging to compress product development cycles, with formulation advances enabling faster geographic and channel expansion than legacy egg-based supply chains permitted.
Aquafaba-derived emulsion systems are consolidating position as the dominant plant-based stabilization platform. Commercial manufacturers in Germany and the United Kingdom have adopted chickpea water processing at scale for retail and food service lines. The technology is consolidating supplier tiers by reducing dependency on multi-ingredient hydrocolloid blends and simplifying label declarations.
EU Green Deal sustainability reporting requirements now extend to ingredient sourcing disclosures for packaged foods. Food manufacturers face expanded documentation obligations for vegetable oil supply chains, particularly palm and sunflower derivatives. Premium natural channel brands in France and the Netherlands are responding by securing segregated-certificate supply contracts ahead of enforcement deadlines.
Food service procurement has fragmented across regional restaurant chains and institutional buyers, displacing consolidated national vendor relationships. Smaller operators now source through broadline distributors carrying multiple egg-free SKUs rather than single-supplier contracts. This pattern is most visible in the United States, where third-party logistics networks enable just-in-time delivery without dedicated cold-chain investment by individual restaurants.
Egg-Free Mayonnaise Market Segmentation
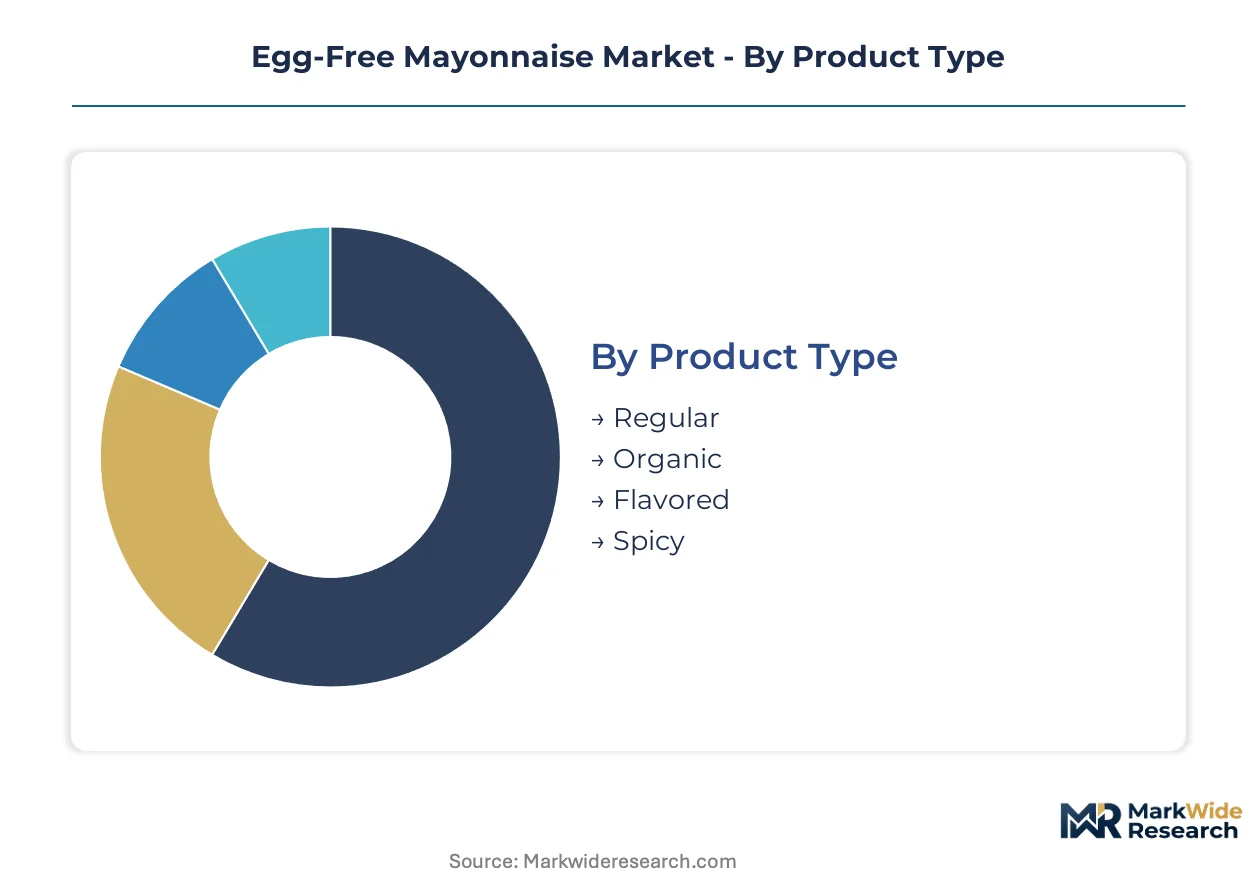
Segmentation in egg-free mayonnaise reveals how formulation choices, channel access, and end-use requirements create distinct competitive arenas. Each axis carries different margin structures and regulatory exposure, demanding targeted production and distribution strategies.
Product Type:
Formulation specifications determine ingredient cost bases, shelf stability, and certification complexity across the category.
- Regular:Standard vegetable oil emulsions stabilized by modified starches or hydrocolloids achieve 60-80% oil content with viscosity matching conventional mayonnaise. Demand concentrates in food service operations across Germany and the United States where allergen compliance mandates drive bulk procurement.
- Organic:Certified organic variants require segregated supply chains for vegetable oils and plant protein emulsifiers, commanding placement in premium natural channel retail. Clean-label enforcement intensity in France and the Netherlands accelerates sourcing documentation obligations under EU Green Deal sustainability reporting.
- Flavored:Garlic, herb, and specialty variants target direct-to-consumer e-commerce channels with minimal conventional grocery slotting requirements.
- Spicy:Chili-infused formulations attract younger household segments through online distribution, bypassing traditional retail barriers.
Regular leads on scale; Spicy leads on momentum.
Distribution Channel:
Channel selection governs cold-chain investment, margin retention, and consumer demographic access.
- Online:E-commerce platforms enable flavor innovation and subscription models without slotting fee burdens, expanding fastest among millennial and Gen-Z household segments seeking direct brand relationships.
- Supermarkets:Conventional grocery placement demands refrigerated distribution infrastructure and trade promotion spending, with Kraft Heinz Company anchoring mass-market penetration through established slotting relationships in North American retail.
- Health Food Stores:Specialty grocers carry premium organic and clean-label SKUs with higher margin structures and educated consumer bases.
- Restaurants:Food service procurement fragments across regional chains and institutional buyers sourcing through broadline distributors carrying multiple egg-free SKUs.
Supermarkets dominate volume capture; Online shows steepest expansion trajectory.
End User:
User type dictates batch size requirements, certification needs, and formulation stability specifications.
- Households:Retail consumers purchase smaller formats with extended shelf life requirements, driving demand for ambient-stable pouches and squeeze tubes.
- Food Services:Restaurants and QSR chains require bulk formats with consistent emulsion performance under high-shear dispensing equipment, with procurement shifting toward multi-supplier distributor relationships.
- Catering:Institutional K-12 schools and hospital systems in the United States expand allergen-free menu mandates, creating dedicated procurement channels with explicit vegan certification requirements.
- Food Manufacturers:Industrial buyers incorporate egg-free mayonnaise as binding and moisture-retention ingredients in packaged salads, sandwiches, and prepared foods, demanding tanker-scale delivery with customized viscosity specifications.
Food Services anchor current volume; Catering demonstrates fastest policy-driven expansion.
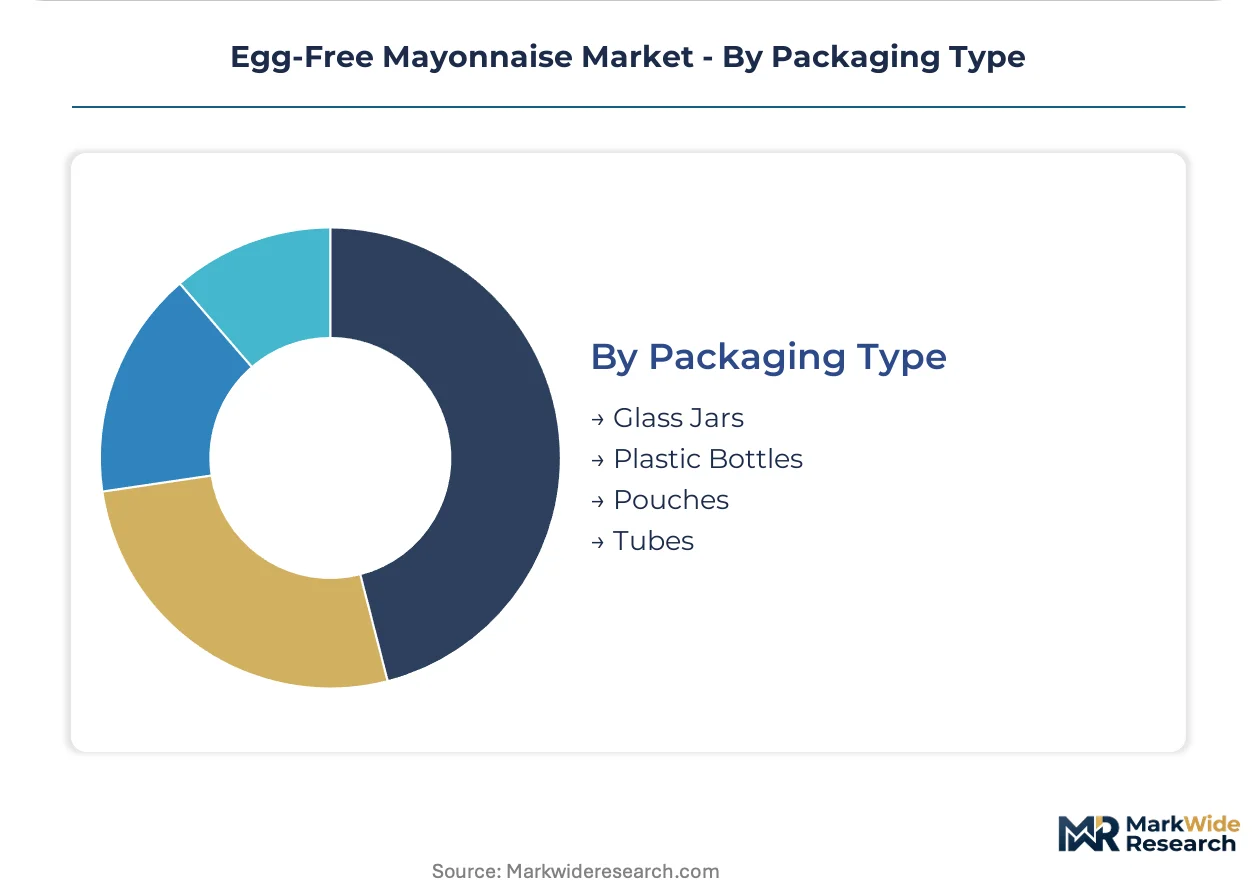
Packaging Type:
Packaging format selection balances shelf stability, sustainability positioning, and consumption occasion targeting.
- Glass Jars:Premium positioning in European retail leverages perceived quality and recyclability, though weight increases logistics costs.
- Plastic Bottles:Standard retail and food service formats optimize for squeezability and cost efficiency across mass-market channels.
- Pouches:Flexible packaging reduces material costs and shipping weight, gaining traction in online direct-to-consumer shipments and single-serve food service portions.
- Tubes:Portion-control formats target institutional catering and on-the-go consumption with precise dispensing and minimal waste.
Plastic Bottles maintain volume leadership; Pouches gain share fastest through e-commerce alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium shelf space for plant-based condiments while the United States drives institutional procurement volume through allergen-free mandates in schools and hospitals.
Germany
Retail chains Edeka and REWE have expanded vegan condiment sections by over 40% since 2022, creating dedicated fixture space for egg-free emulsions. EU Regulation 1169/2011 mandates explicit egg allergen labeling, compelling reformulation across export-bound production. The Cologne-Düsseldorf corridor hosts multiple aquafaba processing facilities supplying commercial food manufacturers with stabilized chickpea-derived emulsifiers.
United States
K-12 school districts in California and New York now require allergen-free binding agents in prepared salads and sandwiches, opening dedicated procurement channels. FDA Food Allergen Labeling and Consumer Protection Act enforcement drives manufacturer liability exposure for undeclared egg content. Chicago and Dallas metropolitan areas concentrate food service distribution hubs where broadline operators stock multiple egg-free SKUs for fragmented restaurant procurement.
United Kingdom
Tesco and Sainsbury's have allocated incremental refrigerated space to plant-based mayonnaise variants, with private-label introductions accelerating price competition. The Food Standards Agency enforces Natasha's Law allergen labeling requirements for prepacked direct sale foods. Greater Manchester hosts co-manufacturing facilities serving both retail own-brand and food service bulk formats.
India
Quick-service restaurant chains in Mumbai and Bangalore are replacing egg-based mayonnaise with vegan-certified alternatives to serve vegetarian-majority demographics. FSSAI vegan certification protocols formalize compliance pathways for domestic and imported brands seeking retail expansion. The National Capital Region around Delhi concentrates food processing parks where mayonnaise production lines are being retrofitted for plant-protein emulsion systems.
France
Carrefour and Intermarché have introduced dedicated vegan condiment bays in hypermarket formats, with organic variants commanding 35-50% price premiums over conventional lines. EU Green Deal sustainability reporting requirements extend to vegetable oil sourcing disclosures for packaged foods. The Lyon-Grenoble axis hosts specialty food manufacturers developing clean-label emulsion technologies for export to neighboring Benelux markets.
Egg-Free Mayonnaise Market Key Industry Players
European producers anchor the premium clean-label tier; North American conglomerates hold mass-market penetration through conventional grocery slotting. Market structure tilts toward consolidation at the top with Unilever Group and Kraft Heinz Company commanding refrigerated distribution networks, while mid-tier specialists fragment across regional food service channels. Three archetypes dominate: multinational CPG conglomerates with legacy condiment portfolios, plant-based pure-plays with vegan certification credentials, and private-label manufacturers serving retailer own-brand programs. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure aquafaba and pea protein supply contracts.
Among the plant-based pure-play specialists, Follow Your Heart Inc. exemplifies clean-label positioning that competes in premium natural channel retail. Unilever Group and Kraft Heinz Company occupy positions as multinational conglomerates leveraging established refrigerated distribution infrastructure across European and North American mass markets respectively. These three entities represent the strategic archetype spread: a dedicated vegan specialist, a European-headquartered global CPG, and a North American mass-market incumbent.
| Leading Market Players |
|---|
| Follow Your Heart Inc. |
| Veeba Food Services Private Limited |
| Unilever Group |
| Kraft Heinz Company |
| Del Monte Foods Inc. |
| Conagra Brands Inc. |
| Eat Just Inc. |
| Cremica Food Industries Ltd. |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Aquafaba and pea protein emulsion technologies are compressing ingredient cost structures while redrawing supplier tier relationships across commercial production. This transition simultaneously reduces multi-ingredient hydrocolloid dependency and concentrates processing capacity in specific geographies, reshaping how manufacturers negotiate input contracts and calibrate price positioning across retail and food service channels.
Pricing Analysis
Capacity additions in Germany and the United Kingdom are reshaping price floors for aquafaba-derived emulsions as commercial scale reduces per-unit ingredient costs. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels dominates retail placement, with certification grade and volume scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because broadline distributors now carry multiple SKUs, fragmenting procurement power. Food service operators show highest price sensitivity due to bulk volume requirements, while health food store channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and northern European pea protein processing clusters exposed to regional crop yield volatility. Raw material flows draw from chickpea cultivation in India, sunflower oil extraction in Ukraine and Argentina, and modified starch processing in Thailand and Brazil. Tariff exposure on vegetable oil imports complicates cost forecasting for manufacturers serving EU Green Deal compliance markets. Distribution runs through refrigerated broadline networks in North America and temperature-controlled retail logistics in Europe, with ambient-stable pouches enabling direct-to-consumer bypass of conventional cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Regulation 1169/2011 and FDA allergen labeling mandates create structural demand for reformulated alternatives regardless of consumer preference shifts.
For Market Incumbents: Anchor refrigerated distribution relationships against private-label encroachment by securing multi-year aquafaba supply contracts with processors in the Cologne-Düsseldorf corridor. Invest in high-pressure homogenization equipment upgrades to maintain formulation flexibility as pea protein supply volatility threatens input cost stability. Certification investment in FSSAI vegan protocols opens defensive positioning against emerging Indian market entrants. For New Entrants and Emerging Players: Begin with direct-to-consumer spicy and flavored sub-lines targeting millennial households through subscription models, bypassing slotting fee barriers that protect incumbent shelf presence. The most penetrable white space sits in institutional catering procurement channels where K-12 and hospital systems mandate allergen-free binding agents but lack dedicated supplier relationships. A co-manufacturing partnership with existing shear-processing facilities accelerates market entry without capital-intensive production investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier co-manufacturers with installed homogenization capacity and established retailer private-label relationships. Long-term viability hinges on backward integration into aquafaba processing or captive pea protein supply arrangements that insulate margin structures from commodity volatility. The signal to watch is FSSAI certification completion rates among import brands targeting Indian QSR expansion, indicating which entrants have cleared compliance barriers for scalable geographic replication.| Strategic Initiative | Industry Significance |
|---|---|
| Aquafaba Processing Capacity Expansion | Secures ingredient supply independence from volatile pea protein contract markets. |
| FSSAI Vegan Certification Investment | Unlocks compliant market entry into India's QSR and retail expansion channels. |
| High-Pressure Homogenization Equipment Upgrade | Enables production line pivoting between dairy and plant-based emulsion formats. |
| Direct-to-Consumer Subscription Launch | Bypasses conventional grocery slotting fees while capturing younger household segments. |
| Segregated-Certificate Vegetable Oil Sourcing | Satisfies EU Green Deal sustainability disclosure requirements for premium channel placement. |
Research Approach
Direct dialogue with food manufacturing R&D directors, broadline distribution procurement managers, food service chain operators, and plant protein ingredient suppliers grounded qualitative insights in operational realities. Secondary validation drew from FDA allergen labeling guidance documents, EU Regulation 1169/2011 implementation reports, FSSAI vegan certification protocols, customs trade data on vegetable oil imports, and refrigerated logistics operator disclosures. Bottom-up production capacity assessments triangulated against top-down consumption estimates across retail and food service channels.
Bottom-up modeling tracked formulation cost structures by product type, distribution channel access tiers, and end-user batch size requirements over the projection horizon. Segmentation dimensions included organic versus conventional certification, refrigerated versus ambient stability, and food service versus retail channel positioning. CAGRs were derived from production capacity expansion schedules, regulatory enforcement timelines, and channel penetration curves rather than extrapolated historical trends. Forecast inputs incorporated aquafaba processing yield improvements and pea protein contract renewal patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to allergen threshold definitions, breakthroughs in enzymatic emulsion stabilization, and climate-driven vegetable oil harvest collapses beyond historical variance bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Global Hot Pot Condiment Market