
 West Africa Mayonnaise Market | 2026-2036
West Africa Mayonnaise Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Mayonnaise Market Intelligence
Clean-label emulsification technology is tilting production toward reduced-stabilizer formulations across West African manufacturing lines. GB Foods leverages its Moroccan supply base to anchor North African ingredient flows into Senegal and Mali. Nestle SA sustains pan-African distribution density through chilled-chain partnerships with regional logistics operators. Unilever PLC competes via brand recognition built through decades of table-spread presence in Nigerian urban retail.
Mayonnaise is an oil-in-water emulsion stabilized by egg yolk lecithin and acidified with vinegar or lemon juice, typically containing vegetable oil content between 65% and 80% by weight, functioning primarily as a cold sauce base for sandwiches, salads, and prepared foods in commercial and domestic settings. The product type landscape shows regular mayonnaise occupying volume leadership in price-sensitive West African households, while vegan formulations gain shelf space in Accra and Lagos specialty retail. Pouch packaging captures growth in informal trade channels where single-serve units match cash-constrained purchasing patterns, whereas glass jars dominate supermarket placement targeting middle-class consumers.
Nigeria's National Agency for Food and Drug Administration and Control enforces mandatory product registration and Good Manufacturing Practice compliance for all imported and domestically produced mayonnaise, elevating barrier costs for informal entrants. Ghana's Food and Drugs Authority mirrors this framework with standardized oil-content labeling and pathogen-testing protocols that shape formulation decisions by manufacturers serving both markets. The Economic Community of West African States' harmonized standards initiative will determine whether multinational producers can streamline single-recipe production across the region's fragmented regulatory terrain. Stakeholders must monitor ECOWAS convergence timelines to decide between centralized manufacturing scale or country-specific formulation adaptation.
Market Dynamics
Clean-label emulsification technology is collapsing the traditional stabilizer supply chain across West African mayonnaise manufacturing, forcing reformulation investments that reshape competitive positioning between multinational and domestic producers.
Growth Catalysts
- Quick-service restaurant expansion:Lagos and Accra drive condiment volume through sandwich and salad menu proliferation. Chilled-chain logistics partnerships enable shelf-stable distribution to secondary cities.
- ECOWAS harmonization initiative:The regional standards body is advancing unified food safety protocols. Manufacturers anticipate single-recipe production scale across Nigeria, Ghana, and Côte d'Ivoire.
- Pouch packaging innovation:Single-serve units match cash-constrained purchasing patterns in informal trade channels. Sachet formats penetrate rural retail where glass jars face breakage and cost barriers.
Market Restraints
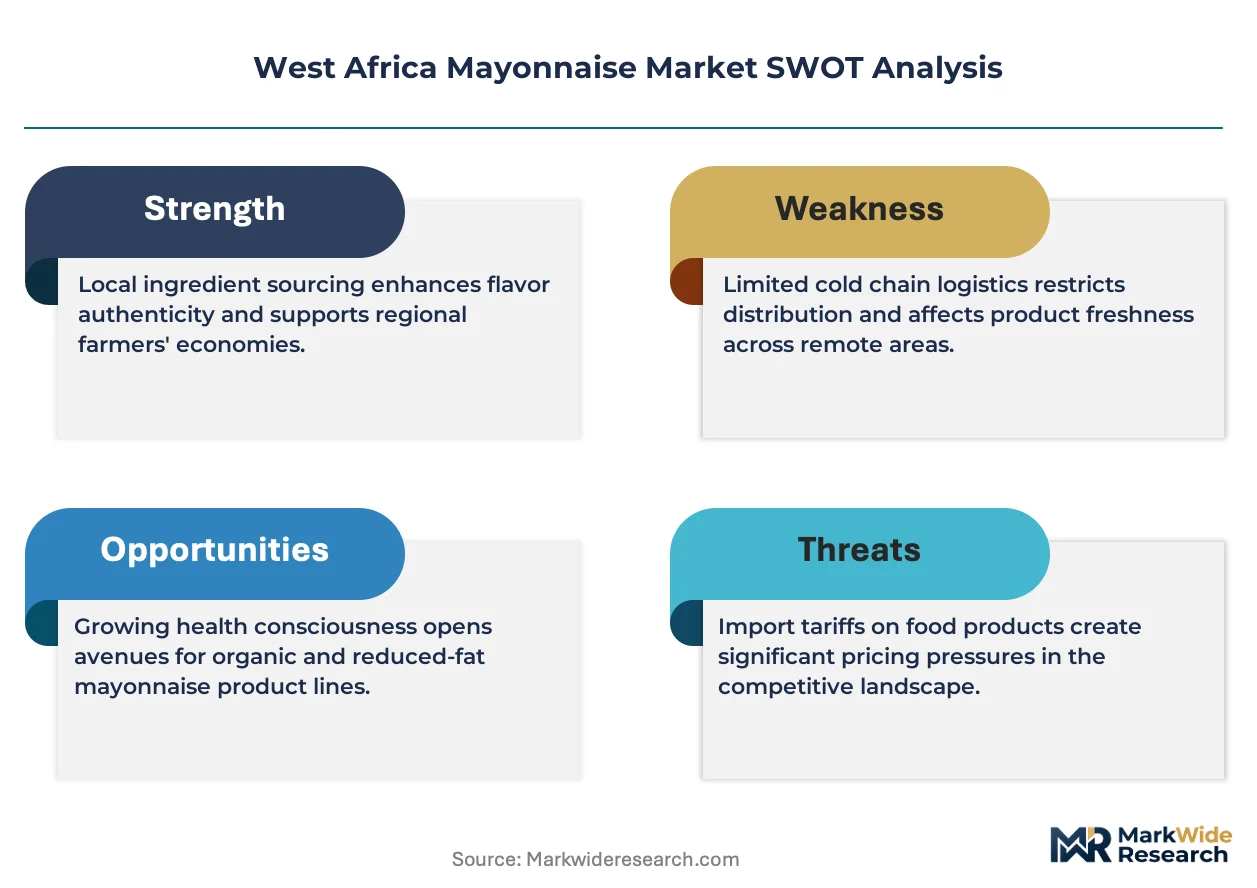
- Vegetable oil price volatility:Palm and soybean oil inputs constitute 65-80% of formulation weight. Currency depreciation in Nigeria amplifies import cost exposure for refined oil supplies.
- NAFDAC compliance costs:Nigeria's food safety regulator mandates product registration and Good Manufacturing Practice certification. Informal entrants face elevated barrier costs that entrench incumbent advantage.
- Egg supply concentration:Yolk lecithin sourcing depends on fragmented poultry operations. Avian influenza outbreaks in the Sahel disrupt emulsifier availability for domestic manufacturers.
Strategic Opportunities
- Vegan formulation white space:Plant-based emulsifiers gain shelf space in Accra and Lagos specialty retail. Aquafaba and modified starch alternatives attract lactose-intolerant and ethically motivated consumers.
- Senegal and Mali penetration:GB Foods leverages its Moroccan supply base to anchor North African ingredient flows into underpenetrated Francophone markets. Distribution infrastructure gaps present first-mover advantages.
- Chilled-chain partnership models:Regional logistics operators offer temperature-controlled last-mile coverage. Asset-light market entry becomes viable for brands lacking captive cold storage.
Industry Challenges
- Formulation chemist scarcity:Reduced-stabilizer emulsion science requires specialized expertise that West African technical institutes underproduce. Multinationals poach talent from domestic competitors.
- Dual-registration burden:Nigeria's NAFDAC and Ghana's Food and Drugs Authority maintain non-identical oil-content labeling and pathogen-testing protocols. Parallel compliance teams drain operational resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Mayonnaise Market |
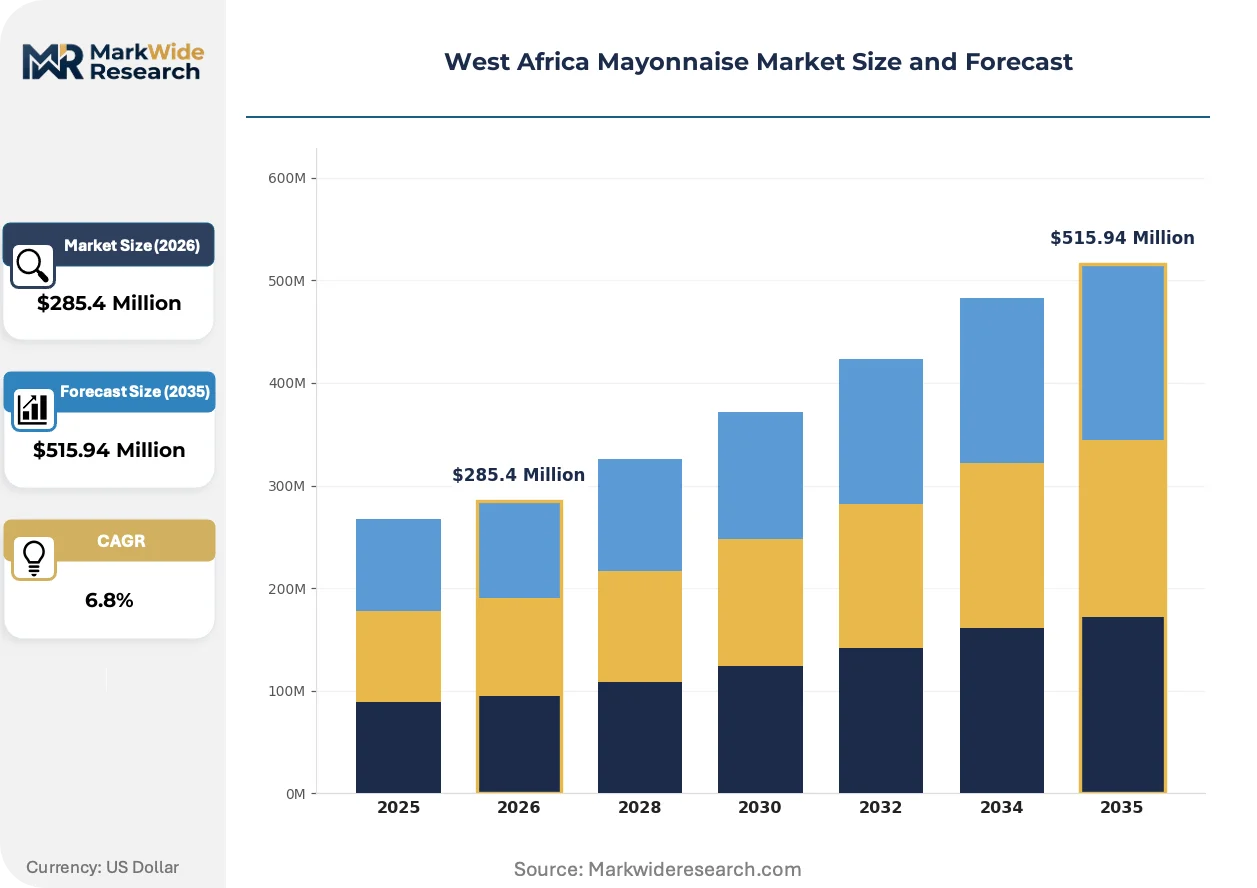
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low-Fat, Vegan, Organic Packaging Type: Glass Jars, Plastic Bottles, Pouches, Tubs Distribution Channel: Supermarkets, Local Markets, Online, Food Service End User: Households, Restaurants, Catering Services, Retailers |
| Companies Covered | GB Foods, Nestle SA, Nurevas, McCormick Corporation, Kraft Heinz, TGI, Pure Food Processing Industries, BM Foods, Unilever PLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Mayonnaise Market Strategic Shifts & Innovations
West African mayonnaise production is experiencing a technology-driven compression of traditional supply structures, with regulatory convergence and retail format innovation creating new competitive battlegrounds.
Clean-label emulsification systems are collapsing the conventional stabilizer procurement model. High-pressure processing and enzyme-modified starches enable texture stability without synthetic additives. Mid-tier manufacturers in Ibadan and Kumasi adopt these systems to meet supermarket buyer specifications. The technology is collapsing margins for legacy stabilizer suppliers dependent on volume sales of xanthan gum and modified cellulose.
Ghana's Food and Drugs Authority has tightened standardized oil-content labeling requirements. Manufacturers must declare precise vegetable oil percentages on primary packaging. Reformulation costs hit brands serving both Ghana and Nigeria, where NAFDAC maintains different disclosure thresholds. Premium-positioned products respond with front-of-pack transparency marketing, while economy lines face label redesign expenses.
Single-serve pouch formats are displacing bulk glass jars in informal retail channels. Street vendors and roadside kiosks in Lagos Island and Accra Central prefer 20-gram sachets that match daily wage purchasing patterns. Supermarket chains counter with multi-pack promotions targeting middle-class stock-up behavior. The channel divergence forces manufacturers to maintain dual packaging SKUs with divergent margin profiles.
West Africa Mayonnaise Market Segmentation
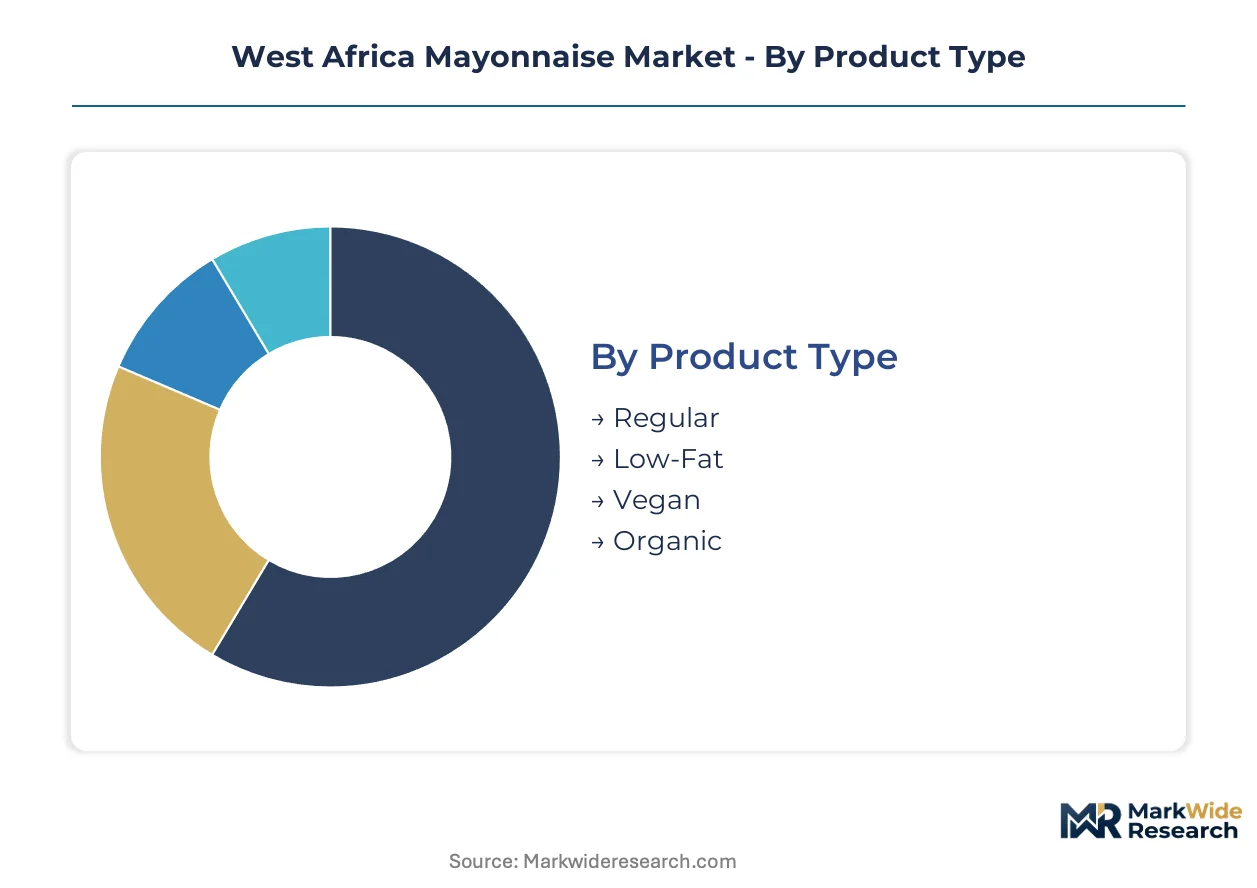
West Africa's mayonnaise market fragments across formulation tiers, retail formats, and procurement channels that each carry distinct margin profiles and regulatory exposure. Understanding these segment boundaries reveals where multinational scale advantages clash with domestic agility.
Product Type:
Cost tier differentiation shapes competitive positioning from mass-market penetration to premium positioning in Lagos and Accra retail.
- Regular:Standard oil-in-water emulsion with 65-80% vegetable oil content stabilized by egg yolk lecithin. Volume concentrates in Nigerian and Ghanaian household procurement through local markets and informal trade where price sensitivity dominates purchase decisions.
- Vegan:Plant-based emulsifier systems using aquafaba or modified starch alternatives eliminate egg dependency. Demand clusters in Accra and Lagos specialty retail among lactose-intolerant consumers and ethically motivated urban professionals.
- Low-Fat:Reduced oil formulations targeting health-conscious middle-class segments.
- Organic:Certified ingredient sourcing for premium supermarket placement.
Regular formulations command the established base. The steepest expansion runs through vegan alternatives.
Packaging Type:
Application context determines format viability, from domestic cold storage to ambient street vending resilience.
- Pouches:Single-serve sachets in 20-gram units match cash-constrained purchasing patterns in Lagos Island and Accra Central informal channels. Street vendors prefer this format for breakage resistance and transaction-size flexibility.
- Glass Jars:Premium positioning in Nigerian and Ghanaian supermarket chains targets middle-class stock-up behavior. Breakage risk and higher unit costs exclude this format from rural retail penetration.
- Plastic Bottles:Mid-tier squeeze formats for household refrigerator storage.
- Tubs:Food service bulk procurement for restaurant back-of-house operations.
Glass jars anchor supermarket placement. Pouch formats are climbing the fastest through informal trade expansion.
Distribution Channel:
Customer type heterogeneity forces parallel channel strategies with divergent working capital requirements.
- Local Markets:Fragmented vendor networks in Ibadan, Kumasi, and secondary cities drive volume through cash-based, small-unit transactions. Chilled-chain gaps limit shelf-stable product placement.
- Supermarkets:Organized retail in Lagos and Accra demands standardized labeling compliance with Ghana's FDA oil-content disclosure rules and NAFDAC registration requirements.
- Food Service:Quick-service restaurant procurement in Lagos and Accra generates institutional condiment volume through sandwich and salad menu proliferation.
- Online:E-commerce penetration remains nascent, constrained by last-mile cold chain reliability.
Local markets capture the volume base. Food service channels show the steepest expansion trajectory.
End User:
Volume scale and procurement frequency separate household consumption from commercial food preparation demand.
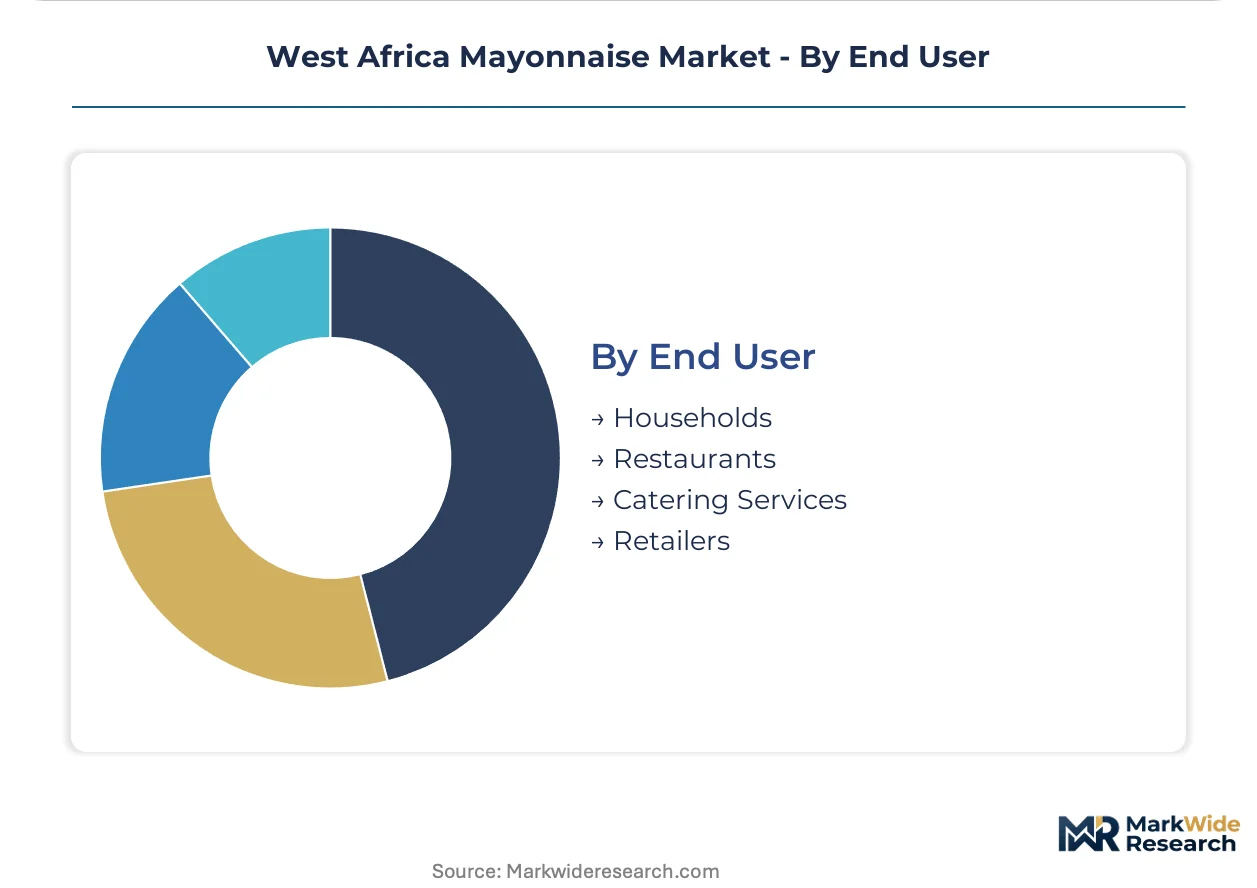
- Households:Domestic consumption across Nigerian and Ghanaian urban centers drives recurring purchase patterns. Supermarket and local market procurement splits by income tier.
- Restaurants:Quick-service operators in Lagos and Accra generate concentrated condiment demand through standardized menu specifications.
- Catering Services:Event-based bulk procurement with seasonal demand fluctuation.
- Retailers:Inventory holding for resale through formal and informal trade networks.
Households command the established base. Restaurant procurement is gaining share fastest through quick-service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco-based ingredient suppliers route North African oil and emulsifier stocks through Dakar and Bamako corridors. Nigerian manufacturers source palm oil domestically while importing specialized stabilizers through Lagos ports. Regional trade flows concentrate on three coastal demand centers with divergent regulatory regimes.
Nigeria
Lagos quick-service restaurants drive institutional mayonnaise procurement through sandwich and salad menu standardization. NAFDAC enforces mandatory product registration and Good Manufacturing Practice certification for all domestic and imported production. Ibadan manufacturing clusters adopt clean-label emulsification systems to meet supermarket buyer specifications.
Ghana
Accra's middle-class supermarket expansion generates glass jar demand for household stock-up behavior. The Food and Drugs Authority mandates standardized oil-content labeling with precise vegetable oil percentage disclosure on primary packaging. Kumasi informal trade channels prefer 20-gram pouch formats matching daily wage purchasing patterns.
Côte d'Ivoire
Abidjan food service operators generate concentrated condiment volume through West African franchise restaurant proliferation. The country's national food safety regulator aligns with ECOWAS harmonization timelines for unified protocol adoption. San Pedro port infrastructure enables refined oil import flows for domestic emulsion production.
Senegal
Dakar specialty retail channels create shelf space for vegan formulations using aquafaba and modified starch alternatives. The national food safety authority maintains distinct labeling requirements from Nigerian and Ghanaian regimes. Thiès industrial zone hosts emerging domestic manufacturers serving Francophone West African distribution networks.
Mali
Bamako informal trade channels absorb single-serve sachet formats through fragmented vendor networks. The landlocked geography amplifies logistics costs for temperature-sensitive emulsion products. Ségou agricultural processing zones supply domestic poultry operations supporting regional egg yolk lecithin availability.
West Africa Mayonnaise Market Key Industry Players
On the supply side, the industry is consolidating around multinational packaged food conglomerates with pan-African distribution infrastructure. Domestic manufacturers occupy price-sensitive tiers through informal channel specialization. Three strategic archetypes dominate: North Africa-anchored regional integrators, global FMCG giants with chilled-chain partnerships, and local pouch-format specialists. Competitive moves center on clean-label reformulation licensing and regional logistics operator acquisitions.
Among the multinational cohort, Nestle SA, Unilever PLC, and Kraft Heinz occupy positions defined by decades of table-spread brand recognition in Nigerian urban retail. These entities exemplify the scale-driven archetype through chilled-chain density and supermarket placement dominance. GB Foods represents the North Africa-anchored regional integrator model, leveraging Moroccan supply bases for Francophone West African penetration. Domestic specialists such as Pure Food Processing Industries and BM Foods sit within the informal-trade-focused tier, competing through sachet-format agility and local market responsiveness.
| Leading Market Players |
|---|
| GB Foods |
| Nestle SA |
| Nurevas |
| McCormick Corporation |
| Kraft Heinz |
| TGI |
| Pure Food Processing Industries |
| BM Foods |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Palm oil price volatility determines both pricing tier spreads and supply chain shape across West African mayonnaise manufacturing. Currency depreciation in Nigeria amplifies import cost exposure for refined vegetable oil supplies, forcing manufacturers to stratify formulations around domestic versus imported oil sourcing.
Pricing Analysis
Clean-label versus conventional emulsification technology defines the generational pricing gap in this market. Three-tier pricing structure across premium, standard, and economy levels separates NAFDAC-registered supermarket brands from informal pouch-format competitors. Price differentiation rests on NAFDAC registration status and chilled-chain certification. Cost compression in economy tiers is intensifying because informal entrants undercut registered products in fragmented local markets. Quick-service restaurants show least price sensitivity; cash-constrained household procurement through street vendors shows most.
Supply Chain Analysis
Contract manufacturing concentration sits with Nestle SA, Unilever PLC, and GB Foods operating captive production facilities across Nigeria and Ghana. Geographic supply concentration centers on Morocco for North African ingredient flows, Nigeria for domestic palm oil, and European ports for specialized stabilizer imports. Raw material dependencies draw from refined vegetable oils, egg yolk lecithin, and vinegar or citric acid acidifiers. Single-source vulnerability runs through fragmented Sahel poultry operations supplying emulsifier stocks. Distribution runs through regional logistics operators offering temperature-controlled last-mile coverage to supermarket and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward quick-service restaurant chains as Lagos and Accra sandwich-format expansion concentrates procurement volume. This consolidation among institutional buyers demands volume-commitment pricing from suppliers.
For Market Incumbents: Insulate margin position by deepening backward integration into domestic palm oil refining and securing multi-year chilled-chain partnerships with regional logistics operators. Nestle SA and Unilever PLC face substitution pressure from vegan formulation specialists capturing specialty retail shelf space in Accra and Lagos. For New Entrants and Emerging Players: Establish a beachhead in Senegal and Mali through GB Foods-style North African supply base leverage, targeting underpenetrated Francophone markets where distribution infrastructure gaps persist. Vegan formulation white space in Dakar specialty retail offers the most penetrable segment. Partner with regional logistics operators for asset-light market entry rather than building captive cold storage. For Investors and Strategic Acquirers: The market sits at a clean-label transition phase that favors mid-tier manufacturers with reformulation licensing capabilities and informal-trade pouch-format agility. Long-term viability hinges on ECOWAS harmonization execution and regulatory convergence timelines. Acquisition target archetype: domestic specialists with NAFDAC registration and sachet-format production lines. Quarterly review of ECOWAS protocol adoption progress and NAFDAC enforcement intensity is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Licensing | High-pressure processing adoption enables reduced-stabilizer production meeting Ghana FDA and NAFDAC specifications. |
| Chilled-Chain Partnership Expansion | Regional logistics operator acquisitions secure temperature-controlled distribution to secondary cities beyond Lagos and Accra. |
| Vegan Product Line Introduction | Aquafaba and modified starch alternatives capture lactose-intolerant consumers in Lagos and Accra specialty retail. |
| Francophone Market Penetration | Moroccan supply base leverage opens underpenetrated Senegal and Mali distribution networks. |
| Pouch Format Scale-Up | Single-serve sachet production matches cash-constrained purchasing patterns in informal Lagos Island and Accra Central channels. |
Research Approach
A standing panel of mayonnaise manufacturing plant managers, quick-service restaurant procurement heads, NAFDAC regulatory affairs officers, and regional logistics operators provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, NAFDAC product registration databases, Ghana Food and Drugs Authority labeling directives, and ECOWAS harmonization protocol documents. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, and distribution channel dimensions.
Scenario-bracketing framed analytical outputs across the projection horizon. Segmentation dimensions modeled include formulation tier, retail format, procurement channel, and regulatory compliance status. CAGRs were derived from trend extrapolation anchored to documented quick-service restaurant expansion and clean-label technology adoption curves. Forecast inputs incorporated vegetable oil price trajectory assumptions and ECOWAS convergence timeline scenarios.
Sensitivities concentrate around palm oil commodity volatility, naira depreciation severity, and avian influenza disruption to egg supply chains. Forecasts reflect documented assumptions on regulatory harmonization progress and chilled-chain infrastructure buildout. Quarterly review of NAFDAC enforcement actions, Ghana FDA labeling requirement amendments, and ECOWAS protocol ratification milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Condiments Market