
 Ketchup Market | 2026-2036
Ketchup Market Size, Share, and Industry Trends Forecast 2026-2036
Ketchup Market Outlook
Food service procurement is rebalancing toward premium and clean-label condiment programs as quick-service operators reduce artificial additive dependence. The Kraft Heinz Company anchors North American retail shelf presence through extensive manufacturing scale. Kagome competes in Asia-Pacific markets with tomato varietal specialization and regional recipe adaptation. Unilever extends its European footprint through diversified condiment portfolios spanning multiple price tiers.
Ketchup is a tomato-based condiment produced by cooking strained tomatoes with vinegar, sweeteners, and spices to a minimum 12 percent tomato solids content, functioning primarily as a flavor enhancer for fried foods, sandwiches, and processed meat applications. Organic and reduced sugar variants capture expanding margin pools as health-conscious consumers scrutinize ingredient panels. Squeezy bottle packaging dominates household convenience channels while bulk containers anchor food service supply contracts. Distribution through online retailers grows fastest as direct-to-pantry subscription models reduce traditional supermarket dependency.
FDA nutritional labeling requirements and EFSA food additive evaluations shape reformulation timelines and ingredient substitution costs across major producing jurisdictions. USDA organic certification and EU organic regulations create tiered market access thresholds that favor producers with established supply chain documentation. Stakeholders must monitor evolving sodium and sugar threshold policies in multiple jurisdictions to anticipate mandatory recipe adjustment cycles.
Market Dynamics
Clean-label reformulation mandates from EFSA and FDA are forcing simultaneous recipe overhauls across multiple producing jurisdictions, compressing reformulation timelines while elevating ingredient documentation costs for manufacturers.
Growth Catalysts
- EFSA Additive Scrutiny:European re-evaluation of artificial preservatives and colorants is accelerating natural ingredient substitution across premium product lines.
- Quick-Service Customization:Restaurant chains are expanding proprietary condiment programs that specify clean-label ketchup formulations for co-branded retail SKUs.
- Tomato Solids Innovation:Processing advances enabling higher concentrate yields from heirloom varietals are reducing sugar dependence in reduced-calorie formulations.
Market Restraints
- Tomato Paste Concentration:California and Xinjiang processing clusters control over 70% of global paste supply, creating geographic vulnerability to drought-induced price spikes.
- Sweetener Cost Volatility:High-fructose corn syrup and cane sugar price swings directly compress margin on standard-tier formulations.
- Glass Bottle Substitution:Food service operators are mandating PET and flexible pouch formats that require capital-intensive packaging line conversions.
Strategic Opportunities
- Direct-to-Pantry Subscriptions:Online retailers are capturing household volume through auto-replenishment models that bypass traditional supermarket slotting fees.
- USDA Organic Certification:Tiered organic regulations create premium shelf positioning that commands 40-60% price elevation over conventional equivalents.
- Fermented Ketchup Variants:Probiotic positioning aligns with gut-health consumer trends in German and Japanese functional food markets.
Industry Challenges
- Clean-Label Reformulation Talent:Food chemists with natural preservation expertise command premium compensation in tight labor markets.
- Dual Jurisdiction Compliance:Simultaneous FDA nutritional labeling updates and EFSA additive bans require parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketchup Market |
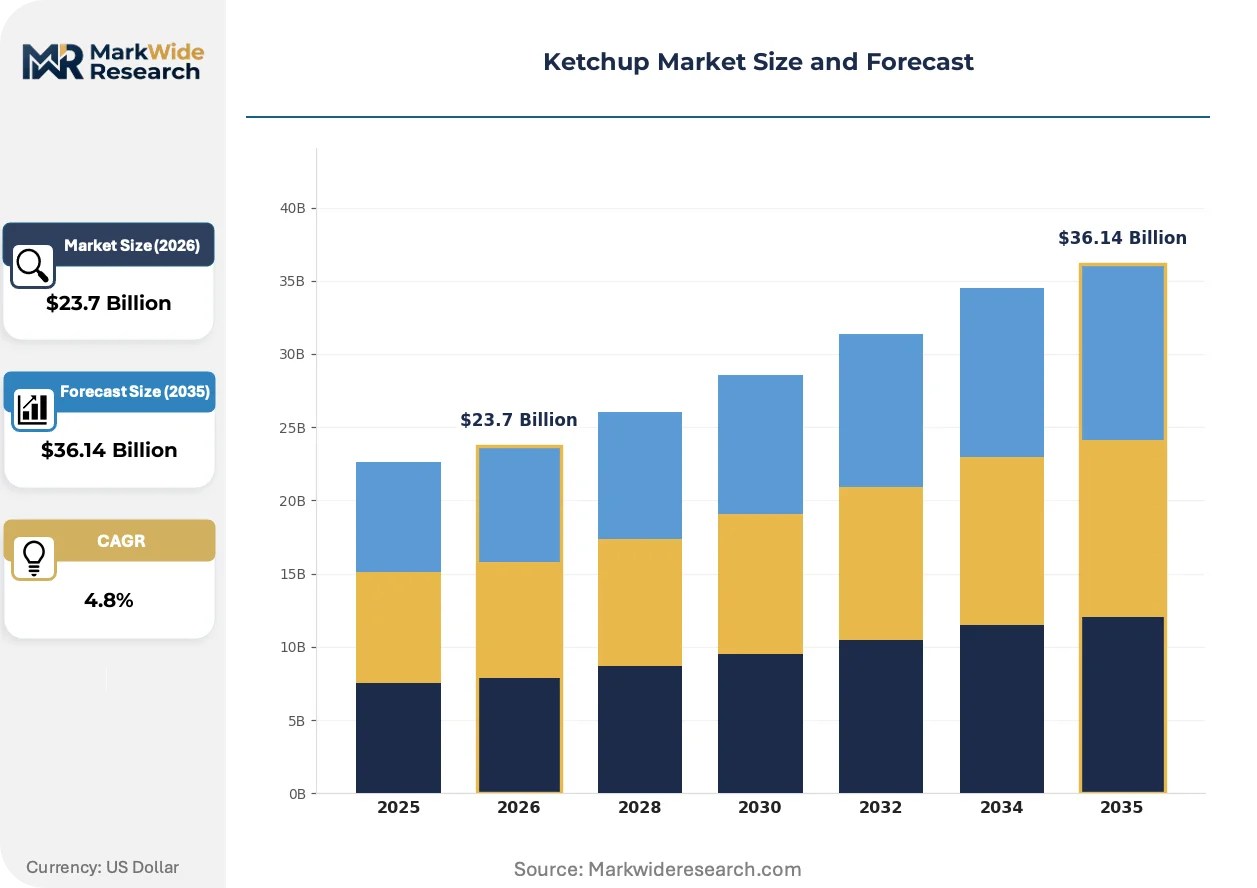
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Organic, Reduced Sugar, Spicy Packaging Type: Squeezy Bottle, Glass Jar, Pouch, Bulk Container Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Food Service End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Nestlé, Campbell Soup Company, The Kraft Heinz Company, Premier Foods, General Mills, Conagra Brands, Del Monte Foods, Kagome, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketchup Market Strategic Shifts
Reformulation science and packaging automation are converging to enable mass-market clean-label production at conventional price points. Three developments are compressing competitive differentiation cycles.
High-pressure processing technology is integrating into tomato paste sterilization workflows, eliminating thermal degradation of volatile flavor compounds. Mid-tier manufacturers are adopting HPP equipment to achieve clean-label positioning without organic ingredient cost premiums. The technology is integrating natural preservation capabilities into conventional supply chains, eroding the premium tier's taste-based differentiation.
EFSA's systematic re-evaluation of food additives under the reauthorization program is removing calcium disodium EDTA and tartrazine from approved preservative lists. European manufacturers face compressed 18-month transition windows to reformulate distributed inventory. Reduced-sugar variants encounter the steepest technical barriers, as alternative preservation systems must compensate for reduced osmotic stability.
Restaurant procurement teams are consolidating condiment specifications across franchise networks, replacing distributed purchasing with centralized clean-label mandates. Single-source contracts now specify additive-free formulations with volume commitments that lock out conventional suppliers. This concentration is most visible in United States quick-service chains, where procurement standardization is displacing regional formulation variation.
Ketchup Market Segmentation
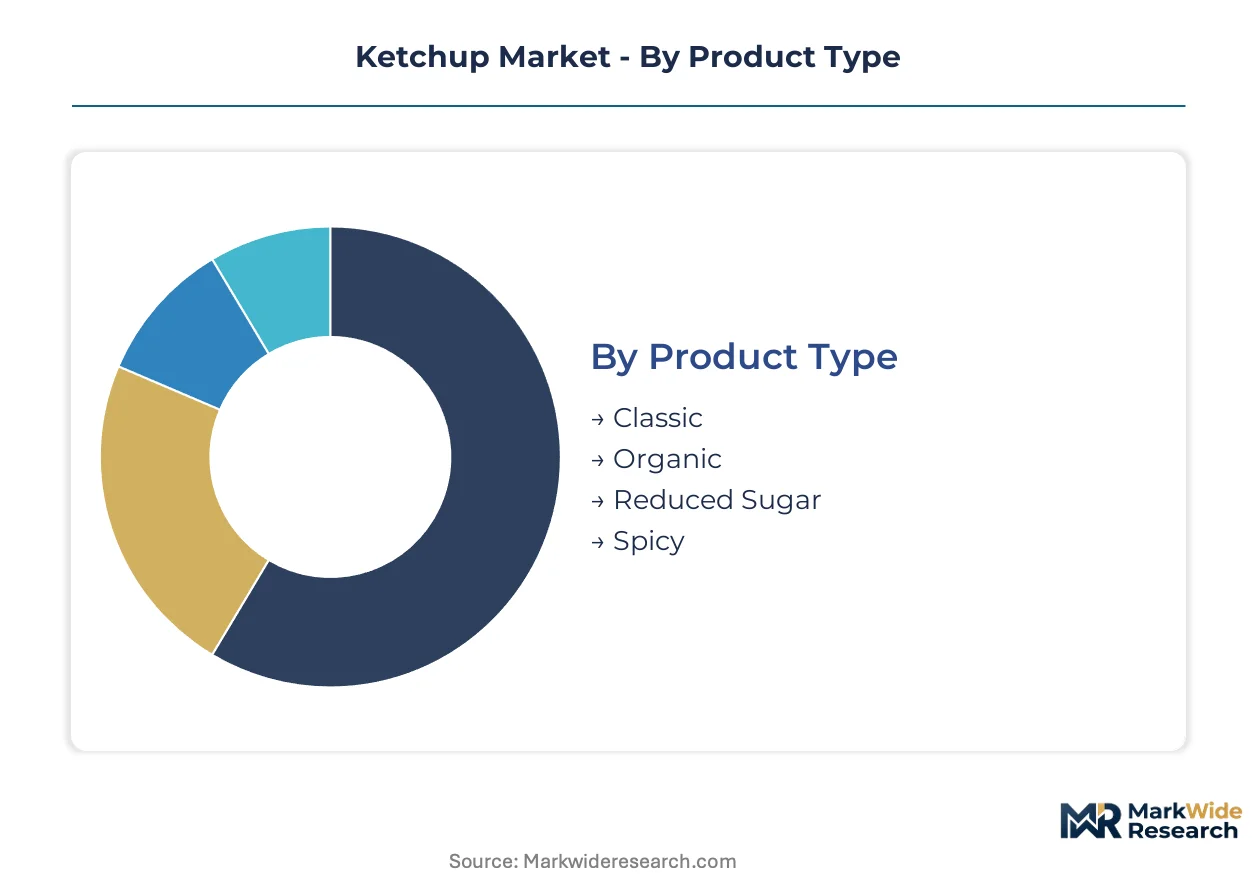
Ketchup segmentation reflects divergent certification burdens and supply chain requirements across conventional and premium tiers. Product positioning varies sharply by channel economics and end-use application specifications.
Product Type:
Organic variants require USDA certification or EU organic regulations compliance, while reduced-sugar formulations face additional FDA nutritional labeling scrutiny for modified nutrient claims.
- Classic:Standard tomato solids formulations meeting minimum 12 percent concentration specifications anchor retail volume through established vinegar-sweetener-spice profiles. Demand concentrates in United States quick-service chains where procurement standardization favors consistent, cost-optimized recipes. FDA nutritional labeling requirements apply without additive scrutiny complications.
- Organic:USDA organic certification and EU organic regulations mandate supply chain documentation from seed through processing. Germany and United States premium retail channels command 40-60% price elevation over conventional equivalents, with EFSA additive bans accelerating natural ingredient substitution timelines.
- Reduced Sugar:Alternative preservation systems compensate for osmotic stability loss in lower-calorie profiles.
- Spicy:Regional chili varietal adaptations target flavor differentiation in Asia-Pacific markets.
Leading the category by volume: Classic. Growing fastest: Organic.
Packaging Type:
Format selection correlates with channel margin structures and capital conversion requirements for filling line equipment.
- Squeezy Bottle:PET and multi-layer plastic constructions dominate household convenience channels with controlled-dispense functionality. Japan and United States retail shelves prioritize shelf-stable, shatter-resistant formats for family consumption occasions. Food service operators increasingly mandate this format for back-of-house efficiency.
- Glass Jar:Premium positioning in European retail maintains traditional aesthetic associations despite higher logistics costs. Germany specialty retailers and United States organic channels specify glass for perceived purity signaling. EFSA packaging material regulations impose stricter migration testing than FDA requirements.
- Pouch:Flexible format adoption accelerates in food service and single-serve applications.
- Bulk Container:Institutional procurement contracts specify aseptic bag-in-box or steel drum formats.
Dominating shelf presence: Squeezy Bottle. Expanding most quickly: Pouch.
Distribution Channel:
Channel economics determine slotting fee exposure and direct-to-pantry subscription viability.
- Supermarkets:Traditional retail gatekeepers extract substantial slotting fees that disadvantage emerging brands. United States and Germany hypermarket chains control household volume through promotional calendar coordination. Clean-label reformulation investments recover through premium shelf positioning negotiations.
- Online Retailers:Auto-replenishment subscription models bypass supermarket dependency while capturing recurring revenue. Direct-to-pantry logistics concentrate in United States urban corridors with same-day delivery infrastructure. E-commerce packaging regulations vary by state and municipality.
- Convenience Stores:Impulse-oriented single-serve and travel formats target immediate consumption.
- Food Service:Centralized procurement mandates specify additive-free formulations with volume commitments.
Capturing largest volume share: Supermarkets. Steepest expansion trajectory: Online Retailers.
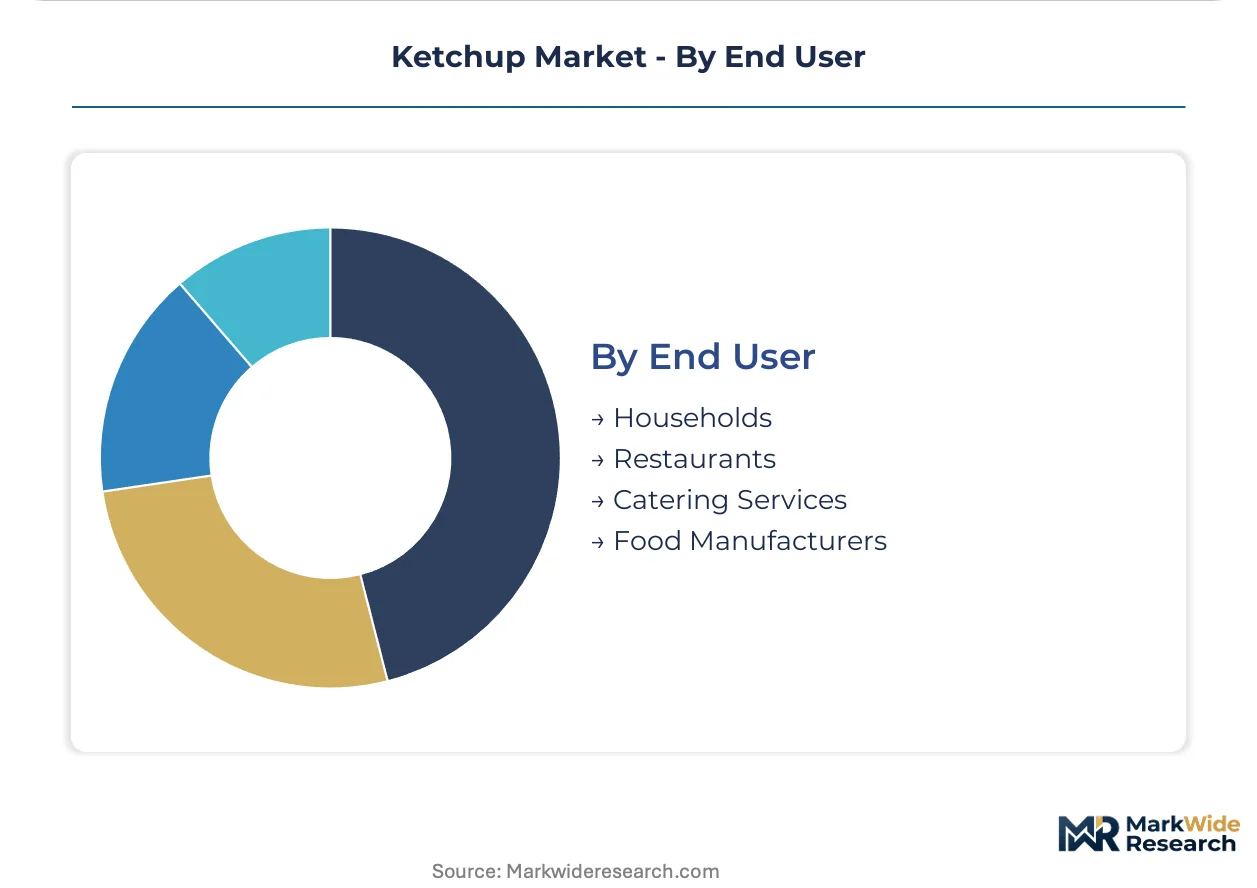
End User:
User specifications range from household taste preference to industrial ingredient compliance.
- Households:Consumer preference for clean-label ingredient panels drives premium private-label acceptance. United States and Japan households scrutinize sodium and sugar thresholds per FDA and national dietary guidelines. Squeezy bottle convenience dominates repeat purchase behavior.
- Restaurants:Quick-service chains consolidate condiment specifications across franchise networks with centralized clean-label mandates. United States burger and chicken chains specify proprietary formulations for co-branded retail SKU extensions. Procurement teams negotiate single-source contracts locking out conventional suppliers.
- Catering Services:Bulk format procurement prioritizes portion control and waste reduction.
- Food Manufacturers:Ingredient-grade specifications require tomato solids consistency for processed meat and sauce applications.
Generating highest absolute volume: Households. Fastest specification tightening: Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in tomato processing regions concentrate production capacity and attract clean-label reformulation investment. Tax incentives for organic certification in California's Central Valley and Italy's Po Valley anchor supply chain documentation systems. FDA nutritional labeling requirements in the United States and EFSA additive reauthorization timelines in Europe create parallel compliance burdens that favor producers with established multi-jurisdiction quality systems.
United States
Quick-service restaurant chains consolidate condiment specifications across franchise networks, driving demand for proprietary clean-label formulations. FDA nutritional labeling updates mandate modified nutrient claim documentation for reduced-sugar variants. California's Central Valley processing clusters control tomato paste supply for North American formulation facilities.
Germany
Organic retail channels command 40-60% price elevation over conventional equivalents, with consumers scrutinizing EFSA-compliant ingredient panels. EFSA additive reauthorization programs ban calcium disodium EDTA and tartrazine, compressing reformulation timelines to 18 months. Hamburg and Berlin specialty retailers specify glass jar formats for perceived purity signaling in premium positioning.
Japan
Household demand for squeezy bottle convenience dominates repeat purchase behavior in urban corridors. METI guidelines on functional food claims support probiotic positioning for fermented ketchup variants. Kanto region manufacturing facilities specialize in tomato varietal adaptation for regional recipe profiles.
China
Food service procurement teams specify bulk container formats for institutional supply contracts in expanding quick-service networks. SAMR food additive regulations impose documentation requirements parallel to FDA and EFSA standards. Xinjiang processing clusters supply concentrated paste to domestic formulation plants despite drought vulnerability.
United Kingdom
Premium private-label offerings gain shelf space in supermarket channels as consumers shift toward clean-label ingredient scrutiny. UK organic regulations align with EU standards post-transition, maintaining certification burden for imported formulations. London and Southeast retail corridors concentrate distribution infrastructure for direct-to-pantry subscription models.
Ketchup Market Competitive Environment
Top-tier vendors anchor retail shelf presence through manufacturing scale, while mid-tier specialists occupy clean-label niches. The vendor base stratifies across three archetypes: diversified food conglomerates with condiment portfolios, tomato-specialist processors with varietal expertise, and private-label manufacturers serving retail channel specifications. Competitive moves concentrate on clean-label reformulation capacity expansion and direct-to-pantry distribution partnerships.
Among diversified food conglomerates, The Kraft Heinz Company and Nestlé exemplify scale-driven archetypes with extensive North American retail penetration. Kagome occupies a position within the tomato-specialist tier, representing regional recipe adaptation capabilities in Asia-Pacific markets. Unilever anchors the European multi-tier portfolio archetype, spanning conventional and premium condiment positioning across diversified price points.
| Leading Market Players |
|---|
| Nestlé |
| Campbell Soup Company |
| The Kraft Heinz Company |
| Premier Foods |
| General Mills |
| Conagra Brands |
| Del Monte Foods |
| Kagome |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Tomato paste futures indices in California and Xinjiang anchor cost structures across formulation tiers, cascading through concentrate procurement contracts into finished goods pricing. Premium organic SKUs absorb documentation and certification premiums while conventional formulations compete on spot paste availability and sweetener cost arbitrage.
Pricing Analysis
Lead-time contracting creates tiered value capture, with quick-service restaurant chains paying premiums for 30-day guaranteed supply windows while spot purchasers access discounted inventory during harvest surplus windows. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier formulations is intensifying because high-fructose corn syrup price volatility directly squeezes margin on high-volume SKUs. Household consumers exhibit highest price sensitivity in squeezy bottle convenience formats, while food service procurement teams prioritize supply security over unit cost in centralized clean-label mandates.
Supply Chain Analysis
Reverse-logistics flows for glass jar returns and bulk container refurbishment create secondary value recovery streams in European and Japanese circular packaging programs. Geographic supply concentration centers on California's Central Valley, Xinjiang's processing clusters, and Italy's Po Valley for tomato paste production. Raw material dependencies draw from high-fructose corn syrup, cane sugar, and vinegar feedstocks. Single-source vulnerability in California-Xinjiang paste supply creates drought exposure risk. Distribution runs through supermarket slotting fee gatekeepers, direct-to-pantry subscription platforms, and food service centralized procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology is displacing thermal sterilization in clean-label reformulation, compressing competitive differentiation cycles and forcing legacy equipment write-downs across mid-tier manufacturing facilities.
For Market Incumbents: Lock in long-term paste supply contracts with California and Xinjiang processors before drought-induced price spikes accelerate. Secure HPP equipment financing now to achieve clean-label positioning without organic ingredient cost premiums. Backward integration into heirloom tomato varietal cultivation in California's Central Valley defends margin position against concentrate yield competition from Kagome and emerging Asia-Pacific specialists.
For New Entrants and Emerging Players: Direct-to-pantry subscription platforms represent the most penetrable channel for bypassing supermarket slotting fee barriers. Target fermented ketchup variants in German and Japanese functional food markets where probiotic positioning commands premium shelf space. White-label manufacturing for quick-service restaurant co-branded retail SKUs offers volume commitment security without brand building investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier clean-label reformulation specialists in California and Italy's Po Valley with established USDA organic certification infrastructure. Long-term viability hinges on multi-jurisdiction compliance capability spanning FDA nutritional labeling and EFSA additive reauthorization timelines. Monitor EFSA systematic additive bans for inflection signals on forced consolidation among conventional formulation-dependent producers.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Equipment Deployment | Enables clean-label sterilization without thermal degradation of volatile flavor compounds in tomato paste processing. |
| Organic Certification Investment | USDA and EU organic regulations create tiered market access thresholds commanding 40-60% price elevation. |
| Direct-to-Pantry Subscription Launch | Auto-replenishment models bypass supermarket slotting fees while capturing recurring revenue in United States urban corridors. |
| Heirloom Varietal Cultivation | Specialized tomato genetics reduce sugar dependence in reduced-calorie formulations for health-conscious consumers. |
| Food Service Procurement Consolidation | Centralized clean-label mandates across quick-service franchise networks lock out conventional suppliers through volume commitments. |
Study Parameters
Document review covered FDA nutritional labeling guidance, EFSA additive reauthorization documentation, and USDA organic certification standards, complemented by interviews with tomato paste procurement directors at quick-service restaurant chains, clean-label reformulation chemists at mid-tier manufacturers, and category buyers at United States and German supermarket chains. Secondary validation drew from customs trade data on tomato paste imports, SEC 10-K filings of diversified food conglomerates, and Nielsen retail audit data on condiment shelf velocity. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Segment-level projections across product type, packaging format, distribution channel, and end-user application dimensions were derived through elasticity-adjusted trend extrapolation over the projection horizon. CAGRs were computed from log-linear regression on normalized volume and value trajectories, incorporating tomato paste price index volatility, sweetener cost forecast ranges, and regulatory compliance timeline assumptions as industry-specific inputs.
Caveats apply where EFSA additive ban acceleration, FDA nutritional labeling enforcement tightening, or California drought severity could materially shift the outlook. Practitioners should monitor tomato paste futures pricing, quick-service procurement mandate standardization, and HPP equipment financing availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Sour Dressings Market