
 Thermoforming Machines Market | 2026-2036
Thermoforming Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoforming Machines Market Analysis
Aftermarket service revenue is rewriting profit architecture across the thermoforming equipment sector. Brown Machine Group leverages its North American installed base to capture recurring retrofit and spare-part streams. Kiefel Technologies anchors European medical and automotive demand through precision pressure-forming platforms. Illig Maschinenbau dominates high-speed packaging lines with tool-less quick-change systems that minimize downtime.
Thermoforming machines heat thermoplastic sheets to pliable temperatures, then use vacuum, pressure, or mechanical force to mold them against patterned dies, typically processing materials from 0.25 mm to 12 mm thickness at cycle speeds up to 60 strokes per minute for thin-gauge packaging. Vacuum forming retains the largest installed base due to its lower capital threshold and operational simplicity, though pressure forming claims expanding share in automotive interior panels and medical device housings where dimensional tolerance tightens. Twin sheet forming commands premium positioning by producing hollow structural parts such as HVAC ducts and fluid reservoirs in a single cycle, eliminating secondary welding.
FDA food-contact regulations and EU REACH compliance on polymer additives compel machine builders to validate processing windows that prevent thermal degradation of polyethylene and polypropylene. ISO 9001 quality management and CE machinery directives further govern export market access, particularly for German and Italian OEMs shipping into Asian manufacturing clusters. Stakeholders must monitor how evolving extended-producer-responsibility frameworks in the European Union and select US states reshape material specifications and retrofit requirements for legacy equipment fleets.
Market Dynamics
Extended-producer-responsibility frameworks in the European Union and California are forcing food packaging manufacturers to retrofit legacy thermoforming lines for recyclable mono-material processing, compressing equipment replacement cycles and elevating aftermarket service intensity.
Growth Catalysts
- FDA food-contact material regulations:Tightening compliance windows in the United States compel polyethylene and polypropylene processors to validate thermal processing windows, driving precision control system upgrades across installed bases.
- Automotive interior panel demand:Pressure forming technology captures expanding share as German and Czech OEMs source dimensional-tolerant housings for electric vehicle battery enclosures and dashboard assemblies.
- Twin-sheet forming:Hollow structural part production in single-cycle HVAC duct and fluid reservoir manufacturing eliminates secondary welding, commanding premium positioning in heavy equipment and agricultural machinery supply chains.
Market Restraints
- Specialized steel and aluminum die costs:Tooling lead times stretch 12-20 weeks for complex medical device housings, constraining rapid product changeover capabilities for mid-scale contract manufacturers.
- German precision engineering concentration:High-throughput forming system supply clusters in Baden-Württemberg and Bavaria create geographic vulnerability to energy price volatility and skilled labor tightness.
- Injection molding substitution:Thin-wall packaging applications below 0.5 mm thickness increasingly migrate to high-speed injection systems where cycle economics favor liquid resin over sheet stock.
Strategic Opportunities
- India packaging modernization:FSSAI food safety mandates and plastic waste management rules are accelerating thermoforming equipment imports for processed food and dairy container production in Maharashtra and Gujarat.
- Medical device cleanroom integration:ISO 14644-compliant pressure forming systems for surgical tray and implant packaging represent underpenetrated white space as hospital sterilization standards tighten.
- Digital twin convergence:Real-time thermal mapping and predictive maintenance algorithms are hybridizing with legacy vacuum forming architectures to reduce unplanned downtime in high-volume operations.
Industry Challenges
- Controls engineering talent scarcity:PLC programming and servo-motion calibration expertise for multi-axis pressure forming systems concentrates among aging technician cohorts in Midwestern US manufacturing corridors.
- CE machinery directive certification timelines:German and Italian OEMs face 6-9 month validation cycles for Asian export markets, delaying revenue recognition on customized automotive and medical equipment builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoforming Machines Market |
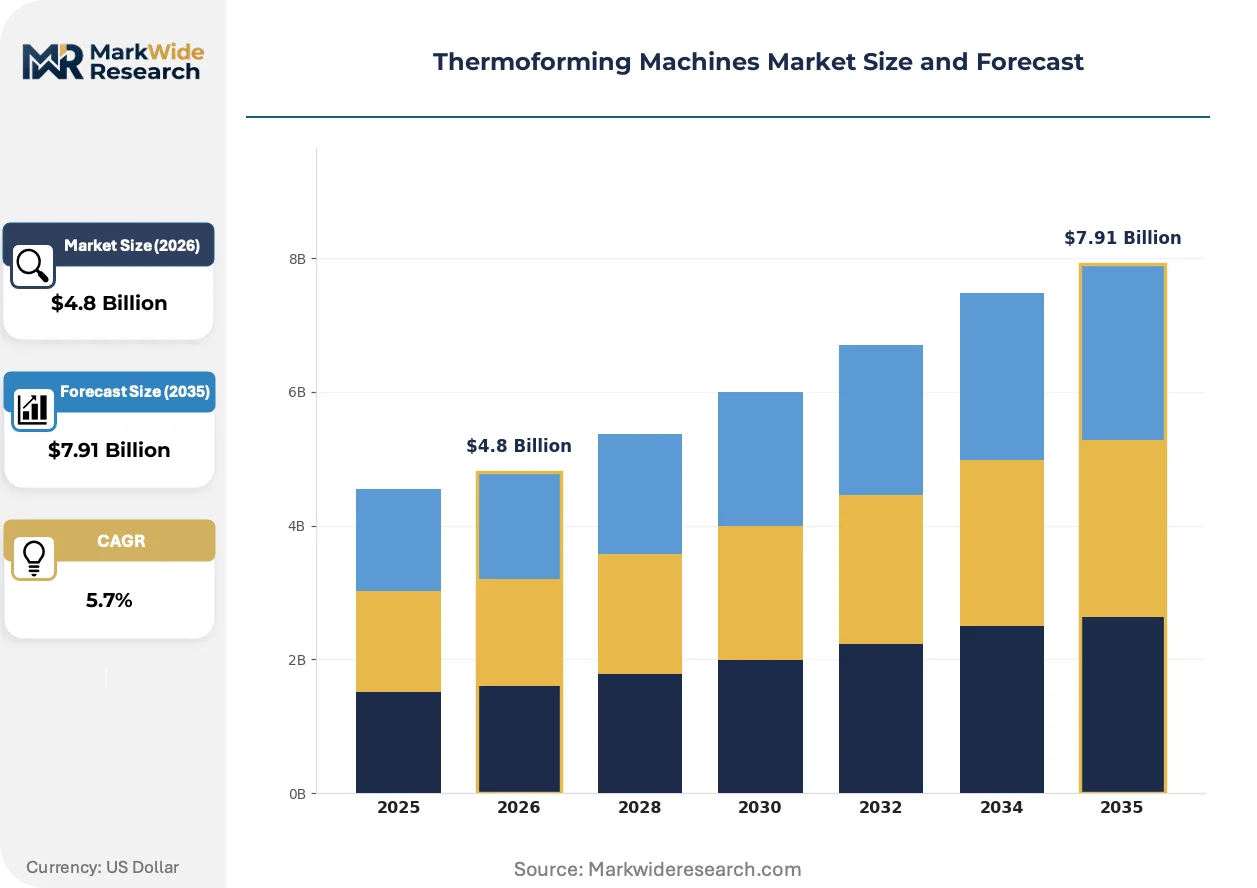
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Forming, Pressure Forming, Twin Sheet Forming, Bi-axial Forming Material: Polyethylene, Polypropylene, Polystyrene, ABS Application: Packaging, Automotive Parts, Medical Devices, Consumer Goods End User: Manufacturers, Retailers, Distributors, Exporters |
| Companies Covered | Brown Machine Group, GABLER Thermoform, Illig Maschinenbau, Asano Laboratories, COMI SpA, Kiefel Technologies, MAAC Machinery, TZ Machinery, Multivac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoforming Machines Market Emerging Trajectories
Equipment architecture is pivoting from standalone forming stations to integrated process cells where heating, forming, trimming, and stacking operations synchronize through unified control platforms. This convergence compresses floor space requirements while elevating throughput consistency.
Electromagnetic susceptors for contactless sheet heating are hybridizing with conventional radiant and conduction systems. Automotive Tier-1 suppliers in Stuttgart and Detroit adopt these hybrid thermal systems for polypropylene composite panels where temperature uniformity across 2-meter sheet widths tightens dimensional tolerances. The technology is compressing energy intensity per formed part while enabling faster cycle transitions between material grades.
EU REACH compliance on polymer additives and the F-Gas Regulation phase-down are reshaping material processing windows. Machine builders must validate forming temperatures that prevent thermal degradation of recycled polyethylene streams while maintaining FDA food-contact safety margins. German OEMs shipping into Asian manufacturing clusters face dual certification burdens that extend engineering resource allocation and compress margin structures on standard equipment lines.
Aftermarket service unbundling is fragmenting traditional bundled maintenance contracts. Food packaging converters in California and New York separately procure spare-part inventories, remote diagnostic subscriptions, and on-site technician dispatch through discrete vendor relationships. This purchasing pattern shift is most visible among mid-scale dairy and produce container manufacturers seeking to match service expenditure to seasonal production volatility rather than fixed annual contracts.
Thermoforming Machines Market Segmentation
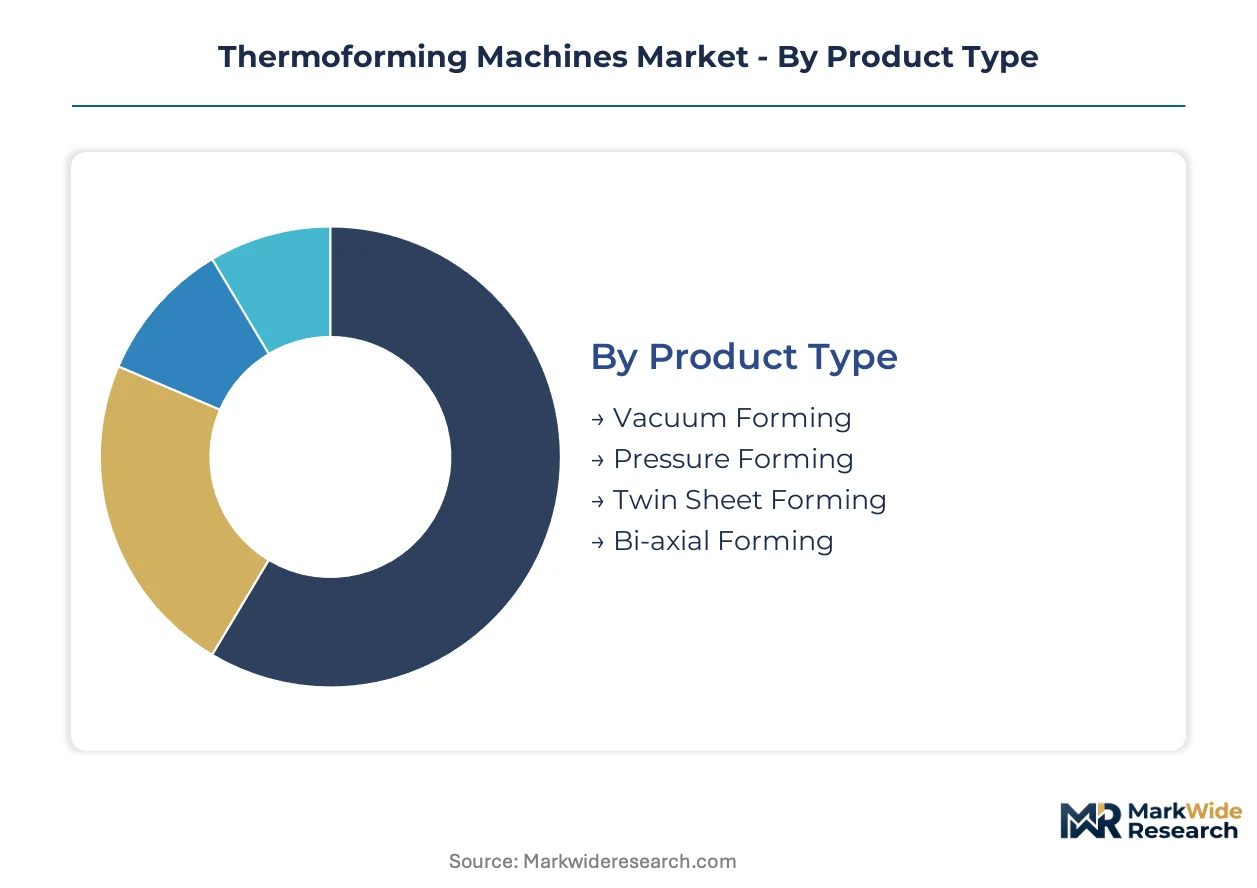
Equipment segmentation in thermoforming machines reveals divergent capital intensity and replacement cadences. Cycle economics vary dramatically across forming technologies, material specifications, and end-use applications, shaping procurement patterns and aftermarket service attach rates.
Product Type:
Vacuum forming cycles fastest on capital deployment, with pressure forming stretching replacement windows and twin-sheet systems anchoring decade-long asset lives.
- Vacuum Forming:Atmospheric pressure draws heated thermoplastic sheets against single-sided molds, processing materials from 0.25 mm to 6 mm thickness. Food packaging converters in California and New York favor these systems for polyethylene tray production where FDA food-contact compliance demands tight thermal control windows.
- Pressure Forming:Compressed air up to 100 psi forces material against female molds, capturing intricate textures and undercuts impossible with vacuum alone. German automotive Tier-1 suppliers in Baden-Württemberg specify these platforms for polypropylene battery enclosures and dashboard assemblies where dimensional tolerances tighten.
- Twin Sheet Forming:Simultaneously forms two sheets welded at the perimeter, producing hollow structural parts in single-cycle operations. Agricultural machinery OEMs source HVAC ducts and fluid reservoirs through this technology.
- Bi-axial Forming:Stretches heated sheet mechanically in perpendicular directions before vacuum or pressure application, orienting molecular chains for enhanced clarity and impact resistance. Medical device housings in Czech manufacturing clusters exploit this capability.
Vacuum forming dominates installed base. Pressure forming is where expansion concentrates.
Material:
Raw material selection governs heating system specifications, forming temperature windows, and downstream recycling economics.
- Polyethylene:Linear and branched grades dominate thin-gauge food packaging where FDA compliance on thermal degradation thresholds compels precise temperature profiling. Dairy container manufacturers in Maharashtra prioritize high-density grades for stiffness-to-weight optimization.
- Polypropylene:Copolymer formulations capture automotive interior panel demand through superior heat resistance and surface finish. Stuttgart-based OEMs specify talc-filled grades for battery enclosure applications.
- Polystyrene:Crystal and high-impact grades serve disposable food service and electronics packaging where clarity and printability matter.
- ABS:Acrylonitrile-butadiene-styrene copolymers command medical device and consumer electronics housings where impact strength and aesthetic surface quality justify premium resin costs.
Polyethylene commands volume leadership. Polypropylene represents the steepest expansion trajectory.
Application:
End-use verticals impose divergent regulatory burdens and performance specifications on machine configuration.
- Packaging:Blister packs, clamshells, and food trays constitute the largest addressable equipment demand. EU REACH compliance on polymer additives and extended-producer-responsibility frameworks in California force retrofit cycles on legacy polyethylene and polypropylene processing lines.
- Automotive Parts:Door panels, instrument clusters, and battery enclosures require pressure forming or twin-sheet systems with robotic trimming integration. Czech and German OEMs source dimensional-tolerant housings for electric vehicle architectures.
- Medical Devices:Surgical trays, implant packaging, and diagnostic housings demand ISO 14644 cleanroom-compatible pressure forming with validated sterilization barrier properties.
- Consumer Goods:Appliance housings, recreational equipment, and point-of-purchase displays span the technology spectrum from vacuum to pressure forming depending on aesthetic complexity.
Packaging anchors installed capacity. Medical devices is where premium system sales concentrate.
End User:
Procurement sophistication and service contract structures fragment sharply across buyer categories.
- Manufacturers:Integrated converters operating captive forming lines drive specification complexity, demanding tool-less quick-change systems and unified control platforms that synchronize heating, forming, trimming, and stacking.
- Retailers:Private-label packaging programs increasingly specify thermoformed containers directly, bypassing traditional converter relationships and forcing equipment decisions upstream.
- Distributors:Equipment financing and lease structures concentrate among mid-scale contract manufacturers seeking to match capital expenditure to seasonal production volatility.
- Exporters:CE machinery directive certification and FDA validation requirements dominate procurement criteria for German and Italian OEMs shipping into Asian manufacturing clusters.
Manufacturers dominate equipment ownership. Retailers is where procurement pattern disruption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit the lowest price elasticity, prioritizing precision and regulatory compliance over capital expenditure. Indian and Chinese converters remain most sensitive to equipment cost, driving localization strategies among multinational suppliers.
United States
Food packaging converters in California and New York accelerate equipment upgrades as FDA food-contact material regulations tighten and extended-producer-responsibility mandates spread across state lines. The EPA oversees industrial emissions standards affecting heating system specifications. Brown Machine Group anchors its North American aftermarket service operations from Michigan, capturing recurring retrofit revenue from dairy and produce container manufacturers.
Germany
Automotive and medical device OEMs in Baden-Württemberg and Bavaria source high-throughput pressure-forming systems for electric vehicle battery enclosures and surgical tray packaging. The KBA enforces machinery safety standards that extend CE certification timelines for Asian export orders. Kiefel Technologies occupies the precision engineering corridor, validating thermal processing windows for REACH-compliant polymer additives.
India
FSSAI food safety mandates and plastic waste management rules accelerate thermoforming equipment imports for processed food and dairy container production. The BIS governs machinery safety certifications for imported forming systems. Maharashtra and Gujarat manufacturing clusters absorb European and East Asian equipment shipments as packaging modernization outpaces domestic fabrication capacity.
China
Automotive Tier-1 suppliers in the Yangtze River Delta adopt hybrid thermal systems for polypropylene composite panels as MIIT promotes energy efficiency in manufacturing equipment. The SAMR oversees quality certification for imported machinery. Shanghai and Jiangsu province converters balance cost pressures against tightening GB standards for food-contact materials.
Japan
Medical device manufacturers in the Kansai region demand ISO 14644-compliant pressure-forming systems for implant packaging and diagnostic housings. METI coordinates industrial technology roadmaps that favor electromagnetic susceptor integration. Osaka-based precision engineering networks specialize in bi-axial forming equipment for high-clarity medical applications.
Thermoforming Machines Market Vendor Landscape
Capability concentration sits with German precision engineering specialists; scale advantage sits with North American aftermarket service platforms. The vendor base stratifies across three tiers: European precision OEMs commanding premium positioning in automotive and medical verticals, North American integrated providers monetizing installed-base service intensity, and East Asian fabricators capturing cost-sensitive packaging demand in emerging markets. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing agreements that accelerate local certification timelines.
Within the European precision tier, Kiefel Technologies and Illig Maschinenbau exemplify engineering-intensive positioning anchored in German manufacturing clusters. Brown Machine Group represents the North American aftermarket archetype, leveraging regional installed-base density to unbundle service contracts into discrete spare-part, diagnostic, and technician-dispatch revenue streams. COMI SpA occupies Italian fabrication expertise serving Mediterranean and Middle Eastern export markets where CE machinery directives govern procurement specifications.
| Leading Market Players |
|---|
| Brown Machine Group |
| GABLER Thermoform |
| Illig Maschinenbau |
| Asano Laboratories |
| COMI SpA |
| Kiefel Technologies |
| MAAC Machinery |
| TZ Machinery |
| Multivac |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors transmit steel and aluminum die cost volatility directly into equipment pricing tiers, concentrating margin pressure on mid-scale contract manufacturers while amplifying price differentiation between German precision OEMs and East Asian fabricators.
Pricing Analysis
Aftermarket service revenue streams anchor lifetime value capture across installed bases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic delivery cost, with FDA-validated systems commanding substantial premiums over CE-only configurations. Cost compression in standard equipment tiers intensifies as East Asian fabricators expand export capacity. Retailer-direct procurement patterns exhibit highest price sensitivity; automotive Tier-1 suppliers demonstrate lowest elasticity.
Supply Chain Analysis
Supplier financing facilities from Baden-Württemberg engineering networks extend 90-120 day payment terms to stabilize working capital for tooling fabricators. Germany, Italy, and China concentrate high-precision forming system production. Specialized steel dies, aluminum molds, and servo-motion control modules constitute critical input dependencies. Single-source vulnerability concentrates in electromagnetic susceptor components sourced through Japanese precision engineering networks. Distribution runs through authorized dealer networks with captive service arms in North America and direct OEM relationships in European automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food packaging retailers consolidating private-label specifications, fragmenting traditional converter-equipment manufacturer relationships and forcing specification decisions upstream.
For Market Incumbents: Harden aftermarket service moats by unbundling maintenance contracts into discrete diagnostic subscriptions and spare-part inventory programs. Deepen captive control over electromagnetic susceptor supply chains to mitigate Japanese single-source exposure. Pressure forming technology substitution from injection molding systems threatens thin-gauge packaging applications below 0.5 millimeter thickness.
For New Entrants and Emerging Players: Pursue ISO 14644-compliant cleanroom system white space in medical device packaging where incumbent penetration remains limited. Maharashtra and Gujarat manufacturing clusters present the most penetrable geography as FSSAI mandates accelerate equipment import demand. Go-to-market execution should anchor on equipment financing partnerships with Indian non-banking financial companies.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized thermoforming equipment divisions lacking aftermarket service infrastructure. Long-term viability hinges on recurring revenue attachment rates exceeding transactional equipment sale cyclicality. Monitor FDA food-contact regulatory revision timelines as inflection indicators for retrofit demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Discrete revenue streams from diagnostic subscriptions capture recurring value from California dairy container manufacturers. |
| Electromagnetic Susceptor Integration | Hybrid thermal systems reduce energy intensity per formed part for Stuttgart automotive Tier-1 suppliers. |
| Cleanroom Certification Investment | ISO 14644-compliant platforms unlock surgical tray packaging demand from Osaka medical device networks. |
| Geographic Distribution Partnership | Localized certification support accelerates CE machinery directive timelines for Asian export orders. |
| Tool-less Quick-Change Development | Rapid die exchange capabilities minimize downtime for high-throughput polyethylene tray production. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade databases, machinery safety certification records, and industry association technical reports. Bottom-up equipment shipment tracking and top-down end-use demand modeling provided triangulation across the analysis window.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include forming technology type, material specification, end-use application vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and aftermarket service intensity curves. Industry-specific forecast inputs incorporated FDA compliance timeline probabilities and EU extended-producer-responsibility implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in energy price volatility, steel input costs, or cross-border machinery tariff regimes would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market