
 Cutter Suction Dredger (CSD) Market | 2026-2036
Cutter Suction Dredger (CSD) Market Size, Share, and Industry Trends Forecast 2026-2036
Cutter Suction Dredger (CSD) Market Insights
EU Green Deal emission benchmarks is rebalancing the cost-of-entry calculus for European fleet operators, compelling investment in hybrid-electric propulsion architectures. Royal IHC leverages its integrated design-to-delivery model to sustain competitive positioning in high-specification contracts. Damen Shipyards Group anchors its presence through standardized platform designs that reduce yard time and capital risk. Boskalis competes on project bundling, combining dredging with marine construction to capture integrated contract value.
A cutter suction dredger is a stationary dredging vessel equipped with a rotating cutter head at the suction inlet to disaggregate compacted soils, slurry pumps conveying material through floating pipelines at discharge rates typically exceeding 5,000 cubic meters per hour, primarily deployed for capital dredging in ports, rivers, and land reclamation sites. Hydraulic type systems dominate the installed base due to proven reliability in cohesive sediments, while electric variants represent the fastest-growing category as harbor authorities impose shore-power compatibility and emission control area compliance. Port development applications command the largest share of contract value, though land reclamation projects in coastal megacities concentrate the premium-margin pool where specialized cutter heads and long-distance pumping configurations justify higher day rates.
EMA emission guidelines, IMO MARPOL Annex VI protocols, and national port authority green procurement standards collectively reshape vessel specifications, restricting market access for builders lacking hybrid-electric or LNG-ready platform offerings. The US EPA and China's MEE enforce parallel discharge and air quality constraints that ripple through global supply chains, elevating certification costs for cross-border projects. Stakeholders must monitor regulatory divergence between emission control zones and emerging carbon border mechanisms to align fleet renewal cycles with compliance windows.
Market Dynamics
Hybrid-electric propulsion architectures are restructuring capital allocation across the CSD fleet, as port authorities in emission control zones now mandate shore-power compatibility and tiered emission benchmarks before contract eligibility.
Growth Catalysts
- Channel deepening mandates:Indonesia's Pelabuhan Indonesia and Vietnam Maritime Administration accelerate harbor modification programs, requiring high-capacity stationary dredgers for access channel maintenance.
- EU Green Deal benchmarks:The European Commission's emission reduction pathways compel fleet operators to replace legacy diesel-hydraulic units with LNG-ready or battery-hybrid platforms to retain concession access.
- Land reclamation scale:Coastal megacity expansion in Southeast Asia generates concentrated demand for long-distance pumping configurations capable of conveying fill material beyond 15 kilometers.
Market Restraints
- Specialized steel and component concentration:High-tensile steel plate and precision cutter head forgings concentrate among German and Dutch metallurgical suppliers, exposing build schedules to single-source bottlenecks.
- IMO MARPOL Annex VI compliance costs:Tier III NOx certification and exhaust after-treatment systems add substantial capital burden to newbuild specifications, compressing margins for mid-tier yards.
- Fixed pipeline logistics:Floating discharge line deployment requires extensive auxiliary vessel support, limiting operational flexibility compared to self-propelled trailing suction alternatives in certain channel geometries.
Strategic Opportunities
- Carbon border adjustment preparedness:The EU's emerging carbon border mechanism creates first-mover advantage for builders offering lifecycle-emission documentation and modular retrofit pathways.
- Autonomous cutter positioning:Integration of dynamic positioning systems with real-time soil density sensors enables precision dredging in environmentally sensitive seabed zones previously excluded from development.
- Secondary equipment leasing:Project bundling by marine contractors opens aftermarket revenue streams through cutter head and pump package rental to smaller regional operators lacking full fleet ownership.
Industry Challenges
- Marine hydraulic system specialization:Shortage of technicians certified in high-pressure slurry pump maintenance and cutter head drivetrain repair extends vessel downtime and inflates crew costs.
- Cross-jurisdictional certification timelines:Dual-class approval processes for simultaneous IMO compliance and national flag state registration delay delivery schedules by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutter Suction Dredger (CSD) Market |
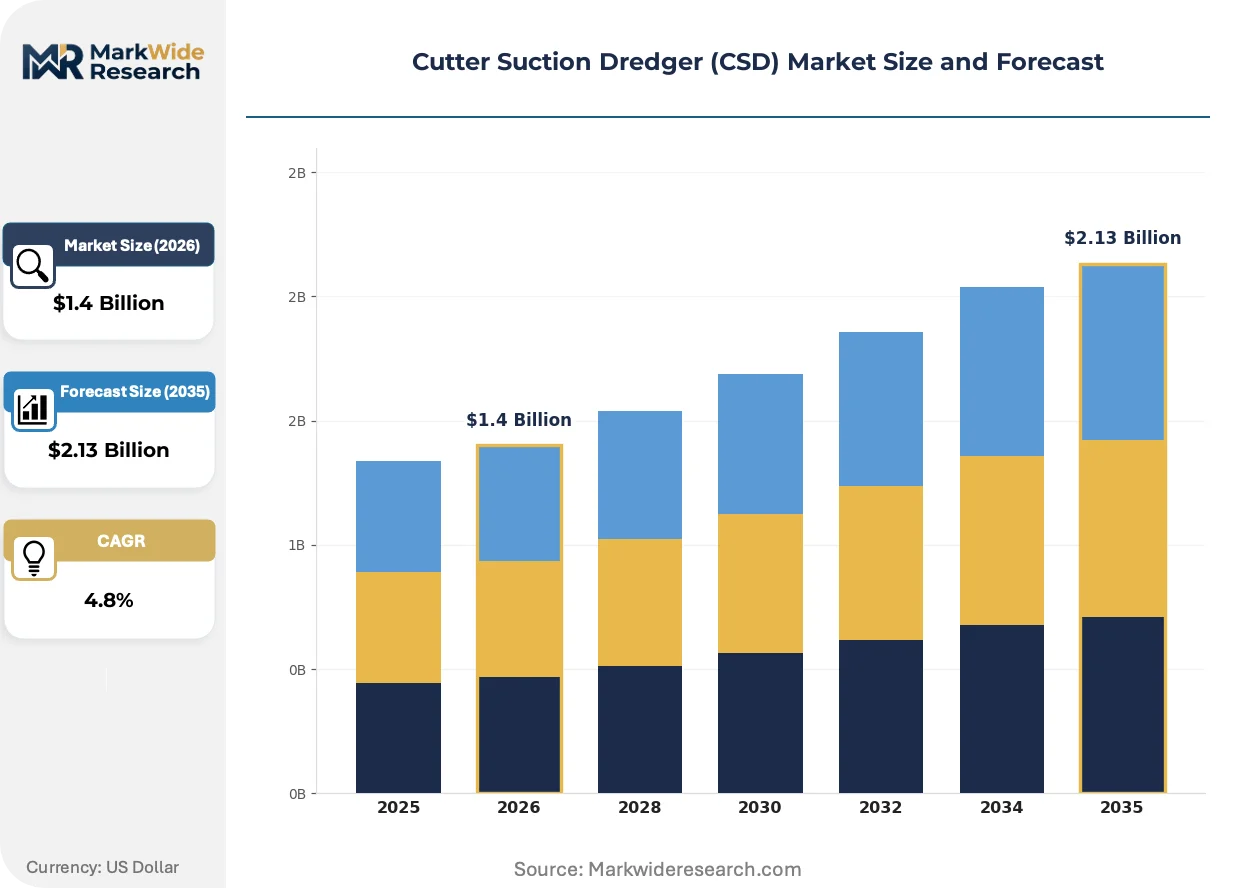
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydraulic, Mechanical, Hybrid, Electric Application: Land Reclamation, Port Development, River Deepening, Canal Maintenance End User: Mining Contractors, Marine Engineering Firms, Government Agencies, Environmental Consultants Deployment: Inland Waterways, Coastal Zones, Offshore Fields, Estuaries |
| Companies Covered | DSC Dredge, ITECH Co., Ltd., Damen Shipyards Group, Wuxi Dredge Machinery Co., Ltd., Zhangjiagang Heavy Dredger Co., Ltd., Royal IHC, Boskalis, China Dredging & Engineering Co., Ltd., Ellicott Dredges, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutter Suction Dredger (CSD) Market Trends and Innovations
Digitalization of dredge monitoring and predictive maintenance systems is compressing operational cost structures while regulatory emission frameworks are forcing propulsion architecture transitions across the installed base.
Electric drivetrain configurations for cutter heads and main pumps are expanding into high-specification harbor maintenance contracts. Port authorities in Rotterdam and Singapore now specify shore-power compatibility as a mandatory tender condition. This electrification trajectory is compressing the residual value horizon for conventional diesel-hydraulic units in regulated waterways.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are constraining hydraulic fluid formulations and refrigerant selections in auxiliary systems. Equipment manufacturers reformulate sealing compounds and cooling circuits to maintain certification eligibility. The regulatory burden falls most heavily on European-flagged vessels operating in North Sea and Baltic emission control zones.
Performance-based contracting is displacing traditional day-rate structures in major capital dredging programs. Indonesian port authorities and Vietnamese development corporations now tie contractor compensation to verified cubic-meter output and environmental compliance metrics. This payment model concentrates risk with equipment owners while rewarding pumping efficiency and precision dredging capabilities.
Cutter Suction Dredger (CSD) Market Segmentation
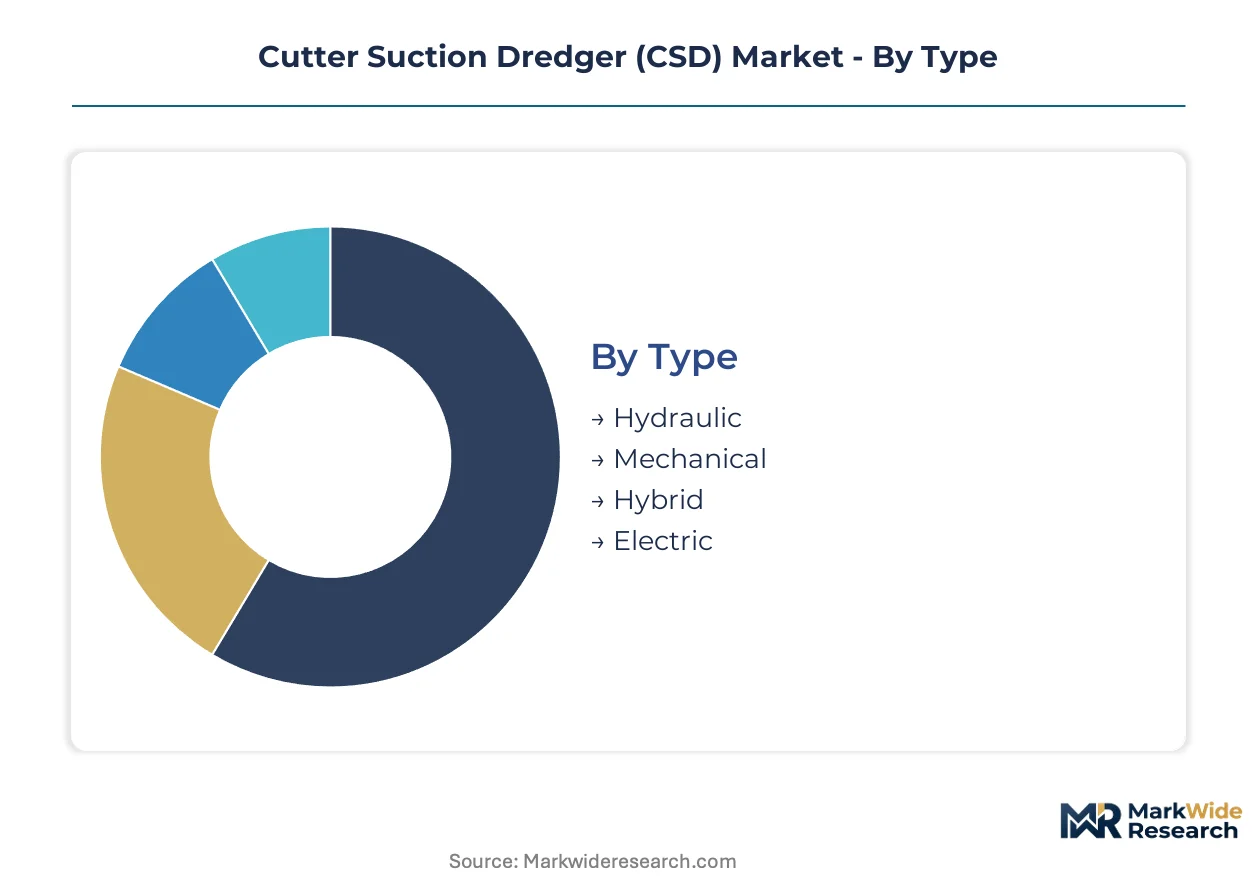
CSD procurement patterns diverge sharply between standalone capital projects and integrated marine construction bundles. Equipment specifications, propulsion architectures, and contract structures all shift depending on whether dredgers operate as primary assets or embedded components within larger port development programs.
Type:
Standalone dredging operations favor proven mechanical reliability, while hybrid-electric systems embed most naturally into port authority fleet modernization mandates with shore-power infrastructure.
- Hydraulic:Diesel-hydraulic drivetrains dominate the installed base with proven slurry pumping reliability above 5,000 cubic meters per hour. Indonesian and Vietnamese port authorities specify these units for channel deepening programs where maintenance access and technician availability outweigh emission considerations.
- Electric:Shore-power compatible architectures with battery-hybrid configurations are displacing conventional units in Rotterdam and Singapore harbor maintenance contracts. Port authorities now mandate emission benchmarks and tiered NOx compliance before tender eligibility, compressing residual values for diesel alternatives in regulated waterways.
- Mechanical:Direct-drive cutter head systems serve specialized rock-cutting applications in mining and quarry reclamation where soil disaggregation demands exceed hydraulic pump tolerances.
- Hybrid:LNG-ready platforms with modular battery retrofit pathways position builders for EU carbon border adjustment preparedness, though capital requirements exceed pure electric alternatives by substantial margins.
Hydraulic systems lead volumes today; electric variants are gaining share fastest.
Application:
Contract value concentrates where fill material must travel beyond 15 kilometers or where precision dredging protects sensitive seabed ecosystems.
- Port Development:Capital dredging for access channel modification and berth deepening commands premium day rates. Indonesian Pelabuhan Indonesia and Vietnam Maritime Administration procurement cycles drive fleet renewal demand.
- Land Reclamation:Long-distance pumping configurations for coastal megacity expansion justify specialized cutter heads and extended floating pipeline arrays. Singapore and Jakarta development corporations specify output-verified compensation tied to cubic-meter delivery.
- River Deepening:Inland waterway maintenance for barge navigation requires compact hull designs with shallow draft capabilities and maneuverable spud positioning systems.
- Canal Maintenance:Periodic sediment removal from constrained waterways favors smaller displacement units with rapid mobilization and demobilization logistics.
Port development anchors revenue concentration; land reclamation shows the steepest expansion trajectory.
End User:
Procurement authority and risk allocation vary dramatically between public infrastructure agencies and private marine contractors bundling dredging with construction services.
- Government Agencies:National port authorities and maritime administrations specify emission benchmarks and performance-based contracting with verified output metrics. Indonesian and Vietnamese regulators now tie contractor compensation to environmental compliance documentation.
- Marine Engineering Firms:Integrated project bundlers combine dredging with marine construction to capture full contract value, leveraging owned fleet assets across multiple concession windows.
- Mining Contractors:Quarry reclamation and tailings dam projects demand rock-cutting cutter heads with reinforced structural components for abrasive sediment conditions.
- Environmental Consultants:Remediation-focused operators require precision dredging with real-time soil density monitoring and dynamic positioning for sensitive seabed zones.
Marine engineering firms dominate fleet ownership; government agencies are accelerating direct procurement fastest.
Deployment:
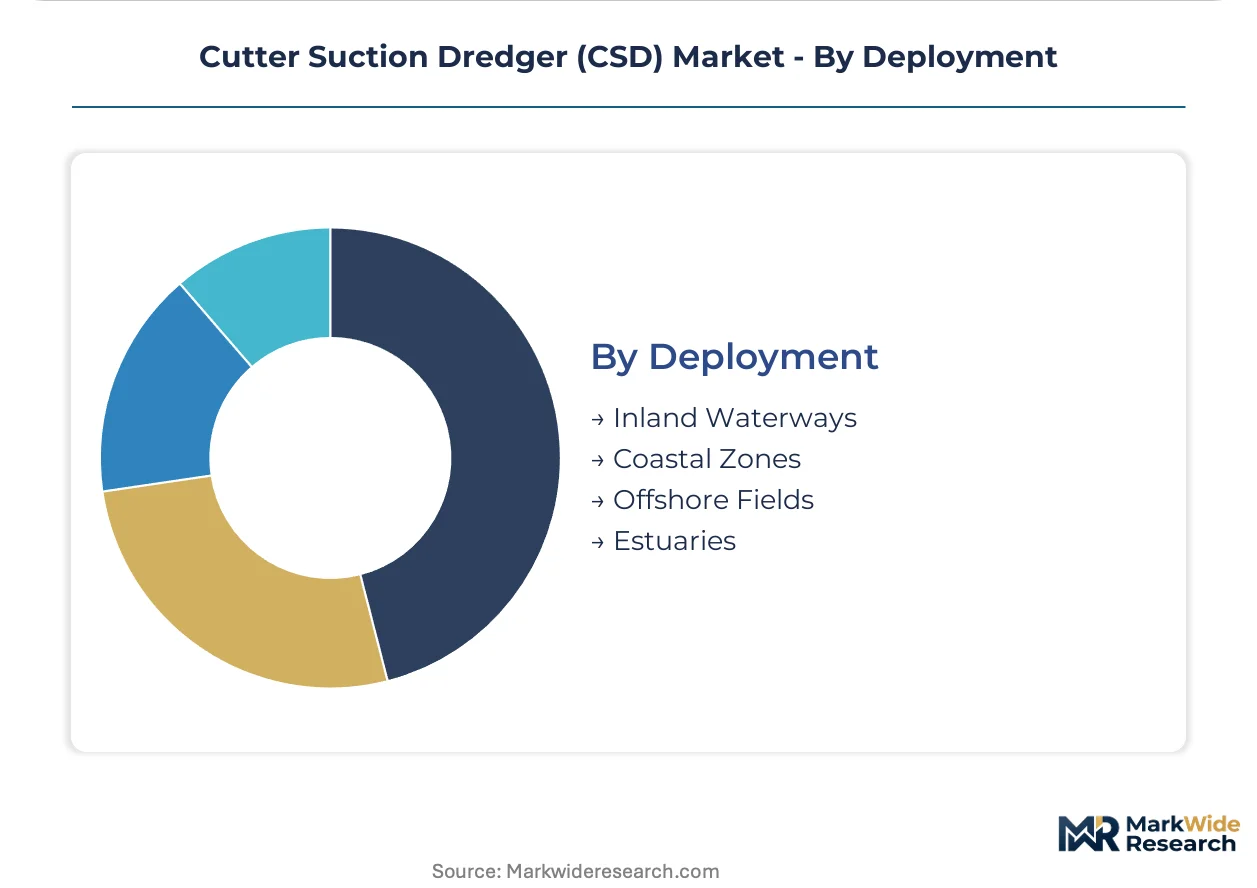
Operating environment dictates hull architecture, station-keeping systems, and auxiliary vessel requirements for pipeline logistics.
- Coastal Zones:Harbor modification and land reclamation projects concentrate premium-margin demand where wave exposure and tidal variation require robust spud carriage and anchor handling configurations.
- Inland Waterways:River and canal maintenance favors compact units with shallow draft and reduced beam for bridge clearance and lock transit.
- Offshore Fields:Island creation and subsea pipeline burial demand heavy-lift spud systems and extended pipeline arrays with dynamic positioning integration.
- Estuaries:Brackish water operations with mixed sediment loads require corrosion-resistant pump components and specialized sealing compounds under REACH substance restrictions.
Coastal zones concentrate contract value; offshore fields are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine engineers and naval architects concentrate in Dutch and Belgian port cities, anchoring Europe's dredging technology base. Asian shipyards in Jiangsu and Guangdong provinces supply hull fabrication capacity. Indonesian and Vietnamese maritime administrations now drive procurement volumes through channel deepening mandates.
Netherlands
Pelabuhan Indonesia's fleet modernization creates export demand for Dutch design expertise. EU Green Deal emission benchmarks compel Rotterdam harbor authorities to mandate shore-power compatibility in tender specifications. Royal IHC and Damen Shipyards Group anchor integrated design-to-delivery capabilities in Kinderdijk and Gorinchem.
Indonesia
Pelabuhan Indonesia accelerates harbor modification programs across Tanjung Priok and Belawan. The country's maritime administration ties contractor compensation to verified cubic-meter output and environmental compliance documentation. Surabaya and Jakarta concentrate land reclamation projects requiring long-distance pumping configurations beyond 15 kilometers.
Vietnam
Vietnam Maritime Administration drives access channel deepening for Cai Mep-Thi Vai and Lach Huyen deepwater ports. National port authority procurement cycles now specify emission benchmarks before contract eligibility. Hai Phong and Ho Chi Minh City anchor concentrated demand for high-capacity stationary dredgers in Mekong Delta estuaries.
Singapore
Jurong Port Authority and PSA Corporation mandate shore-power compatibility as a mandatory tender condition for harbor maintenance contracts. The Maritime and Port Authority enforces tiered NOx compliance benchmarks that compress residual values for diesel-hydraulic alternatives. Tuas megaport development generates premium-margin demand for precision dredging with real-time soil density monitoring.
China
China's MEE enforces parallel discharge and air quality constraints that ripple through regional supply chains. Jiangsu and Guangdong provinces concentrate hull fabrication capacity for export markets. Shanghai and Ningbo port authorities specify hybrid-electric propulsion architectures in green procurement standards for Yangtze River Delta channel maintenance.
Cutter Suction Dredger (CSD) Market Competitive Landscape
The competitive structure tilts toward integrated design-to-delivery specialists with captive metallurgical supply chains. Three strategic archetypes dominate: European full-service yards with in-house propulsion engineering, Asian fabricators leveraging standardized platform designs, and project bundlers combining dredging with marine construction. Capacity expansion and strategic partnerships represent the dominant competitive moves, as yards seek to secure high-tensile steel plate allocations and cutter head forging capacity.
Among Dutch integrated specialists, Royal IHC and Damen Shipyards Group exemplify the design-to-delivery archetype with captive engineering capabilities. Wuxi Dredge Machinery Co., Ltd. represents the Asian fabrication tier serving standardized hull requirements. Boskalis occupies a position within the project bundling segment, combining equipment ownership with marine construction execution.
| Leading Market Players |
|---|
| DSC Dredge |
| ITECH Co., Ltd. |
| Damen Shipyards Group |
| Wuxi Dredge Machinery Co., Ltd. |
| Zhangjiagang Heavy Dredger Co., Ltd. |
| Royal IHC |
| Boskalis |
| China Dredging & Engineering Co., Ltd. |
| Ellicott Dredges |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal emission benchmarks gate qualified supply and premium-tier pricing access, restricting build slots at Dutch and German yards to operators certifying hybrid-electric architectures while compressing margins for conventional diesel-hydraulic configurations in regulated waterways.
Pricing Analysis
Bundled project contracts combining dredging with marine construction command substantial premiums over standalone equipment procurement, with price differentiation anchored in IMO MARPOL Annex VI Tier III certification and shore-power compatibility grades. Cost compression in mid-tier hydraulic systems is intensifying because Indonesian and Vietnamese port authorities now specify verified cubic-meter output metrics that shift performance risk to equipment owners. Government agencies exhibit highest price sensitivity due to public procurement frameworks, while integrated marine contractors demonstrate lowest sensitivity given bundled revenue capture.
Supply Chain Analysis
Secondary equipment leasing and cutter head refurbishment flows extend asset lifecycles and buffer newbuild delivery bottlenecks. High-tensile steel plate and precision cutter head forgings draw from German and Dutch metallurgical suppliers, with auxiliary pump packages sourcing from Chinese Jiangsu fabrication clusters. Single-source vulnerability concentrates in specialized forging capacity for rock-cutting cutter heads. Distribution runs through direct yard-to-operator contracts for premium builds and regional equipment lessors for secondary market circulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the CSD market rests on electrification-driven premium-tier migration and modular retrofit pathways that extend residual value capture for legacy fleet operators.
For Market Incumbents: Lock in captive forging capacity for high-tensile cutter head components and accelerate battery-hybrid platform certification to preempt EU carbon border adjustment eligibility rules. Defend against Asian fabricators standardizing hull designs by embedding proprietary dynamic positioning software and real-time soil density monitoring as differentiated service bundles. For New Entrants and Emerging Players: The price-point gap between premium electric configurations and economy hydraulic units creates white-space opportunity in secondary equipment leasing and regional aftermarket service. Target Vietnamese and Indonesian channel deepening programs where maintenance access constraints outweigh emission compliance priorities. Enter through cutter head and pump package rental partnerships with mid-tier marine contractors lacking full fleet ownership. For Investors and Strategic Acquirers: Roll-up economics work for specialized dredging technology firms because fragmented regional operators lack integrated design-to-delivery capabilities and emission certification expertise. Long-term viability centers on builders offering modular retrofit pathways and lifecycle emission documentation. Monitor EU carbon border mechanism implementation timelines as inflection indicator for accelerated fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Platform Certification | EU Green Deal benchmarks compel Rotterdam and Singapore harbor authorities to mandate shore-power compatibility in tender specifications. |
| Cutter Head Forging Capacity Expansion | German and Dutch metallurgical suppliers anchor premium-tier supply security for rock-cutting applications in mining reclamation. |
| Dynamic Positioning System Integration | Real-time soil density sensors enable precision dredging in environmentally sensitive seabed zones previously excluded from development. |
| Secondary Equipment Leasing Network | Project bundling by marine contractors opens aftermarket revenue streams for regional operators lacking full fleet ownership. |
| Lifecycle Emission Documentation Program | EU carbon border adjustment preparedness creates first-mover advantage for builders offering modular retrofit pathways. |
Research Methodology
Direct dialogue with dredging fleet managers, port authority procurement officers, marine contractor project directors, and high-tensile steel forging specialists grounded the qualitative foundation. Secondary validation drew from IMO MARPOL Annex VI filings, EU ETS registry data, Indonesian Pelabuhan Indonesia procurement disclosures, and Vietnam Maritime Administration harbor modification records. Bottom-up vessel deployment tracking and top-down contract value aggregation were triangulated to reconcile segment-level estimates.
Installed base projections and replacement cycle timing across the modeling period reflect segmentation by propulsion architecture, application intensity, and regional regulatory cluster. CAGRs were derived from contract award velocity analysis and fleet age distribution modeling. Industry-specific forecast inputs incorporated channel deepening program pipelines from Indonesian and Vietnamese maritime administrations and shore-power infrastructure deployment schedules at Rotterdam and Singapore ports.
Caveats apply where IMO emission protocol revisions or EU carbon border mechanism scope expansions could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance windows and metallurgical supply continuity. Practitioners should monitor Indonesian and Vietnamese procurement cycle acceleration and battery-hybrid platform delivery lead times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Part Feeder Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Global Excavators Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Mill Pulverizer Market