
 Biliary Catheters Market | 2026-2036
Biliary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Biliary Catheters Market Analysis
Aftermarket service revenue is reconfiguring how manufacturers capture lifetime value from single-use device portfolios. Boston Scientific Corporation leverages its endoscopy service infrastructure to sustain recurring revenue streams across hospital accounts. Cook Medical anchors its competitive stance through deep specialization in minimally invasive biliary access systems. Medtronic competes by extending its interventional portfolio into integrated procedural platforms that bundle catheters with imaging guidance.
Biliary catheters are flexible or semi-rigid tubular devices, typically manufactured from polyurethane, silicone, or polyethylene blends, designed for cannulation, drainage, or stent delivery within the hepatobiliary tree. These devices incorporate radio-opaque markers and variable durometer construction to navigate tortuous anatomy while maintaining patency under physiological pressure loads. Drainage catheters occupy the largest revenue pool due to their role in managing malignant and benign biliary obstructions, while access catheters represent the fastest-growing segment as complex percutaneous transhepatic cholangiography procedures expand. Material selection increasingly stratifies by procedure complexity, with polyurethane dominating standard interventions and metal-reinforced constructions commanding premium positioning in transhepatic applications.
FDA 510(k) and PMA pathways enforce biocompatibility testing under ISO 10993 standards, while EMA's Medical Device Regulation mandates clinical evidence for biliary stent longevity claims. Japan's PMDA requires local clinical bridging studies for novel catheter designs, creating staggered market entry timelines across major jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for outpatient biliary procedures as ambulatory surgical centers reshape site-of-care economics.
Market Dynamics
Ambulatory surgical centers are compressing site-of-care economics for biliary interventions, forcing catheter manufacturers to reconfigure device specifications and service models around outpatient reimbursement thresholds rather than traditional inpatient workflows.
Growth Catalysts
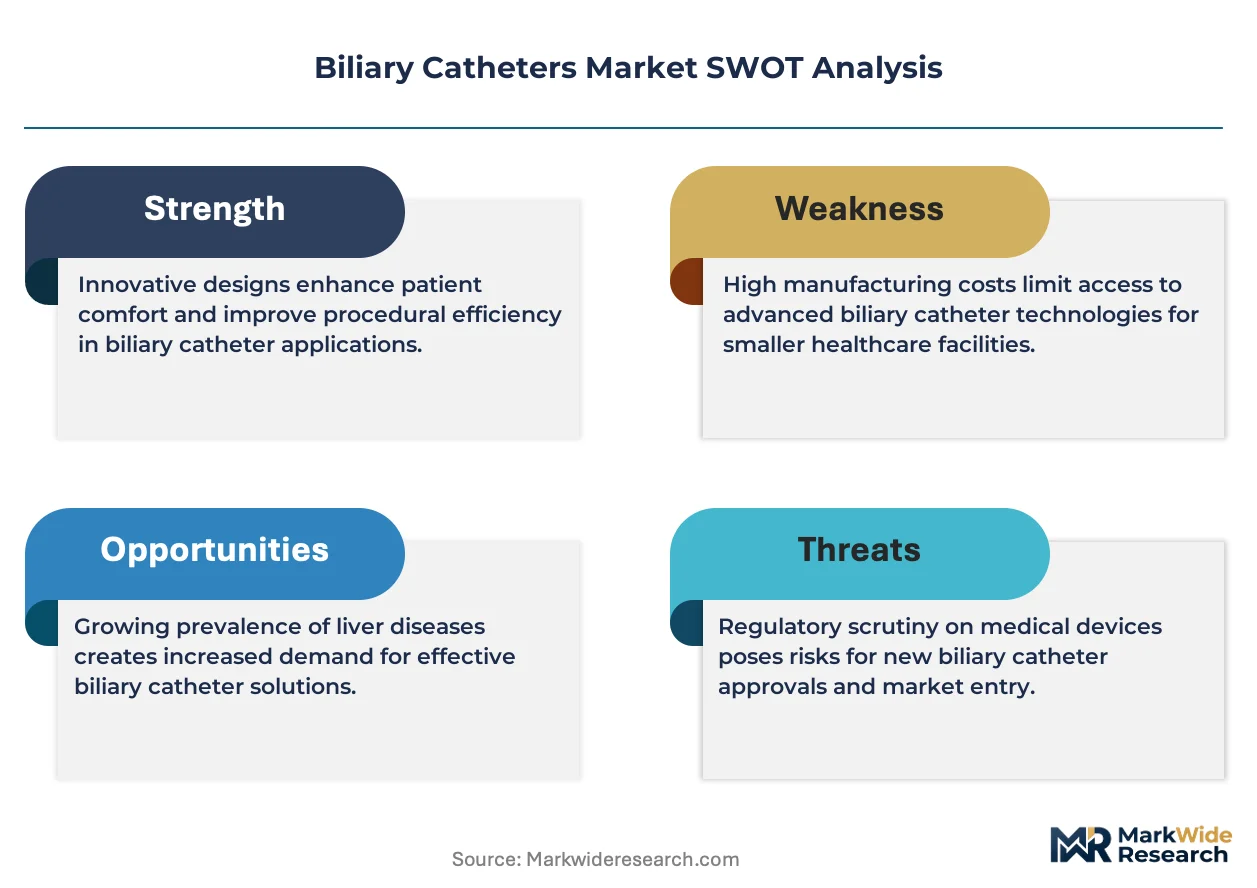
- FDA 510(k) pathway streamlining:Expedited clearances for predicate-based catheter designs are accelerating commercialization timelines for drainage and access devices in the United States.
- Japan's aging hepatobiliary patient pool:Expanding Medicare-equivalent coverage for percutaneous transhepatic cholangiography procedures sustains procedural volume growth in tertiary hospitals.
- Polyurethane material advances:Enhanced durometer gradients and radio-opaque loading techniques are extending functional catheter longevity in malignant obstruction cases.
Market Restraints
- Platinum-iridium marker volatility:Radio-opaque component costs fluctuate with precious metal markets, squeezing gross margins on standard drainage catheter SKUs.
- EMA MDR clinical evidence mandates:Biliary stent longevity claims now require prospective trial data, extending time-to-market for novel designs by 18-36 months.
- Single-use device substitution pressure:Reprocessed access catheters in cost-constrained European hospital systems threaten premium pricing for original equipment.
Strategic Opportunities
- India's interventional radiology infrastructure buildout:Greenfield catheterization labs in tier-2 cities create first-mover positioning for drainage system suppliers.
- Integrated imaging-catheter platforms:Convergence of intraprocedural ultrasound guidance with steerable access devices enables premium bundling in complex transhepatic cases.
- Germany's Diagnosis-Related Group recalibration:Outpatient biliary procedure reimbursement expansion incentivizes ambulatory-capable catheter portfolios.
Industry Challenges
- Interventional radiologist training pipelines:Fellowship program bottlenecks in the United States and Japan constrain procedural capacity expansion regardless of device availability.
- ISO 10993 biocompatibility testing backlogs:Third-party laboratory capacity constraints delay regulatory submissions for novel silicone blend formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biliary Catheters Market |
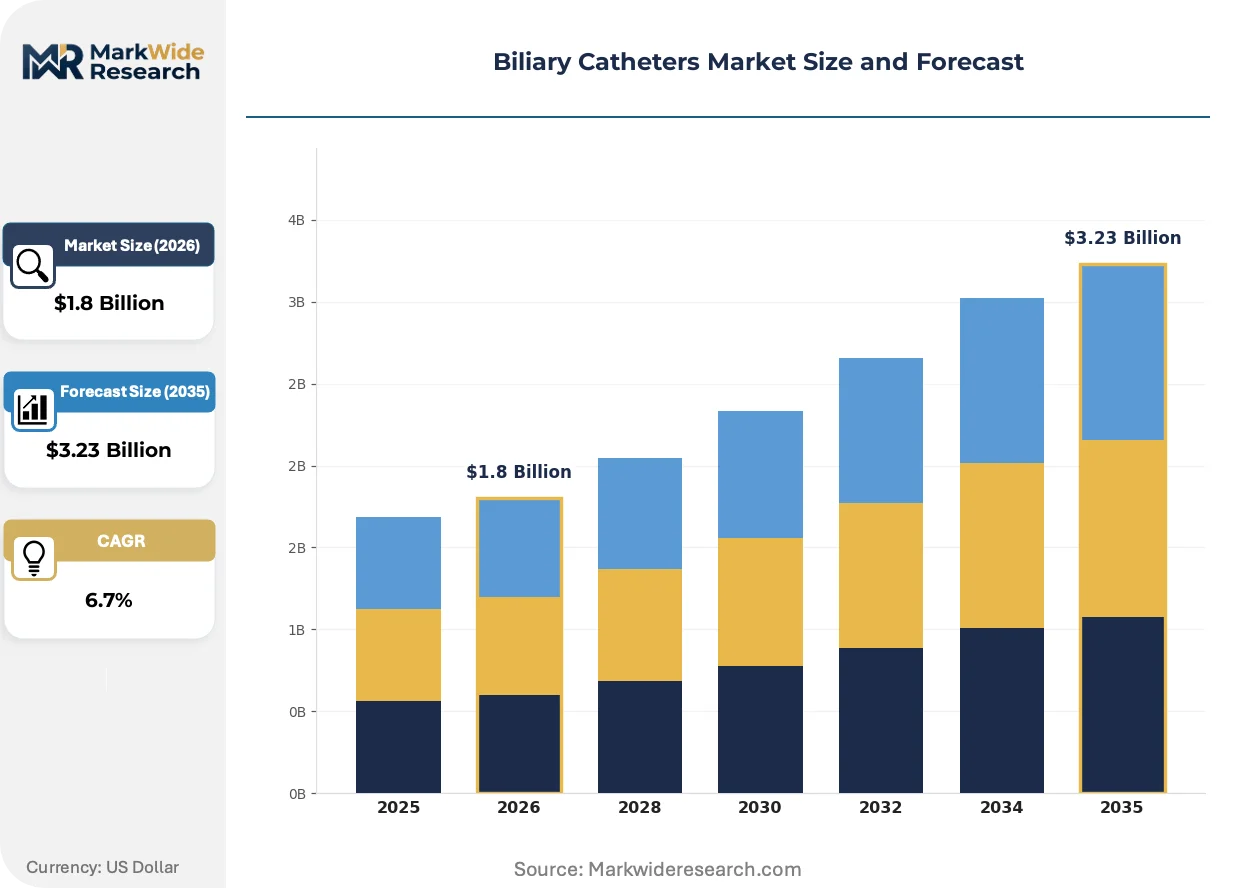
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drainage Catheters,Stent Catheters,Access Catheters,Guiding Catheters End User: Hospitals,Clinics,Ambulatory Surgical Centers,Diagnostic Laboratories Material: Polyurethane,Silicone,Polyvinyl Chloride,Metal Delivery Mode: Transhepatic,Endoscopic,Percutaneous,Transluminal |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Medtronic, Becton, Dickinson and Company, Abbott Laboratories, Teleflex Incorporated, Merit Medical Systems, Olympus Corporation, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biliary Catheters Market Emerging Trajectories
Material science convergence with real-time imaging modalities is collapsing traditional boundaries between diagnostic and therapeutic biliary procedures, compressing the device ecosystem around multifunctional platforms.
Metal-reinforced catheter shafts with variable stiffness transition zones are collapsing the performance gap between standard polyurethane drainage devices and surgical bypass alternatives. Interventional radiology departments in German and Japanese university hospitals are adopting these hybrid constructions for complex malignant strictures. The technology is collapsing the addressable market for purely polymeric devices in transhepatic applications.
EMA's Medical Device Regulation now mandates post-market surveillance for biliary stent patency claims, forcing manufacturers to maintain prospective registries. This surveillance obligation is reshaping commercialization economics toward devices with demonstrated longevity rather than iterative design improvements. High-volume stent suppliers are responding by prioritizing predicate devices with established clinical histories over novel material platforms.
Hospital procurement committees are consolidating biliary catheter purchasing through integrated delivery networks, displacing fragmented specialty distributor relationships. This concentration is most visible in United States health systems where standardized formularies now cover drainage, access, and stent delivery devices under single-source agreements. The shift is compressing vendor margins while rewarding manufacturers with comprehensive interventional portfolios.
Biliary Catheters Market Segmentation
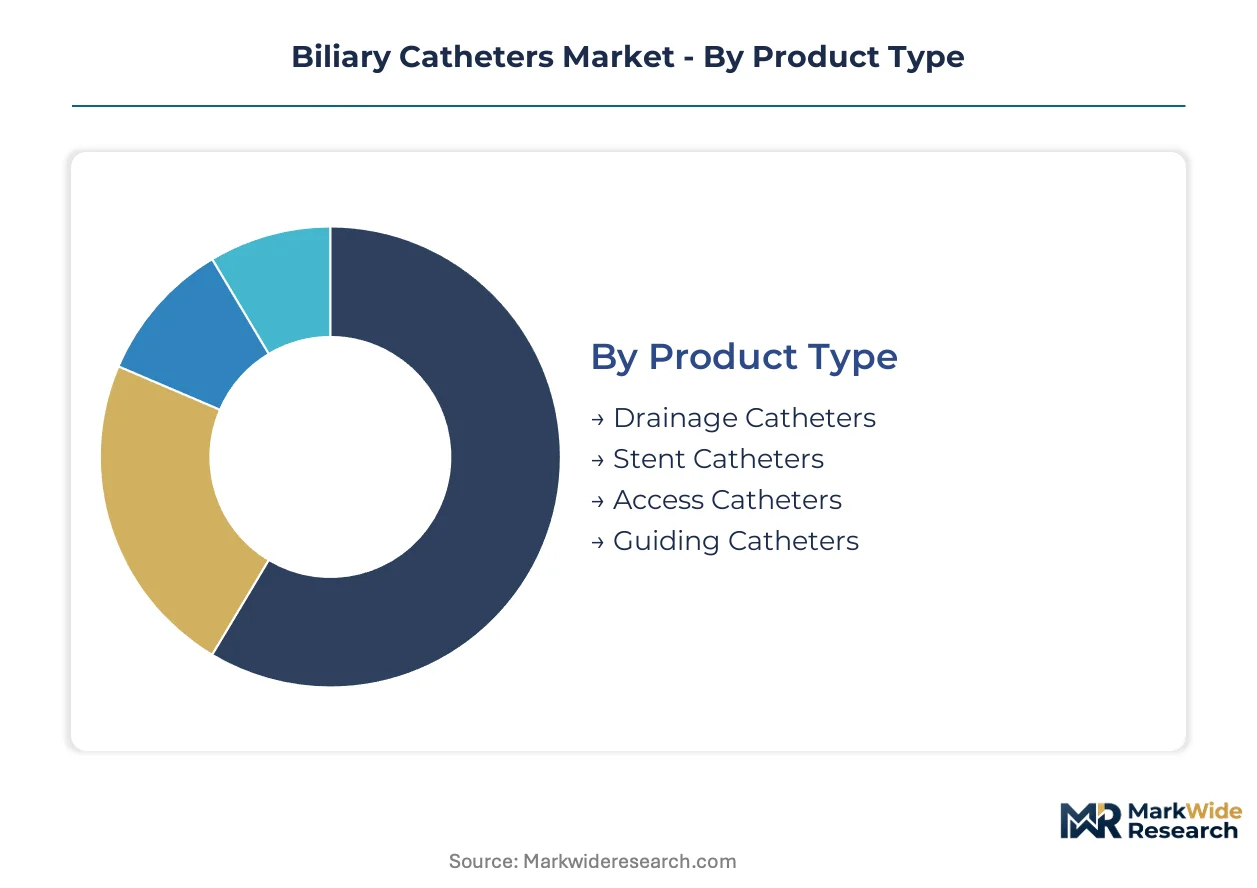
Biliary catheter purchasing decisions fragment across clinical workflow requirements, reimbursement site-of-care economics, and anatomical access routes. Manufacturers must align portfolio architecture with these intersecting dimensions to secure formulary placement.
Product Type:
Application complexity determines catheter construction specifications and pricing tiers across the hepatobiliary intervention spectrum.
- Drainage Catheters:Polyurethane or silicone constructions with multiple side holes and radio-opaque markers manage malignant and benign biliary obstructions. United States tertiary hospitals concentrate demand for multi-lumen configurations in complex hilar strictures.
- Access Catheters:Variable durometer shafts with hydrophilic coatings enable percutaneous transhepatic cholangiography navigation. Japanese university hospitals drive adoption of steerable tip designs for tortuous anatomy.
- Stent Catheters:Delivery systems for metallic and plastic biliary stents.
- Guiding Catheters:Support platforms for wire exchange and device advancement.
Drainage catheters command the established base. The steepest expansion runs through access catheters.
End User:
Customer type shapes device specifications, service requirements, and contracting structures across care delivery settings.
- Hospitals:Inpatient interventional radiology departments and gastroenterology services perform complex transhepatic and endoscopic retrograde procedures. Germany's university hospital networks sustain high-volume purchasing for metal-reinforced constructions.
- Ambulatory Surgical Centers:Outpatient biliary interventions demand compact, single-use kits aligned with same-day discharge protocols. United States reimbursement expansion for outpatient percutaneous procedures accelerates site migration.
- Clinics:Office-based settings for diagnostic cholangiography and catheter maintenance.
- Diagnostic Laboratories:Imaging centers performing cholangiographic assessment.
Hospitals retain the volume anchor. Ambulatory surgical centers are climbing the fastest.
Material:
Biocompatibility profiles and mechanical performance requirements stratify raw material selection across procedure categories.
- Polyurethane:Segmented block copolymers with tunable durometer ranges dominate standard drainage applications. EMA MDR biocompatibility testing under ISO 10993 standards reinforces established supply relationships for validated formulations.
- Silicone:Platinum-cured elastomers offer superior long-term indwelling tolerance for permanent drainage catheters. Japan's PMDA requires local bridging studies for novel silicone blends, extending qualification timelines.
- Polyvinyl Chloride:Cost-sensitive constructions for short-term drainage.
- Metal:Nitinol or stainless steel reinforcements for transhepatic access systems.
Polyurethane holds the incumbent position. Metal-reinforced constructions are gaining share fastest.
Delivery Mode:
Anatomical access route dictates catheter length, curvature, and compatibility with imaging guidance systems.
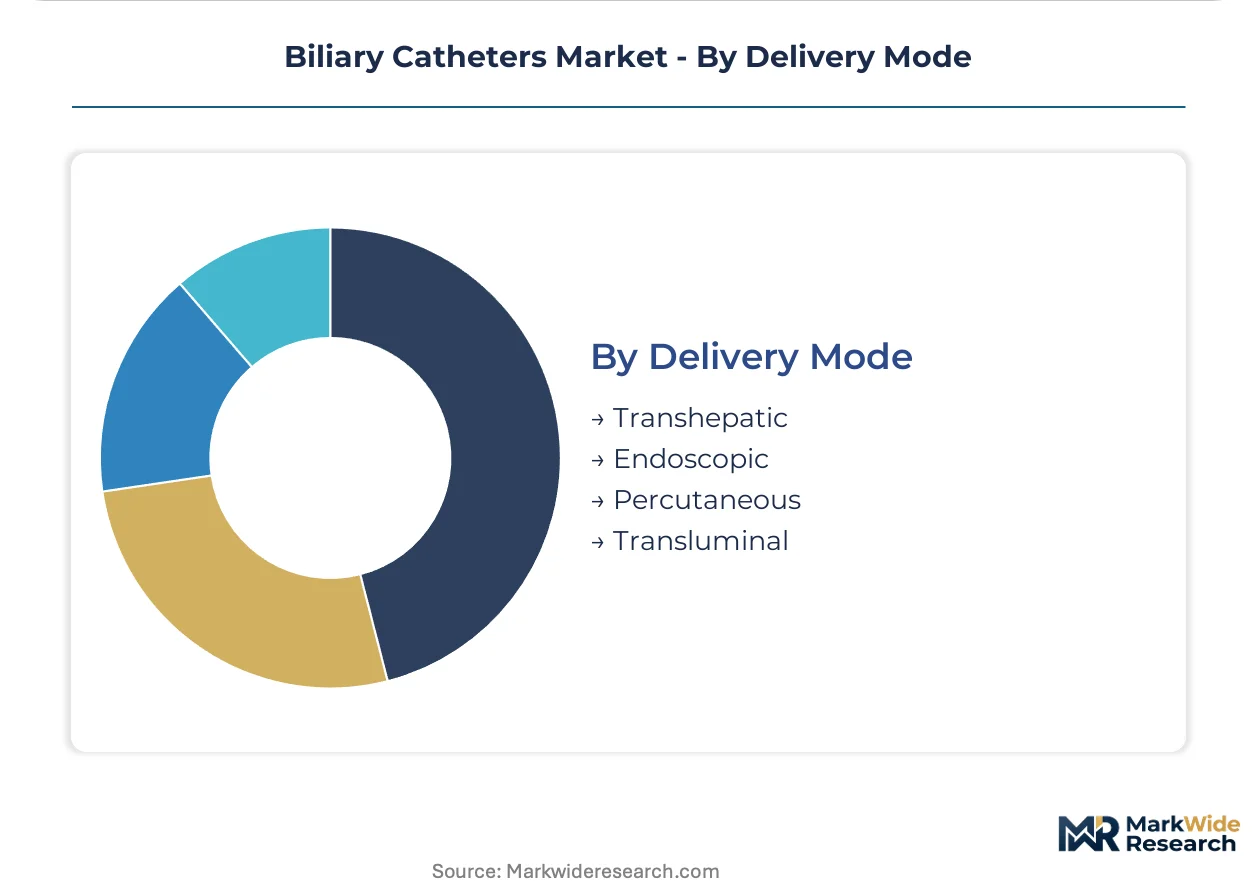
- Transhepatic:Percutaneous liver puncture requires stiffening cannulas and coaxial systems for safe tract dilation. German interventional radiology departments prioritize integrated ultrasound-guidance compatibility.
- Endoscopic:ERCP-compatible devices navigate the duodenal papilla under fluoroscopic control. United States gastroenterology practices concentrate demand for sphincterotome-integrated platforms.
- Percutaneous:Direct skin entry for external drainage without endoscopic assistance.
- Transluminal:Transluminal access for specialized biliary-enteric anastomosis procedures.
Transhepatic delivery anchors procedural volume. Endoscopic applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for standard drainage catheters runs highest in India's tier-2 hospital systems, while Japanese tertiary centers absorb premium metal-reinforced constructions without volume elasticity. German university hospitals occupy the middle ground, demanding performance validation before accepting price premiums.
United States
Ambulatory surgical centers now drive catheter volume growth as outpatient reimbursement expansion accelerates site-of-care migration. FDA 510(k) pathway streamlining expedites predicate-based drainage device clearances, shortening commercialization timelines. Interventional radiology clusters in Houston and Boston concentrate demand for integrated imaging-catheter platforms.
Germany
University hospital networks sustain high-volume purchasing for metal-reinforced constructions in complex hilar stricture cases. EMA MDR clinical evidence mandates for stent longevity claims extend regulatory timelines, favoring established predicate devices. The Rhine-Ruhr metropolitan region anchors procurement consolidation through integrated delivery network standardization.
Japan
Aging hepatobiliary patient pools expand Medicare-equivalent coverage for percutaneous transhepatic cholangiography procedures. PMDA requires local clinical bridging studies for novel catheter designs, creating staggered market entry patterns. Tokyo and Osaka metropolitan areas concentrate interventional radiology fellowship programs and tertiary procedural volume.
India
Greenfield catheterization labs in tier-2 cities create first-mover positioning opportunities for drainage system suppliers. CDSCO regulatory pathways for Class II devices enforce biocompatibility testing aligned with ISO 10993 standards. Maharashtra and Karnataka states lead interventional radiology infrastructure buildout with concentrated private hospital investment.
United Kingdom
NHS procurement frameworks consolidate biliary catheter purchasing through standardized formularies, compressing vendor margins while rewarding comprehensive portfolio suppliers. MHRA post-Brexit regulatory alignment with EMA MDR maintains clinical evidence requirements for stent devices. London and Manchester academic medical centers concentrate complex transhepatic procedural expertise.
Biliary Catheters Market Vendor Landscape
Capability concentration sits with specialized interventional access manufacturers; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies into three tiers: comprehensive portfolio suppliers capturing integrated delivery network contracts, single-category specialists defending premium positioning through technical differentiation, and regional fabricators competing on cost for standard drainage constructions. Dominant competitive moves include portfolio bundling with imaging platforms and aftermarket service infrastructure buildout to capture recurring revenue.
Within the comprehensive portfolio tier, Boston Scientific Corporation and Cook Medical occupy positions anchoring hospital system standardization. Medtronic exemplifies the scale-driven archetype, extending interventional platforms through integrated procedural ecosystems. These three companies represent the competitive fault lines where service infrastructure, regulatory validation depth, and site-of-care economics intersect.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Medtronic |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Teleflex Incorporated |
| Merit Medical Systems |
| Olympus Corporation |
| CONMED Corporation |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit polyurethane and platinum-iridium cost volatility directly into manufacturer margin structures, concentrating pricing power among suppliers with captive raw material positions while forcing tiered differentiation across drainage catheter portfolios.
Pricing Analysis
Aftermarket service contracts anchor lifetime value capture for catheter manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by material reinforcement grade and ISO 10993 biocompatibility certification tier. Cost compression in standard polyurethane drainage SKUs intensifies because reprocessed catheter substitution pressures original equipment margins in European hospital systems. Ambulatory surgical centers exhibit highest price sensitivity due to outpatient reimbursement ceilings, while Japanese tertiary centers absorb premium metal-reinforced constructions without volume elasticity.
Supply Chain Analysis
Export-control restrictions on radio-opaque marker technologies limit platinum-iridium alloy flows from South African and Russian suppliers into catheter manufacturing hubs. Raw material sourcing draws from German polyurethane compounders, Japanese silicone processors, and Chinese nitinol wire producers. Single-source vulnerability concentrates in precious metal marker supply, with tariff exposure running through EU-sourced platinum group metals. Distribution runs through integrated delivery networks in United States health systems and specialty distributors in European university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement committee consolidation and integrated delivery network standardization, fragmenting vendor relationships into single-source agreements that compress margins while rewarding comprehensive portfolio suppliers.
For Market Incumbents: Pre-empt reprocessed catheter substitution by deepening backward integration into platinum-iridium marker supply and accelerating CE marking pathways for metal-reinforced constructions before EMA MDR clinical evidence mandates harden. Lock in ambulatory surgical center formulary placement through compact single-use kit configurations aligned with same-day discharge protocols. For New Entrants and Emerging Players: India's tier-2 city catheterization lab buildout offers first-mover positioning for drainage system suppliers with CDSCO-aligned biocompatibility documentation. Target steerable access catheter segments where Japanese university hospital demand outpaces established supply, leveraging local clinical bridging study partnerships to compress PMDA qualification timelines. For Investors and Strategic Acquirers: Single-category specialists with validated silicone blend formulations and established ISO 10993 testing histories represent prime acquisition targets as EMA MDR surveillance obligations reshape commercialization economics toward predicate devices. Monitor FDA 510(k) clearance velocity for novel catheter designs as inflection indicator for regulatory pathway efficiency and time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Expedited predicate-based clearances accelerate drainage device commercialization timelines in United States markets. |
| Hospital System Partnership | Integrated delivery network standardization secures formulary placement across drainage, access, and stent portfolios. |
| CE Marking Pathway | EMA MDR clinical evidence mandates favor established predicate devices with demonstrated stent patency histories. |
| Reimbursement Strategy | Outpatient biliary procedure coverage expansion in Germany and United States reshapes site-of-care economics. |
| Software Companion Development | Integrated ultrasound-guidance compatibility enables premium bundling for complex transhepatic access platforms. |
Methodological Framework
The analysis maps drainage catheter, access catheter, stent delivery, and guiding catheter sub-sectors, each validated through interventional radiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers. Primary interview intelligence triangulates against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling cross-checks against top-down manufacturer revenue aggregation.
Assumptions held fixed include regulatory pathway timelines across FDA, EMA, and PMDA jurisdictions, while material cost trajectories and ambulatory surgical center migration rates were varied across sensitivity scenarios. Segmentation dimensions encompass product type, end-user setting, material construction, and delivery mode, with CAGR derivation anchored in procedural volume elasticity and price-tier mix shifts. Forecast inputs incorporate platinum-iridium commodity volatility and interventional radiologist fellowship pipeline constraints.
Practitioners should monitor EMA MDR surveillance outcome data and ambulatory surgical center reimbursement recalibrations for early signals of demand trajectory revision. Material shifts in FDA 510(k) pathway efficiency or precious metal supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Elbow Fixators Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Cervical Implants Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Pectus Bar System Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Spinal Needles Market