
 South Africa Digital X-Ray Devices Market | 2026-2036
South Africa Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Digital X-Ray Devices Market Analytics
CE marking alignment for imported medical electronics is unwinding competitive access, forcing distributors to recertify legacy portfolios before tender participation. Siemens Healthineers leverages its established service footprint across tertiary hospitals to sustain recurring revenue streams. GE Healthcare anchors its position through localized technical training programs that lock in radiographer loyalty. Philips competes by bundling digital flat panel upgrades with managed equipment service contracts.
South Africa digital x-ray devices employ amorphous selenium or cesium iodide scintillator layers on thin-film transistor arrays to convert ionizing radiation directly into digital signals, eliminating chemical processing and enabling immediate image distribution across hospital networks. Fixed systems dominate installed base value due to their integration into dedicated radiology suites, while portable systems capture the fastest expansion as point-of-care protocols spread through emergency departments and rural outreach programs. Wireless detector retrofit kits concentrate margin pools by extending the functional life of existing generator infrastructure without full room replacement.
The South African Health Products Regulatory Authority (SAHPRA) governs device registration and post-market surveillance, while the National Department of Health sets tender specifications that increasingly mandate DICOM compliance and local service presence. The Bureau of Standards (SABS) enforces electromagnetic compatibility testing that filters out uncertified imports. Stakeholders must monitor how NHI procurement centralization reshapes vendor qualification criteria and service-level agreement terms.
Market Dynamics
The National Health Insurance policy is compressing procurement timelines and mandating DICOM compliance across public hospital tenders, forcing vendors to restructure service networks before qualification.
Growth Catalysts
- SAHPRA registration harmonization:Streamlined device approval pathways accelerate market entry for certified manufacturers, reducing time-to-revenue for compliant portfolios.
- Point-of-care protocol expansion:Emergency departments in Gauteng province are adopting portable digital systems to bypass radiology suite bottlenecks during peak admission periods.
- Cesium iodide scintillator adoption:This detector material improves low-dose imaging efficiency, enabling rural clinics to achieve diagnostic quality with reduced generator power requirements.
Market Restraints
- Generator import concentration:X-ray tube and high-voltage generator supply chains concentrate in German and Japanese manufacturing clusters, exposing South African distributors to euro-yen volatility and extended lead times.
- SABS electromagnetic compatibility testing:Uncertified Asian imports face automatic exclusion from public tenders, narrowing the supplier base to pre-qualified vendors with established local testing partnerships.
- Computed radiography substitution:Legacy CR systems in underfunded provincial hospitals delay full digital conversion, fragmenting maintenance ecosystems and diluting training standardization.
Strategic Opportunities
- Eastern Cape rural penetration:District hospitals in Mthatha and Port Elizabeth corridors operate with film-based infrastructure, creating first-mover advantage for wireless detector retrofit providers.
- NHI centralized procurement:National tender consolidation favors vendors with established technical training academies and multi-site service contracts spanning provincial networks.
- AI-assisted diagnostic convergence:Machine learning algorithms for automated fracture detection integrate with digital flat panels, creating bundled value propositions for tertiary hospital radiology departments.
Industry Challenges
- Radiographer specialization gaps:Public sector training programs produce insufficient PACS administrators and DICOM integration specialists, forcing hospitals to rely on vendor-contracted personnel for system maintenance.
- Legacy analog room retrofit complexity:Existing generator infrastructure requires electrical and structural modifications to accommodate wireless detector workflows, extending installation timelines and disrupting departmental throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Digital X-Ray Devices Market |
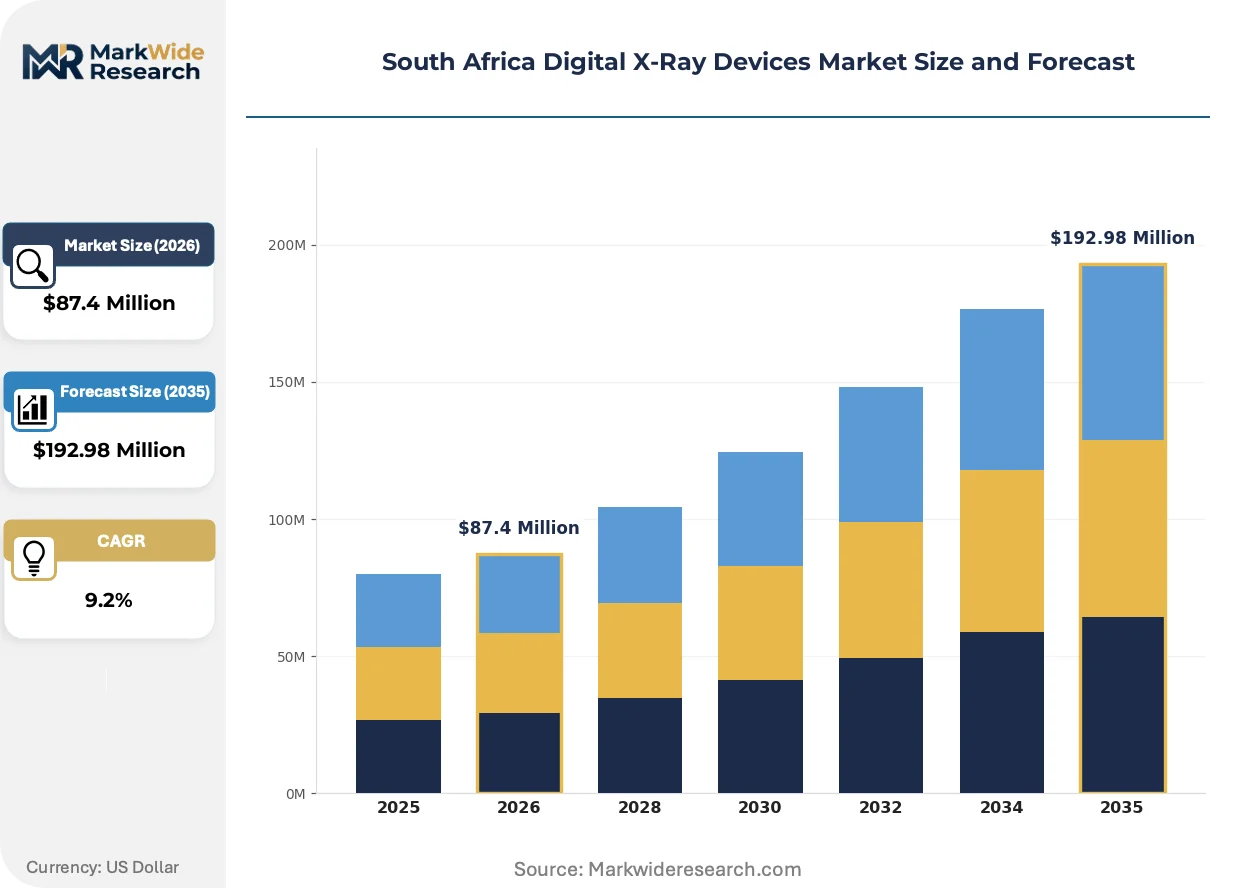
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $192.98 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Mobile Systems, Computed Radiography End User: Hospitals, Diagnostic Centers, Imaging Clinics, Research Institutions Technology: Digital Flat Panel Detectors, CCD Detectors, Wireless Detectors, Computed Radiography Systems Application: Dental Imaging, Orthopedic Imaging, Chest Imaging, Mammography |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Fujifilm Holdings Corporation, Canon Medical Systems, Carestream Health Inc, Agfa Healthcare, Shimadzu Corporation, DRGEM Africa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Digital X-Ray Devices Market Evolving Landscape
Detector technology is compressing form factors while software integration is collapsing diagnostic turnaround times, reshaping competitive advantage around service density rather than hardware specifications alone.
Wireless flat-panel detectors employing cesium iodide scintillator layers are miniaturizing to sub-2.5kg weights, enabling single-operator positioning in orthopaedic and neonatal intensive care settings. Private hospital chains in Johannesburg are deploying these units across multiple wards to eliminate patient transport to centralized radiology suites. This miniaturization is compressing capital allocation per diagnostic site and fragmenting purchasing authority from radiology departments to individual clinical units.
SAHPRA post-market surveillance requirements now mandate adverse event reporting within 72 hours for all Class IIb medical devices, elevating documentation burdens for distributors managing multi-brand portfolios. The regulation forces smaller importers to consolidate around single-vendor partnerships or exit the public tender market entirely. Tertiary hospitals in Pretoria and Cape Town are responding by privileging manufacturers with localized quality management systems and dedicated regulatory affairs personnel.
Managed equipment service contracts are displacing traditional capital purchase models across provincial health departments, bundling hardware, maintenance, and consumables into per-procedure fees. This reconfiguration transfers obsolescence risk from hospital capital budgets to vendor balance sheets, compressing supplier margins while extending contract tenures. The shift is most pronounced in Gauteng and KwaZulu-Natal, where treasury constraints have frozen direct equipment procurement since 2023.
South Africa Digital X-Ray Devices Market Segmentation
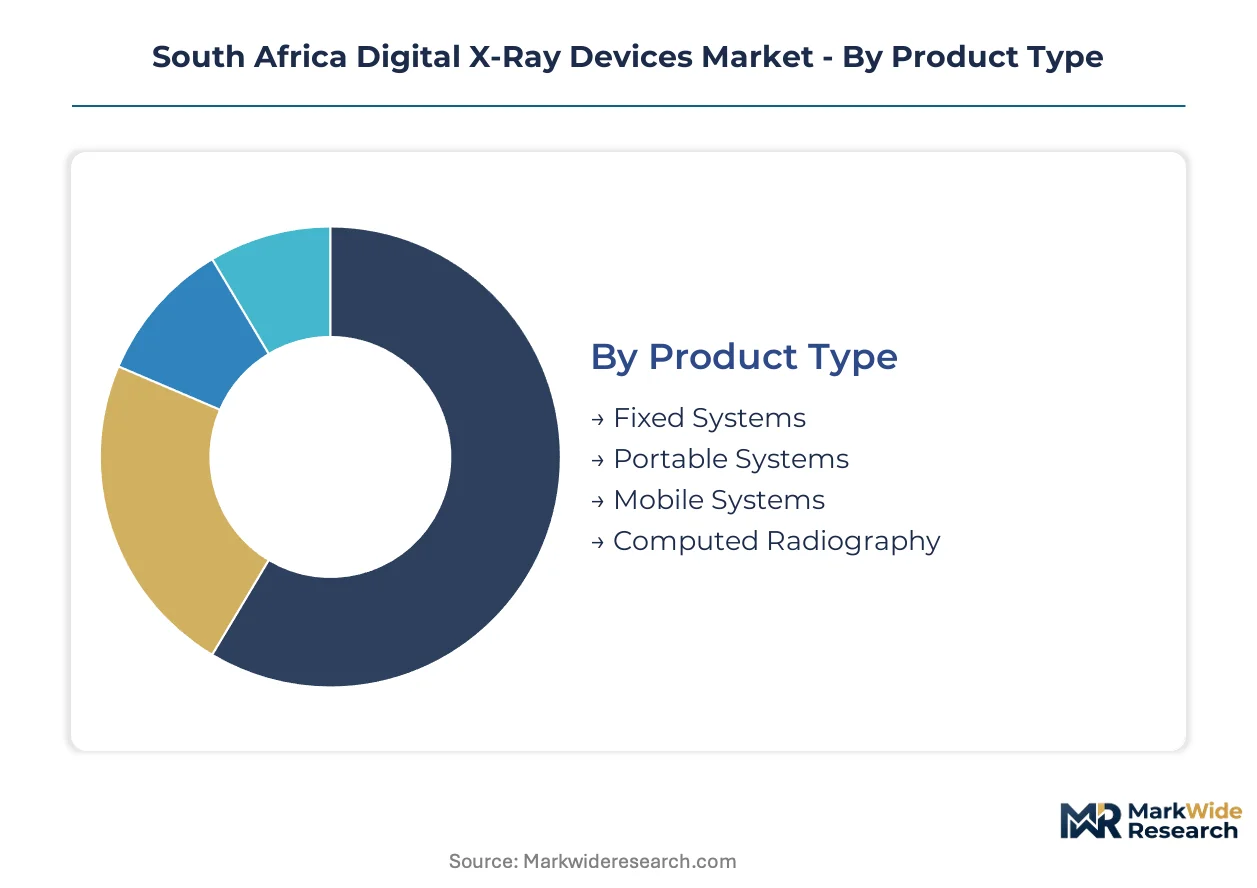
Digital X-ray segmentation in South Africa reveals distinct margin architectures across hardware formats, with procurement centralization under NHI policy reshaping how vendors prioritize product development and service deployment. Each category reflects divergent capital intensity, regulatory exposure, and customer concentration patterns that determine competitive positioning.
Product Type:
Margin pools concentrate in systems that balance upfront revenue with long-term service attachment, favoring vendors with localized technical infrastructure.
- Fixed Systems:These permanent radiology suite installations integrate high-power generators with ceiling-suspended tubes and bucky tables. Tertiary hospitals in Johannesburg and Pretoria anchor demand, where patient volumes justify dedicated rooms and vendor service contracts lock in multi-year relationships.
- Portable Systems:Battery-powered units weighing under 5kg enable bedside imaging in emergency departments and intensive care wards. Point-of-care protocols in Gauteng province are compressing diagnostic turnaround times and fragmenting purchasing authority from centralized radiology to individual clinical departments.
- Mobile Systems:Motorized C-arm configurations serve surgical suites and interventional procedures. Orthopedic theaters in private hospital chains represent the primary deployment sites.
- Computed Radiography:Cassette-based digital intermediaries bridge analog infrastructure and full digital workflows. Underfunded provincial hospitals in Eastern Cape and Limpopo delay conversion due to capital constraints.
The dominant share belongs to Fixed Systems, while Portable Systems is closing the gap fastest.
End User:
Customer concentration patterns split between consolidated public procurement and fragmented private purchasing, with divergent contract structures and compliance burdens.
- Hospitals:Public sector tenders through the National Department of Health mandate DICOM compliance and local service presence, compressing vendor margins while extending contract tenures. Private hospital groups in Johannesburg prioritize managed equipment service models.
- Diagnostic Centers:Independent imaging facilities concentrate in urban corridors with high patient throughput. These operators prioritize rapid image distribution and PACS integration to compete with hospital-affiliated radiology departments.
- Imaging Clinics:Specialized outpatient facilities focus on elective procedures with faster reimbursement cycles. Cape Town and Durban harbor the densest clusters.
- Research Institutions:University medical schools and clinical trial centers drive adoption of experimental detector materials and AI-assisted reconstruction algorithms. Academic medical centers in Pretoria anchor this segment.
Hospitals command the largest revenue base, though Diagnostic Centers are expanding most quickly as outpatient imaging decentralizes.
Technology:
Detector material selection determines dose efficiency, image latency, and retrofit compatibility—factors that reshape upgrade economics across South Africa's mixed installed base.
- Digital Flat Panel Detectors:Amorphous silicon or selenium active matrices deliver immediate image acquisition without cassette handling. New installations in Gauteng and KwaZulu-Natal increasingly specify wireless variants to eliminate cabling infrastructure.
- CCD Detectors:Optical coupling architectures persist in legacy installations where scintillator replacement extends functional life. Rural district hospitals maintain these systems due to limited capital replacement budgets.
- Wireless Detectors:Cesium iodide scintillator layers on thin-film transistor arrays enable single-operator positioning and ward-based deployment. SAHPRA post-market surveillance requirements elevate documentation burdens for distributors managing these Class IIb devices.
- Computed Radiography Systems:Photostimulable phosphor plates require laser scanning stations and cassette handling workflows. These systems fragment maintenance ecosystems and dilute training standardization across provincial health departments.
Digital Flat Panel Detectors hold the installed base majority, yet Wireless Detectors are gaining share fastest as point-of-care protocols proliferate.
Application:
Clinical use cases diverge in reimbursement rates, regulatory scrutiny, and AI integration potential—shaping vendor R&D allocation and training program design.
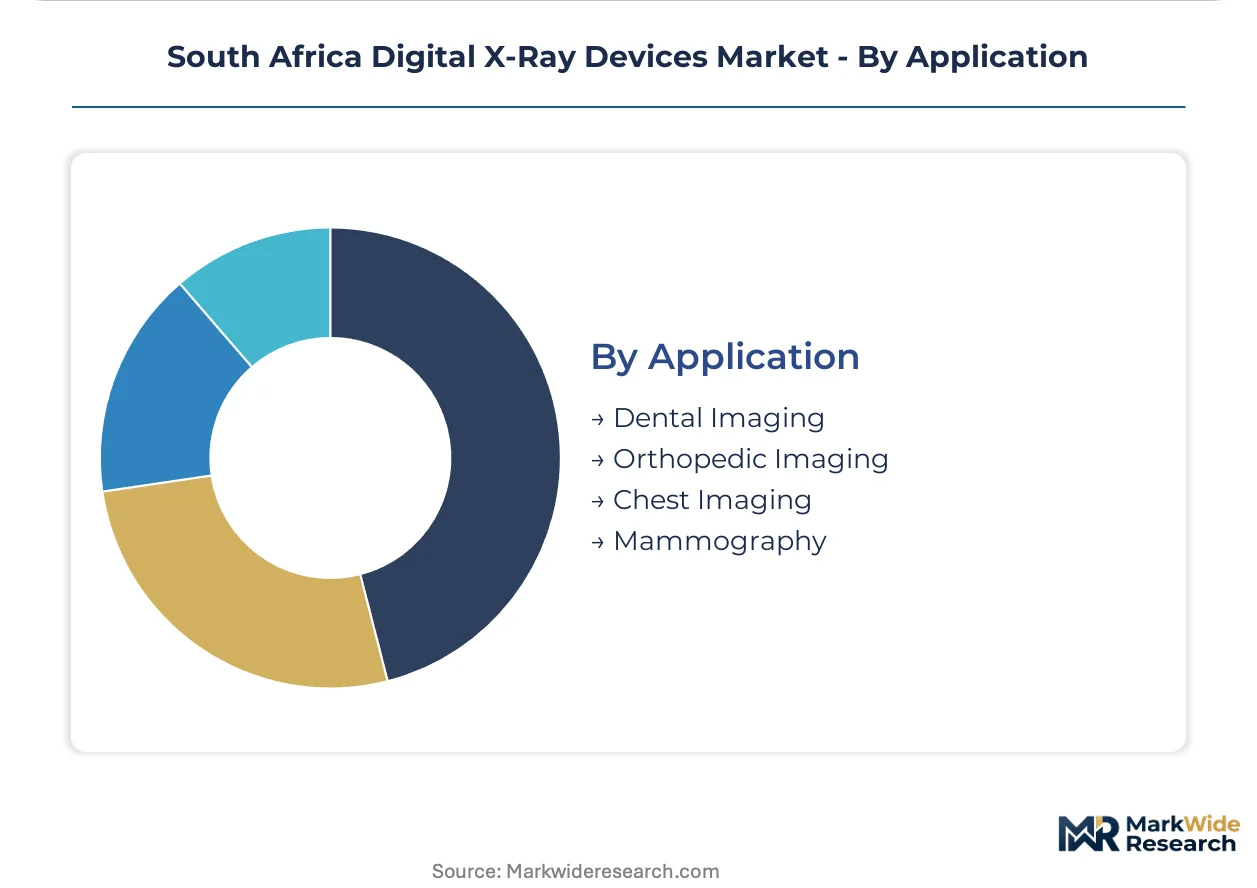
- Dental Imaging:Intraoral and panoramic systems serve private dental practices with high procedure frequency and rapid capital payback. Johannesburg's dense dental clinic networks drive regional concentration.
- Orthopedic Imaging:Weight-bearing extremity and spinal visualization requirements favor high-resolution detectors with specialized positioning capabilities. Sports medicine centers and trauma units in Cape Town generate concentrated demand.
- Chest Imaging:High-volume tuberculosis and pneumonia screening in public hospitals prioritizes throughput and low-dose protocols. The National Health Insurance policy is mandating standardized image quality metrics for these procedures.
- Mammography:Breast cancer screening programs require specialized compression devices and software for microcalcification detection. Academic medical centers anchor adoption, with rollout to district hospitals pending NHI funding allocation.
Chest Imaging dominates procedure volume, though Orthopedic Imaging is climbing fastest as trauma caseloads rise and sports medicine expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement concentrates buyer power within the National Department of Health, while private hospital chains fragment purchasing across Gauteng, KwaZulu-Natal, and Western Cape provinces. Provincial health departments operate as distinct tendering authorities, creating uneven digital conversion timelines across South Africa's nine provinces.
Gauteng
Johannesburg and Pretoria anchor the densest diagnostic imaging infrastructure in sub-Saharan Africa, with tertiary hospitals driving fixed system installations. The National Health Insurance policy mandates DICOM compliance for all new public tenders, compressing vendor qualification windows. Private hospital chains in Sandton and Rosebank corridors are deploying portable wireless detectors across multiple wards to eliminate patient transport bottlenecks.
KwaZulu-Natal
Durban's academic medical centers and district hospital networks generate concentrated demand for mobile C-arm systems in orthopedic and interventional suites. Treasury constraints have frozen direct capital procurement since 2023, accelerating managed equipment service contract adoption. The Port Elizabeth corridor's district hospitals operate with aging film-based infrastructure, creating retrofit opportunities for wireless detector providers.
Western Cape
Cape Town's private diagnostic centers and sports medicine facilities prioritize rapid image distribution and PACS integration to compete with hospital-affiliated radiology departments. The South African Health Products Regulatory Authority's 72-hour adverse event reporting requirement for Class IIb devices elevates documentation burdens for distributors. Stellenbosch's university medical school drives experimental detector material adoption through clinical trial partnerships.
Eastern Cape
Mthatha and surrounding rural districts represent the most underpenetrated digital imaging market in South Africa, with film-based infrastructure persisting due to capital constraints. The Bureau of Standards' electromagnetic compatibility testing filters uncertified imports from public tenders, narrowing supplier options. District hospitals in this corridor lack dedicated radiology suites, making portable systems the viable entry path.
Limpopo
Polokwane and rural health centers maintain computed radiography systems as digital intermediaries, fragmenting maintenance ecosystems and diluting training standardization. Legacy analog room retrofit complexity extends installation timelines, disrupting departmental throughput during conversion projects. The province's radiographer specialization gaps force reliance on vendor-contracted personnel for PACS administration.
South Africa Digital X-Ray Devices Market Competitive Landscape
Player mix skews toward multinational medical technology conglomerates with established service footprints across tertiary hospital networks. Three to four global manufacturers capture the bulk of public tender awards through pre-qualified vendor status and localized technical training academies. The competitive terrain rewards service density and regulatory compliance over hardware differentiation alone. Dominant moves include bundling digital flat panel upgrades with managed equipment service contracts, and consolidating multi-site service agreements spanning provincial health networks.
Among the established imaging technology providers, GE Healthcare, Siemens Healthineers, and Koninklijke Philips NV occupy positions that exemplify divergent competitive archetypes. GE Healthcare anchors its presence through localized technical training programs that cultivate radiographer loyalty and system familiarity. Siemens Healthineers leverages its installed base across tertiary hospitals to sustain recurring revenue through service contracts and detector upgrades. Philips competes by bundling hardware with managed equipment service agreements that transfer obsolescence risk from hospital balance sheets to vendor portfolios.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Canon Medical Systems |
| Carestream Health Inc |
| Agfa Healthcare |
| Shimadzu Corporation |
| DRGEM Africa |
| Others |
Value Network & Pricing Analysis
Fourteen-week generator lead times from German and Japanese manufacturing clusters compress distributor pricing power, forcing South African vendors to absorb euro-yen volatility or surrender tender margins. This inventory-to-pricing feedback loop concentrates margin pools among established importers with pre-qualified SABS electromagnetic compatibility certification and locked generator supply agreements.
Pricing Analysis
Cost-plus contracts with euro-denominated indexation dominate public hospital tenders, transferring currency risk to vendors while capping upside. Price differentiation hinges on SAHPRA registration tier and local service presence density, with wireless detector retrofit kits commanding premiums over full-room replacements. Cost compression in portable system tiers is intensifying because NHI procurement centralization favors volume aggregators. Provincial health departments exhibit highest price sensitivity, while private hospital chains in Johannesburg prioritize managed equipment service bundles over capital expenditure minimization.
Supply Chain Analysis
Germany and Japan anchor x-ray tube and high-voltage generator production, with South Korean flat-panel detector manufacturing expanding as a secondary source. South African distributors draw from these clusters for amorphous selenium substrates, cesium iodide scintillator layers, and thin-film transistor arrays. Single-source vulnerability concentrates in generator supply chains, where Japanese manufacturers control high-power tube architectures. Distribution runs through Johannesburg-based technical importers with SAHPRA-licensed warehousing and Pretoria-corridor service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
National Health Insurance procurement centralization is shifting buyer power toward the National Department of Health, fragmenting provincial tender autonomy and compressing vendor qualification windows.
For Market Incumbents: Shield installed base revenue by embedding PACS administrators within hospital IT departments and extending detector upgrade cycles through wireless retrofit compatibility. Counter emerging portable system specialists by consolidating multi-site service contracts across Gauteng and KwaZulu-Natal provincial networks. Certification investment in SAHPRA Class IIb quality management systems locks out smaller importers from tender participation. For New Entrants and Emerging Players: Rural radiographer training gaps in Eastern Cape and Limpopo present service-layer entry points where Siemens Healthineers and GE Healthcare under-serve district hospitals. Wireless detector retrofit kits for film-based infrastructure in Mthatha and Port Elizabeth corridors offer lowest competitive friction. Go-to-market through Bureau of Standards pre-certification partnerships accelerates tender eligibility. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because managed equipment service contracts displace capital purchase models and extend vendor tenures across provincial health networks. Acquisition targets include regional distributors with SAHPRA registration portfolios and established technical training academies. Monitor NHI funding allocation announcements as inflection indicators for district hospital digital conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Harmonization | Streamlined pathways accelerate market entry for certified manufacturers, reducing time-to-revenue for compliant portfolios. |
| Wireless Detector Retrofit Deployment | Extends functional life of existing generator infrastructure without full room replacement, concentrating margin pools. |
| Managed Equipment Service Expansion | Bundles hardware, maintenance, and consumables into per-procedure fees, transferring obsolescence risk to vendors. |
| Localized Technical Training Academy | Cultivates radiographer loyalty and system familiarity, locking in multi-year service relationships across tertiary hospitals. |
| AI-Assisted Diagnostic Integration | Machine learning algorithms for automated fracture detection create bundled value propositions for tertiary hospital radiology departments. |
Research Methodology
Operator-level perspectives from hospital biomedical engineers, GPO contracts managers, SAHPRA regulatory affairs personnel, and provincial health department procurement officers anchored the qualitative base. These primary insights combined with secondary validation from SAHPRA device registration databases, National Department of Health tender specifications, SABS electromagnetic compatibility testing records, and hospital procurement contract disclosures. Bottom-up installation base modeling and top-down expenditure flow analysis triangulated market sizing.
Sensitivity analysis across detector technology adoption curves, NHI procurement centralization timelines, and currency volatility bands shaped the analytical framework. Segmentation dimensions modeled include product type, end user category, detector technology, and clinical application across the projection horizon. CAGRs derived from installed base replacement cycles and point-of-care protocol expansion rates. Forecast inputs incorporated generator import lead time volatility and radiographer training pipeline capacity constraints.
Underlying assumptions cover SAHPRA registration pathway stability, NHI funding allocation continuity, and generator supply chain reliability, with deviation risk concentrated in euro-yen exchange rate volatility and provincial treasury constraint severity. Recalibration cycles align with material shifts in NHI procurement centralization pace and SAHPRA post-market surveillance requirement amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Embolization Plugs Market
Medical Devices
Otoscope Devices Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Digital Magnifiers Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Implantable Port Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Aesthetic Devices Market