
 Backlit Displays Market | 2026-2036
Backlit Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Backlit Displays Market Analytics
South Korea is reconfiguring its domestic backlit display ecosystem through fresh capital deployment in Gumi and Tangjeong. Samsung Electronics leverages captive OLED capacity to anchor premium smartphone panel supply. LG Display sustains leadership in large-format OLED television substrates through differentiated deposition techniques. BOE Technology Group competes aggressively on LCD cost structure while extending Gen 10.5 manufacturing scale.
Backlit displays are illumination-assisted visual output systems employing LED, CCFL, or electroluminescent sources positioned behind or adjacent to a modulating panel, typically operating at luminance levels between 250 and 500 cd/m² for indoor commercial use. Their primary purpose is to render visible imagery under variable ambient light conditions across consumer, industrial, and mobility environments. LCD panels still occupy the largest installed base among product types, though Mini LED backlighting is gaining structural share in high-end monitor and television configurations where local dimming zones exceed 1,000 segments. Automotive displays represent the fastest-growing application segment as dashboard integration requirements multiply across electric vehicle platforms.
REACH substance restrictions in Europe constrain certain phosphor and rare-earth formulations used in LED backlighting, while China's GB standards mandate escalating energy efficiency thresholds for commercial display products. The FCC regulates electromagnetic emissions from displays sold in the United States, creating divergent testing protocols for multi-regional manufacturers. South Korea's METI-aligned efficiency benchmarks shape domestic procurement criteria for public-sector digital signage. Stakeholders must monitor regulatory divergence between efficiency mandates and material restrictions when configuring regional product portfolios.
Market Dynamics
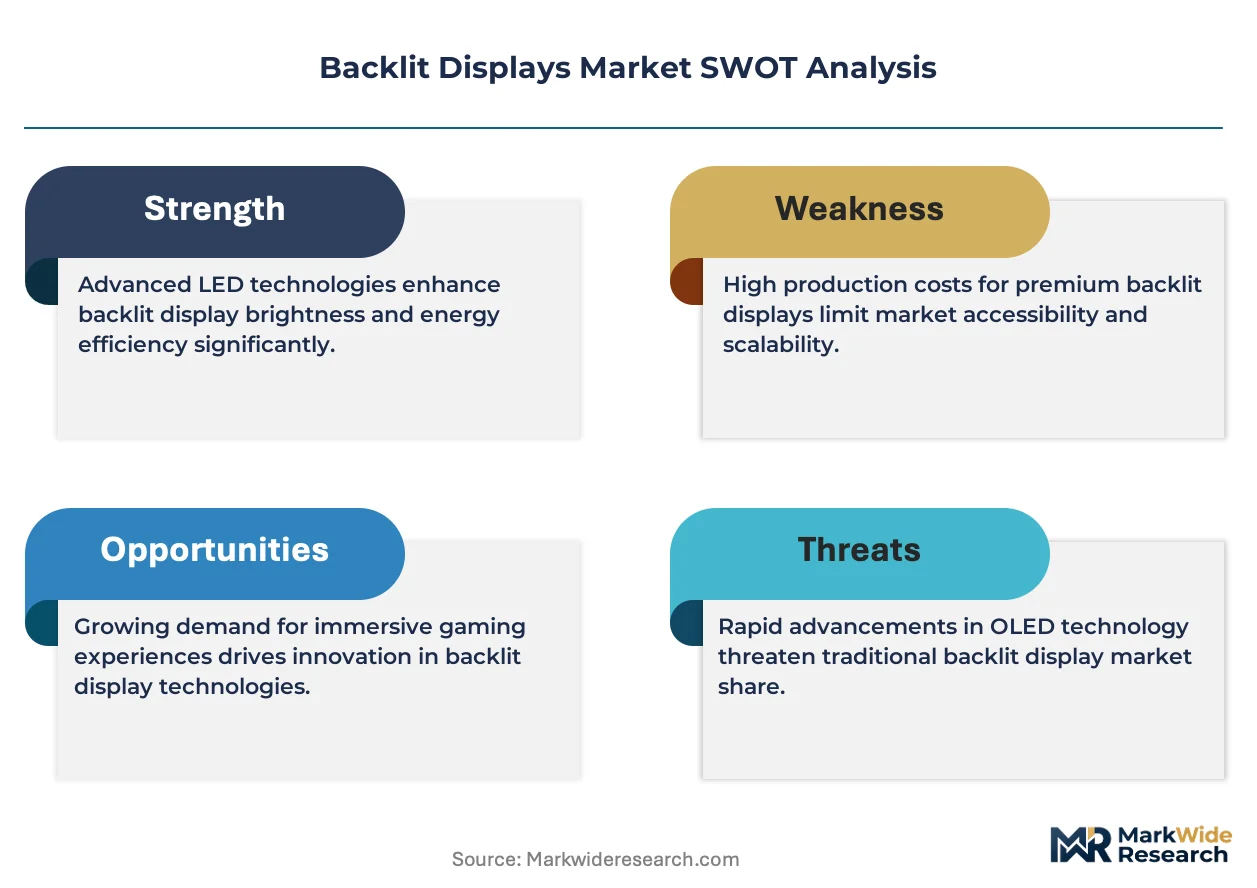
Mini LED backlighting with 1,000-plus local dimming zones is compressing conventional LCD value chains as premium monitor and television buyers demand contrast performance previously reserved for OLED panels.
Growth Catalysts
- Automotive infotainment expansion:Electric vehicle OEMs are multiplying dashboard screen counts per cabin, creating pull-through for high-brightness panels certified to automotive temperature and vibration standards.
- China GB energy efficiency mandates:Escalating efficiency thresholds for commercial display products are accelerating LED phosphor reformulation and driver IC optimization across the supply base.
- Gumi-Tangjeong cluster concentration:South Korea's concentrated display manufacturing ecosystem enables rapid process iteration and shared metrology infrastructure for next-generation deposition equipment.
Market Restraints
- Rare-earth phosphor cost volatility:Europium and terbium price swings constrain LED backlighting cost predictability, particularly for full-array local dimming configurations requiring precise spectral output.
- South Korean supply concentration:OLED substrate and driver IC production clusters in Gyeonggi Province create geographic vulnerability to single-point disruption from seismic or geopolitical events.
- CCFL technical obsolescence:Mercury content restrictions under EU RoHS and REACH substance limitations have eliminated legacy cold-cathode technology as a viable cost alternative for industrial retrofit applications.
Strategic Opportunities
- India commercial signage underpenetration:BIS certification harmonization with IEC standards is lowering import barriers for energy-efficient backlit displays in retail and transit applications.
- Healthcare diagnostic imaging convergence:DICOM calibration standards for medical displays are creating demand for 1,000 cd/m²-plus luminance panels with stable grayscale tracking across 10-year lifecycles.
- Japan METI efficiency procurement incentives:Public-sector digital signage tenders now incorporate total cost-of-ownership scoring that rewards Mini LED and advanced dimming architectures.
Industry Challenges
- Gen 10.5 glass substrate handling expertise:The shift to 2,940mm x 3,370mm motherglass dimensions requires scarce automation engineering talent for thermal expansion control during thin-film transistor deposition.
- FCC and CE electromagnetic compliance divergence:Multi-regional manufacturers face non-overlapping radiated emission test protocols that extend certification timelines by four to six months for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backlit Displays Market |
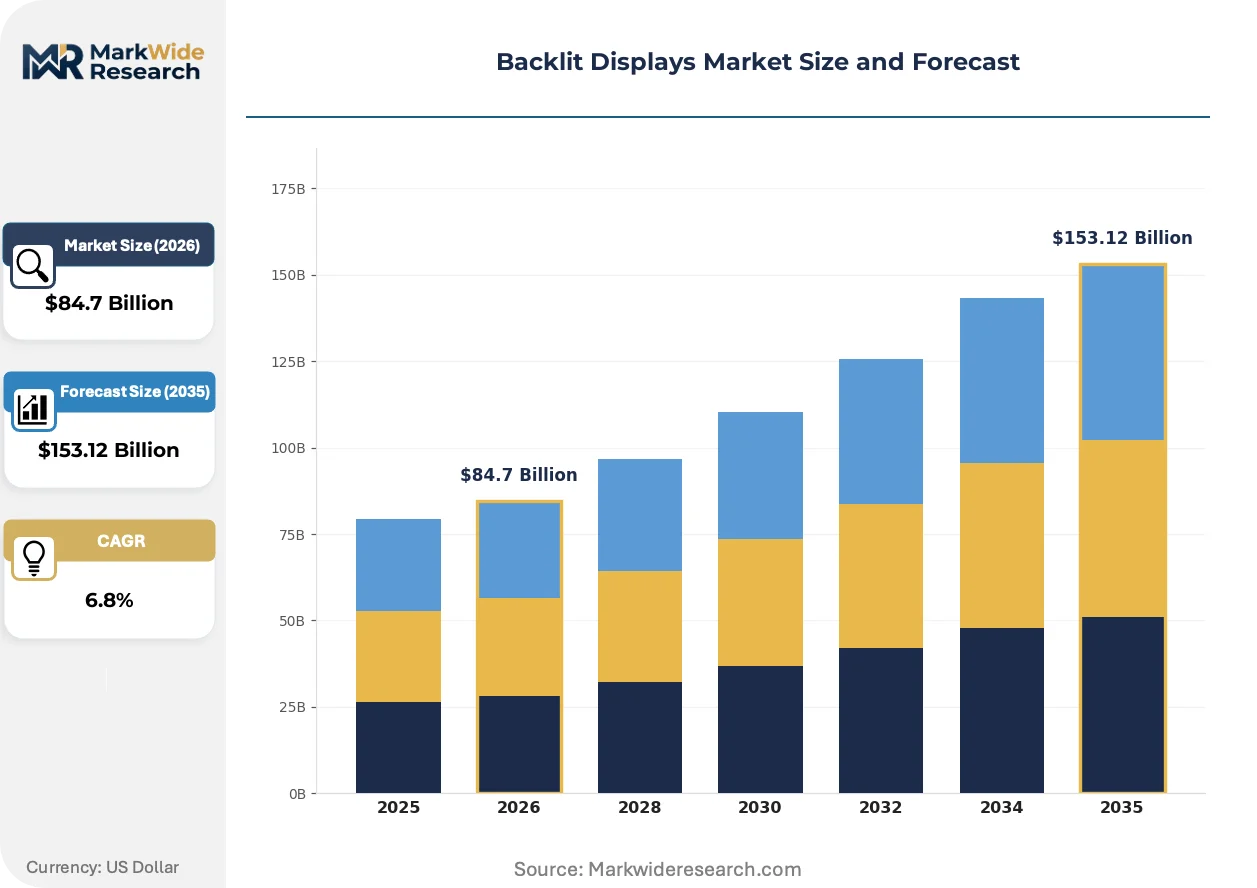
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Mini LED Application: Televisions, Monitors, Smartphones, Automotive Displays End User: Consumer Electronics, Industrial, Automotive, Healthcare Technology: Edge-Lit, Direct-Lit, Quantum Dot, Backlight Control |
| Companies Covered | Samsung Electronics, LG Display, BOE Technology Group, AU Optronics, Sharp Corporation, LG Innotek, NICHIA, Lumileds, Seoul Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backlit Displays Market Evolving Landscape
Backlit display architectures are fragmenting along performance-tier lines as local dimming zone counts become the primary specification differentiator between premium and standard product categories.
Quantum dot enhancement film is virtualizing conventional color filter functions by converting blue LED emission into narrow-band red and green light at the backlight level. Television OEMs are adopting this architecture for 85-inch-plus screen sizes where OLED manufacturing yields remain constrained. The technology is virtualizing the traditional LCD supply chain by shifting color reproduction responsibility from panel fabs to backlight assemblers.
REACH substance restrictions in Europe are constraining specific phosphor formulations containing cadmium-based quantum dots and certain rare-earth activators used in LED conversion layers. Manufacturers serving EU markets are reformulating spectral conversion materials to maintain color gamut coverage while eliminating restricted substances. Medical and professional monitor segments face the steepest compliance burden due to their stringent color accuracy requirements.
Fleet buyers in North American digital out-of-home advertising are consolidating procurement around five-year total cost-of-ownership contracts that bundle hardware, installation, and remote monitoring services. This model displaces traditional capital expenditure purchases through advertising network operators. The shift is most visible in transit hub deployments across the United States where municipal authorities prefer operational expenditure structures.
Backlit Displays Market Segmentation
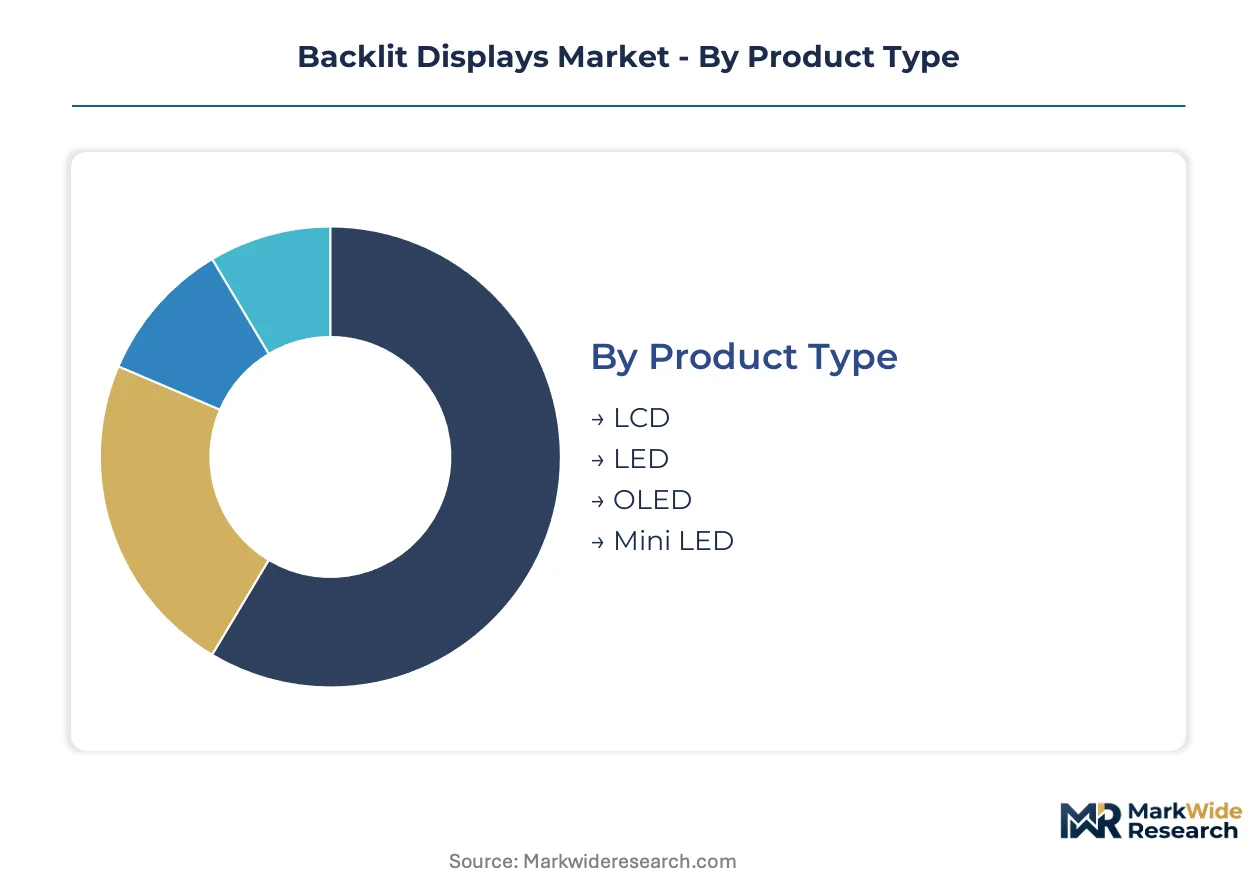
Backlit display procurement decisions fragment across four distinct dimensions. Technology selection determines luminance performance and energy compliance. Application requirements dictate size formats and certification standards. Each segmentation axis carries independent pricing logic and supplier qualification criteria.
Product Type:
Technology cost tiers separate legacy LCD infrastructure from emerging premium architectures. Panel selection directly determines backlight complexity and driver IC specification.
- LCD:Twisted-nematic and in-plane switching architectures dominate commercial signage and budget monitor segments. China's GB energy efficiency mandates are accelerating LED phosphor reformulation across LCD backlights for domestic market compliance.
- LED:Full-array and edge-lit configurations serve mainstream television and desktop monitor production. South Korea's Gumi-Tangjeong cluster concentrates LED backlight module assembly for premium smartphone panel supply.
- OLED:Self-emissive organic stacks eliminate separate backlight layers entirely. LG Display sustains large-format television substrate leadership through differentiated deposition techniques in Gyeonggi Province.
- Mini LED:Thousands of local dimming zones deliver contrast performance approaching OLED at reduced manufacturing cost. Television OEMs are adopting this architecture for 85-inch-plus screen sizes where OLED yields remain constrained.
LCD commands the established base. The steepest expansion runs through Mini LED as premium buyers demand zone-count differentiation.
Application:
End-use volume concentration varies sharply by screen size and certification burden. Automotive and medical applications impose the steepest thermal and vibration testing requirements.
- Televisions:Residential display procurement centers on 55-inch to 85-inch formats with 4K resolution minimum. Quantum dot enhancement film is virtualizing color filter functions at the backlight level for 85-inch-plus screen sizes.
- Monitors:Desktop and professional panels operate at 250-500 cd/m² luminance for indoor commercial environments. DICOM calibration standards are creating demand for 1,000 cd/m²-plus panels with stable grayscale tracking in healthcare diagnostic imaging.
- Smartphones:Handheld panels prioritize power efficiency and thin-form-factor integration. Samsung Electronics leverages captive OLED capacity to anchor premium smartphone panel supply.
- Automotive Displays:Dashboard and infotainment screens multiply per cabin across electric vehicle platforms. Electric vehicle OEMs are expanding procurement for high-brightness panels certified to automotive temperature and vibration standards.
Television volume anchors manufacturing scale. Automotive displays are climbing the fastest as cabin digitization multiplies screen counts per vehicle platform.
End User:
Customer type determines procurement contract structure and lifecycle service expectations. Fleet buyers increasingly demand total cost-of-ownership bundling.
- Consumer Electronics:Retail channel distribution emphasizes seasonal volume spikes and rapid product refresh cycles. Brand OEMs consolidate procurement around five-year total cost-of-ownership contracts in North American digital out-of-home advertising.
- Industrial:Factory automation and control room applications prioritize 24/7 operational reliability. Mercury content restrictions under EU RoHS have eliminated legacy CCFL technology as a viable retrofit option.
- Automotive:Tier-1 suppliers manage qualification programs spanning thermal cycling, mechanical shock, and electromagnetic compliance. FCC and CE electromagnetic compliance divergence extends certification timelines by four to six months for unified product platforms.
- Healthcare:Diagnostic imaging and surgical visualization require DICOM calibration and extended luminance stability. REACH substance restrictions constrain cadmium-based quantum dots and rare-earth activators used in LED conversion layers for EU market access.
Consumer electronics commands unit volume leadership. Healthcare is gaining share fastest as diagnostic imaging convergence drives specialized panel demand.
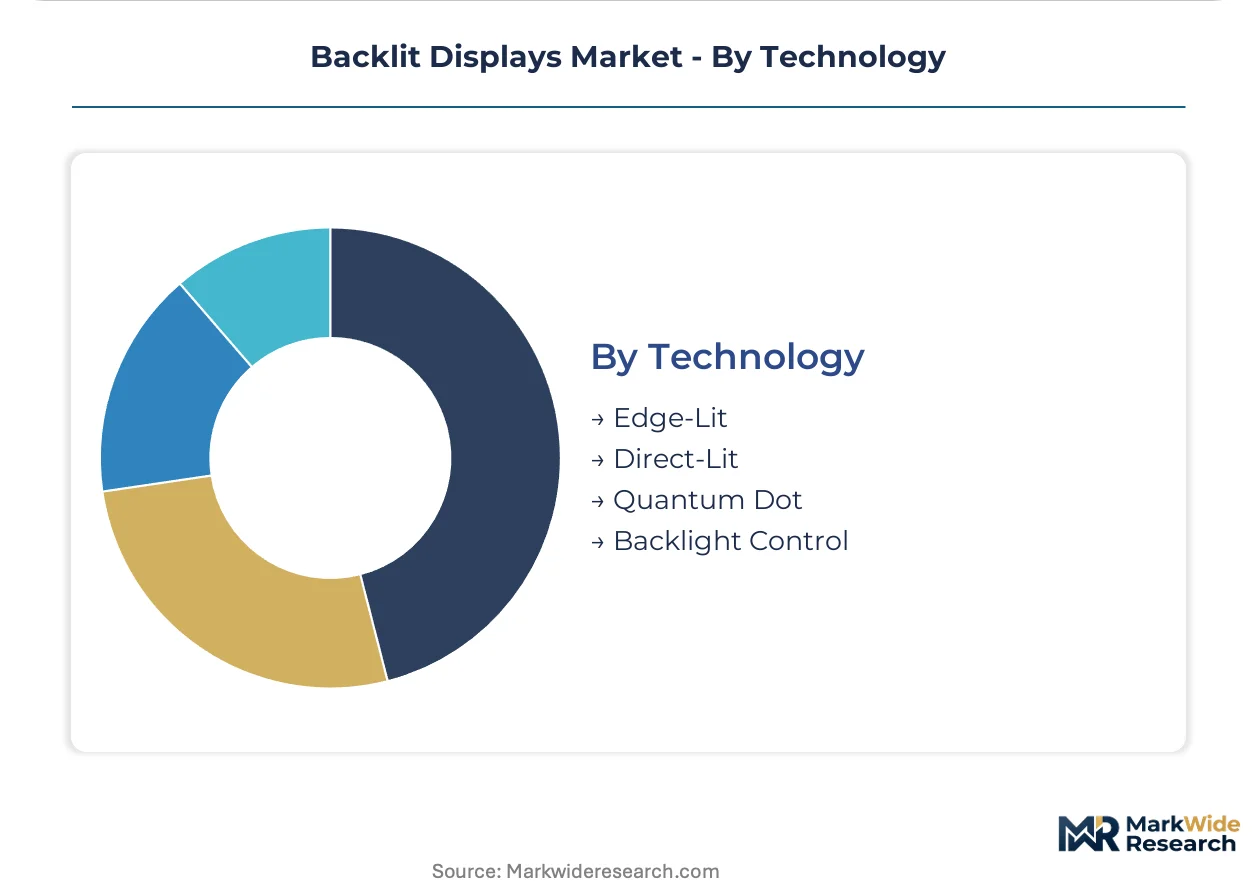
Technology:
Backlight architecture selection determines local dimming capability and energy efficiency performance. Driver IC complexity scales directly with zone count.
- Edge-Lit:LED arrays positioned along panel perimeters enable thin-form-factor designs at reduced cost. This architecture serves budget television and mainstream monitor segments where contrast performance is secondary to price positioning.
- Direct-Lit:Full-array LED positioning behind the panel enables zone-based dimming without Mini LED density. Larger form factors in commercial signage adopt direct-lit configurations for uniform luminance distribution.
- Quantum Dot:Spectral conversion films transform blue LED emission into narrow-band red and green light at the backlight level. Manufacturers serving EU markets are reformulating spectral conversion materials to maintain color gamut while eliminating REACH-restricted substances.
- Backlight Control:Driver IC and firmware architectures manage dimming algorithms and power sequencing. Japan METI efficiency procurement incentives now incorporate total cost-of-ownership scoring that rewards advanced dimming architectures in public-sector digital signage.
Edge-Lit retains the largest installed base. Quantum Dot is expanding most quickly as color gamut competition intensifies in premium television tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backlit display manufacturing clusters in Gumi and Tangjeong anchor South Korean supply, while Chinese scale operations and Japanese precision component bases complete the tripartite Asian production architecture. Regulatory divergence across efficiency mandates and material restrictions shapes regional product configurations. Demand localization follows automotive OEM expansion and digital signage procurement programs.
South Korea
Automotive infotainment screen demand from Hyundai-Kia and Genesis platforms drives high-brightness panel procurement. METI-aligned efficiency benchmarks shape public-sector digital signage tenders with total cost-of-ownership scoring. The Gumi-Tangjeong cluster concentrates OLED substrate production and next-generation deposition equipment metrology infrastructure.
China
GB standards for display energy efficiency mandate escalating thresholds for commercial products sold domestically. BOE Technology Group extends Gen 10.5 manufacturing scale for LCD cost leadership. Yangtze River Delta and Pearl River Delta hubs integrate LED phosphor reformulation with driver IC optimization for compliance.
Japan
METI efficiency procurement incentives reward Mini LED and advanced dimming architectures in public infrastructure tenders. Sharp Corporation maintains legacy television panel operations while diversifying into industrial display applications. Chubu and Kansai regions concentrate precision optical film and driver semiconductor fabrication.
United States
FCC electromagnetic emission regulations create divergent testing protocols that extend certification timelines for multi-regional manufacturers. Fleet buyers in digital out-of-home advertising consolidate procurement around five-year total cost-of-ownership contracts. Texas and Arizona host backend assembly operations serving North American automotive OEMs.
Germany
REACH substance restrictions constrain phosphor formulations containing cadmium-based quantum dots for EU market access. Automotive Tier-1 suppliers manage qualification programs for dashboard integration across electric vehicle platforms. Bavaria and Baden-Württemberg host control room and industrial automation display integration centers.
Backlit Displays Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in backlight modules and driver semiconductors. The vendor base stratifies across three tiers: captive display divisions of consumer electronics conglomerates, independent panel specialists with scale advantages, and niche component suppliers focused on spectral conversion or thermal management. Strategic moves concentrate on capacity expansion in Gen 10.5 glass handling and backward integration into LED epitaxy.
Among Asian panel fabricators, Samsung Electronics, LG Display, and BOE Technology Group occupy positions across the technology spectrum from OLED self-emissive stacks to Mini LED local dimming architectures. Seoul Semiconductor and NICHIA exemplify the upstream component tier supplying spectral conversion and high-efficiency LED dies. The competitive dynamic pits Korean OLED deposition expertise against Chinese LCD scale economics and Japanese precision in optical films and driver ICs.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| BOE Technology Group |
| AU Optronics |
| Sharp Corporation |
| LG Innotek |
| NICHIA |
| Lumileds |
| Seoul Semiconductor |
| Others |
Value Network & Pricing Analysis
Gumi and Tangjeong's concentrated OLED substrate capacity anchors downstream pricing power for premium panel tiers, while Chinese Gen 10.5 scale operations compress mid-range LCD quotations through aggressive depreciation schedules. Buyers face divergent cost structures depending on whether procurement taps Korean deposition expertise or Yangtze River Delta manufacturing density.
Pricing Analysis
China's GB energy efficiency mandates dictate the pricing tier structure across commercial display procurement. Three-tier pricing separates premium Mini LED local-dimming configurations from standard direct-lit LED and economy edge-lit alternatives. Price differentiation hinges on certification grade for automotive temperature standards and volume scale for fleet signage contracts. Cost compression in standard LCD tiers is intensifying because BOE Technology Group extends Gen 10.5 manufacturing scale. Fleet buyers in North American digital out-of-home advertising demonstrate highest price sensitivity through total cost-of-ownership contracting, while healthcare diagnostic imaging buyers prioritize DICOM calibration stability over unit cost.
Supply Chain Analysis
Extended payment terms from South Korean panel fabricators to LED epitaxy suppliers characterize upstream financing arrangements in this supply chain. Manufacturing concentrates in South Korea, China, and Japan, with Gumi-Tangjeong anchoring OLED deposition and Yangtze River Delta hubs integrating phosphor reformulation. Production draws from rare-earth phosphors containing europium and terbium, quantum dot enhancement films, and Gen 10.5 glass substrates measuring 2,940mm by 3,370mm. Single-source vulnerability around OLED driver IC fabrication in Gyeonggi Province presents structural risk. Distribution runs through Tier 1 automotive suppliers, digital signage network operators, and consumer electronics OEMs with divergent certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The backlit display market is recovering from cyclical inventory correction as automotive OEMs multiply cabin screen counts per electric vehicle platform. Panel demand normalization depends on electric vehicle production schedules and infotainment specification upgrades.
For Market Incumbents: Harden supply chain resilience by diversifying driver IC sourcing beyond Gyeonggi Province concentration and securing captive LED epitaxy capacity through backward integration into Seoul Semiconductor or NICHIA supply relationships. Mini LED local dimming architectures from emerging Chinese competitors threaten premium positioning; defend through accelerated deposition equipment iteration in Gumi-Tangjeong shared metrology infrastructure.
For New Entrants and Emerging Players: India's commercial signage underpenetration offers lowest barrier to entry as BIS certification harmonization with IEC standards lowers import friction. Target retail and transit hub applications where municipal authorities prefer operational expenditure structures over capital expenditure procurement. Establish partnerships with Yangtze River Delta LED phosphor reformulators to meet China's GB efficiency mandates without indigenous R&D investment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital out-of-home advertising network operators with five-year total cost-of-ownership bundling contracts. Long-term viability across the analysis window favors component specialists with spectral conversion expertise over commodity panel assemblers. Monitor automotive Tier 1 supplier qualification timelines as inflection indicator for high-brightness panel demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Gen 10.5 Capacity Expansion | BOE Technology Group extends glass substrate scale for LCD cost leadership in 85-inch-plus formats. |
| Mini LED Backlight Integration | Tier 1 suppliers adopt thousand-zone local dimming for premium automotive infotainment specifications. |
| Quantum Dot Reformulation | Manufacturers eliminate REACH-restricted cadmium to maintain EU market access for medical displays. |
| Automotive Qualification Programs | Hyundai-Kia and Genesis platforms drive high-brightness panel procurement with vibration certification. |
| Digital Signage Service Bundling | North American fleet buyers consolidate procurement around remote monitoring and installation contracts. |
Research Methodology
Operator-level perspectives from display procurement managers at automotive OEMs, LED backlight module engineers, digital signage network operators, and regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings from panel fabricators, FCC electromagnetic emission test databases, and China's GB standard disclosure protocols. Bottom-up triangulation across application segments and top-down reconciliation against manufacturing capacity announcements ensured analytical consistency.
Scenario-bracketing framed the projection horizon with conservative, baseline, and accelerated automotive infotainment penetration assumptions. Segmentation dimensions modeled include product technology, application vertical, end-user contract structure, and regional regulatory cluster. CAGRs derived from installed base turnover rates and replacement cycle compression in fleet signage. Forecast inputs incorporated electric vehicle platform screen count specifications and METI efficiency procurement incentive uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese Gen 10.5 operators or sudden phosphor supply disruptions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Europe Microdisplay Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Light Field Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Global Wearable Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Global OLED Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Electronic Display Market
Display Technologies
Smartphone Display Market
Display Technologies
QLED Display Market
Display Technologies
Asia Pacific Computer Monitor Market