
 LED Downlight Market | 2026-2036
LED Downlight Market Size, Share, and Industry Trends Forecast 2026-2036
LED Downlight Market Intelligence
The capital-intensity divergence between chip-scale packaging specialists and assembly-only contractors is unwinding as wafer-level LED economics favor integrated manufacturers. Signify Holding leverages captive semiconductor capacity to control phosphor deposition and thermal management costs. Acuity Brands Inc anchors its position through deep architectural specification relationships and tunable-white R&D pipelines. Cree Lighting competes on silicon-carbide substrate expertise that extends efficacy thresholds beyond conventional sapphire-based architectures.
An LED downlight is a ceiling-embedded luminaire employing a light-emitting diode array as its primary source, typically housed within a die-cast aluminum heat sink with a correlated color temperature range of 2700K to 5000K and efficacy ratings exceeding 100 lumens per watt. Its primary commercial purpose is to deliver directional, energy-efficient illumination with minimal ceiling aperture while supporting dimming protocols and smart-control integration. Recessed installations dominate volume across new construction pipelines, though retrofit segments are gaining share as building owners replace halogen and CFL housings without full ceiling reconstruction. Smart lighting technology commands premium positioning as BACnet and DALI-2 interoperability become baseline requirements in Class A office specifications.
EPA ENERGY STAR certification and California Title 24 building standards shape minimum efficacy and controllability thresholds for products sold in the United States, while EU Ecodesign Directive 2019/2020 mandates phased lumen maintenance and standby power limits across member states. China's GB standards enforced by SAMR impose domestic market access requirements that foreign manufacturers must meet through local testing partnerships. Stakeholders must monitor how tightening F-Gas Regulation phase-down timelines interact with LED thermal management designs that historically relied on fluorinated greenhouse gas-based manufacturing processes.
Market Dynamics
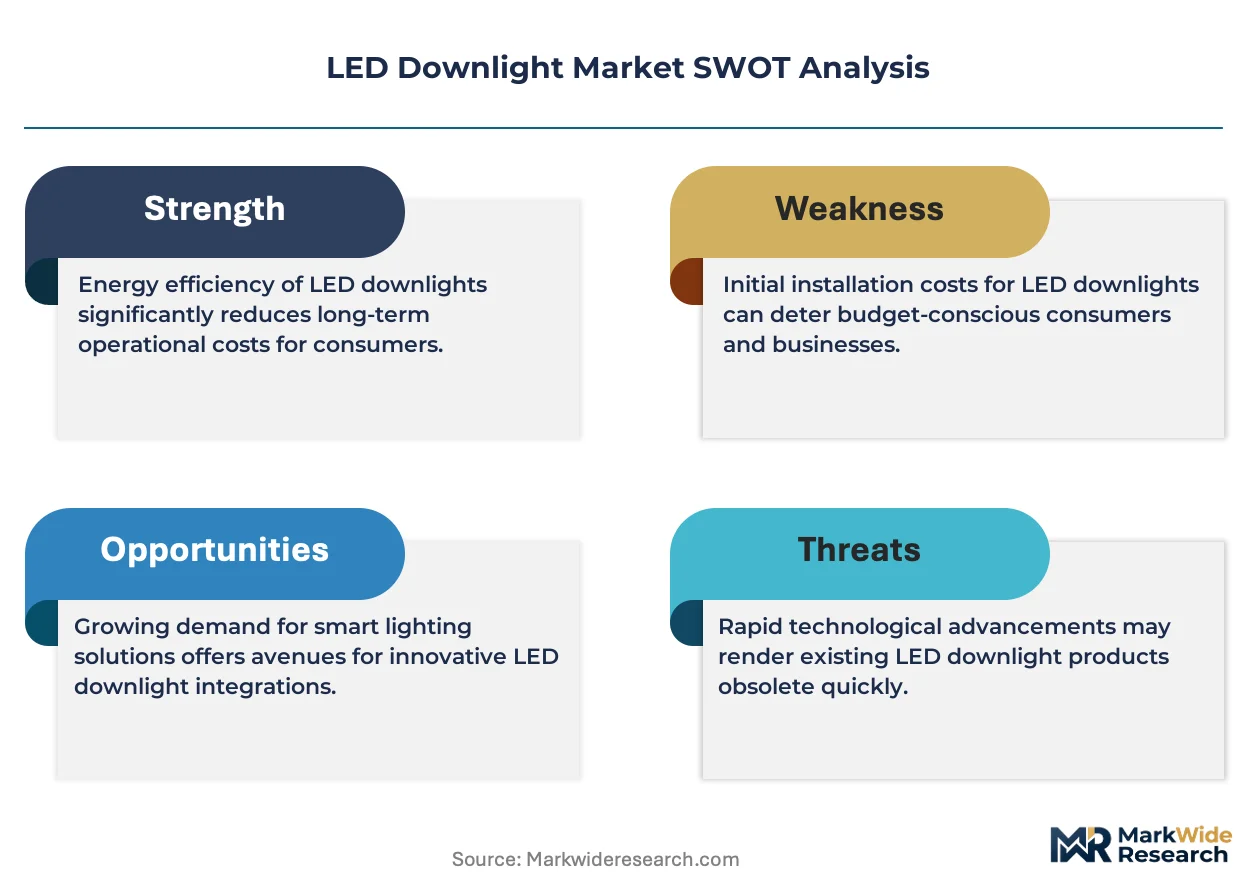
Wafer-level LED economics are consolidating manufacturing advantage around integrated chip-scale packaging specialists, compressing margins for assembly-only contractors unable to control phosphor deposition and thermal management costs in-house.
Growth Catalysts
- EU Ecodesign Directive 2019/2020:Phased lumen maintenance and standby power mandates across member states force portfolio upgrades toward higher-efficacy architectures, accelerating replacement cycles in commercial installations.
- Silicon-carbide substrate expertise:Advanced thermal conductivity properties extend efficacy thresholds beyond conventional sapphire-based LED architectures, opening premium positioning in high-lumen commercial specifications.
- China's GB standards enforcement:SAMR-mandated domestic market access requirements compel foreign manufacturers to establish local testing partnerships, concentrating compliant supply within certified distribution channels.
Market Restraints
- Aluminum heat sink input volatility:Die-cast aluminum pricing sensitivity constrains margin stability for luminaire housings, particularly affecting mid-tier product lines with limited pricing power.
- F-Gas Regulation phase-down timelines:Tightening EU restrictions on fluorinated greenhouse gas-based manufacturing processes interact with legacy LED thermal management designs, forcing process requalification costs.
- Fluorescent and halogen residual stock:Existing CFL and halogen housing inventories in commercial building basements extend effective substitution timelines in price-sensitive retrofit segments.
Strategic Opportunities
- India's building energy code expansion:BIS enforcement of efficacy standards in commercial construction creates first-mover advantage for ENERGY STAR-equivalent certified product lines in underpenetrated metropolitan markets.
- BACnet and DALI-2 convergence:Interoperability between building automation protocols and tunable-white control systems opens specification access in Class A office verticals previously locked to proprietary ecosystems.
- Utility-sponsored LED transition programs:Subsidized retrofit financing in Germany and the United States reduces upfront capital barriers, accelerating payback calculations for building owners.
Industry Challenges
- Phosphor deposition process engineering talent:Scarcity of wafer-level packaging specialists with quantum dot and ceramic phosphor expertise constrains captive capacity expansion timelines.
- Multi-protocol certification complexity:Simultaneous ENERGY STAR, California Title 24, and EU CE marking requirements extend product launch timelines and testing expenditure.
- Legacy dimming infrastructure incompatibility:Forward-phase and reverse-phase dimmer mismatch with LED drivers creates field failure liability and specifier hesitation in renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Downlight Market |
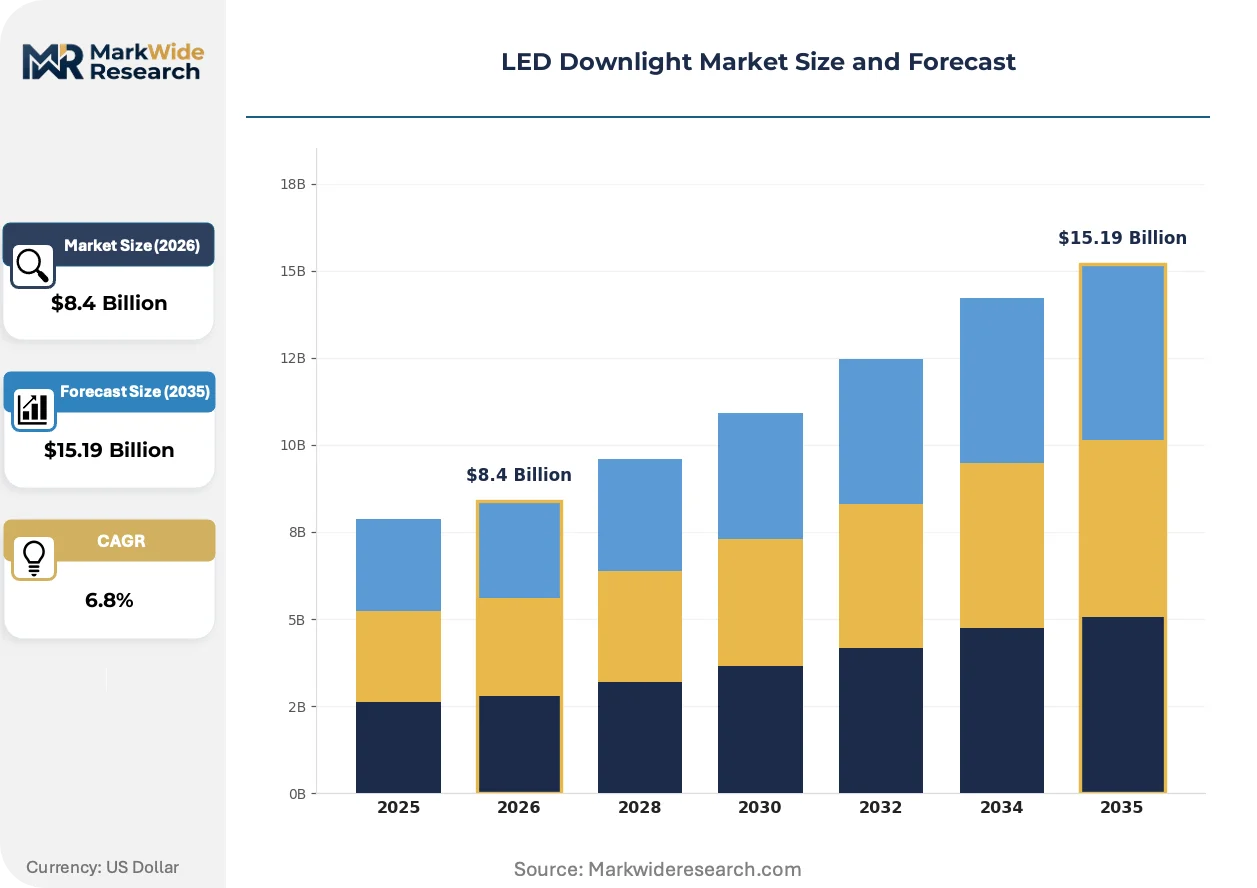
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recessed, Surface Mount, Adjustable, Pendant Use Case: Residential, Commercial, Industrial, Retail Installation Type: New Construction, Retrofit, Integrated, Plug-and-Play Technology: Smart Lighting, Dimmable, RGB, Tunable White |
| Companies Covered | Eaton Corporation plc, General Electric Company, Signify Holding, Philips Lighting, Forest Lighting, Acuity Brands Inc, Osram Licht AG, DMF Lighting, Cree Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Downlight Market Strategic Shifts & Innovations
Chip-scale packaging and intelligent control convergence are compressing the traditional separation between luminaire hardware and building management software, redefining competitive advantage around thermal-photonic integration rather than assembly efficiency alone.
Tunable-white LED engines with discrete warm and cool channel arrays are displacing fixed-CCT downlights in hospitality and healthcare specifications. Hotel operators in Germany and the United States specify circadian-rhythm-aligned installations for guest wellness positioning. The technology is displacing conventional dimming-centric retrofits by bundling spectral control with occupancy sensing.
The EU F-Gas Regulation phase-down is accelerating adoption of fluorinated-gas-free thermal interface materials in luminaire manufacturing. ECHA restrictions on high-global-warming-potential substances force reformulation of die-cast aluminum heat sink bonding processes. German and Italian manufacturers are responding fastest, with domestic supply chains already qualified for alternative thermal greases and phase-change materials.
Building owners are consolidating specification authority around master systems integrators rather than traditional electrical distributors. The shift concentrates procurement leverage with contractors capable of commissioning DALI-2 and BACnet interoperability. This consolidation is most visible in United States Class A office developments, where design-build contracts bundle luminaire supply with controls integration and ongoing performance guarantees.
LED Downlight Market Segmentation
Downlight procurement channels fragment sharply across specification tiers. Electrical distributors dominate volume in residential retrofit, while master systems integrators capture premium commercial specifications bundled with controls commissioning.
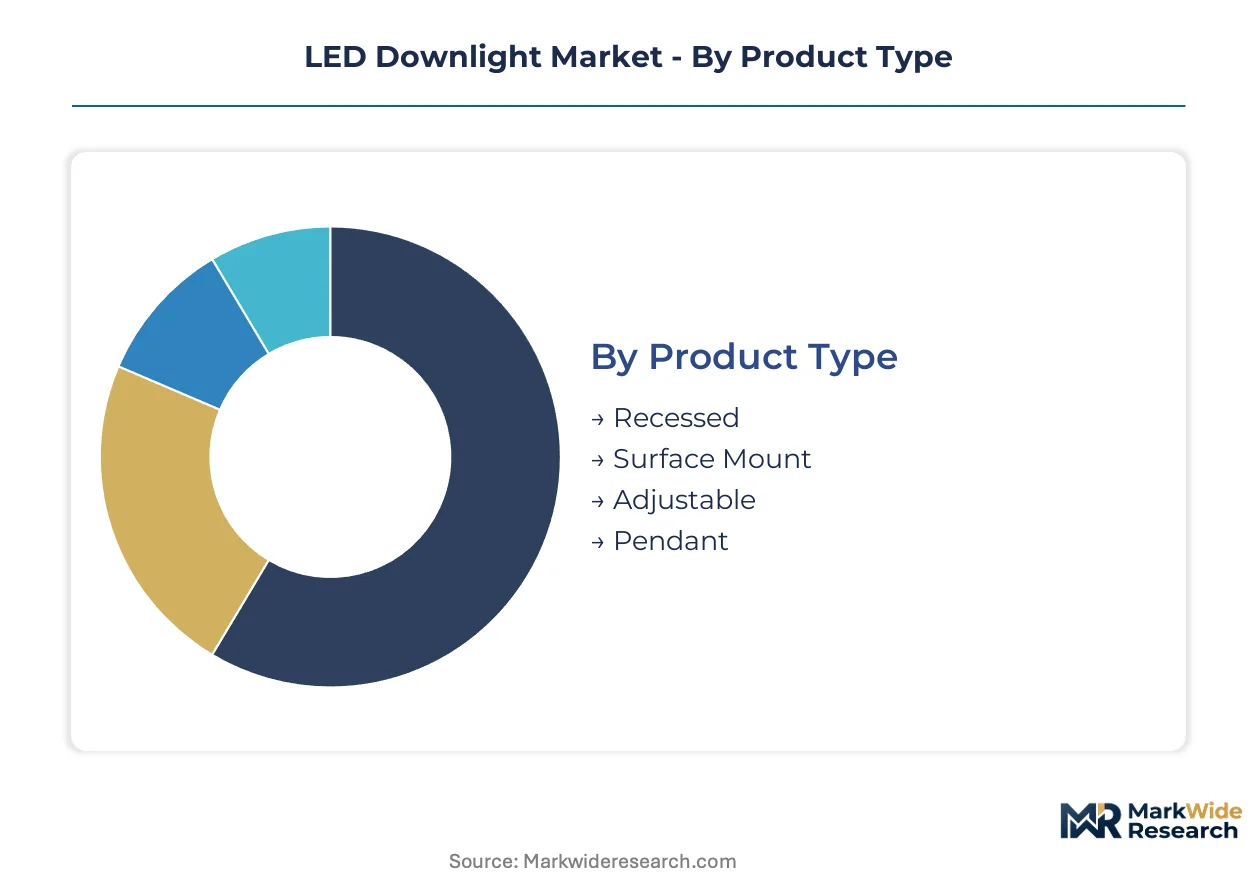
Product Type:
Recessed housings flow through specification-grade distributors in commercial new construction, while surface-mount variants concentrate in big-box retail for residential renovation.
- Recessed:Die-cast aluminum housings with trim-ring compatibility dominate commercial office specifications. Demand concentrates in Germany and United States Class A developments where DALI-2 commissioning requirements favor integrated housings over componentized retrofits.
- Surface Mount:Low-profile junction-box-mounted luminaires eliminate ceiling aperture requirements. Residential renovation in price-sensitive United States metropolitan markets drives volume where plaster ceiling reconstruction costs deter recessed conversion.
- Adjustable:Gimbal mechanisms enable directional accent lighting in museum and gallery specifications.
- Pendant:Suspended downlight modules serve high-bay commercial and hospitality atrium applications.
Recessed dominates installed base. Surface Mount is where expansion concentrates.
Use Case:
Cost tier stratification separates specification-grade commercial procurement from retail residential volume, with margin concentration in healthcare and hospitality verticals.
- Commercial:Office, hospitality, and healthcare specifications demand tunable-white engines with BACnet interoperability. Germany's building energy code enforcement and United States Title 24 compliance create dual certification requirements that filter supplier pools.
- Residential:Single-family and multi-family renovation drives plug-and-play retrofit volume through home improvement retailers. China's GB standards enforcement limits import channel access, concentrating domestic manufacturer share.
- Industrial:High-bay warehouse specifications prioritize efficacy thresholds and motion-sensing integration.
- Retail:Merchandise accent lighting with high color-rendering index requirements shapes fixture selection.
Commercial commands margin concentration. Residential delivers volume scale.
Installation Type:
Volume distribution skews toward retrofit in mature building stock markets, while new construction pipelines concentrate specification authority with design-build contractors.
- New Construction:Integrated architectural specification occurs during design development phase. United States design-build contracts bundle luminaire supply with performance guarantees, locking out distributor-only suppliers.
- Retrofit:LED engine replacement within existing housings avoids ceiling reconstruction. Germany's KfW subsidized financing programs accelerate commercial building owner payback calculations.
- Integrated:Luminaire-and-control factory-paired systems reduce field commissioning complexity.
- Plug-and-Play:Magnetic or twist-lock LED modules enable electrician-installed upgrades without housing replacement.
Retrofit dominates current shipment volume. New Construction is where specification authority consolidates.
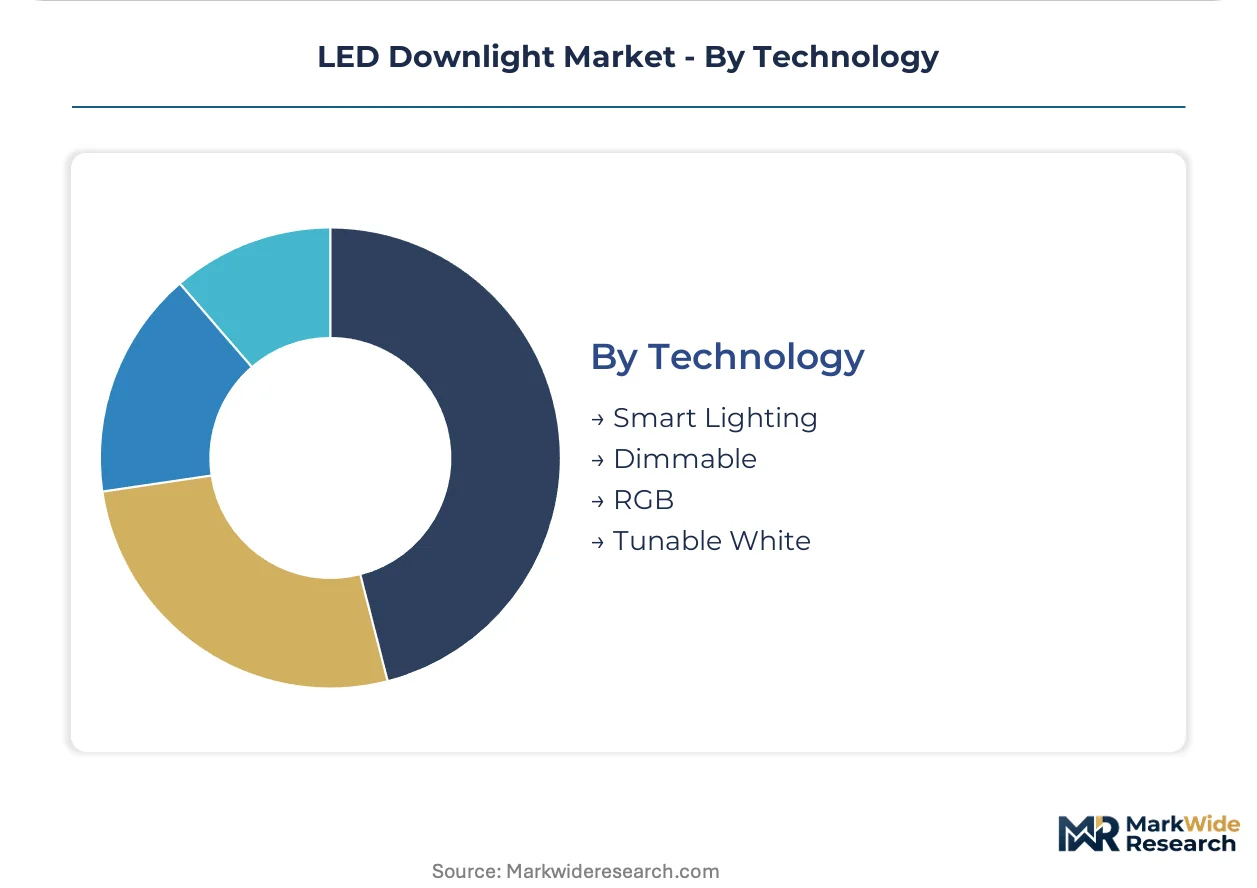
Technology:
Smart feature penetration stratifies pricing tiers, with protocol interoperability becoming a baseline qualifier rather than premium differentiator in commercial channels.
- Smart Lighting:Wi-Fi, Zigbee, or proprietary mesh connectivity enables app-based control and energy analytics. United States Class A office developers specify BACnet and DALI-2 interoperability as mandatory, not optional.
- Tunable White:Discrete warm and cool LED channels enable circadian-rhythm-aligned spectral control. Hospitality operators in Germany specify guest wellness positioning, displacing conventional dimming-centric specifications.
- Dimmable:Forward-phase and reverse-phase driver compatibility remains a field failure liability in renovation projects.
- RGB:Color-mixing engines serve entertainment and architectural accent applications with limited commercial volume.
Dimmable holds installed base dominance. Tunable White is gaining share fastest in specification-grade channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where KfW-subsidized retrofits compress payback periods, while Chinese manufacturers compete on volume through GB standards-compliant domestic channels. The United States enforces dual EPA ENERGY STAR and California Title 24 certification requirements that filter supplier pools. India's building energy code expansion creates first-mover positioning in underpenetrated metropolitan markets.
Germany
Commercial building owners accelerate LED transition through KfW development bank financing programs that subsidize retrofit capital expenditure. The EU Ecodesign Directive 2019/2020 mandates phased lumen maintenance standards that force portfolio upgrades in office and hospitality sectors. Industrial clusters in Bavaria and North Rhine-Westphalia host specification-grade distributors bundling luminaire supply with DALI-2 commissioning services.
United States
Class A office developers specify BACnet interoperability as mandatory baseline for master systems integrator procurement. EPA ENERGY STAR certification and California Title 24 building standards impose minimum efficacy and controllability thresholds that extend product launch timelines. Design-build contracts in Texas and New York Metro bundle performance guarantees with luminaire supply, locking out distributor-only suppliers.
China
SAMR enforcement of GB standards compels foreign manufacturers to establish local testing partnerships for domestic market access. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate die-cast aluminum heat sink production and wafer-level LED packaging capacity. The country's dual carbon goals accelerate building energy code adoption in commercial construction pipelines.
India
BIS efficacy standard enforcement in commercial construction creates specification entry points for ENERGY STAR-equivalent certified product lines. Maharashtra and Gujarat industrial corridors concentrate electrical distribution networks serving metropolitan retrofit demand. Delhi-NCR hospitality operators specify tunable-white installations for guest wellness positioning.
United Kingdom
Commercial retrofit volume concentrates in London and Southeast England where aging halogen housing stocks extend substitution timelines. Ecodesign Directive alignment through post-Brexit product safety regulations maintains standby power limits and lumen maintenance requirements. Midlands manufacturing clusters supply specification-grade recessed housings for hospitality and healthcare verticals.
LED Downlight Market Key Industry Players
Concentration sits with integrated chip-scale packaging specialists who control phosphor deposition and thermal management costs in-house. Assembly-only contractors face margin compression from wafer-level LED economics favoring captive semiconductor capacity. Three archetypes dominate: captive semiconductor manufacturers with substrate expertise, specification-grade architectural lighting specialists, and volume-scale residential retrofit suppliers. Competitive moves center on M&A for controls integration capability and capacity expansion in tunable-white engine production.
Within the captive semiconductor tier, Signify Holding and Cree Lighting occupy positions defined by substrate-level thermal management control. Signify Holding exemplifies integrated manufacturing advantage through in-house phosphor deposition capacity. Cree Lighting represents silicon-carbide substrate specialization extending efficacy thresholds beyond conventional architectures. Acuity Brands Inc anchors the specification-grade vector through architectural relationship depth and tunable-white R&D positioning.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| General Electric Company |
| Signify Holding |
| Philips Lighting |
| Forest Lighting |
| Acuity Brands Inc |
| Osram Licht AG |
| DMF Lighting |
| Cree Lighting |
| Others |
Cost & Logistics Intelligence
Wafer-level LED packaging scale economies compress unit economics for integrated manufacturers while squeezing assembly-only contractors into price-taker positions across mid-tier commercial segments. Die-cast aluminum input volatility and phosphor deposition capacity constraints concentrate margin control with captive semiconductor producers in Germany and China.
Pricing Analysis
Configured-to-order tunable-white specifications command 40-60% premiums over standard fixed-CCT product lines in Class A office and hospitality verticals. Pricing stratifies across premium specification-grade, standard commercial, and economy residential tiers, with differentiation driven by DALI-2 certification level and thermal management material grade. Cost compression in the economy tier intensifies as Chinese GB standards-compliant manufacturers expand volume through domestic retail channels. Residential retrofit buyers exhibit highest price sensitivity, while master systems integrators in German commercial projects prioritize performance guarantees over unit cost.
Supply Chain Analysis
Yangtze River Delta port congestion and Panama Canal transit constraints periodically disrupt die-cast aluminum heat sink delivery schedules to European assembly plants. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning aluminum ingot, sapphire and silicon-carbide substrates, and rare-earth phosphor compounds. Single-source vulnerability sits with Taiwanese wafer-level packaging capacity for high-efficacy chip-scale LEDs. Distribution runs through specification-grade electrical distributors in commercial new construction and big-box retail for residential renovation volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED downlight market constitutes a high-growth disruption as EU Ecodesign Directive efficacy mandates and silicon-carbide substrate advances simultaneously obsolete legacy fluorescent housing stocks and sapphire-based LED architectures.
For Market Incumbents: Secure captive phosphor deposition capacity through backward integration into wafer-level packaging or long-term supply agreements with Yangtze River Delta specialists. Expand tunable-white R&D pipelines to defend specification-grade positioning against emerging silicon-carbide substrate competitors. Lock master systems integrator relationships through bundled DALI-2 commissioning services in German and United States Class A office developments.
For New Entrants and Emerging Players: Anchor in India's underpenetrated metropolitan commercial construction pipeline where BIS efficacy enforcement creates first-mover certification advantages for ENERGY STAR-equivalent product lines. Target Delhi-NCR and Maharashtra hospitality operators specifying circadian-rhythm-aligned installations with limited incumbent specification presence. Pursue utility-sponsored retrofit financing partnerships to reduce upfront capital barriers for building owners.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated chip-scale packaging specialists with in-house thermal management capabilities over assembly-only contractors facing margin compression. Long-term viability rests on substrate-level innovation pipelines and controls integration competency rather than luminaire hardware scale alone. Monitor F-Gas Regulation phase-down compliance timelines as inflection indicator for manufacturing process requalification costs and competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer-Level Packaging | Captive phosphor deposition capacity insulates margins from assembly-only contractor compression in China. |
| Tunable-White Engine Capacity Expansion | Circadian-rhythm-aligned specifications displace fixed-CCT retrofits in German hospitality wellness positioning. |
| DALI-2 and BACnet Certification Investment | Protocol interoperability unlocks master systems integrator procurement in United States Class A offices. |
| Utility-Sponsored Financing Partnerships | KfW-style subsidized retrofit programs accelerate building owner payback calculations in underpenetrated markets. |
| F-Gas-Compliant Thermal Material Qualification | ECHA-aligned alternative thermal greases secure continued EU market access as fluorinated gas restrictions tighten. |
Research Approach
The analysis maps recessed, surface-mount, and tunable-white product architectures, each validated through specification-grade distributor interviews, master systems integrator procurement directors, die-cast aluminum heat sink suppliers, and phosphor deposition process engineers. Primary fieldwork combined with secondary validation from EPA ENERGY STAR certification databases, EU Ecodesign Directive regulatory filings, SAMR GB standards documentation, and SEC 10-K disclosures from listed lighting manufacturers. Bottom-up shipment volume triangulation against top-down construction spend allocation ensures segmentation consistency.
Consistency checks against external benchmarks validated projection outputs against historical efficacy improvement curves and regulatory phase-in timelines. The analytical framework models product type, installation mode, technology tier, and end-use vertical dimensions across the projection horizon. CAGRs derive from segmented adoption curve analysis incorporating building energy code enforcement schedules and utility program expansion trajectories. Forecast inputs include KfW subsidy allocation trends and Title 24 compliance cost pass-through estimates.
Material uncertainties — aluminum price volatility, F-Gas Regulation acceleration, and phosphor deposition talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory phase-in adherence and construction pipeline continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Lighting Solution Market
LED
Architectural LED Products Market
LED
LED Phosphor Materials Market
LED
Microled Market
LED
Asia Pacific LED Lighting Market
LED
China Outdoor LED Lighting Market
LED
LED Light Bar Market
LED
France Indoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Tube Drivers Market
LED
Infrared (IR) LED Market
LED
Mini LED Display Market
LED
LED Driver Market
LED
India LED Outdoor Lighting Market
LED
LED Light Market
LED
LED Services Market