
 India LED Outdoor Lighting Market | 2026-2036
India LED Outdoor Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India LED Outdoor Lighting Market Insights
BEE's mandatory star-labeling program for LED luminaires is realigning the cost-of-entry calculus for manufacturers seeking government tenders. Syska LED Lights leverages its extensive distribution network across Tier-2 and Tier-3 cities to sustain volume leadership in street lighting projects. Crompton Greaves Consumer Electricals anchors its position through backward integration into driver electronics, while Philips Lighting India (Signify) competes on optical engineering expertise for highway and tunnel applications.
India LED Outdoor Lighting comprises solid-state luminaires engineered with aluminum die-cast housings, IP65+ ingress protection, and correlated color temperatures ranging from 3000K to 6500K for roadway, facade, and landscape illumination. Street Lights dominate procurement volumes as municipal corporations account for the bulk of public tenders, while Smart Lighting commands premium positioning through remote monitoring and adaptive dimming capabilities that reduce energy draw during off-peak hours. Solar Lighting segments are gaining traction in rural and peri-urban zones where grid reliability remains inconsistent, though upfront capital costs limit penetration relative to conventional AC-powered systems.
BIS enforces photometric and safety standards through IS 16102 and IS 10322 series certifications that gate market access for domestic and imported products alike. The Ministry of Housing and Urban Affairs channels funding through AMRUT and Smart Cities Mission frameworks that mandate LED specifications in project guidelines, while state electricity distribution companies administer demand-side management programs with utility-linked financing for bulk replacements. Stakeholders must monitor evolving procurement norms around domestic value addition and component localization thresholds that determine eligibility for government contracts.
Market Dynamics
State-level smart city mandates are compressing procurement cycles as urban local bodies accelerate LED street lighting replacements under centrally sponsored schemes. Municipal corporations now bundle adaptive controls with luminaire tenders, forcing vendors to reconfigure product architectures around remote monitoring capabilities.
Growth Catalysts
- AMRUT Mission Funding:The Ministry of Housing and Urban Affairs channels capital into municipal LED retrofits, mandating energy-efficient specifications in project guidelines that lock in demand for certified suppliers.
- Utility-Linked Financing:State electricity distribution companies administer demand-side management programs offering bulk replacement schemes with deferred payment structures for urban local bodies.
- LiDAR-Based Adaptive Dimming:Traffic-responsive illumination systems reduce off-peak energy draw by 30-40 percent, creating measurable opex savings that justify premium procurement.
Market Restraints
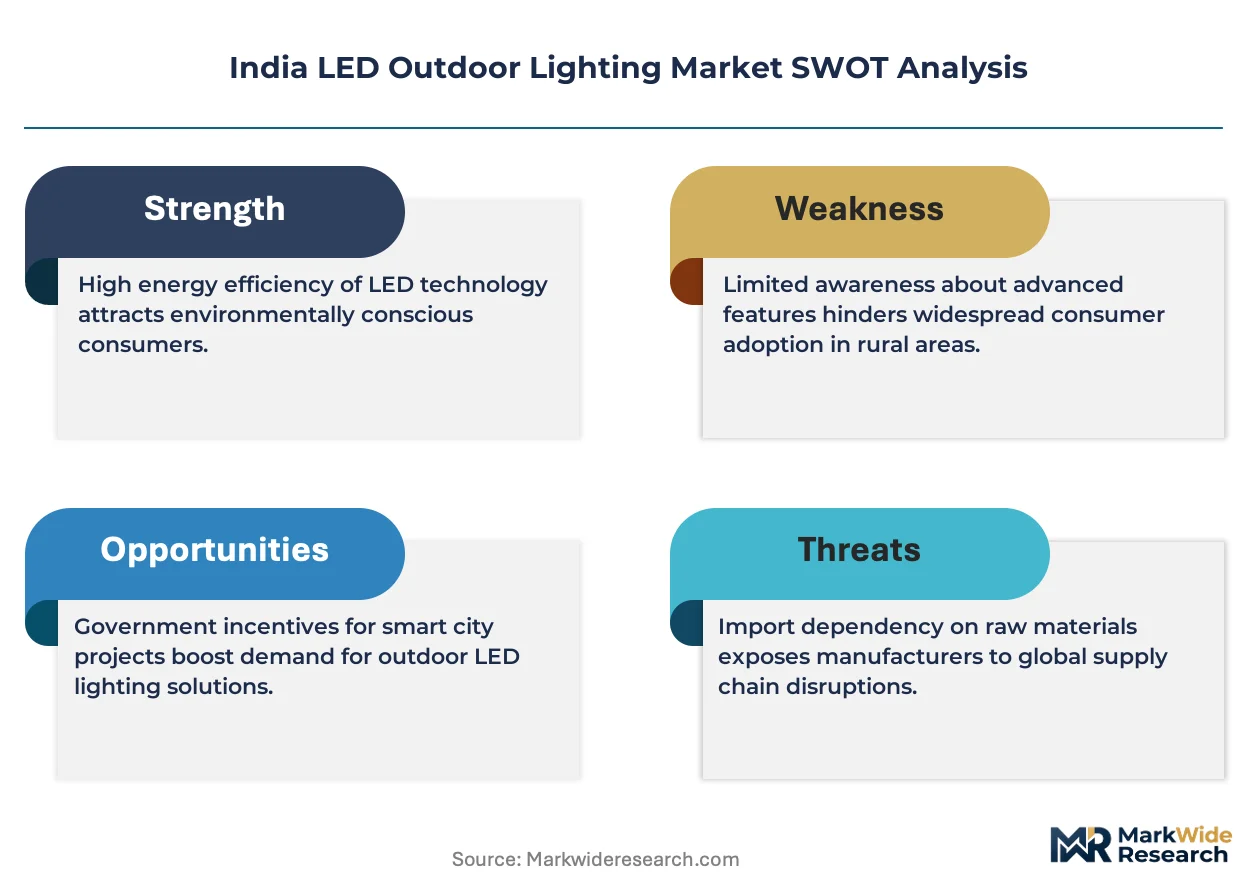
- Driver IC Import Dependence:Domestic manufacturers source 70-80 percent of LED driver electronics from East Asian foundries, exposing margins to currency volatility and shipping disruptions.
- Aluminum Die-Cast Cost Volatility:Housing material costs fluctuate with London Metal Exchange pricing, compressing gross margins for mid-tier luminaire assemblers.
- Grid Reliability in Peri-Urban Zones:Solar-hybrid systems face 18-24 month payback periods where grid downtime falls below threshold levels, limiting addressable market expansion.
Strategic Opportunities
- Tamil Nadu Industrial Corridors:Manufacturing clusters along Chennai-Salem and Coimbatore-Erode highways present concentrated demand for tunnel and high-mast lighting with 10-year maintenance contracts.
- PLI Scheme Localization:Production-linked incentives for LED component manufacturing are attracting driver electronics and chip-on-board module investments that reduce import exposure.
- IoT Platform Convergence:Integration of luminaire networks with city command centers creates recurring software revenue streams beyond hardware sales.
Industry Challenges
- BIS Certification Timelines:IS 16102 and IS 10322 testing protocols require 8-12 weeks for photometric validation, delaying tender participation for new market entrants.
- Legacy Sodium Vapor Infrastructure:Municipalities face integration complexity when retrofitting smart controls onto existing pole architectures without full cable replacement.
- Optical Design Talent Scarcity:Shortage of thermal management and lens engineering specialists constrains product development velocity for domestic firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India LED Outdoor Lighting Market |
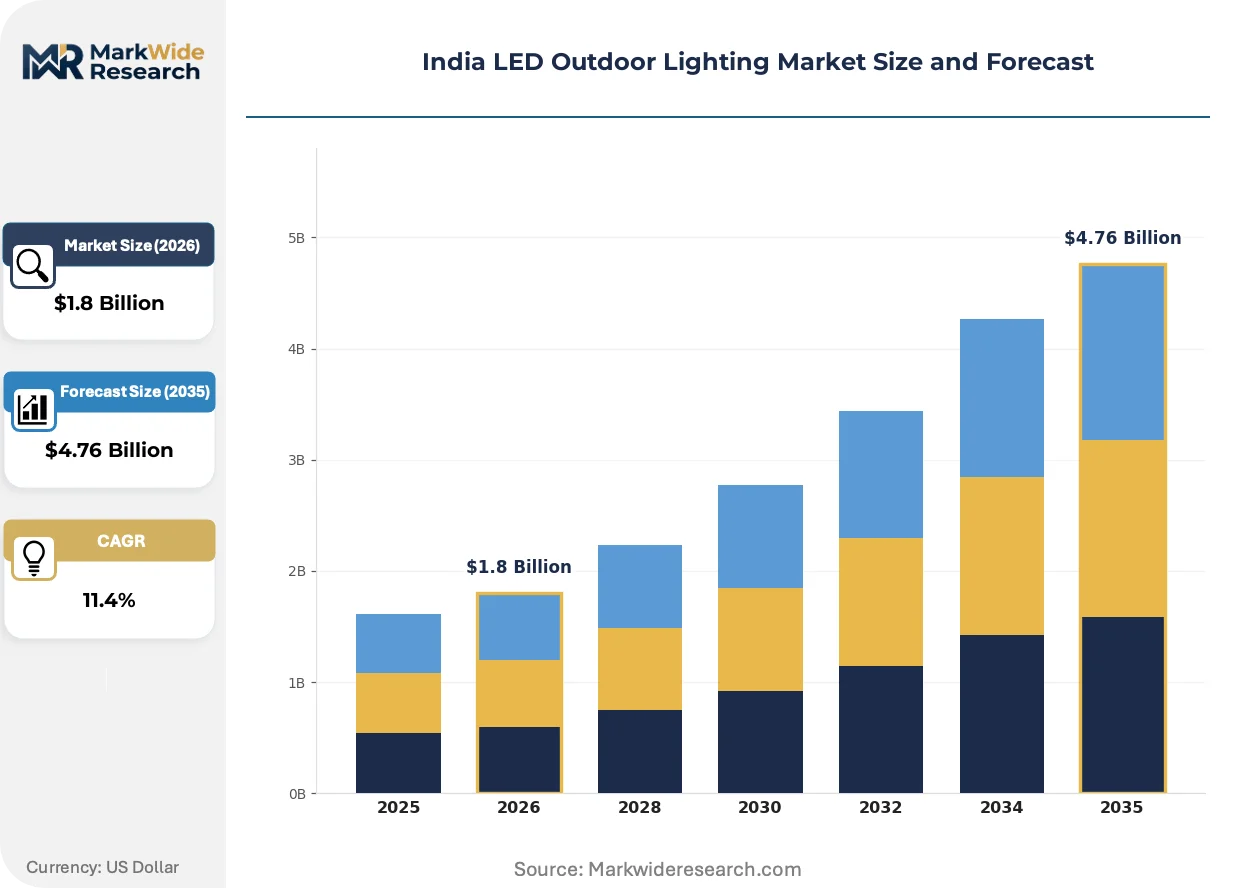
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flood Lights, Street Lights, Garden Lights, Wall Lights Technology: Smart Lighting, Solar Lighting, Conventional Lighting, Motion Sensor Application: Residential, Commercial, Industrial, Public Spaces End User: Government, Enterprises, Homeowners, Contractors |
| Companies Covered | Syska LED Lights, Crompton Greaves Consumer Electricals, Philips Lighting India (Signify), Surya Roshni, Osram Lighting Solutions India, Havells India, Bajaj Electricals, Tata Power Solar Systems, Wipro Lighting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India LED Outdoor Lighting Market Trends and Innovations
Photonic engineering advances are converging with networked control architectures to redefine performance benchmarks across roadway, facade, and landscape applications. Three developments are restructuring competitive requirements.
Chip-on-board LED arrays are absorbing thermal management functions previously handled by discrete heat sinks, enabling slimmer luminaire profiles without lumen depreciation. Municipal corporations in Gujarat and Maharashtra are specifying these modules for coastal installations where salt corrosion accelerates housing degradation. The technology is absorbing market share from conventional SMD packages in high-wattage street lighting segments.
Bureau of Energy Efficiency star-labeling mandates are tightening photometric efficiency thresholds for luminaires seeking government tender eligibility. The regulation is disqualifying Tier-3 assemblers lacking testing laboratory partnerships while rewarding manufacturers with in-house integrating sphere facilities. Highway and tunnel lighting categories face the steepest compliance curves under revised norms.
Municipal procurement officers are consolidating vendor relationships around 10-year comprehensive maintenance contracts that bundle hardware, remote monitoring, and failure replacement. The model is displacing transactional luminaire-only purchasing in Smart Cities Mission projects. Maharashtra Urban Development Department tenders now require demonstrated service network presence across at least three state districts as qualification criteria.
India LED Outdoor Lighting Market Segmentation
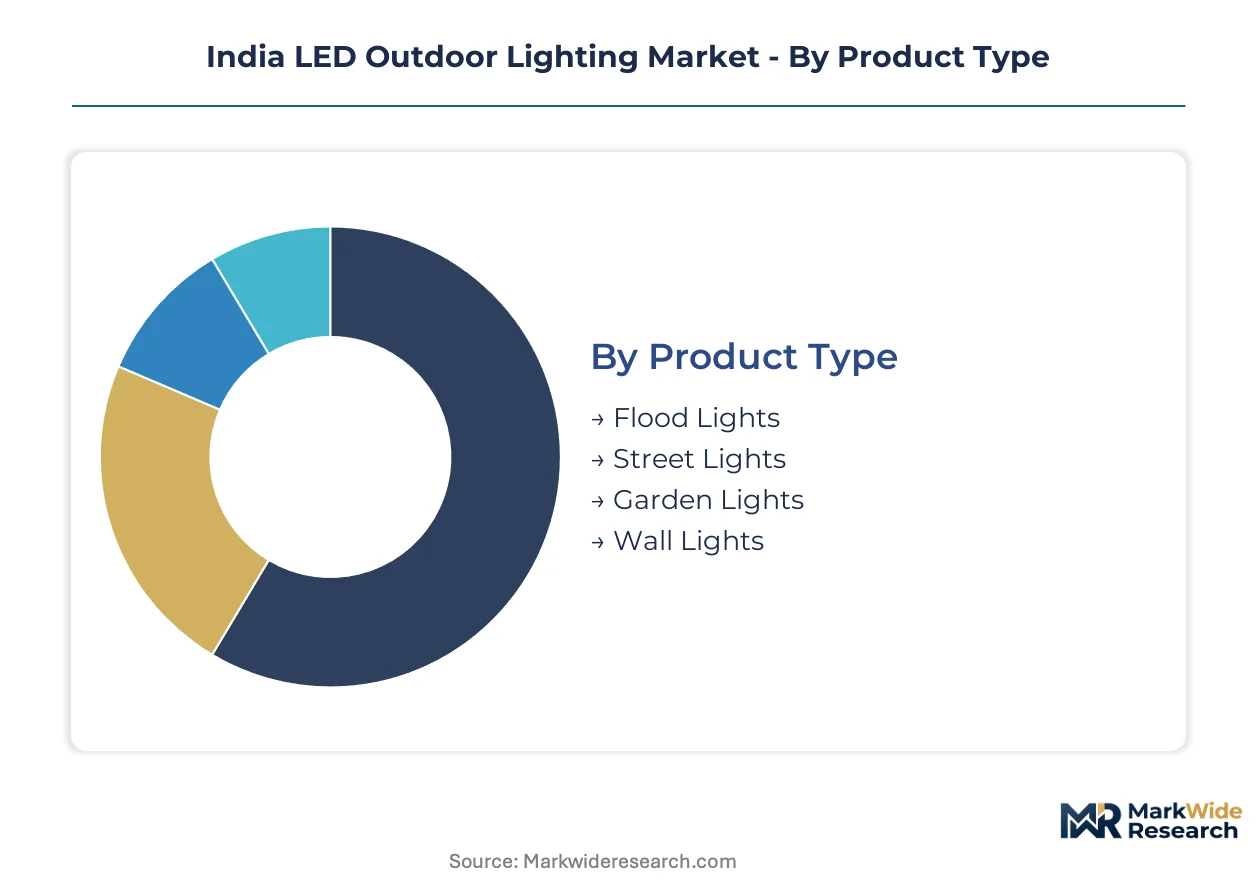
India LED Outdoor Lighting Market segmentation reveals how procurement concentration shapes competitive positioning across product architectures and customer channels. Understanding these divides illuminates where certification requirements and financing structures create divergent margin profiles.
Product Type:
Supply concentration for aluminum die-cast housings and driver electronics clusters around luminaire categories with standardized specifications and volume tender potential.
- Street Lights:High-wattage COB arrays mounted on aluminum die-cast housings with IP65+ ingress protection dominate municipal procurement. Maharashtra, Gujarat, and Tamil Nadu urban local bodies account for concentrated demand as AMRUT Mission funding accelerates conventional sodium vapor replacements.
- Flood Lights:Asymmetric beam distribution optics engineered for sports complexes and industrial yards command premium positioning through photometric precision. Demand clusters in Tamil Nadu industrial corridors where manufacturing facilities specify 10-year maintenance contracts.
- Garden Lights:Low-wattage decorative luminaires with 3000K-4000K CCT specifications serve landscape architects and residential developers.
- Wall Lights:Compact facade-mounted units with upward-downward light distribution address commercial building retrofits and new construction.
Street Lights absorb the bulk of installed capacity; Garden Lights are expanding most quickly as peri-urban residential developments proliferate.
Technology:
Cost tier differentiation separates premium networked systems from commodity AC-powered alternatives, with financing availability determining addressable market depth.
- Smart Lighting:Remote monitoring platforms with adaptive dimming capabilities reduce off-peak energy draw through LiDAR-based traffic response. Municipal corporations bundle these controls with luminaire tenders, forcing vendor reconfiguration around IoT architectures.
- Conventional Lighting:AC-powered static output luminaires without networked controls dominate legacy retrofit projects where capital constraints limit technology upgrade scope.
- Solar Lighting:PV-integrated systems with battery backup address grid reliability gaps in rural and peri-urban zones, though 18-24 month payback periods constrain penetration.
- Motion Sensor:PIR-activated luminaires for security and pathway applications serve residential and light commercial installations with intermittent illumination requirements.
Conventional Lighting retains the largest installed base; Smart Lighting is climbing the fastest as Smart Cities Mission mandates compress procurement cycles.
Application:
Volume concentration tracks government funding flows, with public infrastructure commanding procurement scale that private segments cannot replicate.
- Public Spaces:Roadway, tunnel, and plaza illumination governed by BIS IS 16102 standards and Bureau of Energy Efficiency star-labeling mandates. Ministry of Housing and Urban Affairs specifications lock in demand for certified suppliers across AMRUT and Smart Cities frameworks.
- Commercial:Retail facade, parking structure, and hospitality exterior lighting where optical engineering and brand aesthetics drive specification.
- Industrial:High-bay and perimeter security lighting for manufacturing facilities with 24-hour operational requirements.
- Residential:Single-family and multi-unit dwelling exterior illumination with limited project scale and price-sensitive procurement.
Public Spaces command the dominant share of annual installations; Commercial applications are gaining share fastest as private development activity accelerates.
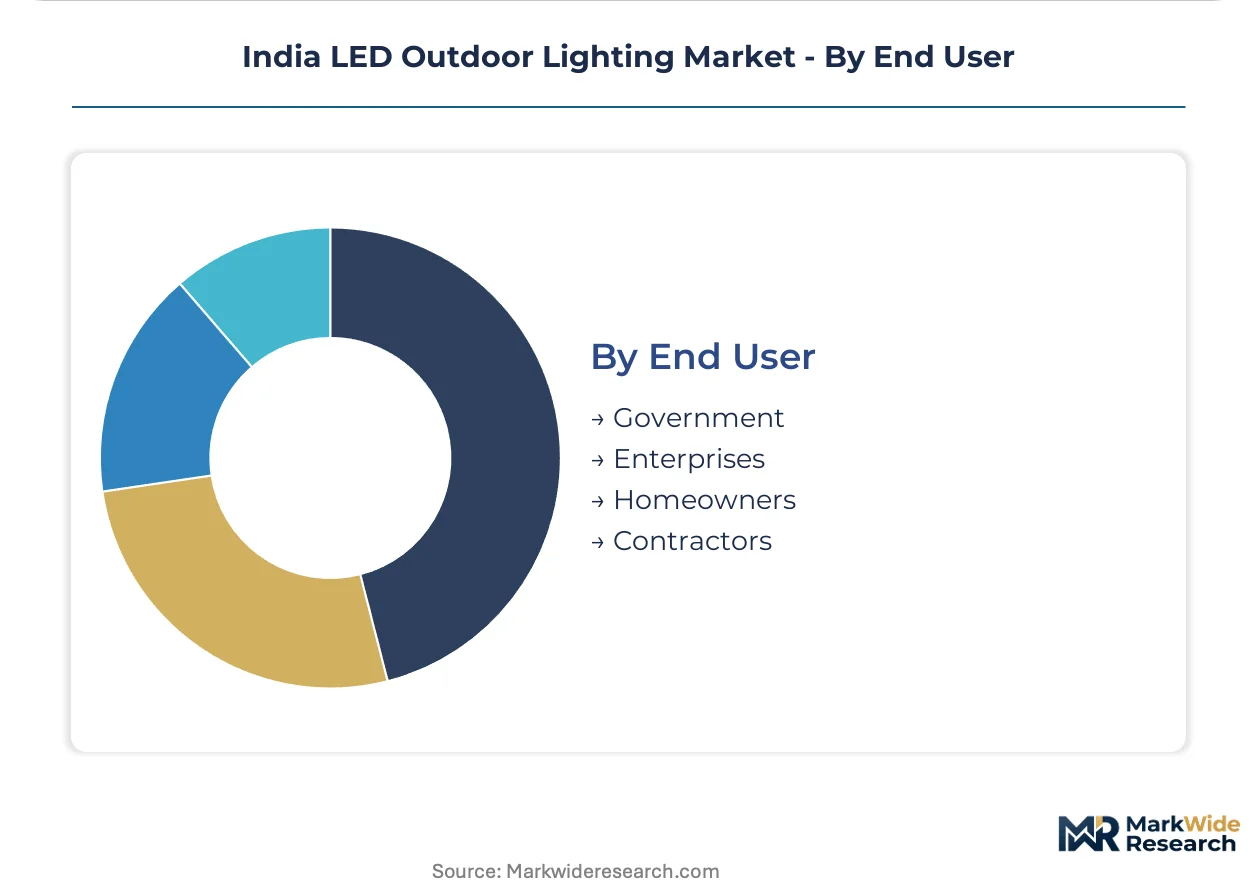
End User:
Customer type determines contracting structure, with government tenders requiring demonstrated service networks and extended warranty commitments that exclude smaller competitors.
- Government:Municipal corporations, urban development authorities, and state public works departments procuring through centralized tender processes. Maharashtra Urban Development Department now requires vendor presence across at least three state districts as qualification criteria.
- Contractors:EPC firms executing infrastructure projects with lump-sum turnkey contracts and penalty clauses for commissioning delays.
- Enterprises:Corporate facility managers and industrial plant operators with direct procurement authority for campus lighting.
- Homeowners:Individual consumers purchasing through electrical retail channels with minimal specification complexity.
Government end users absorb the dominant procurement volume; Contractors are expanding their share fastest as project bundling concentrates purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate LED luminaire manufacturing capacity through state-sponsored tax incentives and infrastructure subsidies. These coastal corridors anchor procurement volume for municipal street lighting retrofits under centrally sponsored missions.
Maharashtra
Mumbai Metropolitan Region and Pune Municipal Corporation drive concentrated demand through AMRUT Mission-funded street lighting replacements. The state urban development department mandates BIS IS 16102 certification for all tender participants. Manufacturing clusters in Nashik and Aurangabad supply aluminum die-cast housings to Tier-1 luminaire assemblers.
Gujarat
Surat and Ahmedabad municipal corporations accelerate smart lighting procurement with bundled adaptive control specifications. The state electricity distribution company administers utility-linked financing schemes for bulk LED replacements. GIFT City and Mundra SEZ host component manufacturing facilities serving western India demand.
Tamil Nadu
Chennai-Salem and Coimbatore-Erode industrial corridors generate sustained demand for tunnel and high-mast lighting with extended maintenance contracts. Tamil Nadu Urban Infrastructure Financial Services channels state development funds into municipal LED retrofits. Hosur and Sriperumbudur electronics manufacturing clusters produce driver electronics for domestic luminaire brands.
Karnataka
Bengaluru Smart City Limited mandates networked lighting controls in all new roadway illumination tenders. Karnataka Renewable Energy Development Agency subsidizes solar-hybrid street lighting for peri-urban gram panchayats. Peenya industrial estate houses metal fabrication units supplying housing components to southern India markets.
Telangana
Hyderabad Metropolitan Development Authority specifies LiDAR-based adaptive dimming in highway lighting tenders. Telangana State Renewable Energy Corporation finances standalone solar LED installations for unelectrified rural roads. Genome Valley and Pocharam electronics clusters attract driver IC assembly investments under PLI scheme incentives.
India LED Outdoor Lighting Market Competitive Landscape
Western India producers anchor volume manufacturing through Maharashtra and Gujarat manufacturing bases; southern India specialists hold optical engineering and electronics integration capabilities. The market structures around three tiers: integrated conglomerates with captive component supply, mid-scale assemblers sourcing from distributed vendor networks, and regional fabricators serving single-state procurement. Competitive moves center on backward integration into driver electronics and ten-year comprehensive maintenance contract offerings that displace transactional luminaire sales.
Within the integrated conglomerate tier, Syska LED Lights and Crompton Greaves Consumer Electricals exemplify divergent strategic positions. Syska leverages extensive distribution infrastructure across Tier-2 and Tier-3 urban centers to sustain volume leadership in government tender participation. Crompton Greaves occupies a position anchored by captive production of driver electronics that reduces import exposure and compresses bill-of-material costs. Philips Lighting India (Signify) represents the multinational archetype competing on optical engineering specialization for highway, tunnel, and high-mast applications where photometric precision commands premium positioning.
| Leading Market Players |
|---|
| Syska LED Lights |
| Crompton Greaves Consumer Electricals |
| Philips Lighting India (Signify) |
| Surya Roshni |
| Osram Lighting Solutions India |
| Havells India |
| Bajaj Electricals |
| Tata Power Solar Systems |
| Wipro Lighting |
| Others |
Pricing and Supply Chain Analysis
Municipal ten-year comprehensive maintenance contract mandates from Maharashtra Urban Development Department are compressing vendor margins and forcing supply chain reconfiguration toward localized service networks and captive component production.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to BIS-certified luminaires needed within four-week tender windows, while spot inventory of non-certified units trades at discounts. Three-tier pricing structure across premium smart lighting, standard AC-powered systems, and economy solar-hybrid tiers tracks certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying as Tier-3 assemblers absorb aluminum die-cast price volatility to maintain municipal eligibility. Government tenders show lowest price sensitivity due to mandated quality floors; residential channels exhibit highest sensitivity with minimal specification enforcement.
Supply Chain Analysis
Dual-sourcing requirements in Tamil Nadu and Gujarat municipal tenders mandate qualified suppliers for both driver electronics and LED modules, fragmenting procurement across multiple vendor relationships. Manufacturing draws from China for driver ICs, Taiwan for chip-on-board substrates, and domestic Nashik-Aurangabad clusters for aluminum die-cast housings. Raw material dependencies span London Metal Exchange aluminum pricing, rare earth phosphors, and lithium-ion cells for solar-hybrid systems. Single-source vulnerability concentrates in East Asian foundry capacity for driver electronics. Distribution runs through state electricity distribution company financing programs, EPC contractor networks, and direct municipal tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around BIS certification compliance and ten-year service contract capabilities, with Bureau of Energy Efficiency star-labeling mandates eliminating Tier-3 assemblers lacking laboratory partnerships.
For Market Incumbents: Hedge against driver IC import exposure by accelerating backward integration into driver electronics production under PLI scheme incentives. Anchor market position through captive supply of chip-on-board modules and thermal management components. Defensive consolidation requires acquiring regional fabricators with established district-level service networks to meet Maharashtra's three-district presence mandates. For New Entrants and Emerging Players: BIS IS 16102 certification timelines in India open a window for specialized optical engineering consultancies to partner with domestic assemblers lacking in-house integrating sphere facilities. Target Tamil Nadu industrial corridor tunnel and high-mast lighting segments where 10-year maintenance contracts concentrate demand and technical barriers limit competition. Penetrate through LiDAR-based adaptive dimming system integration partnerships with smart city command center operators. For Investors and Strategic Acquirers: The window for entry favors mid-scale assemblers with captive aluminum die-cast housing production and demonstrated BIS laboratory relationships. Long-term viability rests on component localization thresholds tightening across AMRUT and Smart Cities Mission procurement guidelines. Watch for PLI scheme disbursement acceleration as the signal indicating driver electronics manufacturing investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | PLI scheme incentives reduce import exposure from East Asian foundries and compress bill-of-material costs for municipal tenders. |
| LiDAR-Based Adaptive Dimming Platform Development | Traffic-responsive illumination aligns with Smart Cities Mission remote monitoring mandates and commands 30-40 percent energy savings premiums. |
| In-House Integrating Sphere Investment | Bureau of Energy Efficiency star-labeling compliance requires photometric validation capabilities that disqualify Tier-3 competitors from government eligibility. |
| District-Level Service Network Expansion | Maharashtra Urban Development Department mandates presence across three state districts as tender qualification criteria. |
| Solar-Hybrid System Localization | Tamil Nadu and Karnataka rural financing programs address grid reliability gaps with 18-24 month payback structures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with municipal procurement officers, EPC contractor project managers, luminaire manufacturer R&D directors, and state electricity distribution company planning leads. ELCOMA industry statistics, BIS certification registries, Ministry of Housing and Urban Affairs AMRUT disbursement records, and Bureau of Energy Efficiency star-labeling databases provided demand-side validation. Bottom-up installed base estimates triangulated against top-down funding allocation projections.
Data-stream reconciliation across product type, technology architecture, application segment, and end-user channel dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume build-ups incorporating BIS certification adoption curves and Smart Cities Mission procurement cycle compression. Forecast inputs included aluminum London Metal Exchange price trajectories, PLI scheme incentive disbursement schedules, and state-level urban local body fiscal capacity assessments.
The model assumes a particular technology adoption path; alternative pathways for chip-on-board LED thermal management integration would alter the outlook if discrete heat sink architectures retain cost advantages. Forecasts reflect assumptions around BIS testing protocol timelines and municipal bundled control specification penetration. Deviation in East Asian foundry capacity utilization or currency volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Micro LED Display Market
LED
LED Flip Chip Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
LED High Bay Drivers Market
LED
Bi-Color LED Ring Light Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
LED Services Market
LED
North America Micro-LED Display Market
LED
Indonesia LED Market
LED
Thailand LED Market
LED
LED and OLED Display Market
LED
LED Light Bar Market
LED
Infrared (IR) LED Market
LED
LED Street Light Drivers Market
LED
Saudi Arabia LED Lights Market