
 Tile Backer Boards Market | 2026-2036
Tile Backer Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Backer Boards Market Insights
Premium-specification waterproofing tiers is rotating demand toward cement and foam-core backer boards with enhanced moisture-barrier ratings. James Hardie Industries leverages fiber-cement expertise to dominate commercial-grade wall-backing specifications in North America. Saint-Gobain sustains broad product breadth across glass-mat and cement-board categories through its CertainTeed distribution network. wedi GmbH specializes in extruded polystyrene foam boards for European wet-area applications where thermal insulation codes are tightening.
Tile backer boards are rigid substrate panels engineered from Portland cement, glass-fiber mesh, gypsum, or extruded polystyrene foam, typically manufactured in 1/4-inch to 1/2-inch thicknesses with density ratings between 1,200 and 1,800 kg/m³, serving as structural underlayments that prevent moisture penetration and tile delamination in wet environments. Cement board commands the largest volume share due to decades of contractor familiarity and fire-rated performance in commercial flooring underlayments, while foam board captures the fastest specification growth in European wet-area renovations where lightweight handling and integrated waterproofing membranes reduce installation labor. Glass mat board occupies a defensible margin pool in multifamily construction where mold-resistant paperless facing satisfies extended moisture-exposure warranties.
EPA lead-safe renovation rules and OSHA silica-exposure limits shape US manufacturing compliance costs for cement-based backer production, while EU REACH restrictions on formaldehyde emissions from resin binders push glass-mat and magnesium-oxide formulations toward low-VOC certification. China's GB standards for building waterproofing, enforced by SAMR market surveillance, restrict import access for uncertified substrate products. Stakeholders must monitor how evolving EPD requirements and embodied-carbon disclosures in the EU Green Deal reshape material selection criteria for public infrastructure tenders.
Market Dynamics
Water-efficiency mandates and embodied-carbon disclosure rules are compressing specification timelines for tile backer boards, forcing manufacturers to recertify products across multiple jurisdictions simultaneously while wet-area renovation demand accelerates substrate replacement cycles.
Growth Catalysts
- MEE water-efficiency mandates:China's Ministry of Ecology and Environment tightening standards for bathroom waterproofing drives cement-board upgrades in residential wet-room retrofits.
- Hospitality bathroom retrofits:European hotel renovation cycles are accelerating foam-core backer specifications where thermal insulation codes are tightening.
- Glass-mat technology:Mold-resistant paperless facing satisfies extended moisture-exposure warranties in multifamily construction, expanding addressable applications.
Market Restraints
- Silica-exposure compliance:OSHA limits on respirable crystalline silica raise manufacturing costs for Portland cement-based backer production in the United States.
- Formaldehyde binder restrictions:EU REACH regulations push glass-mat and magnesium-oxide formulations toward low-VOC certification, extending R&D timelines.
- Cement supply concentration:Clinker production gravity in select regions creates input cost volatility for fiber-cement board manufacturers.
Strategic Opportunities
- EPD-driven public tenders:EU Green Deal embodied-carbon disclosure requirements create first-mover advantage for manufacturers with verified environmental product declarations.
- Integrated membrane systems:Convergence of extruded polystyrene foam with factory-applied waterproofing layers reduces field labor for European wet-area contractors.
- SAMR certification pathways:China's State Administration for Market Regulation building waterproofing standards restrict import access, creating captive demand for compliant domestic production.
Industry Challenges
- Multi-jurisdiction certification lag:Simultaneous compliance with EPA moisture-resistance standards, EU REACH, and GB standards extends product launch timelines by 12-18 months.
- Skilled installer scarcity:Proper cement-board cutting and fastening techniques require training that outpaces contractor workforce development in renovation-heavy markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Backer Boards Market |
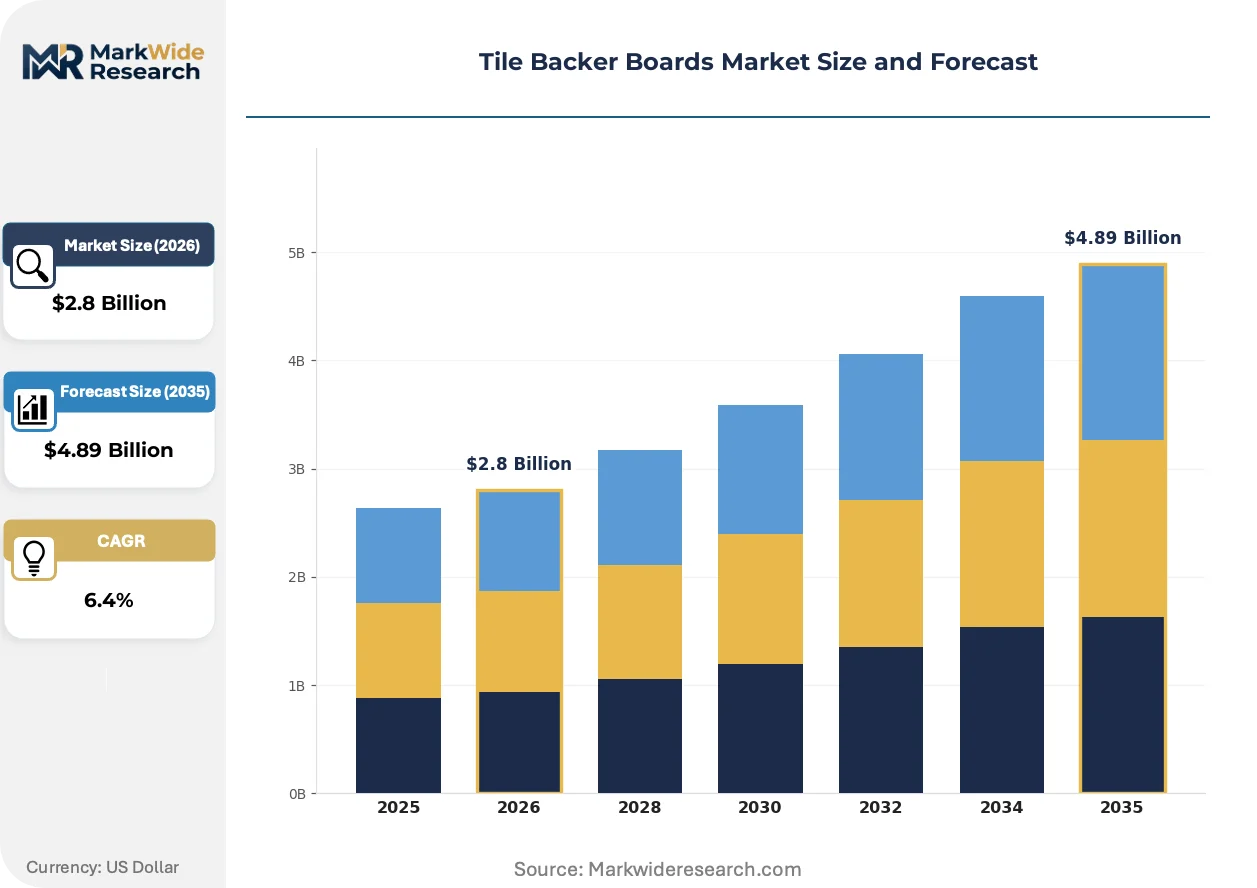
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Board, Foam Board, Fiber Cement Board, Glass Mat Board, Magnesium Oxide Board Application: Wet Areas, Flooring Underlayments, Wall Backing, Countertops, Fire Protection Boards End User: Construction Contractors, Interior Designers, Flooring Installers, Homeowners, Commercial Developers Sales Channel: Building Material Stores, Online Retailers, Specialty Dealers, Direct Sales, Wholesale Distributors |
| Companies Covered | James Hardie Industries, Georgia-Pacific Wood Products, Saint-Gobain (CertainTeed), USG Corporation, National Gypsum, Knauf, Johns Manville, wedi GmbH, Schluter Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Backer Boards Market Trends and Innovations
Material science advances and regulatory disclosure requirements are compressing traditional substrate categories, with lightweight engineered panels capturing specification share from legacy cement products through integrated performance bundling.
Extruded polystyrene foam boards with factory-laminated waterproofing membranes are miniaturizing installation steps for European wet-area contractors. Hospitality renovation teams in Germany and Austria specify these systems for steam shower enclosures where thermal bridging codes have tightened. The technology is compressing project timelines from substrate prep to tile-ready surfaces, displacing multi-layer cement-board assemblies in premium residential bathrooms.
REACH restrictions on formaldehyde emissions from resin binders are forcing glass-mat board manufacturers toward bio-based adhesive formulations. Industrial consequence includes extended curing processes and higher scrap rates during production ramp-up. Multifamily developers in France and the Netherlands face the tightest compliance windows, with projects specifying low-VOC certified substrates to meet extended mold-resistance warranties.
Certification-driven procurement now dominates public infrastructure tendering across EU member states, with environmental product declarations weighted alongside unit pricing. General contractors are consolidating supplier relationships to reduce documentation burden, favoring manufacturers with multi-standard pre-certification. Germany's federal building procurement guidelines illustrate this shift most clearly, where EPD scoring now determines shortlist eligibility for school and hospital bathroom renovations.
Tile Backer Boards Market Segmentation

Tile backer board specification diverges sharply across moisture-exposure severity and fire-rating requirements. Regulatory pressure on embodied carbon and silica exposure is compressing traditional material hierarchies, forcing contractors to recalibrate substrate selection against multi-jurisdiction compliance burdens.
Product Type:
Regulatory differentiation separates cement-based products facing silica-exposure limits from foam-core alternatives navigating thermal-bridge codes and REACH chemical restrictions.
- Cement Board:Portland cement and glass-fiber mesh composite with density ratings between 1,200 and 1,800 kg/m³ delivers fire-rated performance for commercial flooring underlayments. Construction contractors in the United States specify this material for hospital and school renovations where OSHA silica-compliance documentation is mandatory.
- Foam Board:Extruded polystyrene core with factory-laminated waterproofing membranes reduces field labor in European wet-area applications. Hospitality bathroom retrofits in Germany and Austria drive specification where thermal insulation codes have tightened beyond legacy cement-board capabilities.
- Fiber Cement Board:James Hardie Industries dominates North American commercial-grade wall-backing specifications through fiber-cement expertise and established distribution.
- Glass Mat Board:Mold-resistant paperless facing satisfies extended moisture-exposure warranties in multifamily construction across France and the Netherlands.
- Magnesium Oxide Board:Low-VOC certification requirements under EU REACH push manufacturers toward bio-based adhesive formulations with extended curing processes.
Cement board handles the majority of throughput; foam board is the fastest mover on share.
Application:
Cost tier stratification separates premium wet-area systems with integrated waterproofing from commodity flooring underlayments competing on unit price.
- Wet Areas:Steam shower enclosures and residential wet-rooms demand substrates with enhanced moisture-barrier ratings and thermal insulation compliance. European renovation contractors specify foam-core systems with factory-applied membranes to compress project timelines.
- Flooring Underlayments:Fire-rated cement boards anchor commercial specifications where building codes mandate flame-spread resistance. Retail and healthcare construction in the United States drives volume through familiar contractor installation protocols.
- Wall Backing:Interior designers and commercial developers specify glass-mat or fiber-cement products for multifamily residential applications requiring mold-resistance warranties.
- Countertops:Kitchen renovation demand concentrates specification of lightweight foam boards where substrate weight limits tile selection flexibility.
- Fire Protection Boards:High-density cement formulations serve industrial and institutional applications with stringent flame-resistance requirements.
Flooring underlayments absorb the largest share of material volume; wet-area applications are expanding most quickly as renovation cycles accelerate.
End User:
Customer type determines specification authority and compliance documentation burden, with commercial developers consolidating supplier relationships to reduce certification complexity.
- Construction Contractors:General contractors managing public infrastructure tenders in Germany weight environmental product declaration scoring alongside unit pricing, favoring manufacturers with multi-standard pre-certification.
- Commercial Developers:Hotel renovation teams accelerate substrate replacement cycles, specifying integrated membrane systems to compress bathroom retrofit timelines.
- Flooring Installers:Skilled labor scarcity for proper cement-board cutting and fastening techniques outpaces workforce development in renovation-heavy markets.
- Interior Designers:Aesthetic and performance specifications in premium residential projects drive demand for lightweight engineered panels with clean substrate edges.
- Homeowners:DIY renovation demand concentrates in online retail channels for smaller-format foam board products with simplified installation.
Construction contractors represent the largest procurement volume; commercial developers are gaining specification influence fastest through consolidated supplier programs.
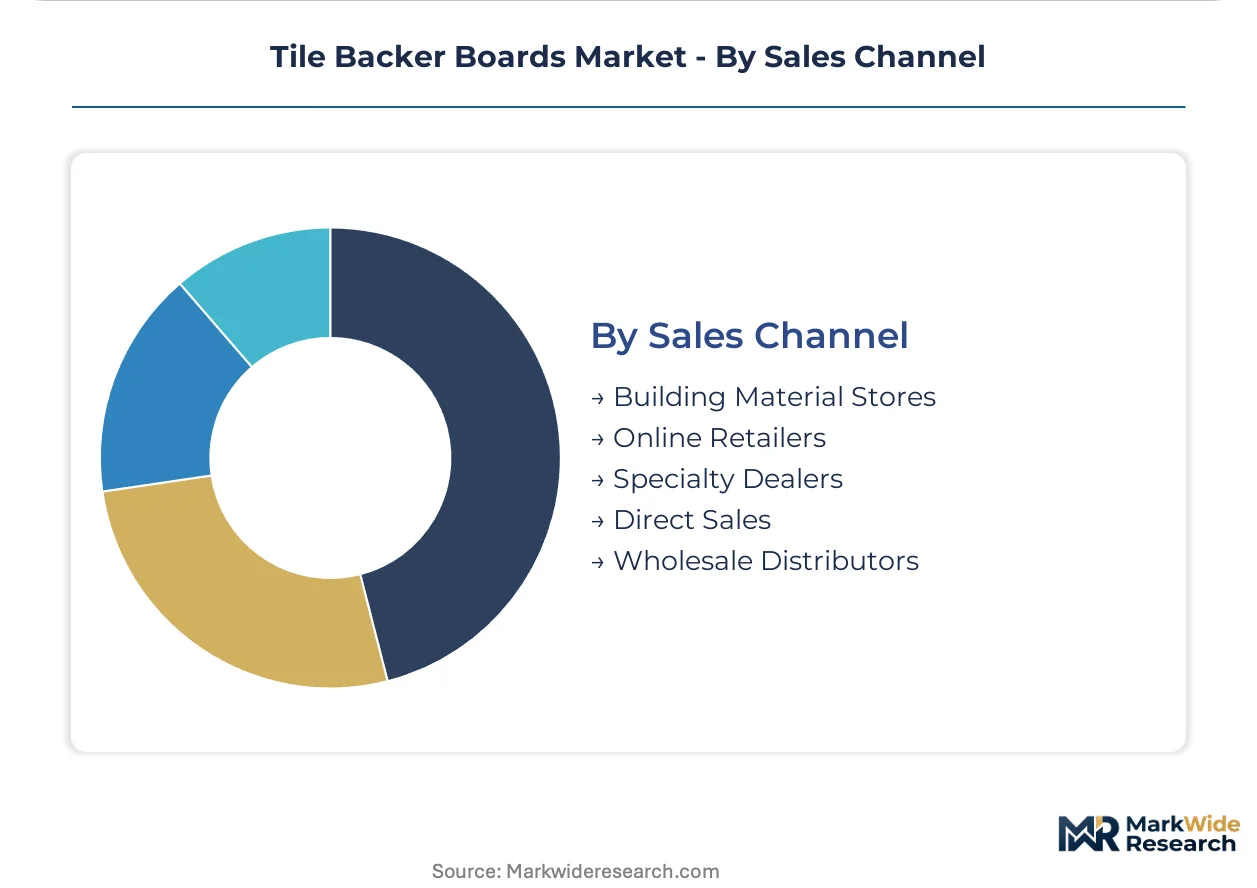
Sales Channel:
Supply concentration among building material stores and wholesale distributors shapes regional availability, while specialty dealers capture premium-specification margins through technical consultation.
- Building Material Stores:National home improvement chains in the United States stock cement and glass-mat boards for contractor pickup, with inventory depth determined by regional renovation activity.
- Wholesale Distributors:Saint-Gobain's CertainTeed network and similar broad-line distributors aggregate multi-product specifications for large-scale commercial projects.
- Specialty Dealers:wedi GmbH and Schluter Systems anchor premium foam-board supply chains through Germany's renovation sector with technical support and training.
- Direct Sales:Large commercial developers bypass distribution layers for volume procurement of certified substrates with project-specific documentation.
- Online Retailers:Homeowner and small-contractor demand for cut-to-size foam boards and accessories concentrates in digital channels with delivery logistics.
Building material stores and wholesale distributors together handle the majority of volume movement; specialty dealers are climbing the fastest on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cement clinker production clusters in China, Germany, and the United States shape raw material access for fiber-cement board manufacturers. These three countries anchor supply chains while divergent regulatory frameworks create distinct specification environments for substrate products.
United States
Hospital and school renovation contractors drive cement-board volume through OSHA silica-compliance documentation requirements. EPA moisture-resistance standards for wet-area construction mandate enhanced substrate performance ratings in commercial flooring applications. Dallas-Fort Worth and Atlanta metro construction corridors concentrate distribution networks for fiber-cement products serving the Southeast renovation market.
Germany
Federal building procurement guidelines now weight environmental product declaration scoring for school and hospital bathroom renovations. EU REACH restrictions on formaldehyde emissions push glass-mat manufacturers toward low-VOC certification pathways. wedi GmbH and Schluter Systems anchor premium foam-board supply chains through technical dealer networks concentrated in Bavaria and North Rhine-Westphalia.
China
Residential wet-room retrofits accelerate cement-board upgrades under MEE water-efficiency mandates for bathroom waterproofing. SAMR building waterproofing standards enforced by market surveillance restrict import access for uncertified substrate products. Yangtze River Delta manufacturing clusters around Shanghai dominate domestic production capacity for GB-certified backer boards.
France
Multifamily developers in Paris and Lyon specify low-VOC certified glass-mat substrates to meet extended mold-resistance warranties. EU Green Deal embodied-carbon disclosure requirements reshape material selection criteria for public infrastructure tenders. Auvergne-Rhône-Alpes industrial corridors host formulation facilities adapting bio-based adhesive processes for REACH compliance.
India
Urban bathroom renovation demand concentrates in Mumbai and Delhi-NCR metro construction markets. BIS building material standards for moisture-resistant substrates create certification barriers for imported cement-board products. Gujarat and Maharashtra manufacturing zones develop domestic foam-core production capacity to serve hospitality retrofit specifications.
Tile Backer Boards Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tile backer boards market. Fiber-cement specialists with decades of contractor relationships dominate commercial-grade specifications, while foam-core innovators capture premium wet-area renovations through integrated waterproofing systems. Three archetypes define competitive structure: scale-driven cement-board producers, specialized foam-system suppliers, and diversified building materials conglomerates with broad distribution networks. Capacity expansion in Asia-Pacific manufacturing zones and strategic partnerships for EPD certification dominate competitive moves among mid-tier players.
Within the diversified conglomerate tier, Saint-Gobain S.A. and Knauf Gips KG exemplify scale advantages through multi-product building material portfolios. James Hardie Industries plc occupies a position as the fiber-cement category anchor in North American commercial construction. wedi GmbH represents the specialized foam-system archetype with concentrated European wet-area expertise. These three company structures illustrate how geographic origin and corporate form signal strategic positioning without requiring operational detail.
| Leading Market Players |
|---|
| James Hardie Industries |
| Georgia-Pacific Wood Products |
| Saint-Gobain (CertainTeed) |
| USG Corporation |
| National Gypsum |
| Knauf |
| Johns Manville |
| wedi GmbH |
| Schluter Systems |
| Others |
Pricing and Supply Chain Analysis
Portland cement substitution by extruded polystyrene foam in European wet-area specifications simultaneously shifts supply geography toward Germany's chemical processing corridors and compresses pricing economics through reduced freight-weight costs and streamlined installation labor.
Pricing Analysis
EU REACH dictates the pricing tier structure across the tile backer boards market, separating low-VOC certified substrates from uncertified imports through extended mold-resistance warranties. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with multifamily developers in France and the Netherlands showing highest price sensitivity due to compressed project margins. Cost compression in economy-tier cement boards is intensifying because OSHA silica-compliance documentation adds manufacturing overhead. Premium foam-core systems with factory-applied membranes command least price sensitivity from hospitality renovation contractors prioritizing timeline compression.
Supply Chain Analysis
Just-in-time inventory preferences dominate European wet-area contractor procurement, while North American hospital and school renovators maintain strategic stockpiles of fire-rated cement boards to buffer against OSHA compliance documentation delays. Manufacturing concentrates in China, Germany, and the United States, with clinker production gravity in select regions creating input cost volatility for fiber-cement formulations. Raw material dependencies center on Portland cement, glass-fiber mesh, and extruded polystyrene resin. Single-source vulnerability runs through concentrated polystyrene resin supply. Distribution runs through Saint-Gobain's CertainTeed network and wedi GmbH's technical dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tile backer boards market functions as a defensive-moat story anchored in regulatory entrenchment, where multi-jurisdiction certification requirements create switching costs that cement incumbent positions and raise barriers for unqualified entrants.
For Market Incumbents: Secure multi-standard pre-certification across EPA moisture-resistance, EU REACH, and China's GB standards to compress product launch timelines against emerging foam-core specialists. Deepen captive supply of extruded polystyrene resin through backward integration into chemical processing partnerships, insulating margin positions from raw material volatility. For New Entrants and Emerging Players: Lead with integrated membrane systems targeting India's hospitality retrofit specifications, where BIS certification barriers restrict import access and domestic foam-core production capacity remains underdeveloped. Establish technical training partnerships with flooring installer networks to overcome skilled labor scarcity in renovation-heavy metro markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified building materials conglomerates with established EPD verification and multi-product distribution networks. Long-term viability favors acquisition targets possessing verified environmental product declarations and pre-certified compliance across at least two major regulatory jurisdictions. Monitor EU Green Deal embodied-carbon disclosure threshold adjustments as the primary inflection indicator for public infrastructure tender eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Certification Investment | Environmental product declarations unlock EU public infrastructure tender eligibility under Green Deal procurement guidelines. |
| Backward Integration into Resin Supply | Captive polystyrene sourcing insulates foam-board margins from petrochemical feedstock volatility. |
| Technical Dealer Network Expansion | Specialty distribution in Germany's renovation sector captures premium-margin foam-system specifications. |
| Multi-Jurisdiction Compliance Pre-Certification | Simultaneous EPA, REACH, and GB standard validation compresses 12-18 month launch timelines for commercial projects. |
| Installer Training Program Development | Skilled labor certification addresses contractor workforce scarcity in cement-board cutting and fastening techniques. |
Research Methodology
Desk research of trade association technical bulletins, customs import records, and regulatory filing databases preceded structured interviews with cement-board plant managers, foam-system R&D directors, hospitality procurement leads, and wet-area contractor supervisors. Primary fieldwork with distribution channel partners and secondary validation against SEC 10-K disclosures and building material trade data enabled bottom-up production estimates and top-down demand triangulation across the analysis window.
Variance decomposition across product type, application severity, end-user procurement authority, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories calibrated to renovation cycle intensity and compliance mandate implementation schedules. Modeled inputs included MEE water-efficiency mandate enforcement timelines, EU REACH formaldehyde restriction phase-in dates, and SAMR market surveillance intensity.
Underlying assumptions cover steady clinker production capacity, stable silica-exposure compliance costs, and sustained hospitality renovation demand, with deviation risk concentrated in cement supply disruptions and REACH adhesive formulation delays. Revision becomes warranted when EU Green Deal embodied-carbon disclosure thresholds tighten beyond current EPD verification capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Autoclave Aerated Concrete Market