
 Decks Market | 2026-2036
Decks Market Size, Share, and Industry Trends Forecast 2026-2036
Decks Market Analytics
North American lumber producers and composite resin suppliers are hardening output commitments as residential construction rebounds. Trex Company Inc leverages recycled polyethylene supply chains to dominate the composite segment. Fiberon LLC anchors its position through in-house extrusion capacity across multiple states. The AZEK Company Inc differentiates via polymer-capped board technology that commands premium specification.
Decks are load-bearing outdoor platforms engineered from timber, thermoplastic composites, or cellular PVC, typically spanning 16-inch on-center joist spacing with deflection limits of L/360 for residential applications. They extend functional living space and support structural occupancy ratings for entertainment, storage, and egress. Composite materials capture expanding specification share as contractors prioritize dimensional stability and fade resistance over traditional pressure-treated lumber. Custom-built construction methods retain margin concentration in high-end residential projects, while pre-fabricated and modular systems penetrate multi-family and commercial installations where labor scarcity elevates field-assembly value.
FDA guidelines for food-contact surfaces influence commercial deck specifications in hospitality applications, while EPA regulations on wood preservative leaching constrain treated-lumber distribution channels. OSHA fall-protection standards for elevated structures above four feet shape guardrail and stair design across municipal procurement. Stakeholders must monitor evolving building code adoptions at the state and municipal level, as ICC-ES certification requirements and local amendment cycles determine product eligibility and competitive access.
Market Dynamics
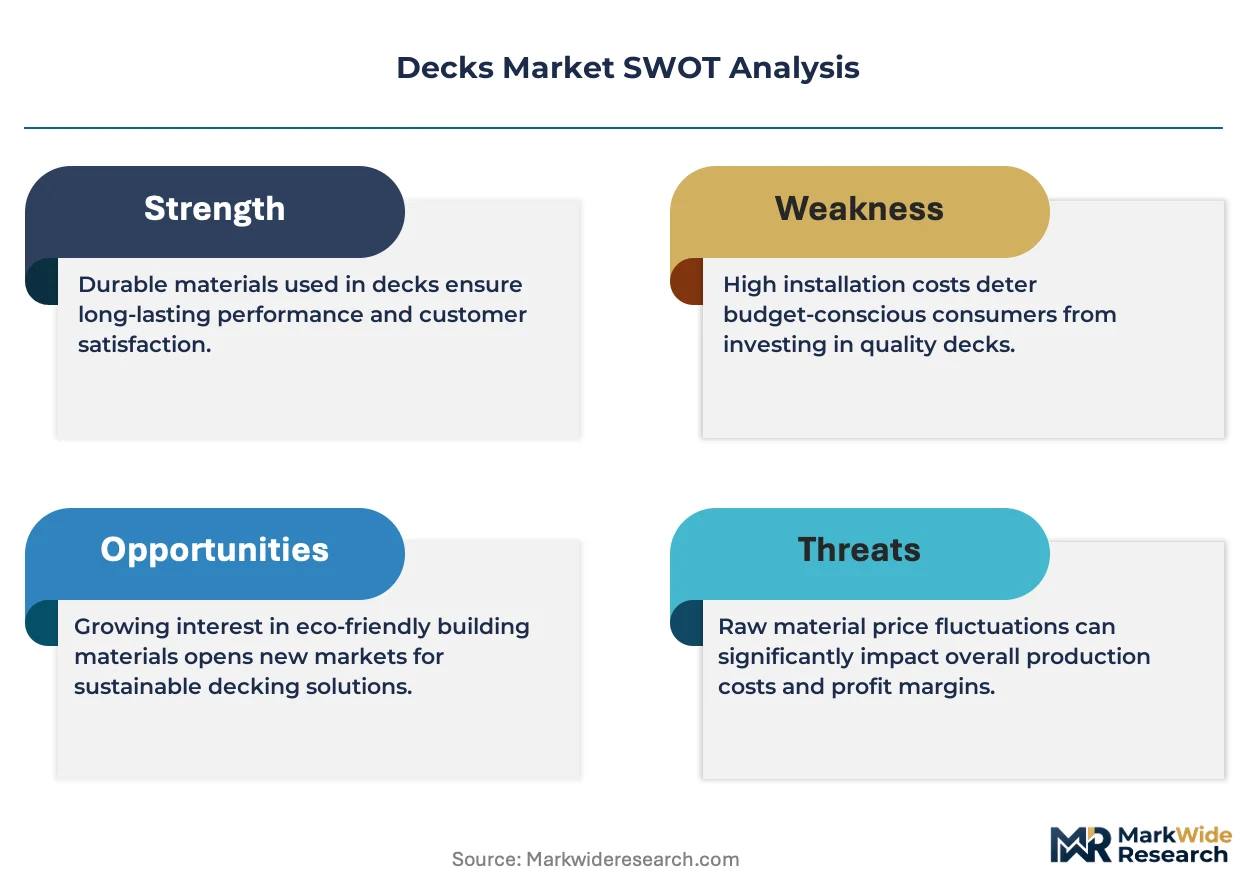
Residential renovation spending is redirecting material specification toward low-maintenance alternatives as EPA-treated wood regulations and California formaldehyde standards tighten compliance costs for traditional lumber.
Growth Catalysts
- Composite resin technology:Thermoplastic formulations deliver dimensional stability and fade resistance that contractors prioritize over pressure-treated lumber in suburban renovation projects.
- OSHA fall-protection standards:Elevated structure requirements above four feet are mandating engineered guardrail systems that integrate with modular deck platforms.
- Australia outdoor living investment:Persistent consumer spending on functional exterior space sustains demand for load-bearing platforms across metropolitan suburbs.
Market Restraints
- Polyethylene feedstock volatility:Recycled resin supply fluctuations compress composite manufacturers' margin predictability.
- ICC-ES certification cycles:State-level building code adoption timelines delay product eligibility in fragmented municipal procurement.
- Cellular PVC substitution:Polymer-capped board technology captures premium specification from conventional composite lines.
Strategic Opportunities
- Germany multi-family housing:Pre-fabricated modular systems address labor scarcity in field-assembly commercial installations.
- US hospitality FDA compliance:Food-contact surface specifications for commercial deck applications create specification pathways in restaurant and hotel construction.
- Digital specification platforms:Online procurement channels are compressing distributor margins while accelerating contractor access to engineered material data.
Industry Challenges
- Skilled carpenter availability:Custom-built construction methods require trained labor that residential contractors struggle to source.
- Local amendment tracking:Municipal building code variations force manufacturers to maintain multiple product certifications simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decks Market |
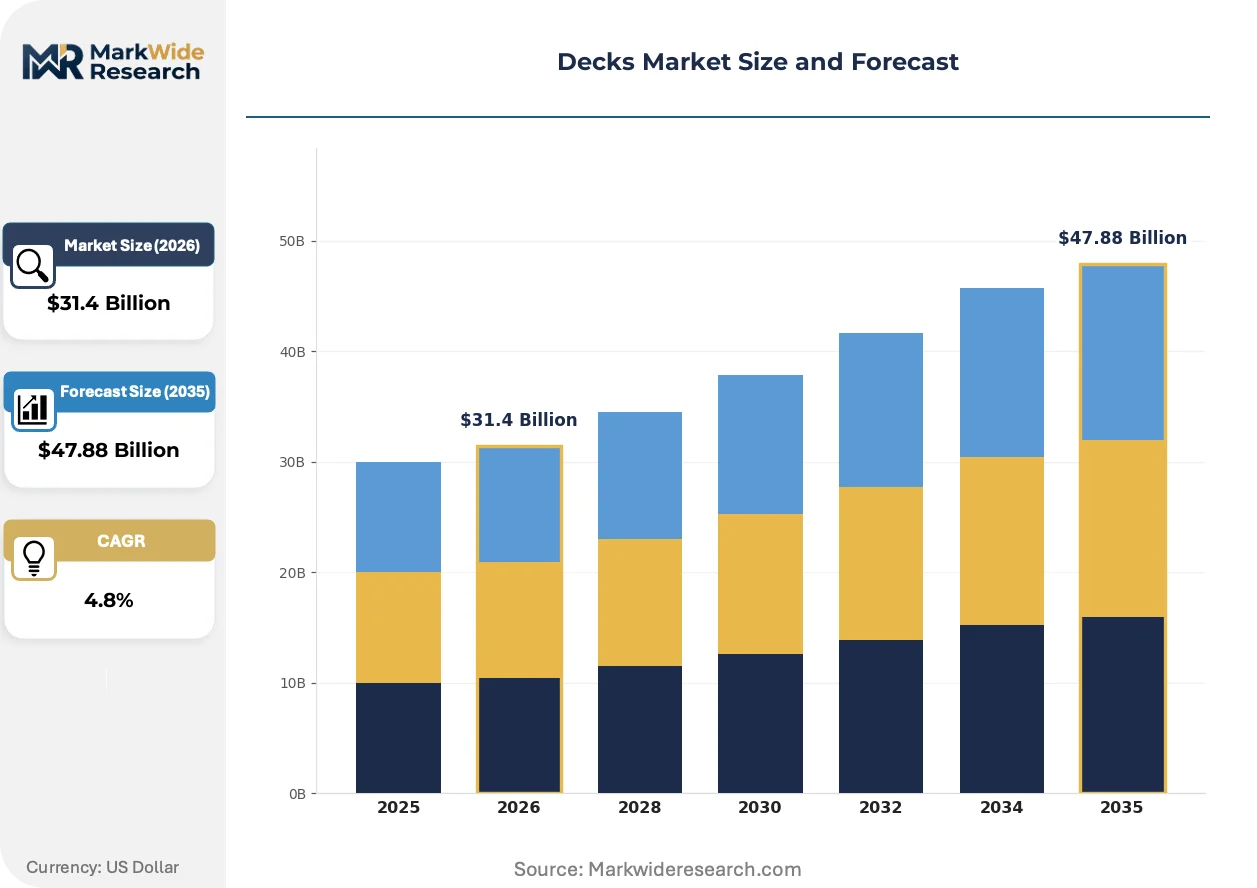
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Composite, PVC, Aluminum Design Type: Standard, Multi-Level, Elevated, Rooftop Construction Method: Pre-Fabricated, Modular, Custom Built, Kit End User: Residential, Commercial, Municipal, Contractors |
| Companies Covered | Trex Company Inc, The AZEK Company Inc, Fiberon LLC, Deckorators Inc, MoistureShield, Thermory AS, Cali Bamboo LLC, UFP Industries Inc, Lumberock Premium Decking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decks Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape how load-bearing outdoor platforms are specified, procured, and assembled across residential and commercial construction.
Cellular PVC core technology with polymer capping is decentralizing specification authority from regional distributors to direct contractor procurement. High-end residential builders are specifying fade-resistant boards for coastal and high-UV installations. This shift is compressing traditional lumber yard intermediation while elevating manufacturer-direct relationships.
EPA wood preservative leaching restrictions are constraining treated-lumber distribution channels across US residential markets. Retailers face inventory liability as regulatory scrutiny intensifies on chromated copper arsenate alternatives. Composite and PVC manufacturers are capturing shelf space as big-box building supply chains reconfigure outdoor lumber assortments.
Specification behavior is fragmenting across contractor tiers as digital takeoff tools enable precise material quantification. Mid-size residential builders are bypassing traditional distributor relationships for factory-direct composite orders. This pattern concentrates in Sun Belt metropolitan markets where renovation volume sustains dedicated procurement staff.
Decks Market Segmentation
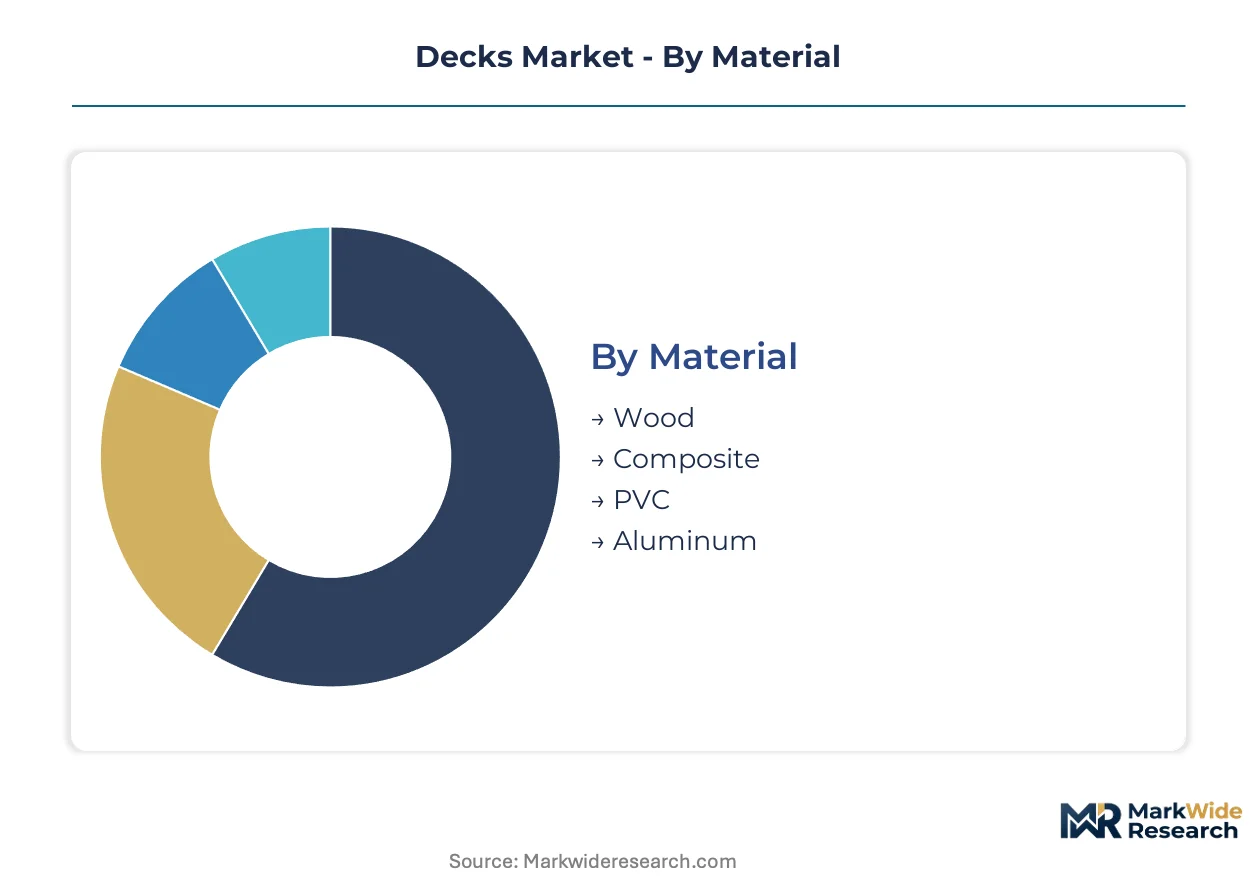
Material specification, design complexity, and construction methodology fragment the decks market into distinct procurement channels with divergent margin structures and specification authority. Each dimension reveals where value concentrates and how competitive positioning shifts across residential renovation and commercial new-build cycles.
Material:
Standalone deck platforms dominate residential applications, while embedded structural systems integrate with multi-story building envelopes in commercial and municipal specifications.
- Composite:Thermoplastic formulations blend recycled polyethylene with wood fiber to deliver dimensional stability and fade resistance. Demand concentrates in United States suburban renovation markets where contractors prioritize low-maintenance performance over pressure-treated lumber alternatives. EPA wood preservative regulations accelerate specification shifts away from traditional treated products.
- Wood:Pressure-treated lumber and tropical hardwoods retain cost advantage in budget-conscious residential segments. Specification persists in rural United States markets and Australia where established carpenter networks favor familiar fastening techniques and field-cut customization.
- PVC:Cellular polymer core technology with protective capping commands premium positioning in coastal and high-UV installations. California formaldehyde emission standards redirect specification toward inert synthetic alternatives.
- Aluminum:Extruded metal decking serves commercial rooftop and elevated platform applications requiring non-combustible ratings. Municipal procurement in Germany specifies aluminum for multi-family housing fire-code compliance.
Volume placements concentrate in Wood; the faster expansion belongs to Composite.
Design Type:
Cost tier stratification separates entry-level single-plane installations from engineered multi-structure systems requiring specialized load calculations.
- Standard:Single-level platforms at grade or modest elevation dominate residential renovation volume. United States suburban homeowners specify standard designs for backyard entertainment space expansion.
- Multi-Level:Tiered platforms with integrated stair systems command premium pricing in high-end residential construction. Australia metropolitan markets sustain demand for complex designs supporting outdoor living investment.
- Elevated:Structures exceeding four feet in height trigger OSHA fall-protection guardrail mandates. Commercial hospitality applications in United States Sun Belt markets require engineered elevated systems for poolside and dining terraces.
- Rooftop:Pedestal-mounted decking systems for structural roof applications demand lightweight materials and drainage integration. Germany multi-family housing construction specifies rooftop designs for amenity space maximization.
Standard designs capture the greatest installation volume; rooftop systems are climbing the fastest as urban density intensifies.
Construction Method:
Customer type divides between skilled carpenter-dependent custom work and labor-scarce markets favoring factory-controlled quality.
- Custom Built:On-site framing and finishing by trained carpenters retains margin concentration in high-end residential projects. United States coastal markets sustain custom demand where architectural review boards mandate site-specific design compliance.
- Pre-Fabricated:Factory-assembled modules reduce field labor requirements and accelerate installation timelines. Germany multi-family contractors specify pre-fabricated systems to address skilled carpenter availability constraints.
- Modular:Interlocking platform components enable rapid reconfiguration and seasonal removal. Australia hospitality operators deploy modular systems for event-flexible outdoor dining spaces.
- Kit:Packaged material bundles with pre-cut components target DIY residential renovators. United States big-box retail channels distribute kit systems to suburban homeowners seeking weekend installation projects.
Custom built methods retain the highest value per project; pre-fabricated systems are gaining share fastest where labor scarcity elevates factory assembly value.
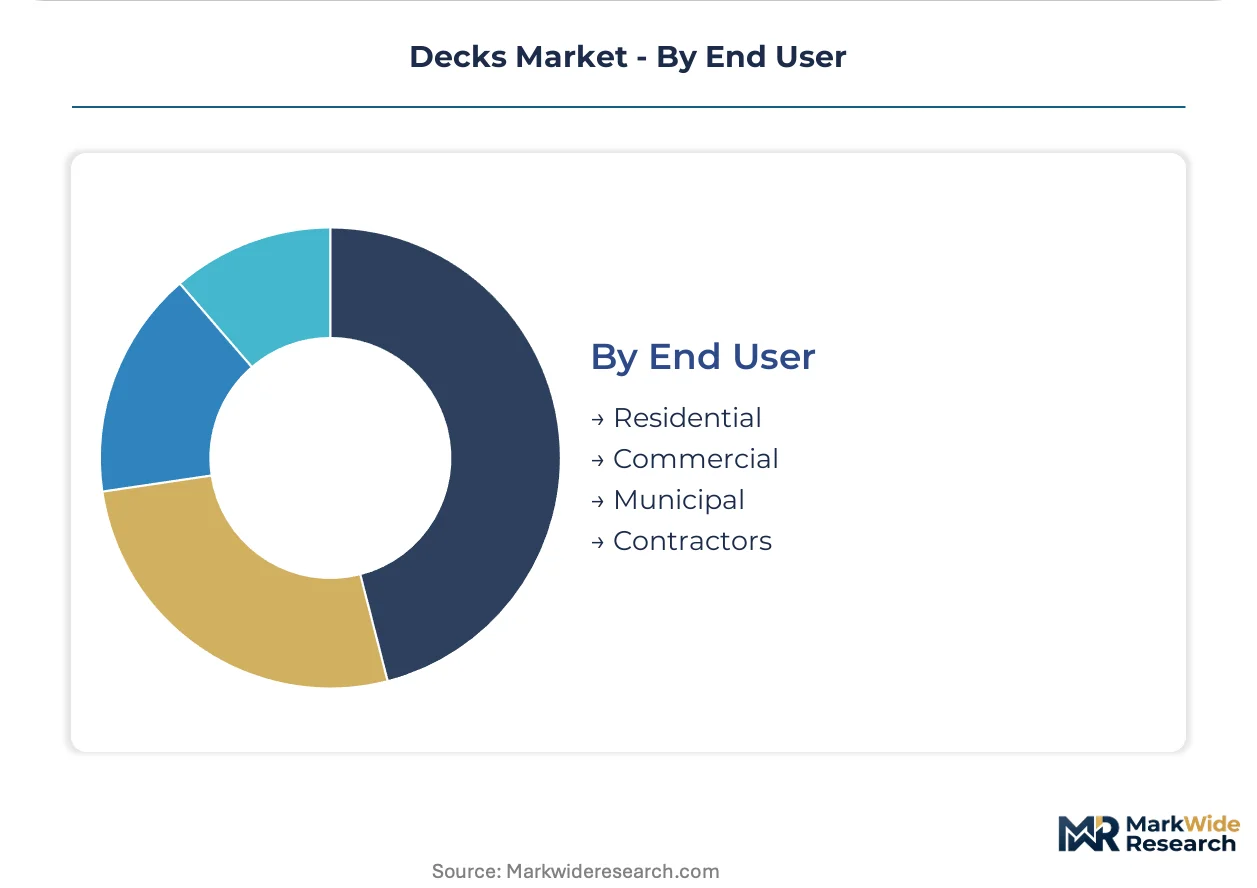
End User:
Application maturity separates established residential replacement cycles from emerging commercial specification pathways.
- Residential:Single-family and multi-family homeowners drive material specification through renovation spending and new construction. United States suburban markets concentrate demand for composite and PVC alternatives to traditional wood.
- Commercial:Restaurants, hotels, and retail operators specify decks for functional exterior dining and display space. FDA food-contact surface guidelines influence commercial material selection in United States hospitality applications.
- Municipal:Parks departments and public works agencies procure elevated observation platforms and boardwalk systems. Australia coastal municipalities specify durable materials for high-traffic public installations.
- Contractors:Professional installers function as specification gatekeepers, translating architect drawings into material orders. United States regional contractor networks concentrate procurement authority in Sun Belt metropolitan markets.
Residential end users account for the greatest material volume; commercial applications are expanding most quickly as hospitality outdoor dining investment persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled polyethylene supply chains concentrate in the United States Gulf Coast, anchoring composite resin availability for North American deck manufacturing. Timber feedstocks in Scandinavia and the Baltic states sustain European wood decking production. Australian hardwood plantations provide tropical species for premium residential installations.
United States
Suburban renovation spending in Sun Belt metropolitan markets accelerates composite deck specification. EPA wood preservative leaching regulations constrain treated-lumber distribution channels across residential markets. Dallas-Fort Worth and Phoenix contractor networks concentrate procurement authority for factory-direct composite orders.
Germany
Multi-family housing construction and labor scarcity elevate pre-fabricated modular system demand. ECHA REACH compliance requirements redirect specification toward low-emission synthetic alternatives. Bavaria and North Rhine-Westphalia municipal procurement specifies aluminum decking for fire-code compliance in elevated platforms.
Australia
Metropolitan outdoor living investment sustains demand for load-bearing platforms across suburban markets. TGA-influenced material safety standards shape commercial hospitality specifications. Sydney and Melbourne coastal municipalities specify durable materials for high-traffic public boardwalk installations.
Canada
Pressure-treated lumber retains cost advantage in budget-conscious rural renovation segments. Health Canada wood preservative guidelines influence retailer inventory decisions. Ontario and British Columbia residential contractors favor familiar fastening techniques for field-cut customization.
United Kingdom
Garden room and outdoor entertainment space expansion drives residential deck installation volume. CE marking requirements for construction products shape imported material compliance. Southeast England and Greater London high-end residential builders specify fade-resistant boards for premium installations.
Decks Market Competitive Landscape
Global majors compete with regional champions across material technology and distribution reach, producing a tiered structure where scale-driven resin compounders face specialized timber processors. Composite manufacturers leverage recycled supply chain control against traditional lumber yard networks. Three archetypes dominate: integrated resin-to-board producers, distributor-captive fabricators, and specialty hardwood importers. Capacity expansion and direct-to-contractor digital platforms represent the dominant competitive moves reshaping channel access.
Among North American composite specialists, Trex Company Inc and The AZEK Company Inc exemplify the integrated technology tier, while Fiberon LLC occupies a position within the multi-state extrusion capacity segment. These three entities anchor the competitive landscape through differentiated material approaches—recycled polyethylene formulations, polymer-capped cellular PVC, and in-house manufacturing scale—each representing a distinct pathway to contractor specification authority.
| Leading Market Players |
|---|
| Trex Company Inc |
| The AZEK Company Inc |
| Fiberon LLC |
| Deckorators Inc |
| MoistureShield |
| Thermory AS |
| Cali Bamboo LLC |
| UFP Industries Inc |
| Lumberock Premium Decking |
| Others |
Value Network & Pricing Analysis
Recycled polyethylene bale indices from the United States Gulf Coast cascade through composite resin pricing tiers, compressing margins for manufacturers without captive supply while elevating premium positioning for polymer-capped cellular PVC alternatives. California formaldehyde emission standards and EPA wood preservative regulations amplify cost differentials between compliant synthetic materials and constrained treated-lumber distribution channels.
Pricing Analysis
Warranty bundling separates premium composite lines offering 25-year fade-and-stain coverage from economy-tier wood products carrying limited structural guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by material technology and certification grade, with ICC-ES evaluation reports commanding contractor specification premiums. Cost compression in entry-level pressure-treated lumber intensifies as retailers face inventory liability from regulatory scrutiny. Residential DIY renovators exhibit highest price sensitivity, while commercial hospitality specifiers prioritize FDA-compliant surface performance over unit economics.
Supply Chain Analysis
Domestic-content mandates in United States municipal procurement and Germany multi-family housing construction reshape sourcing toward regional extrusion capacity. Composite resin compounding concentrates in the United States, Germany, and China, drawing from recycled polyethylene feedstocks, wood fiber byproducts, and virgin polymer additives. Single-source vulnerability runs through Gulf Coast resin suppliers exposed to hurricane disruption. Distribution runs through big-box building supply chains and contractor-direct digital platforms fragmenting traditional lumber yard intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled carpenter scarcity constrains custom-built capacity, propping pricing power for factory-controlled pre-fabricated and modular alternatives. This supply bottleneck sustains margin concentration where labor substitution technology penetrates fastest.
For Market Incumbents: Extend polymer-capped board technology into coastal high-UV applications to defend against cellular PVC substitution threatening conventional composite lines. Anchor backward integration into recycled polyethylene supply chains to offset feedstock volatility compressing margin predictability. Capture specification authority through direct-to-contractor digital platforms bypassing distributor intermediation. For New Entrants and Emerging Players: Regional contractor networks in United States Sun Belt metropolitan markets represent the most penetrable specification gatekeepers, as mid-size builders bypass traditional distributors for factory-direct composite orders. Target Germany multi-family housing pre-fabricated systems where labor scarcity elevates field-assembly value. Deploy digital takeoff tools enabling precise material quantification as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated resin-to-board producers with captive Gulf Coast supply in the United States, as polyethylene feedstock volatility compresses non-integrated competitors. Long-term viability hinges on regulatory tailwinds redirecting specification from treated lumber toward low-maintenance alternatives. Monitor ICC-ES certification adoption timelines at state level as inflection indicator for product eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Supply Chain Integration | Captive polyethylene sourcing insulates Trex and AZEK from resin price volatility. |
| Polymer Capping Technology Expansion | Fade-resistant cellular PVC commands premium specification in California coastal markets. |
| Pre-Fabricated Modular Capacity Buildout | Factory assembly addresses Germany carpenter scarcity in multi-family construction. |
| Direct-to-Contractor Digital Platform | Online procurement compresses distributor margins while accelerating specification access. |
| ICC-ES Certification Investment | State-level building code adoption unlocks municipal procurement eligibility. |
Research Methodology
Independent corroboration across composite manufacturer resin procurement directors, big-box building supply category managers, and Sun Belt metropolitan contractor networks underwrites the qualitative findings. Primary fieldwork captured specification behavior, installation cost structures, and code adoption timelines. Secondary validation drew from EPA regulatory filings, ICC-ES evaluation report databases, and customs data tracking polyethylene resin trade flows. Bottom-up volume modeling triangulated against top-down construction spending projections.
Comparable-period anchoring to historical residential renovation cycles and commercial new-build permits established the forecast baseline across the analysis window. Segmentation dimensions modeled include material technology, design complexity tier, construction methodology, and end-use application. CAGRs derived from elasticity-adjusted demand curves incorporating composite substitution rates and treated-lumber regulatory constraints. Forecast inputs encompassed skilled labor availability indices and municipal code amendment tracking.
Several conditions sit outside the modeled scope, including extreme weather disruption to Gulf Coast resin infrastructure and abrupt shifts in federal wood preservative enforcement posture. Forecasts reflect assumptions around steady regulatory trajectory and gradual composite cost parity achievement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market