
 Acoustic Plasterboard Market | 2026-2036
Acoustic Plasterboard Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Plasterboard Market Analytics
Multi-source procurement for mineral-core substrates is hardening as tier-one contractors reduce single-plant dependency risks. Saint-Gobain leverages captive gypsum reserves across multiple continents to buffer raw-material volatility. Knauf Group anchors its competitive stance through continuous board-line automation that compresses unit conversion costs. USG Corporation differentiates via specification-grade fire-resistant portfolios that dominate North American healthcare and education bids.
Acoustic plasterboard denotes a gypsum-core panel engineered with perforated, fissured, or fabric-wrapped facings to achieve noise reduction coefficients between 0.55 and 0.95 across speech-frequency ranges; manufacturers bond glass-fiber or mineral-wool layers to the rear face to extend absorption into lower octaves, serving open-plan offices, auditoriums, and patient wards where reverberation control is mandatory. Fire-resistant and moisture-resistant variants command the widest specification spreads in commercial and healthcare end uses, while lightweight boards are gaining fastest in retrofit residential ceilings where dead-load constraints limit standard-density alternatives. Thickness segments stratify by performance tier: 12mm and 15mm boards occupy the volume core for standard partitions, whereas 20mm systems capture premium soundproofing applications requiring multi-layer attenuation.
REACH and the EU Green Deal are tightening embodied-carbon disclosure rules for interior construction products sold across Europe, compelling reformulation of gypsum binders and recycled-content claims. In the United States, ASTM E84 and UL 263 fire-performance standards filter market access for non-domestic suppliers seeking specification in commercial and institutional projects. Stakeholders must monitor evolving MEE enforcement of dual-carbon goals in China, where gypsum mining permits and clinker-free core innovations will reshape export-competitive supply bases.
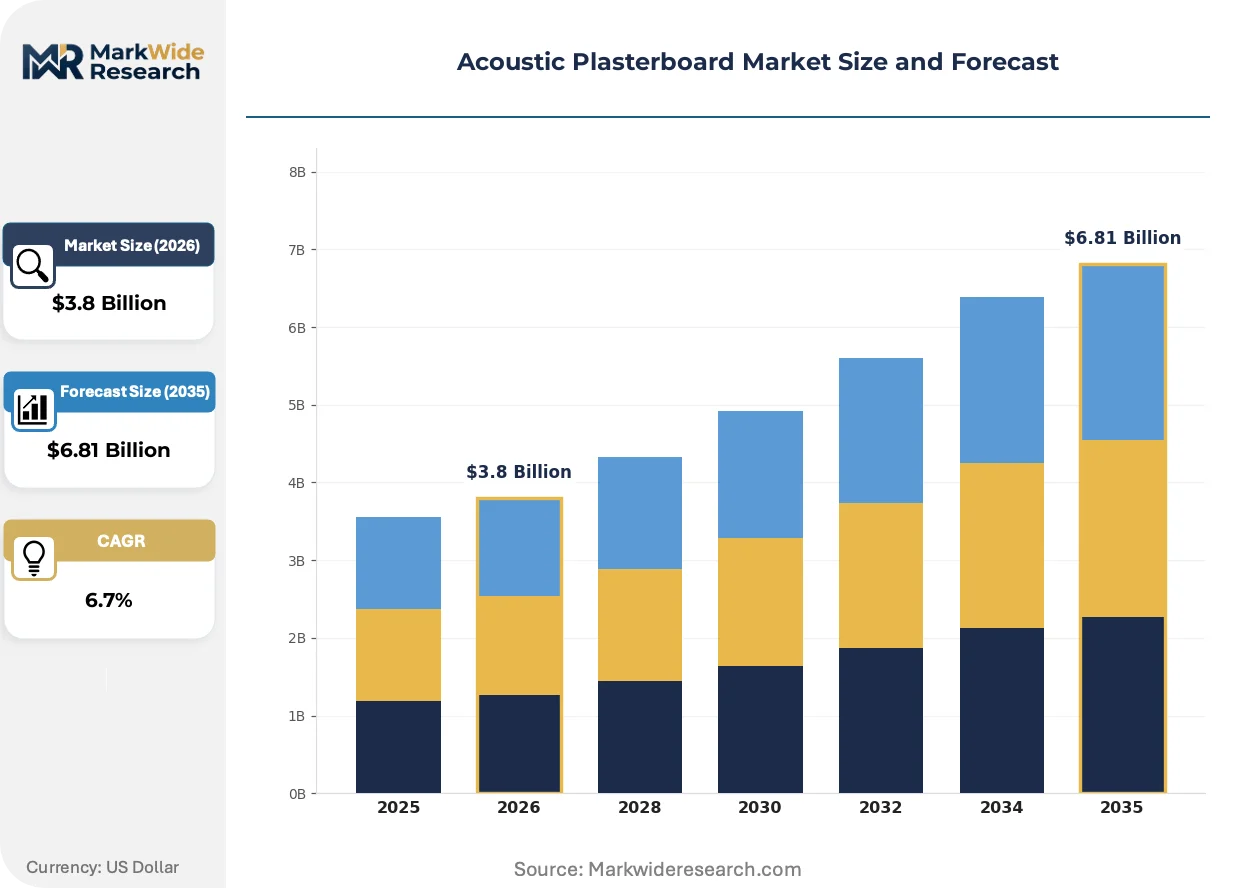
Market Dynamics
EU Green Deal embodied-carbon thresholds are forcing gypsum-core reformulation across European manufacturing footprints, compressing margins for producers dependent on high-clinker binders while advantaging operators with captive recycled-content streams.
Growth Catalysts
- Healthcare privacy mandates:Hospital renovation cycles in Germany specify certified acoustic boards to meet patient confidentiality requirements. Fire-resistant variants capture premium positioning in clinical environments.
- REACH disclosure expansion:ECHA enforcement of recycled-content verification creates specification pull for manufacturers with transparent gypsum sourcing. Certification gaps penalize non-compliant imports.
- Office-to-residential conversions:Urban density pressures in Frankfurt and Berlin accelerate dead-load-sensitive retrofit demand. Lightweight 12mm boards displace standard-density alternatives in ceiling applications.
Market Restraints
- Raw material volatility:Synthetic gypsum supply from flue-gas desulfurization fluctuates with coal-power plant operating rates. Captive mining reserves buffer tier-one producers against spot-market spikes.
- Single-plant dependency risk:Mineral-wool backing layers concentrate production in Eastern European facilities. Logistics disruptions propagate through just-in-time contractor inventories.
- Technical thickness limitations:Multi-layer 20mm systems require specialized installation crews. Labor scarcity constrains premium segment expansion in secondary cities.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland specify acoustic performance in school construction but lack domestic gypsum-core capacity. Import logistics favor Baltic Sea port distributors.
- Moisture-resistant variants:Swimming pool and aquatic center retrofits create specification pull for glass-fiber reinforced facings. Humidity cycling tests differentiate premium tiers.
- Digital specification platforms:BIM-integrated product selection tools bypass traditional merchant channels. Architects in the Netherlands and Denmark source directly from manufacturer databases.
Industry Challenges
- Certification timeline compression:EU Green Deal carbon-footprint verification requires third-party auditing of gypsum extraction through end-of-life. Small manufacturers lack capital for parallel certification tracks.
- Installation skill fragmentation:Perforated facing alignment demands acoustic testing competence absent in general drywall crews. Training program scaling lags specification growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Plasterboard Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Fire-Resistant, Moisture-Resistant, Lightweight End User: Commercial Buildings, Residential Buildings, Educational Institutions, Healthcare Facilities Thickness: 9mm, 12mm, 15mm, 20mm Application: Interior Partitions, Ceilings, Walls, Soundproofing |
| Companies Covered | Saint-Gobain, Knauf Group, USG Corporation, Etex Group, Georgia-Pacific, Armstrong World Industries, Rockfon, Owens Corning, British Gypsum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Plasterboard Market Evolving Landscape
Reformulation of gypsum binders around lower-clinker chemistries is compressing the competitive set, rewarding producers with integrated recycling infrastructure and transparent supply-chain documentation.
Mineral-wool composite backing is consolidating specification preference in healthcare and education verticals. Hospital operators in Germany and the Netherlands specify NRC 0.75+ performance tiers for open-plan clinical zones. Multi-material bonding expertise is concentrating market share among producers with captive glass-fiber supply.
REACH recycled-content disclosure rules are tightening verification requirements for gypsum-core products sold across Europe. ECHA enforcement actions against unsubstantiated environmental claims are filtering distributor portfolios. Manufacturers with blockchain-tracked demolition gypsum streams capture specification preference in public-sector tenders.
Architects are unbundling acoustic performance specification from general contractor procurement packages. Direct manufacturer relationships in Denmark and Sweden bypass traditional builder-merchant markups. Digital product configurators with real-time NRC calculators compress the design-to-specification cycle.
Acoustic Plasterboard Market Segmentation
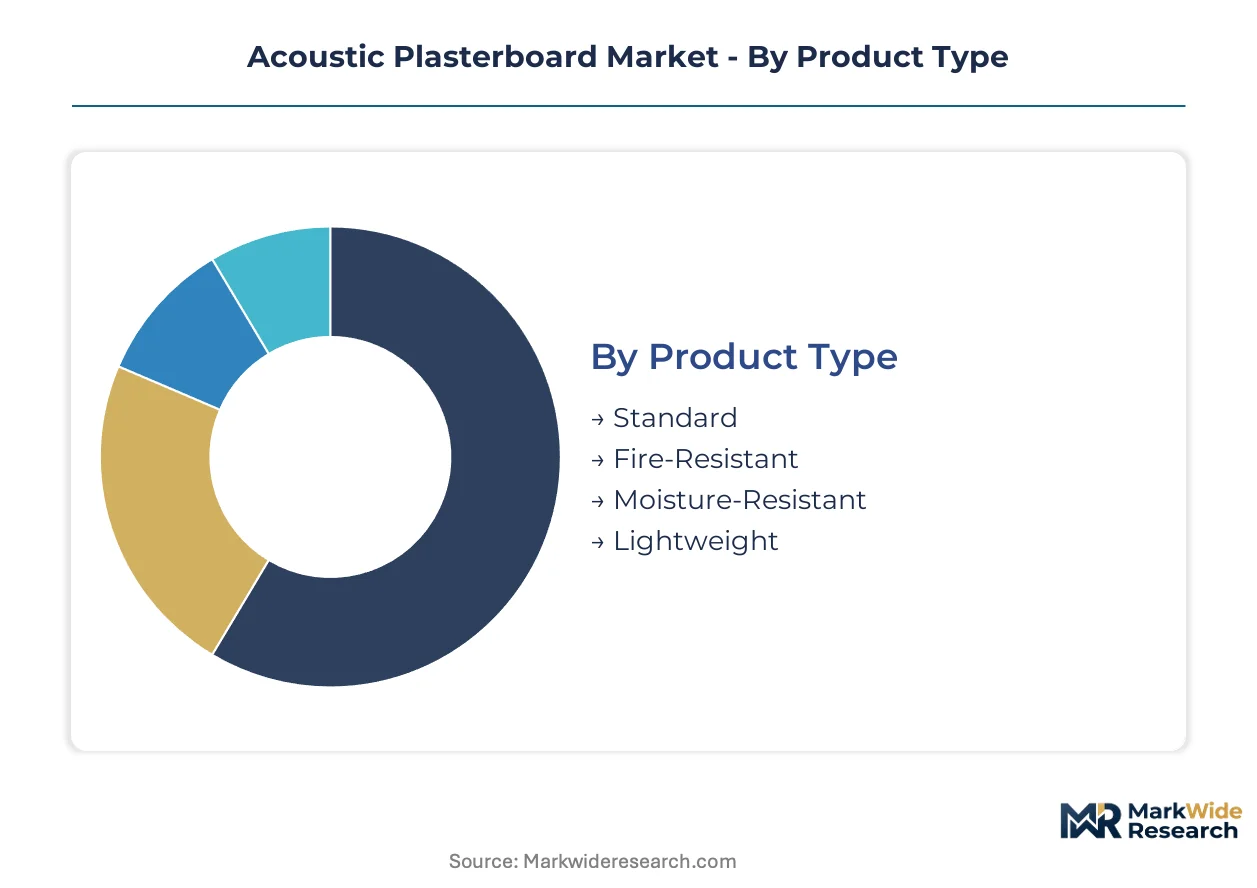
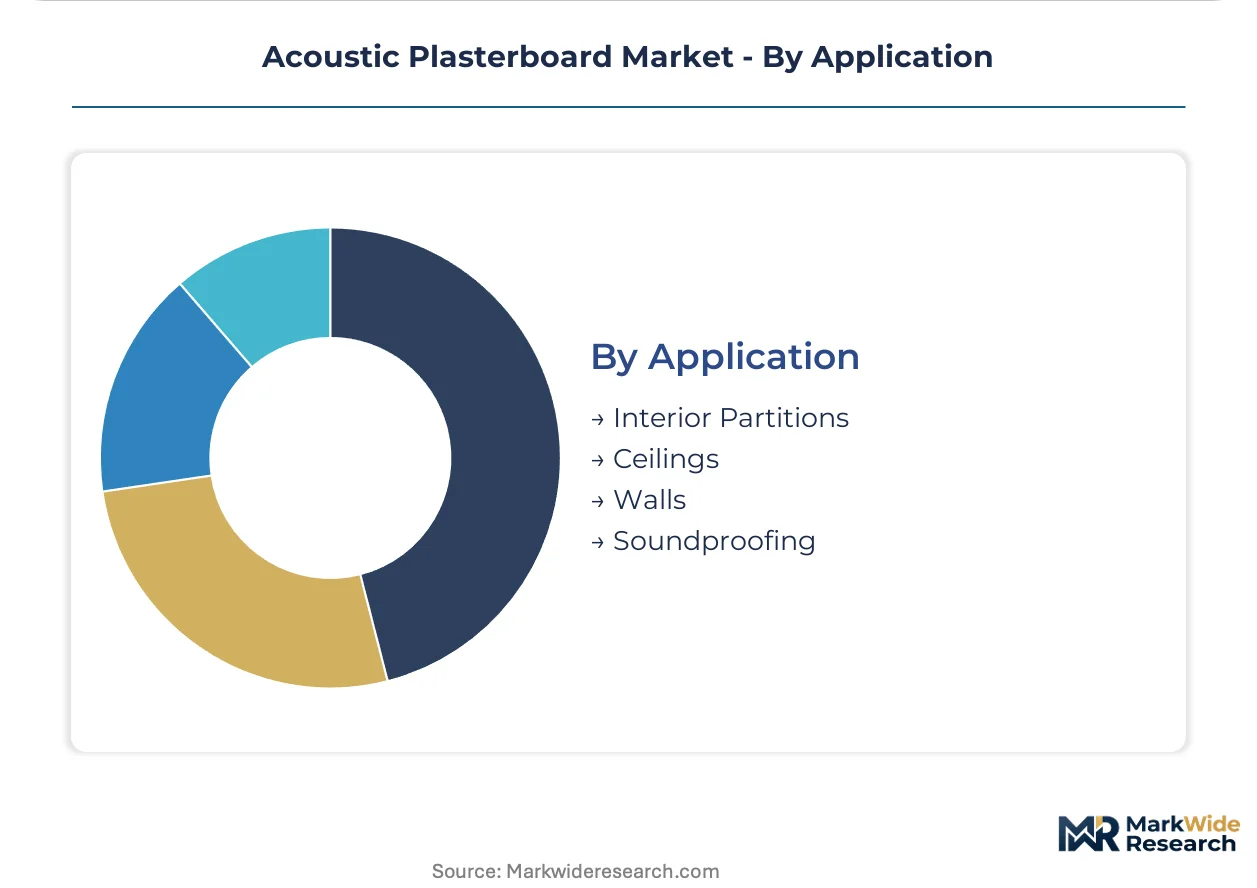
Segmentation in acoustic plasterboard reflects divergent technical requirements across building codes, acoustic performance tiers, and installation constraints. Specification-grade variants command distinct procurement channels from commodity boards, while thickness selection ties directly to structural load limits and multi-layer attenuation needs.
Product Type:
Upgrade cycles in healthcare and education verticals are accelerating specification shifts toward performance-graded variants that satisfy evolving fire-safety and humidity-resistance mandates.
- Fire-Resistant:Glass-fiber reinforced gypsum cores achieve ASTM E84 Class A and UL 263 ratings. German hospital renovation tenders specify these boards for corridor and patient-room applications where fire-stop continuity is mandatory.
- Moisture-Resistant:Silicone-treated facings and wax-impregnated cores resist humidity cycling. Swimming pool retrofits in the Netherlands and aquatic centers in Denmark drive specification for glass-fiber reinforced facings that pass accelerated aging protocols.
- Standard:Unfaced gypsum-core panels serve cost-sensitive residential and light commercial partitioning where acoustic performance requirements remain minimal.
- Lightweight:Reduced-density cores cut dead loads by 25-30% versus standard boards. Ceiling retrofits in Frankfurt and Berlin office-to-residential conversions favor these systems where structural capacity constraints limit traditional alternatives.
Fire-Resistant sits at the top of the volume ranking, with Lightweight climbing the fastest.
End User:
Procurement concentration varies sharply by vertical, with institutional buyers demanding certified supply chains and residential developers prioritizing cost-per-square-meter metrics.
- Healthcare Facilities:Patient privacy mandates under Germany's hospital accreditation standards specify NRC 0.75+ acoustic performance. Fire-resistant and anti-microbial facings capture premium positioning in clinical environments where infection control intersects with sound dampening.
- Commercial Buildings:Open-plan office fit-outs in Frankfurt and Munich specify perforated-facing boards for reverberation control. Lease-cycle renovations every 7-10 years sustain replacement demand.
- Educational Institutions:School construction in Sweden and Finland mandates acoustic performance for learning environments. Import logistics from Baltic Sea ports favor distributors with established specification relationships.
- Residential Buildings:Multi-family housing retrofits concentrate demand for 12mm lightweight ceiling boards. Dead-load sensitivity in older building stock limits specification of standard-density alternatives.
Healthcare Facilities command the highest specification premiums, with Educational Institutions expanding most quickly.
Thickness:
Thickness selection maps directly to acoustic attenuation targets, structural constraints, and labor skill availability across installation geographies.
- 12mm:Standard residential and light commercial ceiling applications where dead-load limits and cost sensitivity dominate. Office-to-residential retrofits in Berlin specify this thickness for speed of installation.
- 20mm:Multi-layer systems achieve STC 50+ ratings for premium soundproofing. Hospital patient wards and recording studios in Germany specify these boards where speech privacy is non-negotiable.
- 9mm:Curved ceiling applications and feature wall cladding where flexibility and reduced weight enable complex geometries.
- 15mm:Standard partition walls in commercial fit-outs balancing acoustic performance with material cost. General contractor preference in secondary German cities where labor rates compress premium segment adoption.
12mm maintains volume leadership across all end uses, with 20mm gaining share fastest in healthcare specification.
Application:
Application-specific installation protocols are fragmenting the contractor base, with acoustic testing competence concentrating in specialized crews.
- Ceilings:Suspended grid systems dominate commercial and institutional retrofit. Lightweight 12mm boards displace standard-density alternatives where structural capacity is constrained.
- Interior Partitions:Demountable wall systems in Frankfurt office renovations specify acoustic boards with integrated electrical and data raceways. Flexibility for future reconfiguration drives specification.
- Walls:Direct-applied facing boards serve residential and light commercial verticals where cost minimization outweighs premium acoustic performance.
- Soundproofing:Dedicated acoustic retrofit projects in recording studios, home theaters, and confidential meeting rooms. NRC 0.85+ performance tiers command specialized installation and testing protocols.
Ceilings capture the largest installed base, with Soundproofing posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting acoustic plasterboard production toward jurisdictions with lower embodied-carbon compliance costs, even as specification demand concentrates in mature markets with stringent hospital privacy mandates and office-to-residential conversion pipelines.
Germany
Hospital renovation cycles in Frankfurt and Berlin drive specification for NRC 0.75+ fire-resistant boards under patient confidentiality mandates. EU Green Deal carbon-footprint disclosure rules compel reformulation of gypsum binders in domestic manufacturing. The Rhine-Ruhr industrial corridor hosts concentrated board-line automation investments serving central European distribution.
United States
Healthcare and education verticals sustain demand for ASTM E84 Class A certified systems across hospital and campus construction. HIPAA privacy requirements intersect with fire-performance standards in clinical environment specifications. The Southeast manufacturing belt leverages synthetic gypsum from regional coal-power desulfurization for cost-competitive core production.
China
Dual-carbon enforcement by MEE is tightening gypsum mining permits and accelerating clinker-free core innovation in export-competitive supply bases. Domestic demand for acoustic performance lags Western specification intensity. The Yangtze River Delta clustering integrates demolition gypsum recycling streams into board manufacturing for lower-carbon product lines.
Netherlands
BIM-integrated specification platforms enable Dutch architects to source acoustic boards directly from manufacturer databases, bypassing traditional merchant channels. REACH recycled-content verification creates preference for transparent gypsum sourcing. The Randstad urban agglomeration concentrates office-to-residential retrofit activity driving lightweight 12mm ceiling demand.
Sweden
School construction mandates specify acoustic performance for learning environments without domestic gypsum-core manufacturing capacity. Import logistics through Baltic Sea ports favor established distributor relationships. Stockholm and Gothenburg construction pipelines concentrate demand for certified boards meeting Nordic building code reverberation controls.
Acoustic Plasterboard Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital specification channels and recycled-content verification as differentiation vectors. Market structure tilts toward consolidated tier-one operators with captive mineral reserves and automated board-line capacity, while mid-scale fabricants compete on regional logistics and specialized performance variants. Three archetypes dominate: integrated gypsum miners with multi-continent reserve bases, automation-heavy converters compressing unit costs, and specification-grade specialists commanding healthcare and education premiums. Competitive moves concentrate on M&A for recycled-content supply chains and strategic partnerships with BIM platform developers.
Within the integrated-reserve archetype, Saint-Gobain anchors positioning through captive gypsum holdings across multiple continents. Knauf Group exemplifies the automation-driven converter model with continuous board-line investments. USG Corporation occupies the specification-grade tier, representing fire-resistant portfolio differentiation in North American institutional bidding. These three entities collectively illustrate how raw-material security, manufacturing efficiency, and certification depth segment competitive positioning across end-use verticals.
| Leading Market Players |
|---|
| Saint-Gobain |
| Knauf Group |
| USG Corporation |
| Etex Group |
| Georgia-Pacific |
| Armstrong World Industries |
| Rockfon |
| Owens Corning |
| British Gypsum |
| Others |
Value Network & Pricing Analysis
Certification-grade fire-resistant acoustic boards command substantial premiums over standard-density alternatives, with the EU Green Deal's embodied-carbon disclosure rules compressing margins for producers lacking transparent gypsum sourcing while rewarding operators with integrated recycling infrastructure. This bifurcation manifests in procurement channels where hospital systems in Germany pay specification premiums for NRC 0.75+ performance tiers, while residential retrofit contractors in Berlin negotiate volume discounts on lightweight 12mm boards sourced through Baltic Sea distributors.
Pricing Analysis
Distributor markups of 15-25% separate specification-grade boards from commodity alternatives in European merchant channels. Pricing stratifies across premium, standard, and economy tiers based on fire-resistance certification depth and recycled-content verification transparency. Cost compression in standard-density segments is intensifying because synthetic gypsum supply from coal-power desulfurization fluctuates with plant operating rates. Healthcare facilities demonstrate lowest price sensitivity due to patient privacy mandate compliance requirements, while residential developers in secondary German cities drive hardest bargain on per-square-meter metrics.
Supply Chain Analysis
Demolition gypsum return flows from construction waste streams are consolidating around Rhine-Ruhr industrial corridor processors serving Saint-Gobain and Knauf Group board-line operations. Manufacturing concentrates in Germany, China, and the United States, with each jurisdiction leveraging distinct feedstock advantages: captive mining reserves, synthetic gypsum from power generation, and recycled-content integration respectively. Supply chain risk centers on single-plant dependency for mineral-wool backing layers produced in Eastern European facilities. Distribution runs through specification-grade merchant networks for institutional buyers and direct-to-contractor platforms for residential retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustic plasterboard market functions as a regulatory compounder where EU Green Deal carbon-footprint verification creates sustained specification pull for manufacturers with transparent supply-chain documentation and certified recycled-content streams.
For Market Incumbents: Cement market position through captive gypsum reserve expansion and continuous board-line automation investments that compress unit conversion costs against emerging recycled-content specialists. Prioritize REACH compliance infrastructure to defend specification access in German hospital renovation tenders where ECHA enforcement actions filter non-compliant imports. Backward integration into demolition gypsum recycling streams anchors margin defense against spot-market synthetic gypsum volatility. For New Entrants and Emerging Players: Digital specification platforms with BIM-integrated NRC calculators offer technology-first wedge into architect-direct procurement channels bypassing traditional merchant markups in the Netherlands and Denmark. Target underpenetrated Nordic school construction markets in Sweden and Finland where acoustic performance mandates lack domestic manufacturing capacity. Pursue moisture-resistant variant specialization for aquatic center retrofits as the most penetrable premium segment with differentiated humidity-cycling test protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where small manufacturers lack capital for parallel EU Green Deal certification tracks and REACH third-party auditing requirements. Long-term viability favors integrated operators with captive mineral reserves, automated board-line capacity, and established specification relationships in healthcare and education verticals. Monitor ECHA enforcement action frequency against unsubstantiated environmental claims as the inflection indicator for distributor portfolio filtering acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Supply Chain Acquisition | Captures specification preference in German public-sector tenders requiring transparent gypsum sourcing documentation. |
| BIM Platform Partnership Development | Enables direct architect engagement in Denmark and Netherlands, bypassing traditional builder-merchant channel markups. |
| Moisture-Resistant Variant Capacity Expansion | Addresses swimming pool and aquatic center retrofit demand in Netherlands with glass-fiber reinforced facing differentiation. |
| Nordic Distribution Network Establishment | Secures Baltic Sea port logistics advantage for Swedish and Finnish school construction specification mandates. |
| Fire-Resistance Certification Investment | Maintains access to German hospital renovation cycles where UL 263 and ASTM E84 ratings filter market entry. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gypsum plant managers, healthcare facility procurement directors, architectural specification consultants, and distribution channel partners with secondary validation from EU ECHA enforcement databases, REACH compliance registries, German hospital accreditation standards, customs trade flow records, and SEC filings of publicly traded building materials producers. Bottom-up volume modeling across thickness segments and end-use verticals triangulated against top-down market sizing from production capacity analysis.
Historical reference periods anchored the projection horizon through verified shipment data and specification trend analysis, with segmentation modeling across product type, end user, thickness, and application dimensions plus regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycles, renovation pipeline tracking, and carbon-regulation compliance timeline assessment. Forecast inputs incorporated hospital renovation cycle intensity in Germany, office-to-residential conversion permitting velocity in Frankfurt and Berlin, and REACH recycled-content verification enforcement trajectory.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to synthetic gypsum supply disruption from coal-power plant closures, MEE dual-carbon enforcement acceleration in Chinese export bases, and EU Green Deal carbon-border adjustment implementation scope. Practitioners should monitor ECHA environmental claim audit announcements, German hospital accreditation standard revisions, and Baltic Sea shipping rate volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Building Insulation Market