
 New Zealand Window Covering Market | 2026-2036
New Zealand Window Covering Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Window Covering Market Foresight
The gap between premium automated shading and commodity manual coverings is realigning how distributors structure their portfolios. Luxaflex New Zealand leverages its motorized technology leadership to dominate the high-end residential channel. Impact Blinds anchors its position through manufacturing scale in the volume builder segment. Venluree Blinds differentiates via specialized commercial project capabilities across Auckland and Wellington.
Window coverings comprise operable and fixed treatments engineered to control light transmission, thermal transfer, and visual privacy through specified openness factors, fabric weights, or slat geometries. Blinds and shades lead product type demand, with fabric-based systems capturing margin pools in the hospitality renovation cycle. Metal and vinyl materials compete on durability for commercial end users, while wood sustains premium residential positioning. Distribution through specialty stores and home improvement channels shapes how manufacturers navigate project-specified versus retail-discretionary demand.
New Zealand's Building Code, administered by the Ministry of Business, Innovation and Employment, mandates thermal performance standards that filter which glazing-compatible coverings qualify for new construction. The country's national energy efficiency framework and local council consenting processes shape product specification pathways for developers and architects. Stakeholders must monitor how upcoming amendments to the Healthy Homes Standards redirect landlord investment toward insulating window treatments.
Market Dynamics
New Zealand's window covering sector faces structural pressure from the Building Code's escalating thermal performance mandates, which filter product eligibility through energy efficiency compliance rather than aesthetic preference alone.
Growth Catalysts
- Auckland construction pipeline:Residential and commercial building consents in New Zealand's largest city concentrate demand for premium fenestration treatments, pulling automated shading into mainstream specification.
- Healthy Homes Standards amendments:Landlord obligations under the country's rental housing quality framework redirect capital expenditure toward insulating window treatments that improve thermal ratings.
- Smart home integration:Motorized blind systems with IoT connectivity are capturing renovation spend as homeowners prioritize centralized climate and light management.
Market Restraints
- Fabric supply concentration:Specialty technical textiles for solar shading rely on limited Australasian weaving capacity, exposing distributors to lead time volatility and freight cost fluctuations.
- Aluminum extrusion dependency:Metal component pricing tracks global commodity markets, compressing margin stability for venetian and vertical blind manufacturers serving the commercial segment.
- Consenting complexity:Local council interpretation of Building Code clause H1 creates inconsistent approval pathways across territorial authorities, fragmenting product rollout timelines.
Strategic Opportunities
- Wellington commercial retrofit:Seismic strengthening projects in the capital's central business district create bundled specification opportunities for integrated shading and glazing upgrades.
- Passive House alignment:Certification growth among high-performance residential builders favors specialized low-emissivity cellular shades that meet stringent airtightness requirements.
- Direct-to-installer platforms:Digital ordering systems bypassing traditional merchant intermediaries are capturing trade contractor volume through configurators that automate specification compliance.
Industry Challenges
- Building Code interpretation variance:Inconsistent thermal modeling assumptions across territorial authorities force manufacturers to maintain multiple product certification pathways for identical specifications.
- Installation workforce scaling:Motorized system deployment outpaces the availability of electricians with fenestration integration experience, particularly in Canterbury's post-earthquake rebuild zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Window Covering Market |
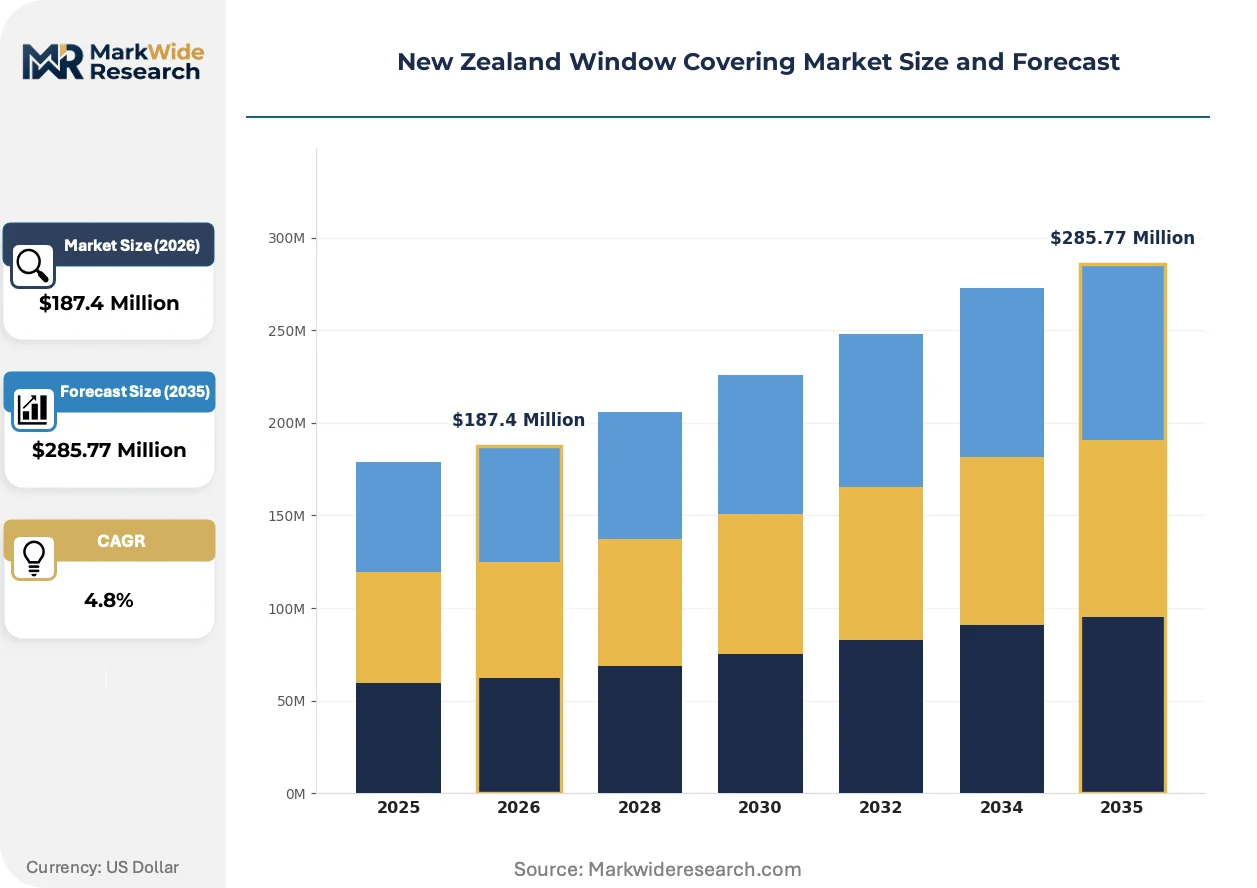
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blinds, Shades, Curtains, Shutters Material: Wood, Fabric, Vinyl, Metal End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Offline, Specialty Stores, Home Improvement |
| Companies Covered | Venluree Blinds, Impact Blinds, Luxaflex New Zealand, Intex Concepts, Mr Blinds, Santa Fe Shutters & Blinds, The Interiors Group, SunGuard, Window Treatments NZ Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Window Covering Market Shifts & Advancements
Automation and energy compliance are rewiring how window coverings are specified, manufactured, and installed across New Zealand's fragmented building supply chain.
Battery-powered motorized shading is decentralizing control architecture in residential and light commercial installations. Lithium-ion cell technology eliminates hardwired power requirements, enabling retrofit applications in heritage buildings where electrical penetration is restricted. Auckland renovation contractors are specifying these systems at accelerating rates, compressing the addressable market for manual chain-operated alternatives.
The Ministry of Business, Innovation and Employment's administration of Building Code clause H1 is tightening thermal bridging calculations for fenestration assemblies. Developers must now demonstrate whole-window U-values that factor in covering integration, forcing manufacturers to submit coordinated glazing-shading performance data. Multi-unit residential projects in Tauranga and Hamilton are experiencing the most acute specification friction as design teams reconcile aesthetic briefs with compliance thresholds.
Trade procurement through merchant showrooms is fragmenting as quantity surveyors and project managers migrate specification authority to digital platforms. These tools embed compliance checking against local council databases, reducing reliance on distributor technical support. The shift is most pronounced in Auckland's volume builder segment, where procurement centralization favors suppliers with API-accessible product data and automated quoting workflows.
New Zealand Window Covering Market Segmentation
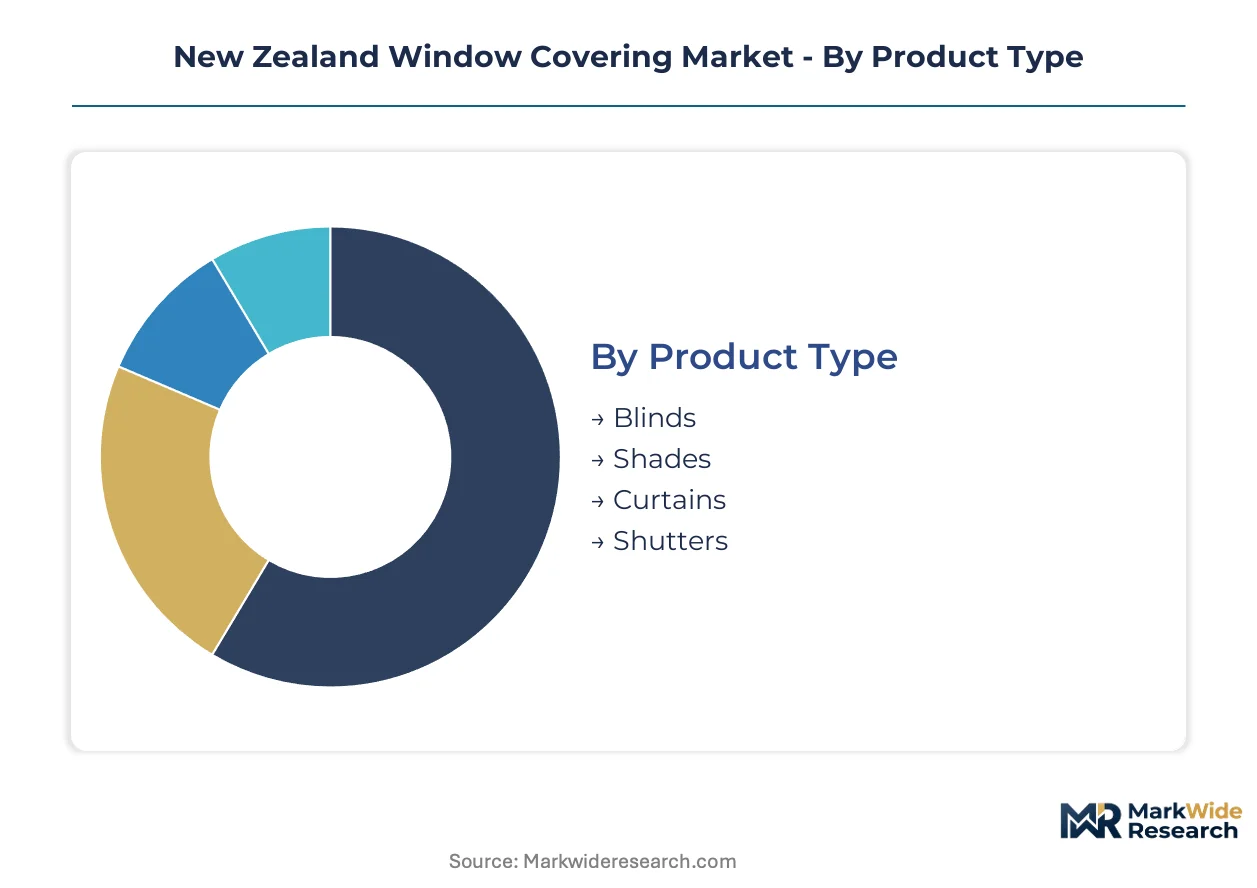
Segmentation in New Zealand's window covering market reveals how specification authority splits between project-driven commercial channels and retail-discretionary residential purchases. Understanding these divides helps manufacturers align production capacity with the divergent lead times, compliance requirements, and margin structures each pathway demands.
Product Type:
Standalone operable systems dominate retrofit applications, while embedded automated shading increasingly penetrates new construction specifications across Auckland and Wellington.
- Blinds:Slatted systems using aluminum, wood, or synthetic materials enable precise light control through adjustable vane angles. Auckland's volume home builders specify metal venetian blinds for cost-engineered thermal compliance in multi-unit developments. Demand concentrates where Building Code H1 calculations require proven U-value improvements without premium outlays.
- Shades:Continuous fabric surfaces—roller, cellular, and roman variants—deliver superior insulation through trapped air layers and low-emissivity coatings. Wellington's seismic retrofit projects favor motorized cellular shades for their combination of thermal performance and automated control integration. Passive House-certified residential builders specify these for airtightness compatibility.
- Curtains:Drapery systems with track or pole mounting provide acoustic dampening and decorative flexibility. Heritage renovation contractors in Christchurch specify heavy interlined curtains for thermal bridging mitigation where external shading is restricted.
- Shutters:Hinged or fixed louvre panels in timber or composite materials offer security and storm protection alongside light management. Coastal North Island specifications favor marine-grade polymer shutters for humidity resistance.
Blinds lead volumes today; shades are gaining share fastest.
Material:
Cost tier alignment determines material selection, with premium wood and technical fabric commanding specification in architect-designed projects while vinyl and standard metal serve merchant-channel volume.
- Wood:Solid timber and engineered wood composites deliver thermal mass and aesthetic warmth. Premium residential architects in Auckland's Herne Bay and Remuera specify sustainably sourced hardwoods for facade-integrated shutter systems.
- Fabric:Technical textiles span solar screen meshes through to blackout-coated weaves, with openness factors calibrated to glare control requirements. Tauranga's hospitality renovation cycle drives demand for flame-retardant contract fabrics in hotel guestroom specifications.
- Vinyl:Extruded and foamed polymer slats offer moisture immunity and uniform color stability. Volume builders in Hamilton specify vinyl vertical blinds for rental housing compliance with Healthy Homes Standards at minimum capital cost.
- Metal:Aluminum extrusions and perforated steel deliver durability for commercial high-cycle applications. Wellington CBD office retrofits specify anodized aluminum venetian blinds for longevity in tenant improvement budgets.
Fabric commands the widest specification range; wood maintains the steepest price premium.
End User:
Application context shapes procurement authority, with landlord compliance obligations driving residential specification while facilities managers control commercial replacement cycles.
- Residential:Owner-occupier and landlord purchasers prioritizing thermal performance, smart home integration, or rental compliance. Auckland's infill housing developers specify automated roller shades as standard in townhouse specifications.
- Commercial:Office, healthcare, and education facilities requiring glare management and HVAC load reduction. Wellington's government tenancy upgrades favor integrated building management system connectivity.
- Hospitality:Hotels and serviced apartments balancing guest experience with operational durability. Queenstown's luxury lodge sector drives demand for blackout-compatible motorized systems.
- Retail:Shopfront and mall tenancies requiring security screening and merchandise protection. Christchurch's rebuild retail precincts specify perforated metal roller shutters for after-hours security.
Residential anchors volume; commercial retrofit represents the steepest expansion trajectory.
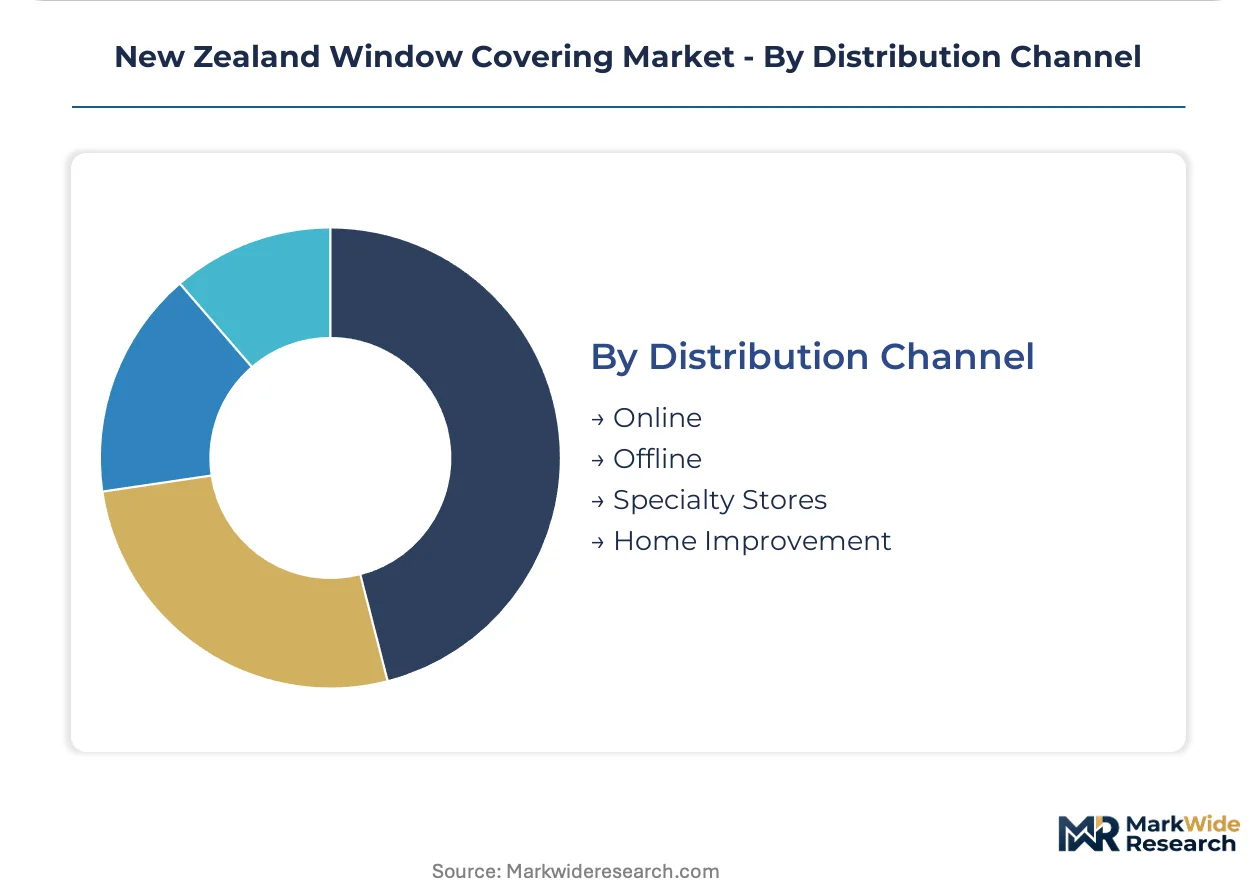
Distribution Channel:
Customer type fragmentation splits procurement between trade contractors seeking specification support and direct consumers prioritizing tactile evaluation.
- Online:Direct-to-consumer and trade ordering platforms with automated quoting and compliance checking. Auckland's quantity surveyors increasingly specify through digital configurators linked to council consent databases.
- Offline:Traditional merchant and showroom channels providing physical sample evaluation. Provincial markets retain higher offline dependency where installer networks remain relationship-based.
- Specialty Stores:Dedicated window covering retailers offering measurement, design consultation, and installation coordination. Premium automated systems concentrate here due to technical pre-sale requirements.
- Home Improvement:Big-box retailers serving DIY and light trade replacement demand. Standard manual blinds dominate this channel for immediate availability and price transparency.
Offline channels retain majority share; online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glazing installers and certified electricians cluster around Auckland and Wellington, anchoring the industry's technical workforce concentration.
Auckland
Residential infill housing and commercial high-rise construction concentrate demand for automated shading systems. The Ministry of Business, Innovation and Employment administers Building Code clause H1 compliance that shapes specification pathways. Auckland's volume builder segment drives standardization of motorized roller shades in multi-unit townhouse developments.
Wellington
Seismic strengthening of commercial buildings and government tenancy upgrades create bundled specification opportunities. Local council interpretation of thermal performance standards varies, creating consenting complexity for integrated glazing-shading assemblies. The central business district's retrofit pipeline favors building management system connectivity in office refurbishment projects.
Canterbury
Post-earthquake rebuild zones sustain elevated demand for replacement window treatments across residential and commercial stock. Installation workforce scaling lags motorized system deployment, particularly for fenestration-integrated electrical work. Christchurch heritage renovation contractors specify heavy interlined curtains where external shading faces preservation restrictions.
Waikato
Hamilton's rental housing market responds to Healthy Homes Standards amendments redirecting landlord capital toward insulating treatments. Volume builders specify vinyl vertical blinds for compliance at minimum capital outlay. The region's distribution networks serve provincial markets where relationship-based installer networks retain higher offline channel dependency.
Queenstown-Lakes
Luxury lodge construction and hospitality renovation cycles drive demand for blackout-compatible motorized systems. Tourism accommodation operators balance guest experience specifications with operational durability requirements. The district's high-value residential architects prioritize facade-integrated automated shading for premium positioning.
New Zealand Window Covering Market Competitive Landscape
Top-tier vendors anchor the premium automated segment, while mid-scale fabricators compete on manufacturing scale and specialized commercial capabilities. The vendor base spans three strategic archetypes: technology-led motorized specialists, volume-optimized manufacturers, and project-capable commercial contractors. Competitive moves concentrate on portfolio diversification into adjacent building envelope products and direct-to-installer digital platform development.
Within the premium-tier vector, Luxaflex New Zealand occupies a position exemplifying technology leadership in motorized systems. Impact Blinds and Venluree Blinds represent contrasting scale-driven and project-specialist archetypes respectively. These three companies anchor the competitive structure across residential renovation, volume builder, and commercial specification channels.
| Leading Market Players |
|---|
| Venluree Blinds |
| Impact Blinds |
| Luxaflex New Zealand |
| Intex Concepts |
| Mr Blinds |
| Santa Fe Shutters & Blinds |
| The Interiors Group |
| SunGuard |
| Window Treatments NZ Ltd |
| Others |
Supply & Pricing Matrix
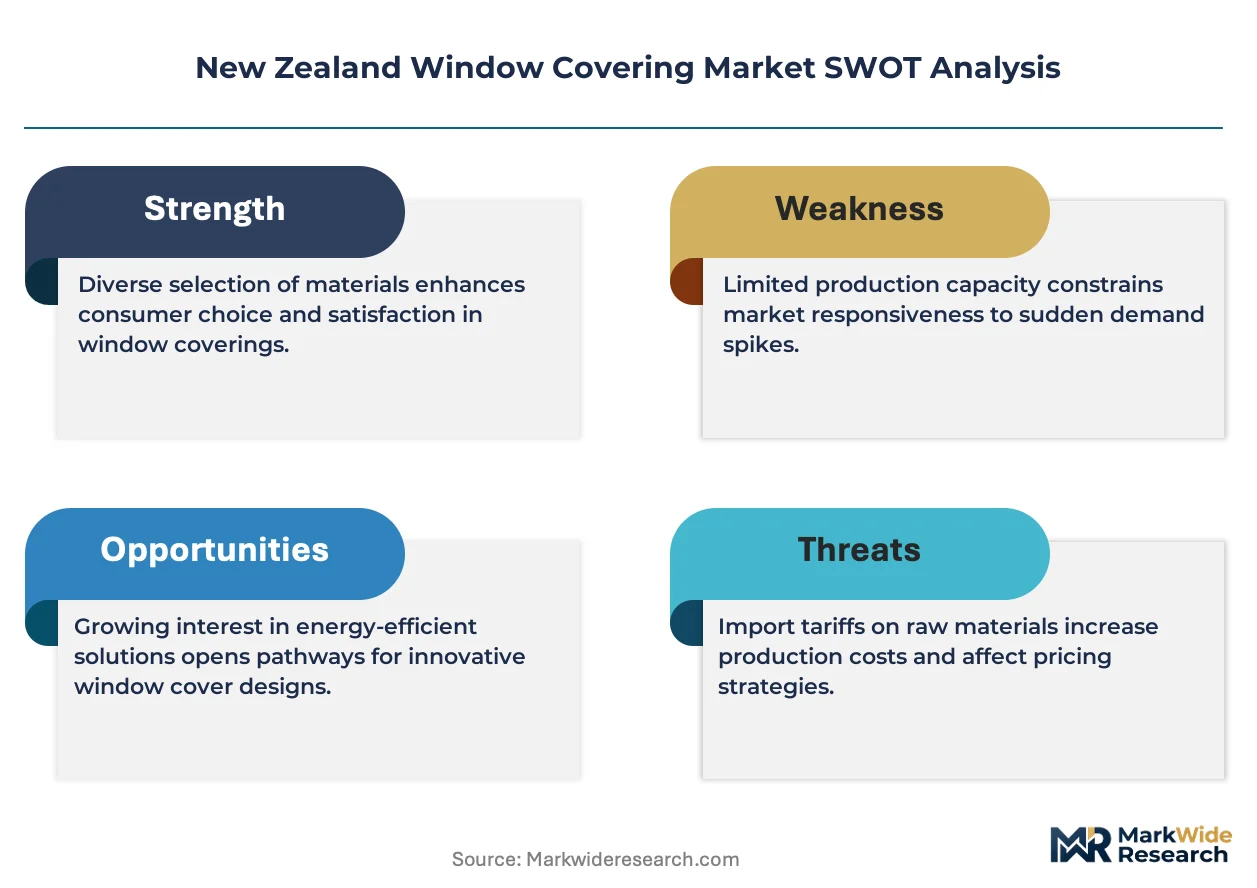
Building Code H1 thermal compliance mandates are forcing developers to specify certified glazing-compatible coverings, compelling suppliers to absorb certification costs and segment offerings by performance tier rather than aesthetics alone.
Pricing Analysis
Bundled installation and compliance documentation commands premium positioning over unbundled product-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates motorized automated systems from manual chain-operated alternatives and commodity vinyl slats. Price differentiation hinges on thermal certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because volume builders negotiate centralized procurement contracts. Landlord purchasers in Hamilton show highest price sensitivity; luxury lodge developers in Queenstown-Lakes exhibit lowest.
Supply Chain Analysis
Freight cost volatility from limited Australasian weaving capacity exposes distributors to margin erosion on technical textile imports. Manufacturing concentrates in China for aluminum extrusions, Australia for specialty fabrics, and New Zealand for timber shutter assembly. Raw material dependencies span lithium-ion cells for battery-powered motors, anodized aluminum for commercial venetians, and low-emissivity coated fabrics for cellular shades. Single-source vulnerability in technical textile weaving creates supply chain risk. Distribution runs through merchant showrooms and direct-to-installer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's window covering market functions as a regulatory compounder where Building Code H1 amendments continuously escalate baseline performance requirements and redirect capital flows toward compliant suppliers.
For Market Incumbents: Extend motorized system portfolios into battery-powered retrofit architectures to capture heritage building demand where electrical penetration faces restrictions. Deepen backward integration into technical fabric sourcing to mitigate Australasian weaving capacity constraints. Certification investment in Passive House-aligned cellular shades defends positioning against emerging low-cost Asian entrants.
For New Entrants and Emerging Players: Launch via direct-to-installer digital platforms with embedded compliance checking against Auckland and Wellington council databases to bypass incumbent merchant relationships. Target Wellington's seismic strengthening pipeline for bundled glazing-shading specification opportunities. Hamilton's rental housing market offers the most penetrable volume segment for Healthy Homes Standards-compliant vinyl vertical blinds.
For Investors and Strategic Acquirers: Asymmetric upside sits with project-capable commercial contractors possessing Wellington government tenancy relationships and Building Code interpretation expertise. Long-term viability favors specialists with in-house installation workforce development and API-accessible product data infrastructure. Watch Auckland consenting velocity as the primary inflection indicator for motorized system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Textiles | Captive fabric supply mitigates Australasian weaving capacity constraints and freight volatility. |
| Battery-Powered Motorized System Launch | Retrofit-enabled architecture unlocks heritage building demand without electrical penetration. |
| Direct-to-Installer Platform Development | API-accessible product data captures Auckland volume builder procurement centralization. |
| Passive House Certification Investment | Airtightness-compliant cellular shades command premium positioning in high-performance residential. |
| Wellington Commercial Retrofit Partnership | Seismic strengthening bundling creates integrated glazing-shading specification control. |
Research Methodology
Multiple input streams — primary interviews with window covering manufacturers, merchant distributors, and quantity surveyors; secondary validation through Building Code compliance databases and territorial authority consent records; and customs data on aluminum extrusion and technical textile imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured specification authority shifts across Auckland's volume builder segment, Wellington's government tenancy managers, and Christchurch heritage renovation contractors. Secondary sources included Ministry of Business, Innovation and Employment regulatory filings, local council consenting statistics, and industry association membership directories.
Data-stream reconciliation across product type, material grade, end-user application, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from reconciling historical consenting volumes with retrofit replacement cycle assumptions and regulatory amendment implementation timelines. Forecast inputs incorporated Auckland construction pipeline trajectories, Healthy Homes Standards enforcement velocity, and battery technology cost curves for motorized system penetration modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged territorial authority consenting delays or accelerated Building Code H1 amendments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Hearth Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
India Sustainable Home Decor Market