
 Italy Furniture Retail Market | 2026-2036
Italy Furniture Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Furniture Retail Market Foresight
Tuscan upholstery workshops and Brianza casegoods manufacturers are broadening output capacity to serve premium residential and hospitality channels. Natuzzi anchors its competitive stance through integrated leather tanning and frame production in Puglia. Poltrona Frau leverages heritage craftsmanship to dominate the luxury seating segment. Flexform sustains its position via minimalist design systems that appeal to Milan's architect-specifier community.
Italy furniture retail encompasses the domestic sale of finished household and commercial furnishings through branded showrooms, multi-brand stores, and digital platforms, with products typically specified by dimensions, material composition, and finish grade for interior fit-out purposes. Sofas and chairs command the largest revenue share due to shorter replacement cycles and higher unit values in design-conscious households. The hospitality customer type represents the fastest-expanding demand pool as hotel groups renovate properties across Rome, Florence, and Venice. Online distribution channels are gaining traction among mid-range buyers, though showrooms retain margin dominance in luxury tiers where tactile material validation drives purchase decisions.
Italy's national standardization body UNI, the EU Ecodesign framework, and REACH chemical compliance requirements collectively shape product specifications, material sourcing protocols, and market access conditions for domestic and imported furnishings. The EU Deforestation Regulation imposes traceability obligations on wood-based products that retailers must verify through supply chain documentation. Stakeholders should monitor how digital product passport mandates alter inventory management and supplier qualification processes.
Market Dynamics
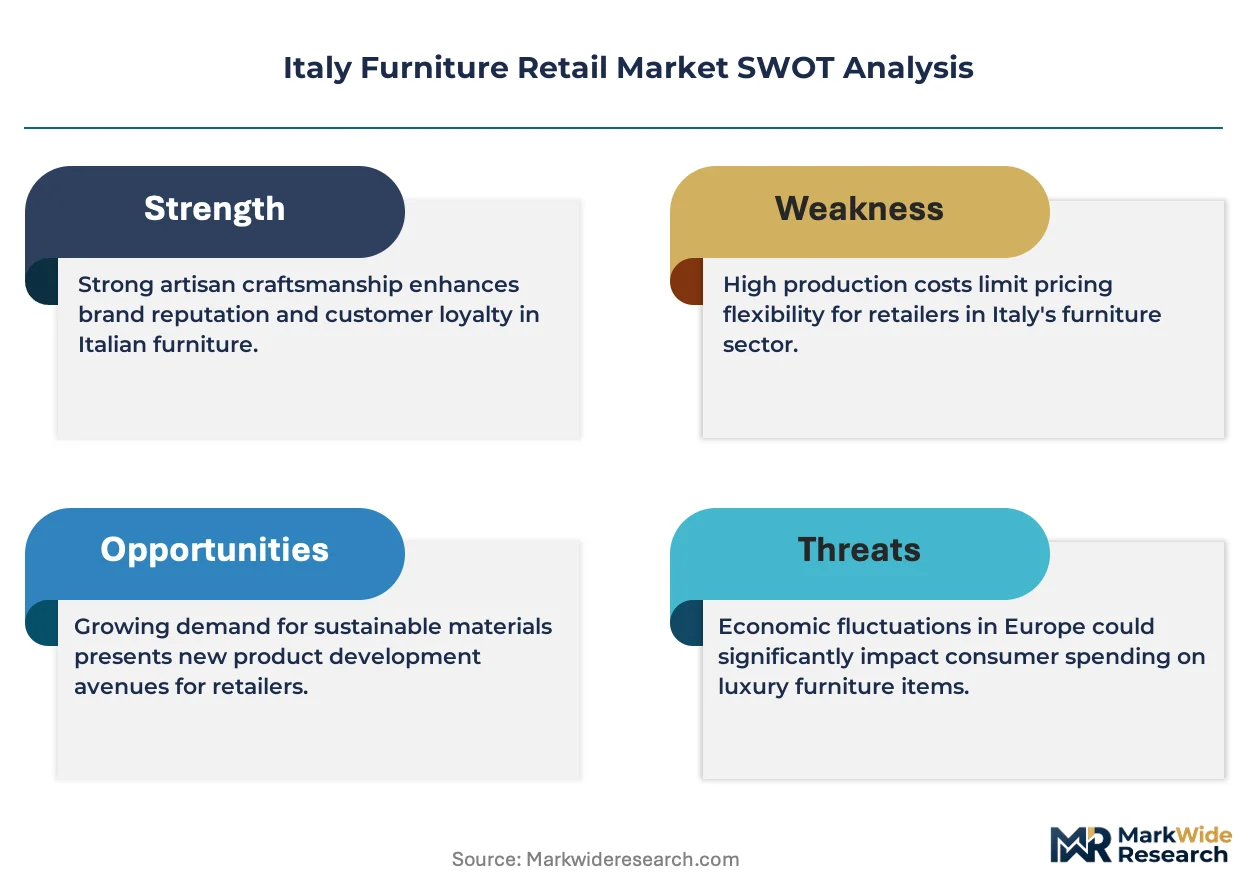
Italy's furniture retail sector confronts a structural squeeze between the EU Ecodesign for Sustainable Products Regulation and the artisanal production traditions concentrated in Brianza and Tuscany. Manufacturers must reconcile heritage craftsmanship with mandated recycled content thresholds and digital product passport traceability.
Growth Catalysts
- EU Deforestation Regulation:Wood-based product traceability requirements favor established Italian manufacturers with documented supply chains over opportunistic importers. Certified origin documentation becomes a competitive moat.
- Hospitality renovation cycle:Hotel groups across Rome, Florence, and Venice are replacing furnishings at accelerated intervals, creating sustained demand for contract-grade upholstery and casegoods.
- Modular living systems:Milan and Rome residential buyers favor reconfigurable seating and storage units that adapt to shrinking urban floorplates, driving specification of transformable furniture platforms.
Market Restraints
- Leather input cost volatility:Tannery capacity concentration in Puglia and Veneto exposes upholstery manufacturers to hide price swings and environmental compliance surcharges.
- Artisan labor scarcity:Brianza's specialized frame-making and hand-finishing skills face generational attrition, constraining output expansion for premium casegoods.
- REACH chemical restrictions:Low-VOC finish mandates eliminate conventional solvent-based coatings, forcing reformulation investments that compress margins for mid-tier producers.
Strategic Opportunities
- Southern Italy underpenetration:Naples and Bari retail corridors lack flagship showroom density, presenting first-mover positioning for brands with logistics infrastructure.
- Digital product passport readiness:Early compliance with incoming EU digital product passport mandates creates supplier qualification advantages for inventory management system investments.
- Contract hospitality specification:Architect-specifier networks in Milan's design district offer channel leverage for hotel group procurement consolidation.
Industry Challenges
- Certification timeline compression:UNI and EU Ecodesign alignment requires simultaneous testing for recycled content verification and chemical emissions, stretching quality assurance bandwidth.
- Legacy showroom inventory reconciliation:Tactile purchase validation in luxury tiers resists full digital migration, forcing parallel physical and virtual asset maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Furniture Retail Market |
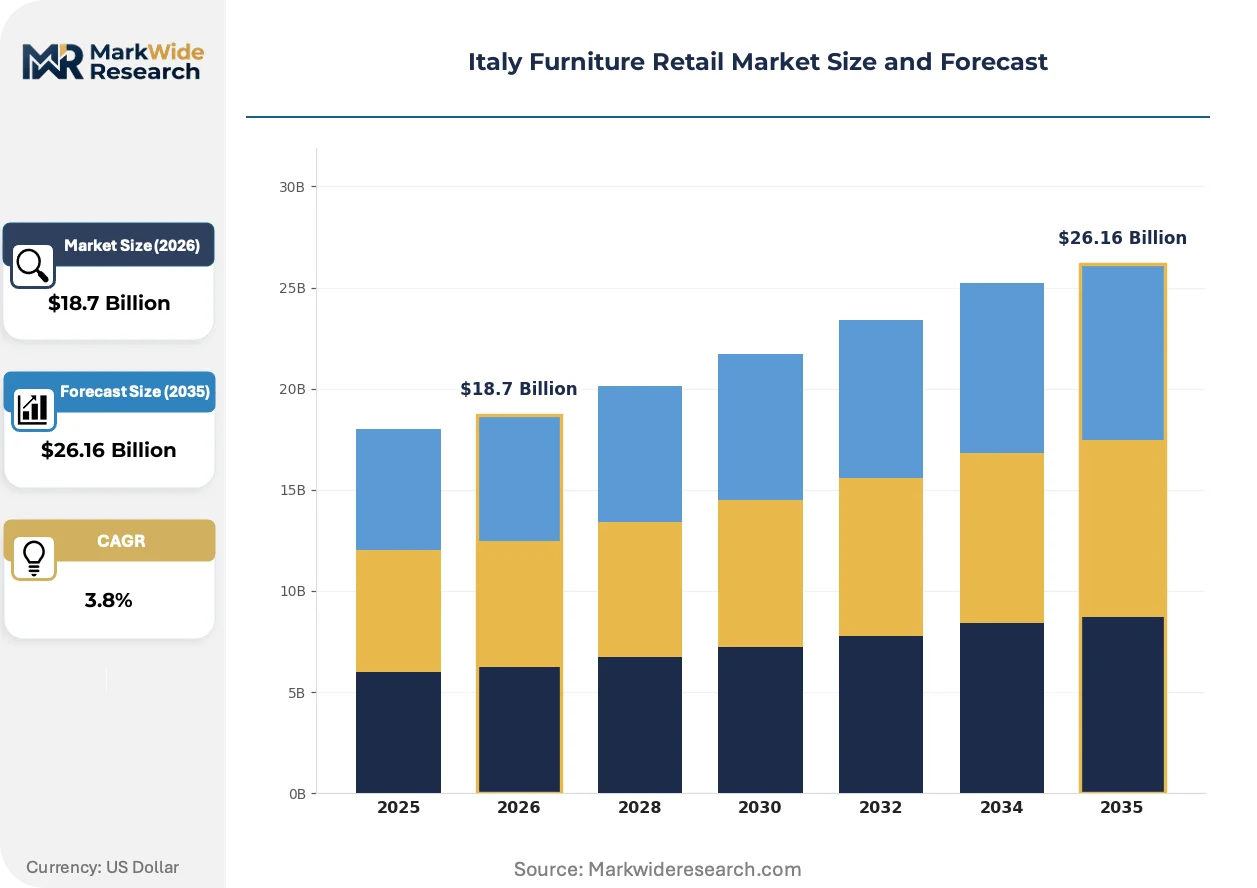
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Customer Type: Residential, Commercial, Hospitality, Institutions Distribution Channel: Online, Showrooms, Retail Stores, Catalogs Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Minotti, Brera Interni, Natuzzi, Viotti, Lovli, Poltrona Frau, Cassina, Flexform, B&B Italia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Furniture Retail Market Shifts & Advancements
Digital specification tools and material traceability systems are compressing traditional design-to-delivery timelines while elevating transparency expectations among architect-specifier networks. Three developments warrant particular attention.
CNC-machined solid surface materials are consolidating bespoke furniture production by enabling mass-customization of dimensions and edge profiles from standardized substrate stock. Milan-based design studios specify these platforms for residential and hospitality fit-outs at expanding scale. The technology is consolidating the historical separation between artisanal one-off production and industrial batch manufacturing into unified fabrication workflows.
EU Ecodesign for Sustainable Products Regulation alignment is mandating recycled wood content thresholds and repairability index disclosures for upholstered products entering the Italian market. Manufacturers must reconfigure supplier qualification protocols to document chain-of-custody certification. The regulation most acutely affects mid-range sofa producers sourcing particleboard frames from Central European suppliers.
Architect-specifier procurement is migrating toward centralized digital platforms that aggregate finish samples, technical specifications, and carbon footprint data for project documentation. Milan's design district practices are displacing fragmented showroom visits with integrated specification software. Hospitality developers in Rome and Venice demonstrate the most rapid adoption of these consolidated procurement interfaces.
Italy Furniture Retail Market Segmentation
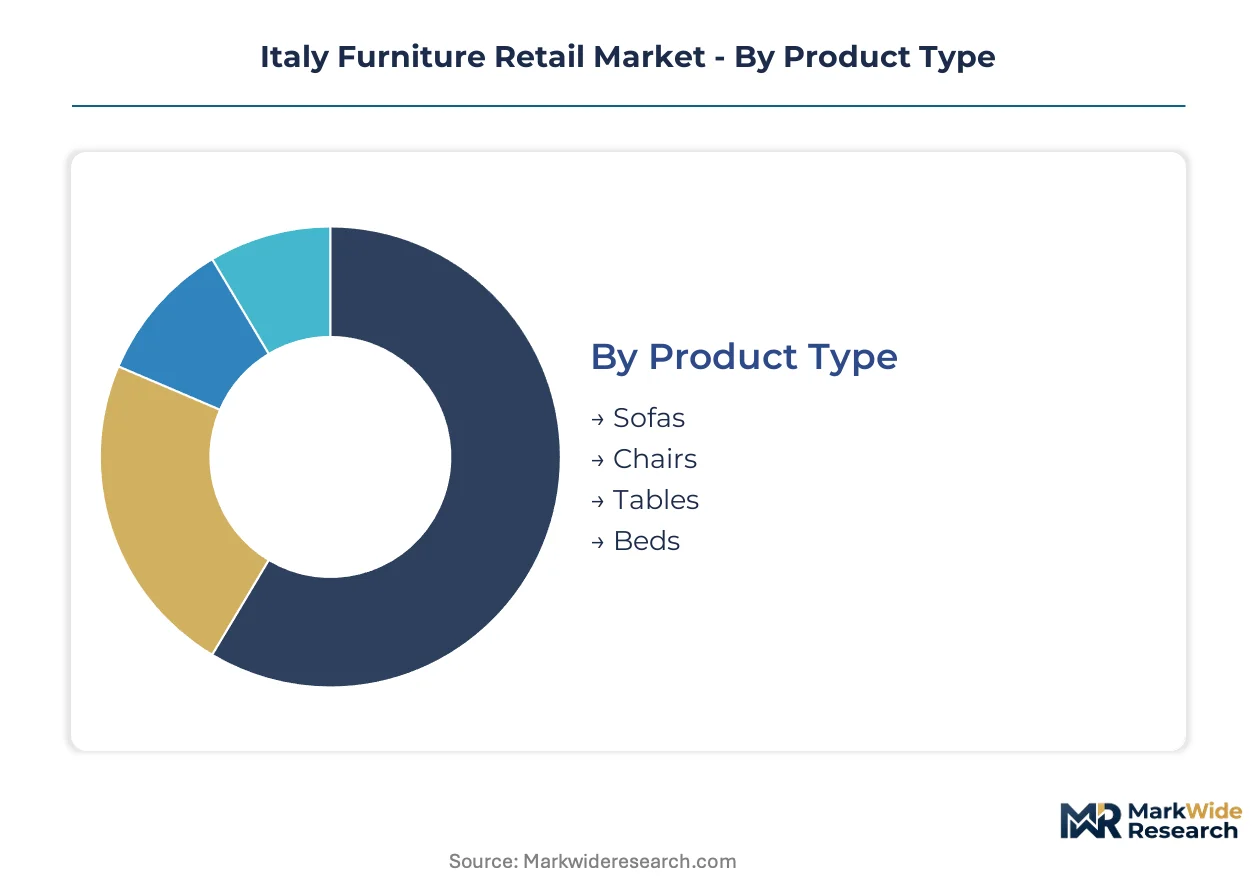
Segmentation in Italy's furniture retail market reveals how regulatory compliance burdens and specification complexity concentrate differently across product categories and buyer profiles. Certification requirements from UNI, REACH, and the EU Deforestation Regulation create asymmetric cost structures that reshape competitive positioning within each segment cluster.
Product Type:
REACH chemical compliance and EU Ecodesign recycled content thresholds impose divergent testing burdens across furniture categories, with upholstered items facing the most intensive certification protocols.
- Sofas:Multi-component assemblies combining frames, cushioning, and textile or leather coverings trigger comprehensive VOC emissions testing and repairability index documentation. Hospitality developers in Rome and Venice specify contract-grade platforms with fire-retardant certifications and modular reconfiguration capabilities for rapid room turnover cycles.
- Chairs:Seating platforms span dining, office, and accent applications with varying structural load requirements and finish durability standards. Milan's architect-specifier community drives demand for ergonomic task seating with carbon footprint disclosures for corporate fit-out projects.
- Tables:Surface and leg assemblies require documented wood origin traceability under EU Deforestation Regulation mandates.
- Beds:Mattress and frame combinations face distinct flammability and dimensional standardization protocols.
Leading the category by volume: Sofas. Growing fastest: Chairs.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with hospitality and institutional purchasers commanding dedicated specification teams while residential buyers rely on showroom validation.
- Residential:Individual households in Milan and Rome prioritize tactile material assessment and dimensional customization for urban apartments with constrained floorplates. Brianza manufacturers direct flagship showroom investments toward this segment where purchase cycles align with property renovation timelines and design-conscious consumers accept extended delivery horizons for bespoke finishes.
- Commercial:Corporate office fit-outs demand bulk procurement with standardized specifications and compressed installation schedules. Turin-based furniture distributors maintain inventory positions for rapid deployment to regional headquarters and co-working operators.
- Hospitality:Hotel groups across Florence, Venice, and Rome accelerate furniture replacement cycles to maintain brand positioning, creating sustained demand for contract-grade durability testing and coordinated logistics for multi-property rollouts.
- Institutions:Public sector procurement follows rigid tender protocols with extended qualification timelines and price-weighted evaluation criteria.
Dominating current procurement value: Residential. Expanding most quickly: Hospitality.
Distribution Channel:
Channel economics reflect the tension between tactile validation requirements and operational efficiency pressures, with luxury tiers resisting full digital migration while mid-range segments accelerate platform adoption.
- Showrooms:Flagship retail spaces in Milan's design district and Rome's central corridors enable material sampling and spatial configuration validation for high-value transactions. Poltrona Frau and Flexform anchor competitive positioning through immersive brand environments where architect-specifier relationships convert to project specifications.
- Online:Digital platforms capture mid-range residential buyers seeking standardized dimensions with transparent pricing and accelerated delivery commitments. Catalog and configurators reduce friction for repeat purchasers familiar with brand quality tiers.
- Retail Stores:Multi-brand furniture retailers aggregate competing manufacturer lines for comparative shopping in secondary urban markets.
- Catalogs:Print and digital lookbooks sustain specification relationships with hospitality procurement teams requiring archival documentation.
Commanding margin dominance: Showrooms. Gaining transaction share fastest: Online.
Price Tier:
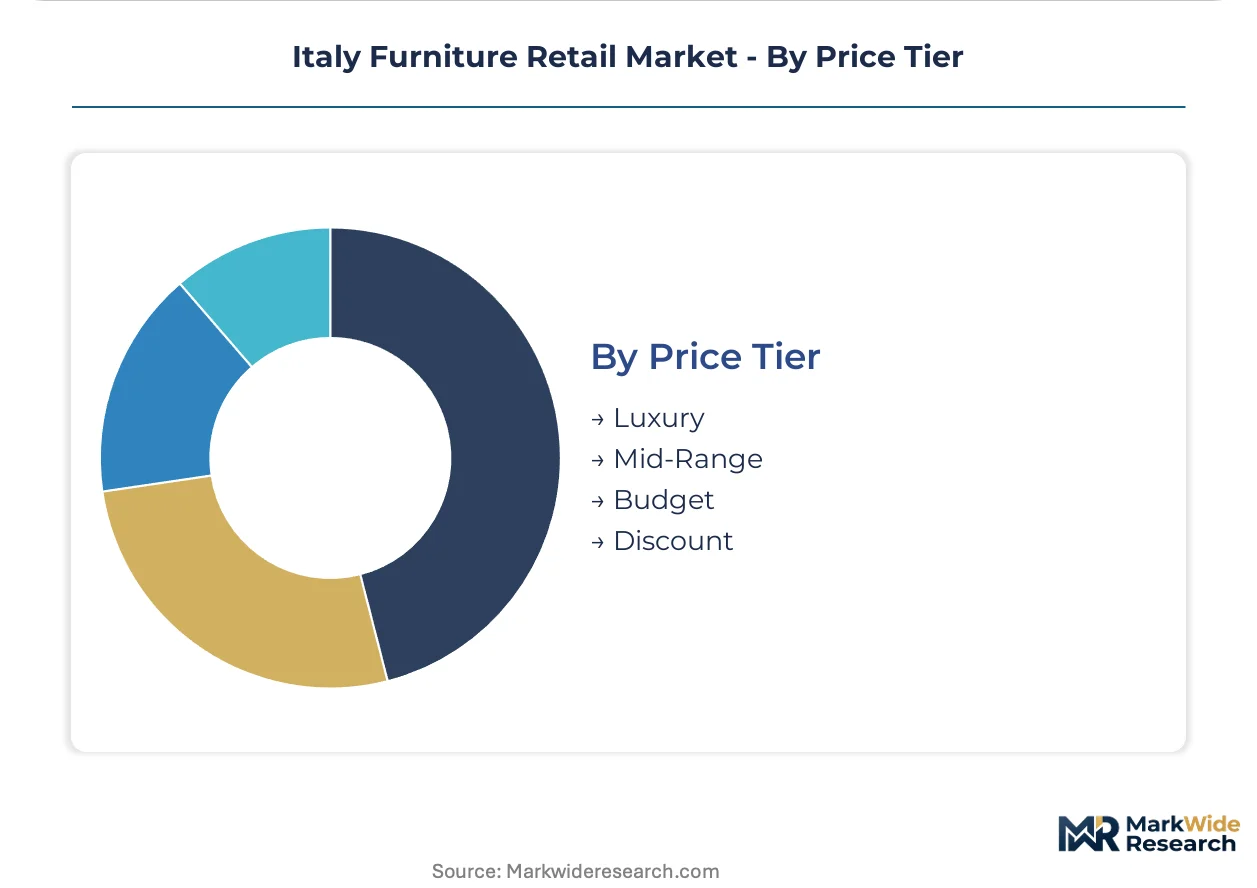
Price stratification aligns with certification intensity and supply chain transparency depth, with luxury tiers absorbing documentation costs that exclude budget competitors from premium specification channels.
- Luxury:Heritage craftsmanship from Tuscan upholstery workshops and Brianza casegoods manufacturers commands substantial premiums through documented provenance and limited production runs. EU Deforestation Regulation chain-of-custody certification and low-VOC finish compliance reinforce exclusivity while satisfying architect-specifier procurement mandates for carbon footprint transparency.
- Mid-Range:Scaled manufacturing from Puglia and Veneto balances specification flexibility with production efficiency for residential and commercial buyers seeking design credibility without artisan pricing.
- Budget:Standardized dimensions and consolidated material specifications serve price-sensitive residential buyers in southern Italy's underpenetrated retail corridors.
- Discount:Inventory liquidation and promotional pricing clear seasonal collections through outlet channels with minimal customization services.
Concentrating revenue contribution: Luxury. Expanding addressable base: Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Puglia's tannery belt and Brianza's machining clusters anchor Italy's furniture production geography, with demand radiating from Milan's design district through Rome's hospitality corridors and into underpenetrated southern markets.
Lombardy
Milan's architect-specifier community drives specification of modular living systems and contract-grade furnishings for corporate and hospitality fit-outs. The region aligns with EU Ecodesign recycled content mandates through documented supply chain partnerships. Brianza's casegoods manufacturers concentrate frame-making and hand-finishing operations in this industrial triangle.
Lazio
Rome's residential buyers favor reconfigurable seating for constrained urban floorplates, accelerating demand for transformable furniture platforms. REACH low-VOC finish requirements shape product availability in this market. The city's hospitality renovation cycle sustains procurement of durable upholstery for hotel properties.
Veneto
Tannery capacity in this region supplies leather inputs to upholstery manufacturers serving premium residential and contract channels. EU Deforestation Regulation traceability obligations concentrate compliance investment among wood-based product fabricators here. Verona and Vicenza host distribution infrastructure connecting artisan production to national retail networks.
Tuscany
Upholstery workshops in Florence and surrounding areas sustain heritage craftsmanship for luxury seating segments. The region's production aligns with UNI standardization protocols for material emissions and durability testing. Artisan clusters face generational labor scarcity that constrains output expansion for bespoke orders.
Puglia
Integrated leather tanning and frame production operations in this southern region feed supply chains for export-oriented manufacturers. Digital product passport readiness investments are beginning to alter inventory management practices among larger producers. Bari's retail corridor remains underpenetrated relative to northern markets, presenting positioning opportunities for brands with logistics infrastructure.
Italy Furniture Retail Market Competitive Landscape
Global majors compete with regional champions across heritage craftsmanship and scaled manufacturing dimensions, producing a tiered structure where luxury artisans coexist with mid-range industrial producers. The vendor base separates into three strategic archetypes: vertically integrated heritage houses controlling tanning-to-retail operations, design-forward studios leveraging architect-specifier relationships, and scaled manufacturers serving contract hospitality channels. Competitive moves concentrate on digital product passport compliance investments and southern Italy retail expansion.
Among heritage-anchored producers, Natuzzi S.p.A. and Poltrona Frau S.p.A. exemplify the vertically integrated archetype, while Flexform S.p.A. occupies a position within the design-studio tier. These entities represent distinct competitive vectors: integrated material control versus specification-network leverage. Minotti S.p.A. and Cassina S.p.A. sit within the luxury craftsmanship cluster, anchoring regional production geography against scaled competitors.
| Leading Market Players |
|---|
| Minotti |
| Brera Interni |
| Natuzzi |
| Viotti |
| Lovli |
| Poltrona Frau |
| Cassina |
| Flexform |
| B&B Italia |
| Others |
Supply & Pricing Matrix
EU Ecodesign recycled content mandates and digital product passport requirements are forcing mid-tier manufacturers toward certified material sourcing that inflates input costs and compresses margins. This specification-driven cost pressure stratifies pricing power between heritage houses with captive supply chains and assemblers exposed to spot-market volatility.
Pricing Analysis
Warranty and white-glove delivery bundling separates luxury positioning from unbundled mid-range transactions where buyers absorb separate logistics costs. Three-tier pricing structure across premium, artisan, and industrial levels reflects certification depth and provenance documentation. Price differentiation hinges on REACH compliance tier and chain-of-custody certification status. Cost compression in mid-range upholstery is intensifying because tannery environmental surcharges and reformulated finish investments transfer downstream. Budget-tier residential buyers in southern Italy exhibit highest price sensitivity, while hospitality procurement teams prioritize durability testing and coordinated logistics over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Milan architect-specifiers and Rome hotel groups mandate multi-supplier qualification that fragments order concentration and elevates vendor management overhead. Production gravity centers on Italy's Brianza machining cluster, Puglia's integrated tanning operations, and Veneto's leather finishing belt. Raw material dependencies encompass hides from South American suppliers, certified recycled wood particleboard from Central European fabricators, and low-VOC coating systems from German chemical specialists. Single-source vulnerability concentrates in Puglia's tannery belt where environmental compliance investments have thinned supplier ranks. Distribution runs through flagship showrooms in Milan's design district, multi-brand retailers in secondary urban markets, and direct digital platforms for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's furniture retail sector is transitioning from artisan-led specification toward digitally intermediated procurement where CNC-machined solid surface platforms displace traditional hand-finishing for volume segments. This technology substitution rewards early compliance investments and inventory system modernization.
For Market Incumbents: Lock in architect-specifier relationships through digital product passport readiness and immersive showroom experiences that validate material provenance. Consolidate frame-making capacity in Brianza against generational labor attrition threatening output expansion. Prioritize backward integration into certified recycled wood supply to deflect EU Deforestation Regulation documentation burdens toward competitors.
For New Entrants and Emerging Players: Capture underpenetrated retail corridors in Bari and Naples where flagship showroom density lags northern markets. Target mid-range hospitality procurement teams seeking contract-grade durability without heritage pricing premiums. Deploy digital-first specification tools with transparent carbon footprint disclosures to bypass incumbent showroom investments.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated heritage houses with tanning-to-retail operations and documented supply chain transparency. Long-term viability hinges on digital product passport compliance infrastructure and southern Italy logistics positioning. Monitor EU Ecodesign enforcement intensity as the inflection indicator separating compliant suppliers from margin-compressed assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Compliance | Creates supplier qualification moat under incoming EU Ecodesign mandates for Milan architect-specifiers. |
| Southern Italy Showroom Expansion | Establishes first-mover positioning in underpenetrated Bari and Naples retail corridors ahead of competitor entry. |
| Backward Integration into Tanning | Secures hide supply and environmental compliance control against Puglia capacity concentration risks. |
| CNC Solid Surface Platform Investment | Consolidates bespoke and batch production workflows for hospitality developers seeking mass customization. |
| Hospitality Procurement Consolidation | Captures Rome and Venice hotel renovation cycles through architect-specifier network leverage. |
Research Methodology
Multi-period observation of REACH compliance adoption rates, hospitality renovation permit filings, and digital platform transaction volumes anchored the trend analysis, supplemented by interviews with Brianza casegoods manufacturers, Tuscan upholstery workshop owners, Milan architect-specifiers, Rome hotel procurement directors, and Puglia tannery operators. Secondary validation drew from UNI standardization protocols, EU Ecodesign regulatory filings, Italian customs trade data, and hospitality industry association membership directories. Bottom-up segment sizing triangulated against top-down market value estimates derived from regional production cluster output assessments.
Input-output matrices modeled demand drivers across product type, customer category, distribution channel, and price tier dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical shipment data against macroeconomic indicators and regulatory implementation timelines. Forecast inputs incorporated EU Deforestation Regulation compliance cost trajectories and generational labor attrition rates in artisan clusters.
The model holds under stable regulatory enforcement intensity and continued hospitality capital expenditure commitment; deviation in EU Ecodesign timeline acceleration or leather input cost volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Upholstered Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Italy Furniture Market
Furniture
Europe Outdoor Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Armchair on Casters Market
Furniture
Russia Home Furniture Market
Furniture
Exam Tables Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Wooden Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Armchairs with Footrest Market
Furniture
India Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
North America School Furniture Market
Furniture
Plastic Furniture Market