
 North America Fiberglass Doors Market | 2026-2036
North America Fiberglass Doors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fiberglass Doors Market Insights
Residential renovation activity is decoupling from commercial construction cycles as the dominant demand driver for fiberglass door volumes. Pella Corporation leverages its vertically integrated manufacturing network across the Midwest to sustain consistent lead times for custom entry configurations. Masonite International Corporation anchors its competitive stance through specialized distribution partnerships with national home improvement retailers. Therma-Tru Corporation dominates the premium replacement segment with proprietary compression-molded skin technology that differentiates surface texture fidelity from commodity alternatives.
North America fiberglass doors consist of reinforced thermoset polymer skins bonded to insulating foam cores, typically manufactured through compression molding or pultrusion processes to achieve dimensional stability across temperature extremes between minus forty and one hundred twenty degrees Fahrenheit. The product category serves primarily as a weather-resistant, thermally efficient barrier for building envelopes, substituting for wood and steel alternatives in climates with high humidity or thermal cycling severity. Entry doors command the largest value share within product type segmentation, though patio and sliding configurations are capturing accelerated specification rates in multifamily and coastal residential applications. Energy efficient feature variants concentrate margin pools through compliance-driven specification in jurisdictions with stringent thermal performance codes, while impact resistant configurations are extending share in Florida and Gulf Coast markets subject to hurricane rating requirements.
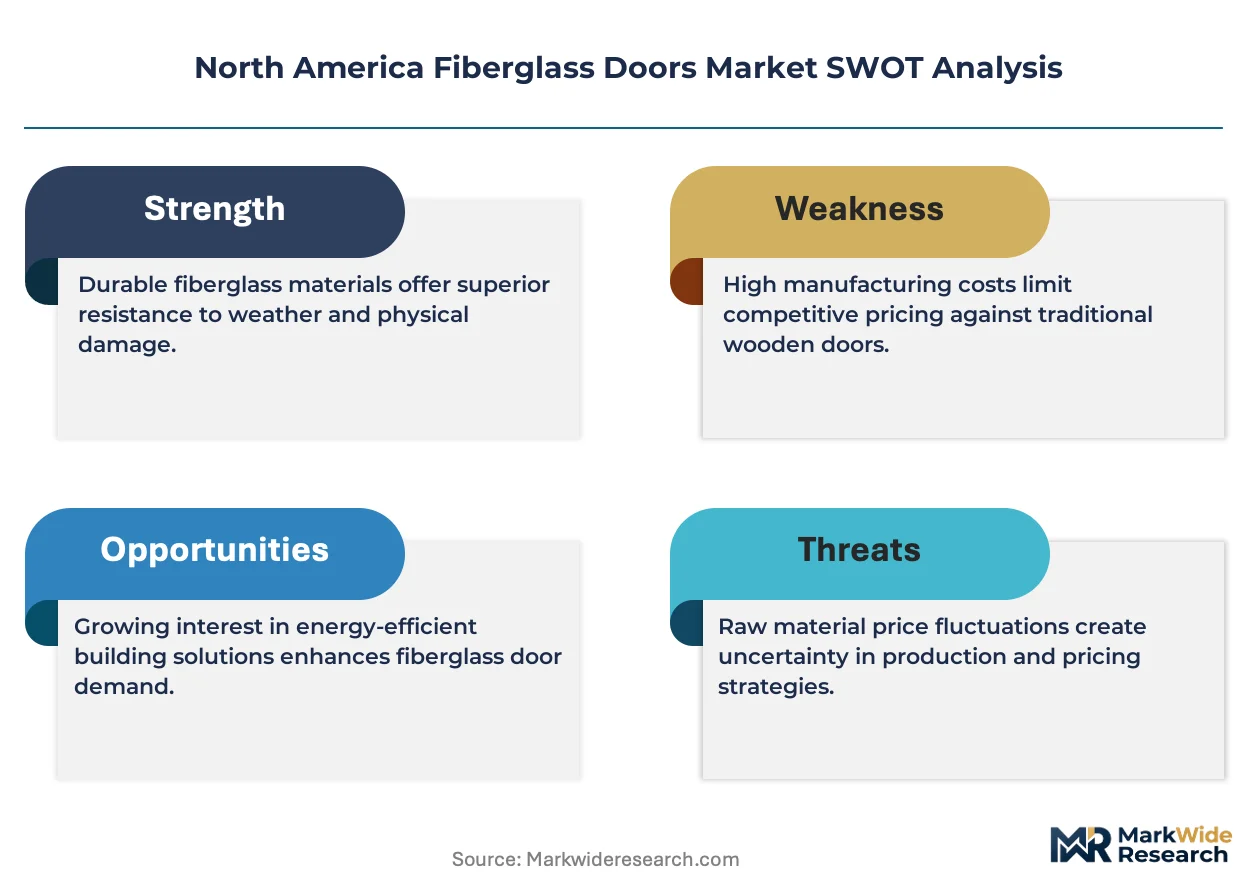
The U.S. Department of Energy enforces thermal transmittance standards through building energy codes that directly shape fiberglass door U-factor specifications in new construction permitting. Health Canada and the Canadian Standards Association coordinate parallel energy performance verification protocols that manufacturers must navigate for cross-border product certification. The National Fenestration Rating Council administers the unified labeling system that both countries recognize for consumer-facing energy performance disclosure. Stakeholders must monitor evolving code harmonization between U.S. state-level amendments and Canadian provincial adoptions to anticipate where certification burden will shift next.
Market Dynamics
Building energy code stringency under U.S. Department of Energy mandates and Canadian National Energy Code for Buildings is compressing specification windows for entry assemblies, forcing material substitution decisions earlier in project timelines.
Growth Catalysts
- Residential new construction velocity:Single-family housing starts in U.S. Sun Belt states and Ontario province are pulling fiberglass door volumes through permit-linked thermal performance thresholds.
- Impact resistance mandates:Florida Building Code hurricane rating requirements are displacing wood and steel alternatives in coastal residential envelopes.
- Renovation cycle acceleration:Aging housing stock replacement demand is decoupling from commercial construction volatility, creating steadier order flow for entry and patio configurations.
Market Restraints
- Petrochemical input volatility:Thermoset resin and glass fiber pricing swings compress margin predictability for compression-molded skin production.
- Regional supply concentration:Midwest manufacturing clusters create logistics cost penalties for Western Canada and Pacific Northwest project deliveries.
- Steel door substitution in commercial:Hollow metal assemblies retain specification share in non-residential retrofit where fire rating and forced entry resistance dominate over thermal performance.
Strategic Opportunities
- Multifamily patio door penetration:Sliding and French door configurations are capturing specification share in Texas and Arizona garden-style apartment construction.
- Inflation Reduction Act efficiency incentives:Federal tax credits for building envelope upgrades are accelerating replacement decisions in 15-year-plus housing stock.
- Smart lock integration:Pre-machined fiberglass door slabs with factory-installed connectivity hardware are converging with residential security system distribution channels.
Industry Challenges
- Skilled installation labor scarcity:Proper foam-core door installation demands trained crews; contractor capacity constraints extend project completion timelines.
- Cross-border certification burden:Dual U.S. NFRC and Canadian CSA verification requirements add testing cost and timeline risk for product line rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fiberglass Doors Market |
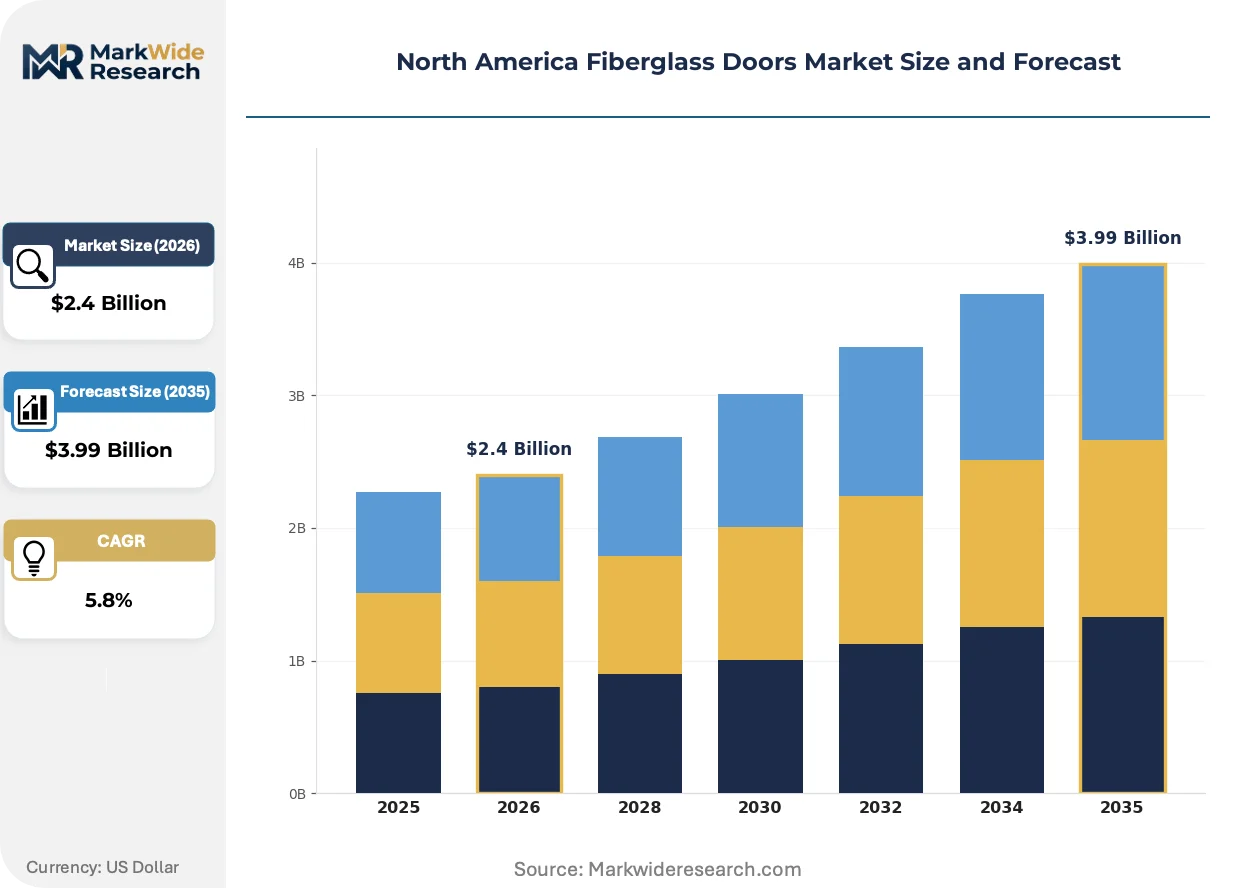
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry Doors, Patio Doors, French Doors, Sliding Doors Application: Residential, Commercial, Industrial, Institutional Style: Modern, Traditional, Rustic, Contemporary Feature: Energy Efficient, Impact Resistant, Low Maintenance, Customizable |
| Companies Covered | Pella Corporation, Milgard Manufacturing LLC, Masonite International Corporation, Kohltech International Limited, Fibertec Window and Door Manufacturing Inc., Jeld-Wen Holding Inc., ProVia LLC, Steves and Sons Inc., Therma-Tru Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fiberglass Doors Market Trends and Innovations
Material science advances and regulatory disclosure requirements are compressing product development cycles while expanding performance verification obligations across the value chain.
Compression-molded fiberglass skin technology is converging with pultruded frame components to create unified thermal breaks that exceed NFRC U-factor thresholds without metal reinforcement. High-volume residential builders in Arizona and Nevada are specifying these assemblies for ENERGY STAR compliance at scale. The convergence is compressing price premiums against commodity fiberglass alternatives while extending performance differentiation from vinyl and steel entry systems.
U.S. Department of Energy building energy code amendments are mandating progressively lower U-factors for climate zones 3 through 7, forcing manufacturers to reformulate core densities and edge-seal technologies. State-level adoption timelines vary, with California Title 24 and Washington State energy codes running ahead of federal minimums. The regulatory patchwork is fragmenting product portfolios and concentrating certification investment in jurisdictions with earliest enforcement dates.
Builder procurement is consolidating around pre-hung door packages with integrated hardware and smart home pre-wiring, displacing traditional component sourcing through lumberyard channels. National production homebuilders in Texas and Florida are driving this specification bundling to compress site labor hours and warranty exposure. The shift is most visible in Sun Belt metropolitan statistical areas where production pace and labor cost pressure intersect most acutely.
North America Fiberglass Doors Market Segmentation
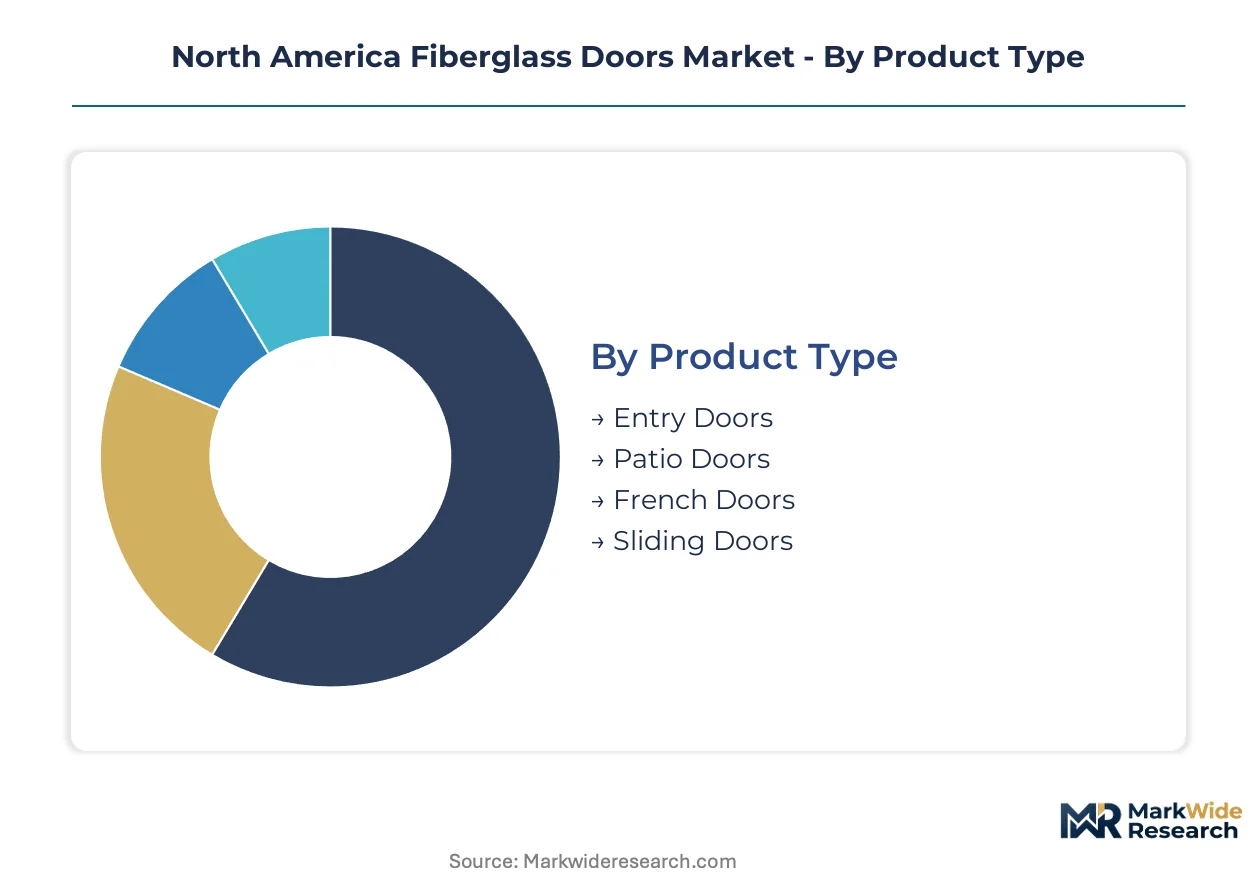
Segmentation in the North America fiberglass doors market reveals how capital deployment, code compliance, and installation labor requirements fragment addressable demand across distinct specification clusters. Manufacturers must align production assets with the thermal performance thresholds and aesthetic requirements that dominate each segment.
Product Type:
Compression molding lines for entry door skins demand the highest upfront tooling investment, while pultruded frame extrusion requires continuous capital for die maintenance and resin formulation.
- Entry Doors:These assemblies combine compression-molded fiberglass skins with polyurethane foam cores to achieve NFRC-certified U-factors below 0.25 in climate zones 5-7. Demand concentrates in Ontario province and U.S. Sun Belt states where energy code amendments are forcing specification upgrades from steel and wood alternatives.
- Patio Doors:Multi-panel sliding and swinging configurations integrate pultruded frames with thermal break technology for expansive glazing openings. Texas and Arizona garden-style apartment construction is pulling volumes as multifamily developers seek ENERGY STAR compliance without aluminum thermal bridging.
- French Doors:Hinged double-door assemblies with divided lite patterns serve traditional residential renovation projects.
- Sliding Doors:Horizontal track systems dominate coastal Florida applications where impact-resistant laminated glass integration is mandatory.
Entry doors absorb the bulk of installed capacity; patio doors are expanding most quickly.
Application:
Commercial specifications prioritize fire ratings and forced entry resistance over thermal performance, redirecting fiberglass demand toward residential and institutional segments where U-factor compliance dominates.
- Residential:Single-family new construction and renovation activity in Sun Belt metropolitan statistical areas drives specification of pre-hung entry assemblies with smart lock pre-machining. The Inflation Reduction Act's envelope upgrade tax credits are accelerating replacement cycles in 15-year-plus housing stock across the U.S. Midwest and Ontario.
- Commercial:Retail and office retrofit projects rarely specify fiberglass due to hollow metal fire door requirements; limited penetration occurs in climate-controlled warehouse facilities.
- Industrial:Food processing and pharmaceutical facilities specify fiberglass for corrosion resistance in high-humidity washdown environments.
- Institutional:Schools and healthcare facilities in California and Washington State specify energy-efficient entry systems to meet Title 24 and state energy code mandates.
Residential applications command the dominant share of manufacturing throughput; institutional specifications are climbing the fastest as public sector procurement integrates life-cycle cost analysis.
Style:
Tooling amortization varies dramatically by style category, with traditional panel configurations requiring extensive mold cavity investment while contemporary flat-slab designs minimize capital recovery timelines.
- Modern:Clean-lined slab doors with minimal surface texture and large lite openings align with production homebuilder specifications in Nevada and Arizona. These configurations leverage simplified compression molds and integrate readily with smart home pre-wiring bundles.
- Traditional:Raised panel and Craftsman-style embossing patterns dominate Midwest renovation markets.
- Rustic:Distressed wood-grain textures and wrought iron grille patterns serve mountain resort construction in Colorado and Utah.
- Contemporary:Asymmetrical lite placements and bold color finishes capture custom home specifications in California coastal markets.
Traditional styling retains the largest installed base; modern configurations are gaining specification share fastest among national production builders.
Feature:
Certification testing costs create tiered capital barriers, with impact-resistant and energy-efficient variants requiring extensive third-party verification that commodity customizable offerings avoid.
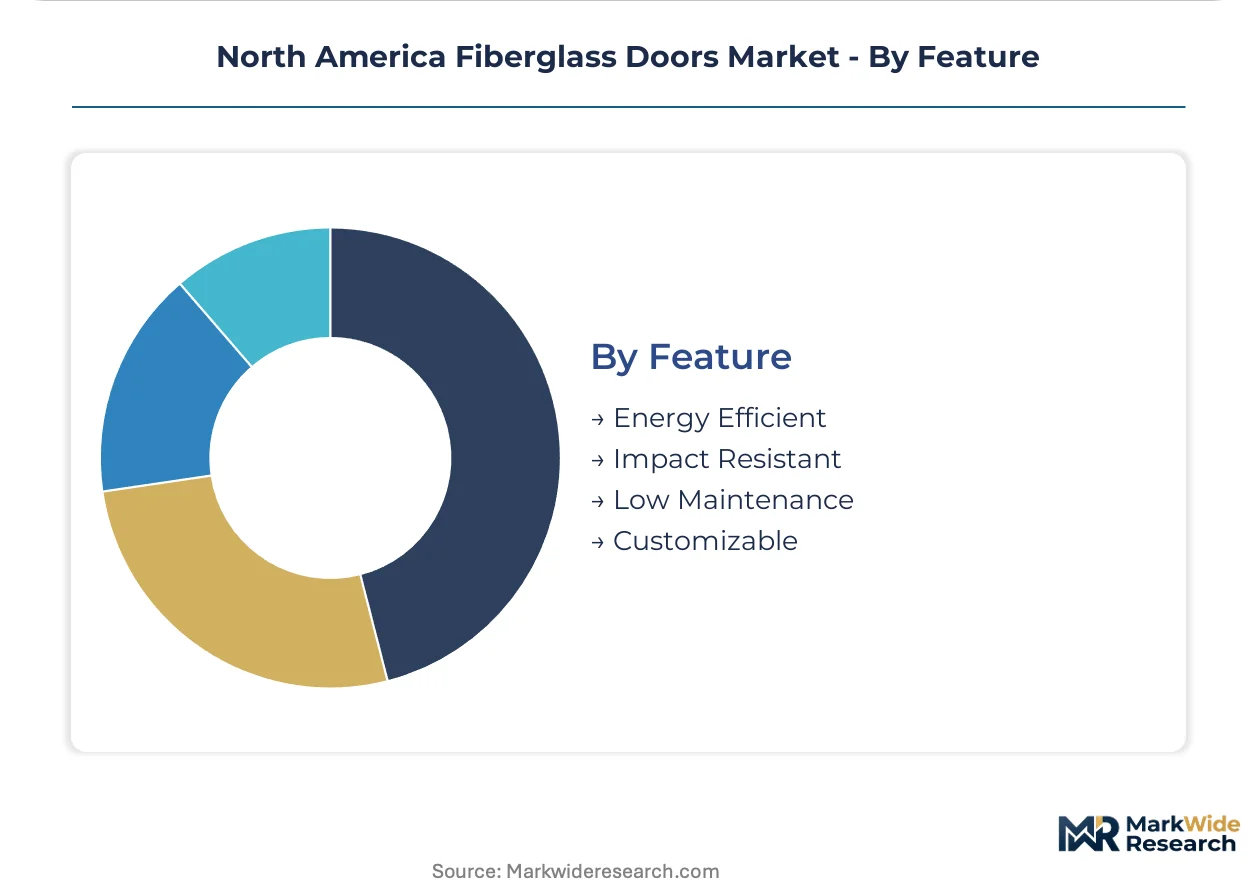
- Energy Efficient:Foam-core densities and warm-edge spacer systems are engineered to exceed NFRC U-factor thresholds for climate zones 3-7. Washington State and California code adoptions are forcing these specifications into base product configurations rather than premium upgrades.
- Impact Resistant:Laminated glass integration and reinforced frame anchors meet Florida Building Code hurricane ratings. Gulf Coast residential permitting requires these assemblies for all new construction within designated wind-borne debris regions.
- Low Maintenance:UV-stable gel coat finishes eliminate refinishing requirements for coastal and high-altitude exposure conditions.
- Customizable:Made-to-order dimension and hardware pre-machining serves architect-driven residential projects.
Energy-efficient features dominate current production allocation; impact-resistant configurations are expanding most rapidly as Florida and Texas coastal construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's residential energy efficiency tax credits are concentrating fiberglass door demand in U.S. jurisdictions with overlapping state-level code acceleration. Canadian provincial adoption of the National Energy Code for Buildings is creating parallel specification pressure in Ontario and British Columbia. Mexico's nearshoring corridor is emerging as a secondary manufacturing node for U.S. border-state distribution.
United States
Single-family housing starts in Texas, Florida, and Arizona are pulling pre-hung fiberglass entry assemblies through permit-linked thermal performance thresholds. The U.S. Department of Energy building energy code amendments for climate zones 3-7 are compressing U-factor specifications below 0.25 in new construction. Midwest manufacturing clusters around Iowa and Wisconsin supply compression-molded skins to Sun Belt metropolitan statistical areas with consistent lead times.
Canada
Ontario province dominates residential new construction volume where the National Energy Code for Buildings mandates NFRC-certified envelope assemblies. Health Canada coordinates CSA verification protocols that manufacturers must complete for cross-border product certification. Toronto and Vancouver construction markets specify energy-efficient entry systems for multifamily and custom residential projects facing stringent thermal bridging requirements.
Mexico
Nuevo León and Baja California manufacturing facilities are capturing contract production for U.S. Southwest distribution networks. Mexican federal energy efficiency standards for residential construction remain less stringent than U.S. equivalents, limiting domestic specification. Monterrey industrial parks host fiberglass pultrusion operations serving Texas and Arizona builder procurement consolidation.
California
Title 24 energy code amendments are forcing ENERGY STAR compliance into base product configurations rather than premium upgrades. California Energy Commission mandates exceed federal U-factor minimums by 15-20% in most climate zones. Los Angeles and San Diego metropolitan statistical areas specify modern slab configurations with smart home pre-wiring for production homebuilder efficiency.
Florida
Florida Building Code hurricane rating requirements are displacing wood and steel alternatives in coastal residential envelopes. Impact-resistant laminated glass integration is mandatory for all new construction within designated wind-borne debris regions. Miami-Dade and Tampa Bay permitting offices process the highest volume of fiberglass door specifications for replacement and new construction activity.
North America Fiberglass Doors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated producers commanding premium replacement channels and OEM suppliers feeding production homebuilder procurement. The market structure concentrates around three tiers: national brand houses with captive distribution, regional fabricators with lumberyard relationships, and private-label assemblers serving big-box retail. Strategic differentiation runs through compression-molded skin fidelity, thermal break engineering, and pre-hung package bundling. Capacity expansion and strategic partnerships represent the dominant competitive moves as lead time reliability becomes a specification filter.
Among vertically integrated specialists, Pella Corporation exemplifies the Midwest production cluster archetype with consistent custom configuration lead times. Masonite International Corporation and Therma-Tru Corporation occupy positions on opposite ends of the premium-commodity spectrum, with the former anchoring big-box distribution partnerships and the latter representing proprietary surface texture differentiation in replacement markets. These three entities collectively illustrate how manufacturing geography and channel specialization fragment competitive positioning across the value chain.
| Leading Market Players |
|---|
| Pella Corporation |
| Milgard Manufacturing LLC |
| Masonite International Corporation |
| Kohltech International Limited |
| Fibertec Window and Door Manufacturing Inc. |
| Jeld-Wen Holding Inc. |
| ProVia LLC |
| Steves and Sons Inc. |
| Therma-Tru Corporation |
| Others |
Pricing and Supply Chain Analysis
Production homebuilder procurement consolidation in Texas and Florida anchors a contract-based pricing model where volume commitments secure preferential thermal performance tier access. Compression-molded skin manufacturers calibrate quotes against resin futures positions and Midwest-to-Sun Belt logistics penalties.
Pricing Analysis
Lead-time premiums compress as spot inventory availability fluctuates with seasonal housing permit velocity. Three-tier pricing structure across premium, standard, and economy levels separates NFRC-certified custom configurations from commodity pre-hung assemblies and private-label big-box offerings. Price differentiation hinges on U-factor certification grade and factory-installed smart hardware pre-machining. Cost compression in standard tiers is intensifying because petrochemical input volatility erodes margin predictability. Renovation contractors exhibit highest price sensitivity; institutional procurement with life-cycle cost mandates shows least.
Supply Chain Analysis
Dual-sourcing requirements from national homebuilders mandate Midwest and Mexico-based supplier qualification for compression-molded skin and pultruded frame components. Manufacturing concentrates in Iowa, Wisconsin, and Nuevo León. Raw material dependencies encompass thermoset polyester resin, E-glass fiber roving, and polyurethane foam cores. Single-source vulnerability in gel coat chemistry creates formulation bottleneck exposure. Distribution runs through lumberyard networks and big-box retail channels to residential contractors and production builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled installation labor scarcity props pricing power for pre-hung package bundling, as contractor capacity constraints extend project timelines and elevate turnkey assembly premiums.
For Market Incumbents: Deepen captive foam-core formulation capabilities to offset resin price volatility exposure. Expand pultrusion capacity in Nuevo León to compress logistics penalties for Southwest distribution. Masonite International Corporation's big-box partnerships demonstrate channel control defensibility against direct-to-builder disintermediation.
For New Entrants and Emerging Players: Capture multifamily patio door specifications in Arizona and Texas garden-style construction where thermal break engineering requirements exceed commodity vinyl capabilities. Target institutional procurement in California and Washington State where Title 24 and state energy code adoptions accelerate ENERGY STAR compliance mandates. Pursue smart lock OEM partnerships for factory-integrated pre-machining differentiation.
For Investors and Strategic Acquirers: The window for entry favors compression-molded skin specialists with NFRC certification infrastructure and Midwest manufacturing footprints. Long-term viability rests on regulatory code harmonization between U.S. state amendments and Canadian provincial adoptions expanding addressable demand. Monitor Florida Building Code amendment timelines as inflection indicator for impact-resistant specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam-Core Formulation | Captive polyurethane density control reduces resin cost pass-through exposure from petrochemical suppliers. |
| Smart Hardware Pre-Machining Certification | Factory-integrated connectivity aligns with residential security system distribution channel consolidation. |
| NFRC-Certified Thermal Break Engineering | Exceeding climate zone 3-7 U-factor thresholds captures Washington State and California code acceleration. |
| Regional Manufacturing Footprint Expansion | Nuevo León pultrusion capacity compresses logistics penalties for Texas and Arizona builder procurement. |
| Impact-Resistant Laminated Glass Partnership | Florida Building Code compliance integration secures coastal residential permitting in wind-borne debris regions. |
Research Methodology
Document review covered U.S. Department of Energy building code amendments, Canadian National Energy Code for Buildings adoption timelines, and National Fenestration Rating Council certification databases, complemented by interviews with plant managers at compression-molding facilities, procurement leads at national production homebuilders, distribution channel partners in lumberyard networks, and regulatory affairs specialists navigating cross-border CSA verification. Secondary validation drew from U.S. Census Bureau housing starts data, Canadian Mortgage and Housing Corporation construction statistics, customs trade records for fiberglass door assemblies, and SEC 10-K filings from publicly traded building products manufacturers. Bottom-up volume estimates from state-level permit data triangulated against top-down market sizing from manufacturer shipment disclosures.
Segmented projections across entry, patio, French, and sliding door configurations incorporate application splits between residential new construction, renovation, and institutional procurement. Modeled dimensions include climate zone regulatory clusters, thermal performance tier penetration, and smart hardware integration rates. CAGRs derive from housing starts elasticity to fiberglass specification share and code amendment enforcement timelines. Key inputs encompass petrochemical resin pricing indices, Midwest-to-Sun Belt freight rate benchmarks, and cross-border certification cost trajectories.
The model holds under steady U.S. Sun Belt housing permit velocity and Canadian Ontario construction growth; deviation in federal energy code amendment delays or prolonged petrochemical price volatility would shift volume and value trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Furnitures Market