
 External Blinds Market | 2026-2036
External Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
External Blinds Market Intelligence
Market Context
The capital-intensity divergence between automated manufacturing platforms and manual assembly operations is redrawing competitive boundaries across the external blinds sector. Hunter Douglas N.V. leverages its integrated supply chain to dominate premium motorized systems across North American and European distribution channels. WAREMA Renkhoff SE sustains engineering leadership through captive R&D facilities in Germany that specialize in climate-responsive facade automation. Griesser AG anchors its position via backward integration into aluminum extrusion and powder-coating processes that reduce third-party dependency.
Technical Definition and Segment Structure
External blinds comprise adjustable shading devices mounted outside building envelopes, typically fabricated from aluminum slats, technical fabrics, or thermoplastic composites with widths ranging from 50mm to 300mm, engineered to manage solar heat gain coefficients and daylight penetration for energy compliance. Roller blinds and venetian blinds occupy the dominant volume positions, with motorized variants commanding margin premiums due to integration with building management systems and IoT-enabled climate algorithms. The residential application segment remains mature across Western European housing stocks, while commercial and hospitality deployments are absorbing advanced UV-resistant and waterproof specifications driven by facade performance warranties.
Regulatory Framework and Outlook
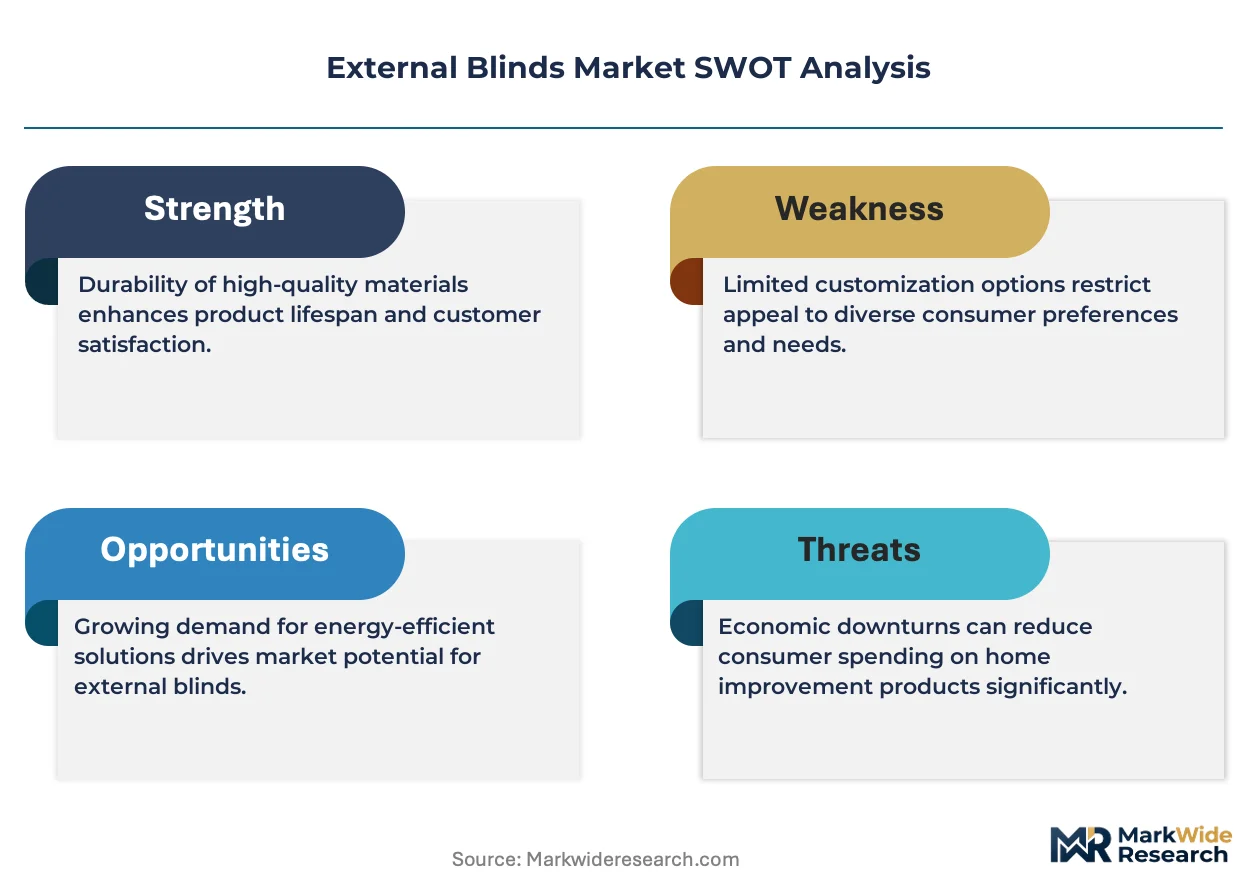
The EU Energy Performance of Buildings Directive and CE marking requirements under the Construction Products Regulation shape product certification pathways and market access conditions for external blind manufacturers serving European jurisdictions. The US EPA Energy Star program and evolving IECC building codes in states including California and New York establish minimum performance thresholds for solar control devices. Stakeholders must monitor the trajectory of national building decarbonization roadmaps and smart building interoperability standards to align R&D portfolios with compliance-driven procurement cycles.
Market Dynamics
The EU Energy Performance of Buildings Directive is compressing installation timelines and forcing procurement officers to specify motorized external blinds with integrated solar tracking algorithms. This regulatory compression is redrawing vendor qualification criteria across commercial retrofit pipelines.
Growth Catalysts
- EPBD solar gain mandates:Member states must deploy automated shading in non-residential buildings exceeding specified energy thresholds, creating specification pull-through for climate-responsive facade systems.
- Aluminum slat manufacturing automation:Robotic extrusion and powder-coating lines are cutting production cycle times for high-performance louvers, enabling faster fulfillment of large-scale commercial contracts.
- Commercial building stock retrofits:Aging office and hospitality assets in Germany, France, and Italy are triggering replacement waves for legacy fixed shading with adjustable motorized alternatives.
Market Restraints
- Aluminum ingot price volatility:Raw material cost swings compress margin predictability for slat fabricators dependent on LME-indexed supply contracts.
- Motor and actuator supply concentration:Sourcing of precision drive mechanisms clusters among specialized electromechanical suppliers in Southern Germany and Northern Italy, creating single-source vulnerability.
- Facade integration complexity:Technical limitations in retrofitting automated blinds onto heritage building envelopes without structural modification restrict addressable building stock.
Strategic Opportunities
- Underpenetrated Nordic residential markets:Sweden, Norway, and Denmark exhibit low motorized external blind penetration relative to solar irradiance levels, presenting first-mover expansion potential for climate-adaptive systems.
- IoT-BMS convergence:Integration of wireless shading controls with building management platforms and predictive weather APIs is opening specification channels for smart building developers.
- Green building certification premiums:LEED and BREEAM point structures for passive solar control are incentivizing architects to specify high-performance external blinds in premium commercial projects.
Industry Challenges
- Facade engineer talent scarcity:Shortages of specialists capable of integrating motorized shading with complex curtain wall systems are extending project design phases and inflating consulting fees.
- CE marking timeline compression:Accelerated Construction Products Regulation certification cycles for fire-rated and wind-load-tested assemblies are straining laboratory capacity and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Blinds Market |
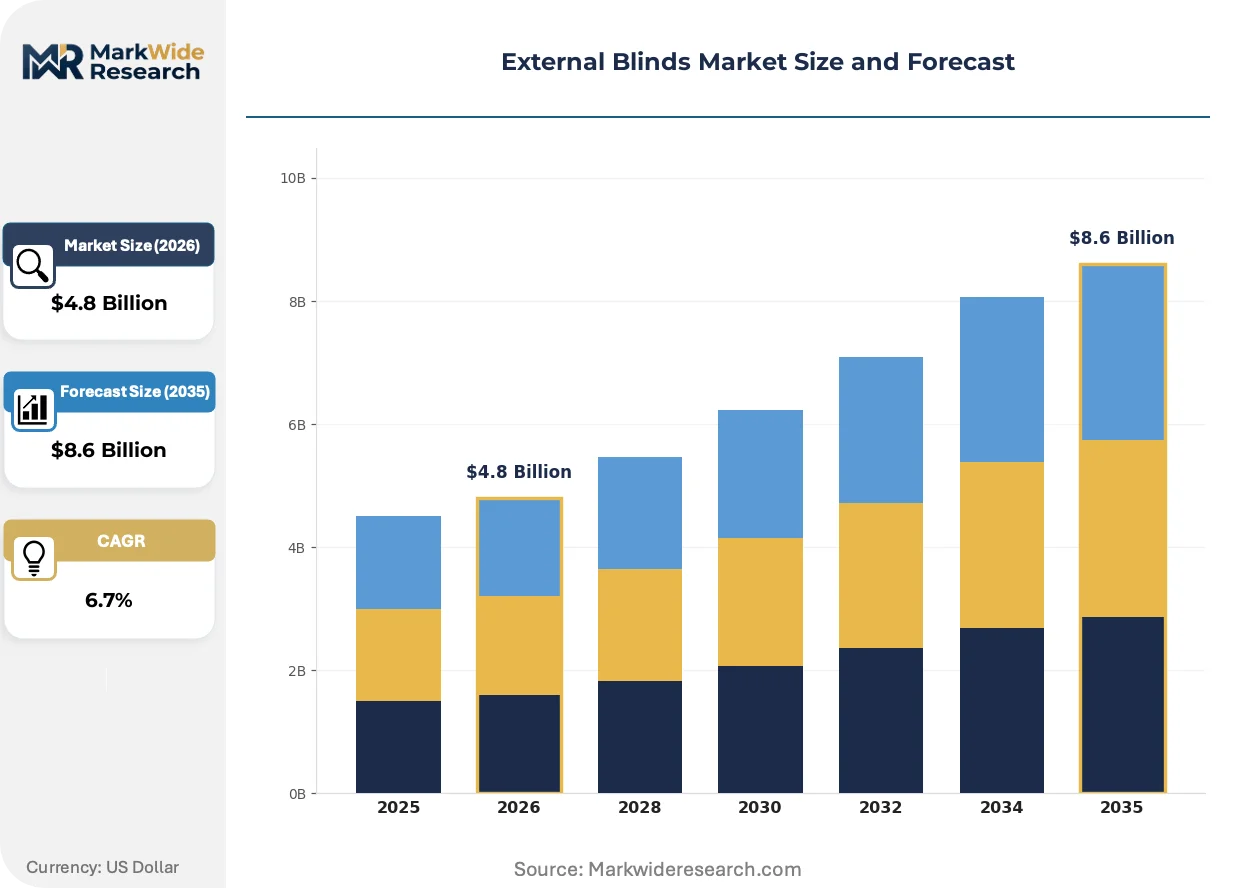
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Blinds, Venetian Blinds, Roman Blinds, Pleated Blinds Material: Aluminum, Fabric, Wood, PVC Application: Residential, Commercial, Hospitality, Industrial Features: Energy Efficient, UV Resistant, Waterproof, Motorized |
| Companies Covered | Griesser AG, Hella Sonnen- Und Wetterschutztechnik GmbH, Hunter Douglas N.V., Brustor NV, Levolux Inc., WAREMA Renkhoff SE, Renson, Winsol NV, Somfy Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Blinds Market Strategic Shifts & Innovations
Connected facade automation is displacing static specification paradigms. Procurement officers now demand shading systems that communicate with HVAC and lighting networks, forcing vendors to reengineer product architectures around interoperability protocols rather than standalone performance.
Photovoltaic-integrated slat systems are supplanting conventional aluminum louvers in premium commercial specifications. These energy-generating blinds capture incident solar radiation while providing shading, enabling building operators to offset facade energy consumption. Developers targeting net-zero certifications in Germany and the Netherlands are specifying these hybrid systems despite 40-60% cost premiums over standard motorized alternatives.
REACH restrictions on chromium VI compounds in surface treatments are compelling powder-coating reformulation across European supply chains. Manufacturers serving EU member states must transition to trivalent chromium or zirconium-based pretreatment chemistries, adding process validation costs and extending qualification timelines for architectural finish warranties. Italian and Spanish coating houses are absorbing the steepest compliance burdens due to legacy hexavalent process dependencies.
Specification authority is migrating from general contractors to facade consultants and energy modelers. These technical intermediaries now control shading selection through whole-building simulation outputs, compressing traditional distributor influence. In France and Belgium, engineering firms with BREEAM assessor credentials are capturing decisive voice in blind procurement for public-sector construction frameworks.
External Blinds Market Segmentation
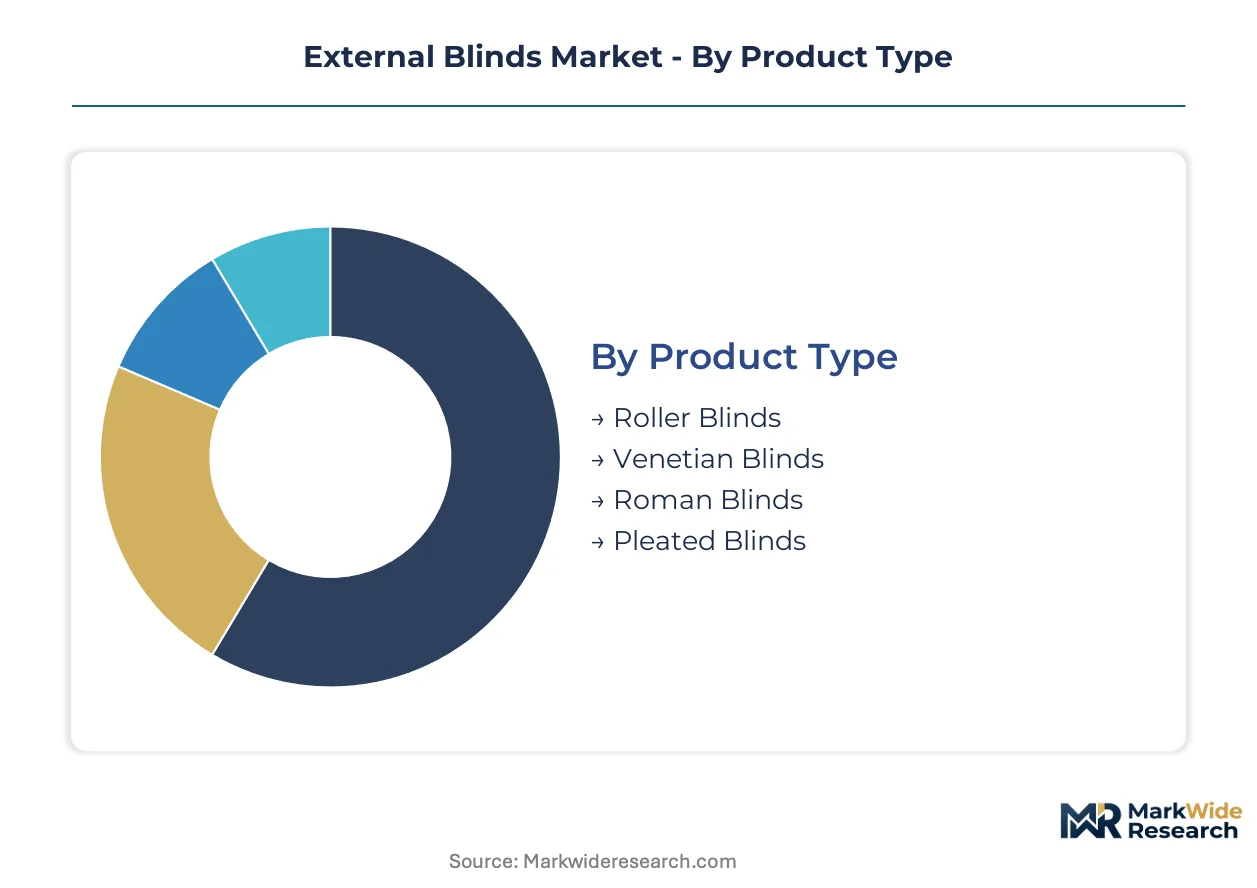
Product architecture in the external blinds sector channels procurement through distinct specification pathways. Architects, facade engineers, and building operators each prioritize different performance attributes, fragmenting demand across material grades, automation levels, and compliance tiers.
Product Type:
Channel flow splits between retrofit distributors favoring standardized formats and facade consultants specifying engineered systems for new construction.
- Roller Blinds:Fabric or aluminum sheets wound onto horizontal drums, typically 80-400mm in diameter, engineered for high-wind-load commercial facades. Demand concentrates in German and French office retrofits where EPBD compliance deadlines are compressing installation schedules.
- Venetian Blinds:Adjustable horizontal slat systems with 50-80mm blade widths, offering precise daylight modulation through motorized tilt control. Hospitality developments in Italy and Spain are specifying these for guest room automation integration.
- Roman Blinds:Fabric panels with horizontal stiffening rods that stack vertically when retracted. Residential channels in Austria and Switzerland favor these for heritage building compatibility.
- Pleated Blinds:Concertina-folded technical fabrics tensioned within frame guides. Skylight and atrium applications in Dutch commercial projects absorb specialized variants with enhanced thermal breaks.
Roller blinds dominate installed base across commercial stock. Venetian blinds are where expansion concentrates for climate-responsive facade upgrades.
Material:
Cost tier stratification separates premium architectural specifications from volume residential replacements.
- Aluminum:Extruded 6060-T66 or 6063-T6 alloys with polyester powder coating, delivering 30-year facade warranties and full recyclability. CE marking under CPR drives procurement in EU public tenders.
- Fabric:PVC-coated polyester or fiberglass composites with 5-10% openness factors for glare control. German and Austrian commercial developers specify these for lightweight retrofit compatibility.
- Wood:Vacuum-pressure-treated hardwoods or modified timber with water-repellent coatings. Premium residential segments in Scandinavia absorb sustainably certified variants.
- PVC:Cellular foam or solid extrusions offering cost-efficient moisture resistance. Volume replacement markets in Southern Europe utilize these for rental housing stock maintenance.
Aluminum commands specification authority in commercial and hospitality channels. Fabric is gaining share fastest for retrofit weight constraints and installation speed.
Application:
Customer type determines automation penetration and warranty complexity.
- Residential:Single-family and multi-unit housing with manual or basic motorized operation. Nordic markets show underpenetration relative to solar exposure levels.
- Commercial:Office, retail, and institutional buildings requiring BMS integration and predictive control algorithms. EPBD mandates in Germany, France, and Italy are accelerating specification.
- Hospitality:Hotels and resorts demanding guest room automation and centralized facility management. Mediterranean coastal developments prioritize corrosion-resistant specifications.
- Industrial:Manufacturing and logistics facilities with large-span facade requirements. Wind-load engineering and rapid-cycle durability differentiate procurement criteria.
Commercial applications anchor revenue concentration. Residential retrofits present the steepest expansion trajectory for climate-adaptive system adoption.
Features:
Margin tier separates compliance-driven base specifications from performance-premium upgrades.
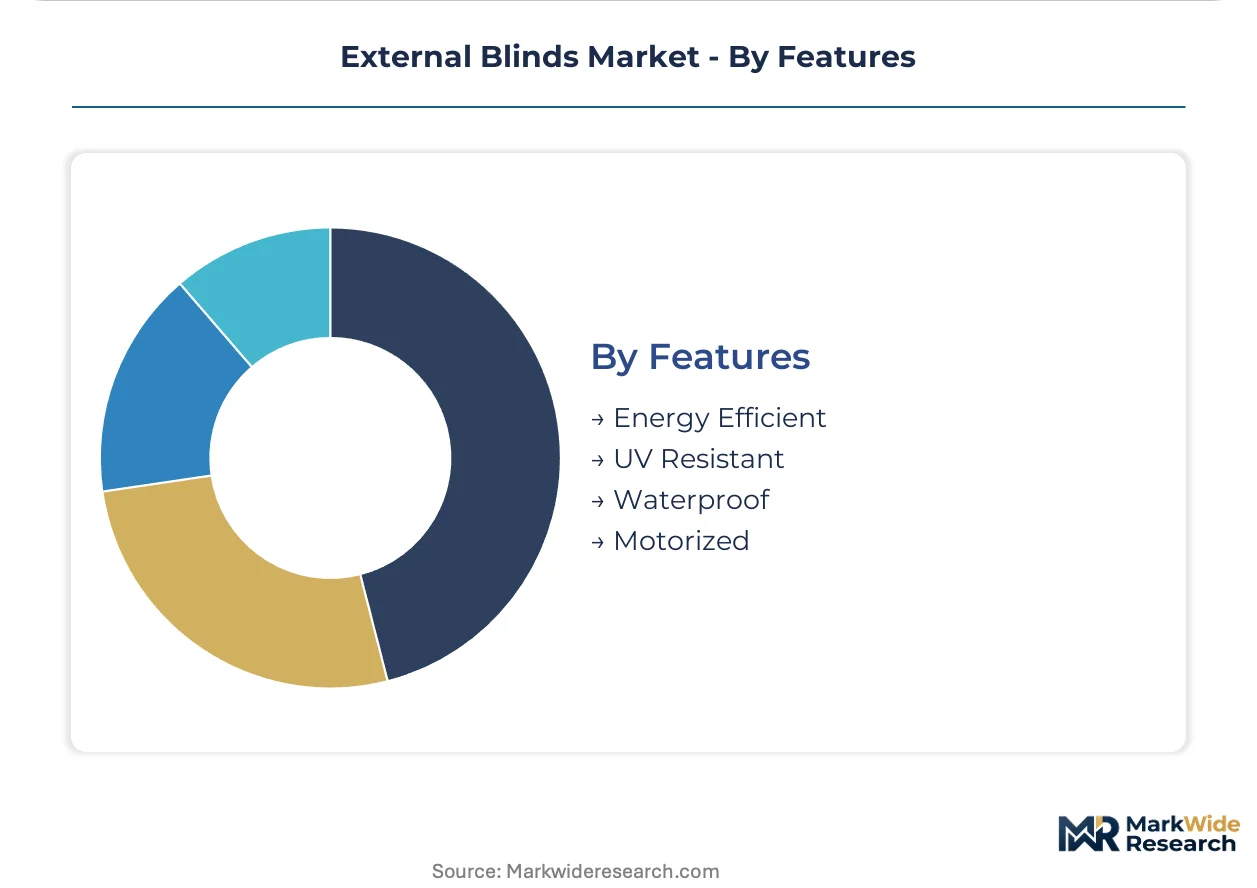
- Energy Efficient:Systems engineered to reduce solar heat gain coefficients below 0.15, qualifying for green building certification points. LEED and BREEAM assessors in France and Belgium drive specification.
- UV Resistant:Stabilized polymers and coatings preventing photodegradation in high-exposure climates. Hospitality operators in Spain and Portugal mandate these for facade warranty compliance.
- Waterproof:Sealed motor housings and drainage-engineered slat profiles for exposed installations. Coastal and alpine applications in Norway and Switzerland absorb specialized variants.
- Motorized:Electromechanical drive systems with IoT connectivity, solar tracking, and weather API integration. Building automation consultants in Germany and the Netherlands control procurement for premium commercial projects.
Energy efficiency features dominate regulatory-driven procurement. Motorized functionality is where vendor differentiation and margin expansion concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys external blinds predominantly for commercial energy compliance, while Nordic markets favor residential climate adaptation. Mediterranean countries absorb corrosion-resistant specifications for coastal hospitality assets.
Germany
Commercial retrofit pipelines dominate demand as property owners race to meet EPBD solar gain deadlines. The Construction Products Regulation mandates CE-marked assemblies for public tenders. Manufacturing clusters in Baden-Württemberg and Bavaria concentrate precision motor production and powder-coating capacity for export markets.
France
Hospitality developers in Provence-Alpes-Côte d'Azur specify UV-resistant motorized systems for facade warranty compliance. BREEAM assessor credentials now control procurement decisions for public-sector construction frameworks. Engineering consultancies in Paris and Lyon are capturing specification authority from traditional distributors.
Italy
Heritage building retrofits in Rome and Florence drive demand for Roman blind formats compatible with protected facades. REACH restrictions on chromium VI surface treatments are compelling coating reformulation across Veneto and Lombardy supply chains. Venice and Milan host specialized electromechanical suppliers for precision actuators.
Netherlands
Net-zero commercial developments in Amsterdam and Rotterdam specify photovoltaic-integrated slat systems despite cost premiums. Integration with predictive weather APIs is opening specification channels for smart building developers. Eindhoven's technical universities are supplying facade automation engineering talent.
Sweden
Residential penetration remains low relative to solar irradiance levels, presenting expansion potential for climate-adaptive systems. Vacuum-pressure-treated timber specifications absorb sustainably certified variants in Stockholm and Gothenburg housing stock. Malmö's proximity to Danish supply chains facilitates cross-border component sourcing.
External Blinds Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in aluminum extrusion and captive R&D separating the two. Backward integration into powder-coating and motor assembly is compressing cost structures for volume producers. Specialist fabricators compete through facade engineering services and heritage retrofit expertise. M&A activity targets electromechanical suppliers in Southern Germany, while capacity expansion concentrates in automated extrusion lines.
Among European-integrated manufacturers, Hunter Douglas N.V., WAREMA Renkhoff SE, and Griesser AG exemplify distinct strategic positions. Hunter Douglas leverages distribution scale across North American and European channels. WAREMA anchors engineering leadership through German-based climate-responsive automation facilities. Griesser occupies a position defined by upstream control over aluminum extrusion and surface treatment processes.
| Leading Market Players |
|---|
| Griesser AG |
| Hella Sonnen- Und Wetterschutztechnik GmbH |
| Hunter Douglas N.V. |
| Brustor NV |
| Levolux Inc. |
| WAREMA Renkhoff SE |
| Renson |
| Winsol NV |
| Somfy Systems Inc. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day powder-coating lead times in Southern Europe compress procurement flexibility for aluminum slat fabricators, concentrating pricing power among vertically integrated German suppliers with captive surface treatment capacity. This inventory-to-pricing linkage rewards backward-integrated manufacturers while forcing spot-market buyers into premium surcharges for expedited CE-marked deliveries.
Pricing Analysis
Project-based contracting dominates commercial facade specifications, with long-term offtake agreements securing aluminum extrusion capacity for multi-year retrofit pipelines. Price differentiation separates CE-marked assemblies with 30-year warranties from economy-grade PVC alternatives serving Southern European rental maintenance. Cost compression in standard motorized systems stems from aluminum ingot volatility indexed to LME contracts. Hospitality developers in Spain and Portugal show least price sensitivity for corrosion-resistant specifications, while residential retrofit distributors in Italy absorb margin pressure from volume commoditization.
Supply Chain Analysis
Strategic stockpiling of precision actuators characterizes procurement behavior among facade automation specialists, buffering against single-source vulnerability from Southern German and Northern Italian electromechanical suppliers. Manufacturing gravity centers on Germany, Italy, and Austria for extrusion, coating, and motor assembly respectively. Raw material flows draw from LME-indexed aluminum ingot, specialized polyester powder resins, and REACH-compliant trivalent chromium pretreatments. Tariff exposure on Chinese motor components creates supply chain risk. Distribution runs through facade consultants and engineering firms capturing specification authority from traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPBD compliance deadlines and CE marking requirements constructs durable defensive moats for incumbent suppliers with validated certification pathways. Switching costs escalate as building operators integrate motorized shading into BMS architectures.
For Market Incumbents: Fortify captive R&D facilities in climate-responsive automation to defend against IoT-native entrants. Prioritize backward integration into powder-coating capacity to absorb REACH compliance burdens that strain Italian coating houses. Channel control through facade consultant relationships anchors specification authority against distributor disintermediation. For New Entrants and Emerging Players: CE marking fast-track services for heritage-compatible Roman blind formats unlock Rome and Florence retrofit pipelines. White-space concentration in Nordic residential markets offers first-mover positioning for climate-adaptive systems. Direct specification through BREEAM-assessor engineering firms bypasses entrenched distribution channels in France and Belgium. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized facade automation divisions. Long-term viability rests on regulatory compliance infrastructure rather than commodity manufacturing scale. Watch electromechanical supplier consolidation in Southern Germany as inflection signal for motor pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Coating | REACH compliance burdens in Italy reward captive surface treatment capacity with margin protection. |
| IoT-BMS Platform Integration | Predictive weather API connectivity opens specification channels with Dutch smart building developers. |
| Photovoltaic Slat System Launch | Net-zero certifications in Amsterdam and Rotterdam absorb 40-60% cost premiums for energy-generating facades. |
| Heritage Retrofit Specialist Acquisition | Roman blind expertise captures protected facade projects in Rome and Florence with limited competition. |
| Nordic Residential Market Expansion | Underpenetrated Swedish and Norwegian housing stock offers expansion runway relative to solar exposure levels. |
Research Approach
Operator-level perspectives from facade automation engineers, building management system integrators, powder-coating plant managers, and hospitality facility directors anchored the qualitative base. Primary fieldwork combined with secondary validation against CE marking databases, Construction Products Regulation filing records, and EPBD implementation timelines across member states. Customs data for aluminum extrusion trade flows and BREEAM project registries provided volume anchors. Bottom-up installation tracking triangulated against top-down building stock energy compliance modeling.
Sensitivity analysis tested forecast robustness across aluminum price volatility bands, EPBD deadline acceleration scenarios, and motor supply disruption assumptions. Segmentation modeling spanned product architecture, material grade, automation tier, application vertical, and geographic regulatory cluster. CAGRs derived from installation run-rate projections indexed to commercial retrofit pipeline visibility and residential penetration elasticity. Climate irradiance mapping and green building certification adoption curves informed regional allocation.
The analysis sits within stated boundaries; outcomes outside sustained EPBD enforcement or aluminum supply stability would require recalibration. Forecasts embed assumptions around CE marking timeline compression and REACH coating chemistry transitions. Revision becomes warranted when motor supplier consolidation crosses concentration thresholds or when photovoltaic slat cost curves steepen unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Double-Hung Windows Market