
 Home Improvement Services Market | 2026-2036
Home Improvement Services Market Size, Share, and Industry Trends Forecast 2026-2036
Home Improvement Services Market Intelligence
Aftermarket service revenue is rewriting profit architecture across the home improvement value chain. The Home Depot leverages its Pro Xtra loyalty program to sustain contractor lock-in and recurring material flows. Lowe's anchors its position through localized inventory positioning and dedicated Pro desk staffing. Angi Inc. competes by aggregating vetted trade labor and reducing homeowner search friction.
Home improvement services encompass skilled trade execution, material installation, and property modification performed on existing residential structures, typically requiring licensed expertise in electrical, plumbing, or structural disciplines and compliance with local building codes. These services preserve asset value, adapt living spaces to evolving household needs, and address deferred maintenance in aging housing stock. Remodeling services capture the largest margin pool given project complexity and design-customization premiums, while exterior upgrades represent the fastest-growing category as climate resilience and curb appeal priorities intensify. Residential homeowners dominate transaction volume, though property managers generate superior repeat-service frequency through portfolio-scale maintenance programs.
OSHA workplace safety standards, EPA lead-based paint renovation rules, and state-level contractor licensing boards collectively elevate compliance costs and create barriers to unqualified market entry. These frameworks push demand toward certified, insured providers and away from informal labor channels. Stakeholders must monitor how municipal building department backlogs and permit automation investments reshape project timelines and contractor capacity planning.
Market Dynamics
EPA lead-safe certification requirements and state-level energy efficiency mandates are systematically elevating contractor qualification standards across the United States. These regulatory frameworks compress informal labor channels while redirecting demand toward certified, insured providers with documented compliance histories.
Growth Catalysts
- IRA Energy Efficiency Tax Credits:Federal incentives for weatherization and electrification retrofits are expanding homeowner renovation budgets. These subsidies directly reduce project payback periods for HVAC and insulation upgrades.
- Aging Housing Stock Demographics:Over half of US owner-occupied homes were built before 1980. This structural condition generates persistent demand for systematic electrical, plumbing, and structural rehabilitation.
- Smart Home Integration:Connected device ecosystems require skilled installation of low-voltage wiring and system integration. Homeowners increasingly bundle these upgrades with traditional remodeling projects.
Market Restraints
- Lumber and Copper Price Volatility:Input cost swings compress project margin predictability for fixed-bid contractors. Material hedging requires working capital reserves that strain smaller operators.
- Skilled Trade Labor Scarcity:Electrician and plumber apprenticeship completions lag replacement demand across the Midwest and Northeast. This bottleneck extends project timelines and inflates wage rates.
- OSHA Compliance Burden:Workplace safety documentation and training requirements add administrative overhead. Smaller contractors face disproportionate compliance cost absorption relative to revenue scale.
Strategic Opportunities
- Texas and Florida Population Influx:Rapid household formation in Sun Belt metros outpaces local contractor capacity. National service platforms can establish density advantages before local competitors scale.
- Residential Solar-Plus-Storage Bundling:Rooftop photovoltaic installations increasingly pair with battery systems and panel upgrades. Contractors with electrical and roofing capabilities capture cross-sell economics.
- Property Manager Portfolio Contracts:Multi-unit maintenance programs generate superior repeat-service frequency compared to one-off homeowner transactions. Scaled operators can secure multi-year service agreements.
Industry Challenges
- EPA RRP Certification Timelines:Lead-safe renovation training and certification renewal create workforce deployment friction. Projects in pre-1978 housing face mandatory 2-3 week scheduling delays.
- Municipal Permit Backlogs:Building department staffing shortages in California and New York extend approval timelines. Contractors must absorb carrying costs or pass delays to customers.
- Legacy System Integration Complexity:Smart home retrofits must interface with aging electrical panels and incompatible wiring standards. Diagnostic labor consumes disproportionate project hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Improvement Services Market |
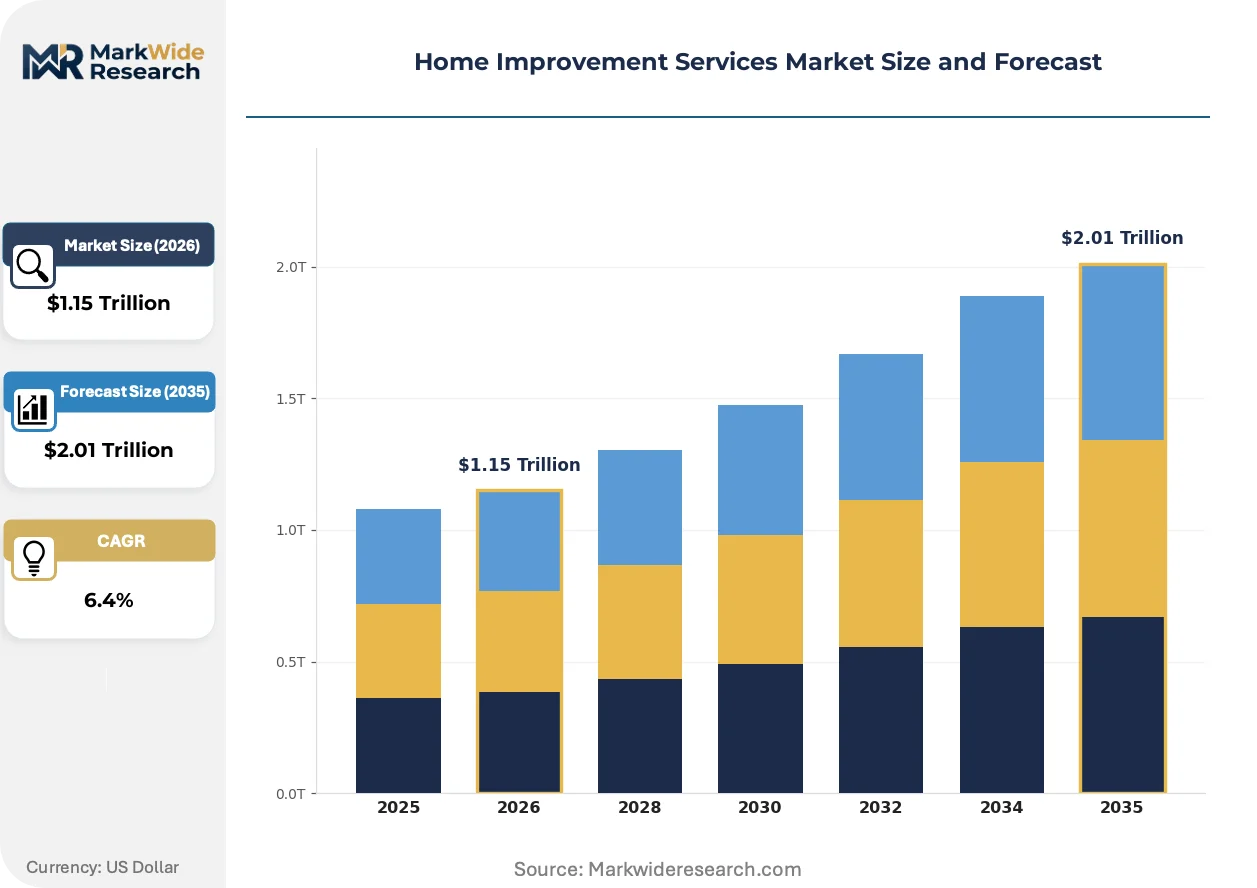
| Market Size in 2026 | $1.15 Trillion |
| Market Size in 2035 | $2.01 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remodeling, Landscaping, Painting, Plumbing End User: Residential Homeowners, Property Managers, Contractors, Real Estate Developers Project Scope: Interior Renovation, Exterior Upgrades, Repair Work, Custom Builds Pricing Model: Fixed Price, Hourly Rate, Cost Plus, Subscription |
| Companies Covered | The Home Depot, Lowe's, Menards, ABC Supply Co., Builders FirstSource, Angi Inc., Frontdoor Inc., ServiceMaster Brands, Power Home Remodeling Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Improvement Services Market Strategic Shifts & Innovations
Digital measurement tools and prefabricated component systems are compressing project timelines while elevating precision standards. These innovations reshape how contractors estimate, procure, and execute residential renovations.
LiDAR-enabled spatial scanning is migrating from commercial construction into residential remodeling workflows. Kitchen and bathroom specialists now deploy handheld devices to generate millimeter-accurate as-built documentation. This technology eliminates manual measurement errors and accelerates custom cabinetry and countertop ordering cycles.
OSHA's updated silica exposure standards for countertop fabrication and demolition activities are forcing operational changes across stone installation trades. Wet-cutting methods and engineered stone alternatives are displacing dry fabrication in high-exposure environments. California and New York enforcement jurisdictions are driving fastest compliance adoption.
Homeowner vetting behavior now prioritizes platform-verified reviews and license documentation over traditional referral networks. Angi and Thumbtack aggregators are capturing search traffic that previously flowed to contractor websites and local directories. This shift concentrates lead generation power in digital intermediaries across suburban markets.
Home Improvement Services Market Segmentation
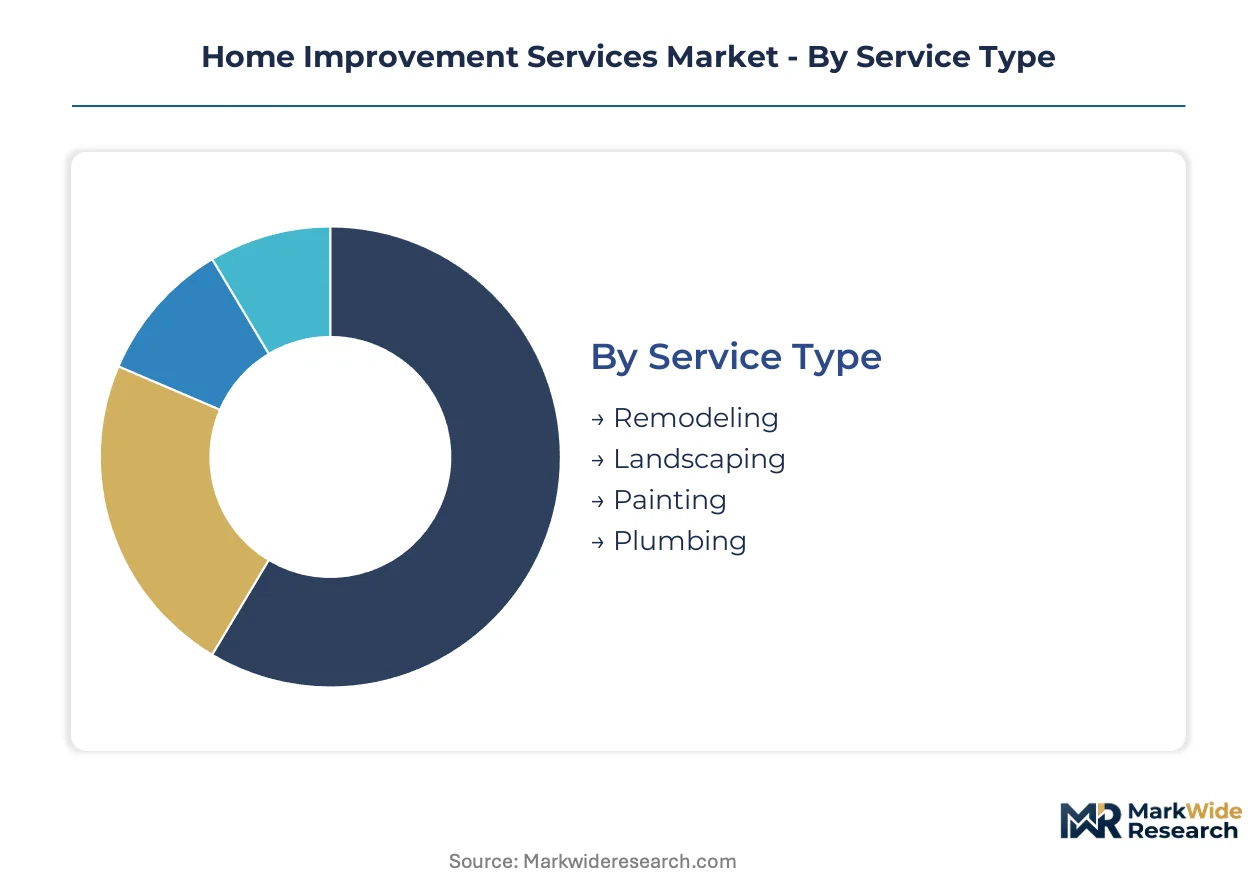
Segmentation in home improvement services reveals distinct operational economics and customer acquisition patterns. Each dimension—service type, end user, project scope, and pricing model—carries unique margin profiles and repeat-transaction potential that reshape competitive strategy.
Service Type:
Use cases span from high-complexity structural modifications to recurring maintenance tasks, with each service tier demanding different certification levels and capital intensity.
- Remodeling:Kitchen and bathroom renovations dominate project value concentration. EPA lead-safe certification requirements elevate contractor qualification barriers in pre-1978 housing stock across the United States. Design-customization premiums and extended project timelines generate the largest margin pool in the services ecosystem.
- Landscaping:Exterior aesthetic and drainage improvements require seasonal workforce scaling. Demand concentrates in Sun Belt metros where rapid household formation outpaces local contractor capacity. Climate resilience priorities are accelerating hardscaping and irrigation system bundling.
- Painting:Interior and exterior surface finishing offers lower barrier to entry with compressed project cycles. OSHA silica exposure standards for surface preparation are elevating compliance costs for smaller operators.
- Plumbing:Emergency repair and fixture replacement generate the highest repeat-service frequency. Skilled trade labor scarcity extends project timelines and inflates wage rates across the Midwest and Northeast.
Established volume favors Remodeling; emerging adoption favors Landscaping.
End User:
Customer type determines contract structure, price sensitivity, and lifetime value economics across the service spectrum.
- Residential Homeowners:Individual property owners drive transaction volume through discretionary renovation decisions. IRA energy efficiency tax credits are expanding weatherization and electrification retrofit budgets. Platform-verified reviews now dominate contractor selection over traditional referral networks.
- Property Managers:Multi-unit portfolio operators generate superior repeat-service frequency through systematic maintenance programs. Scaled operators secure multi-year service agreements with predictable cash flow profiles.
- Contractors:Trade specialists subcontract specialized labor or materials procurement for complex projects. Pro Xtra loyalty programs and dedicated Pro desk staffing anchor material flow relationships with national retailers.
- Real Estate Developers:Pre-sale renovation and new construction finishing demand compressed timelines and volume pricing. Municipal permit backlogs in California and New York extend approval timelines and strain project scheduling.
Transaction density favors Residential Homeowners; contract value concentration favors Real Estate Developers.
Project Scope:
Project scale dictates labor mix, permit complexity, and customer involvement intensity from consultation through completion.
- Interior Renovation:Kitchen, bathroom, and living space modifications require licensed electrical and plumbing expertise. Smart home integration demands low-voltage wiring skills that trade contractors increasingly bundle with traditional remodeling.
- Exterior Upgrades:Roofing, siding, and window replacement address climate resilience and curb appeal priorities. This category is expanding most quickly as aging housing stock faces deferred maintenance accumulation.
- Repair Work:Reactive maintenance and emergency fixes generate immediate revenue but unpredictable scheduling. Diagnostic labor for legacy system integration consumes disproportionate project hours.
- Custom Builds:Tailored additions and structural modifications command premium pricing and extended design phases. LiDAR-enabled spatial scanning is compressing measurement and ordering cycles for millimeter-accurate component fabrication.
Margin depth favors Custom Builds; volume accessibility favors Repair Work.
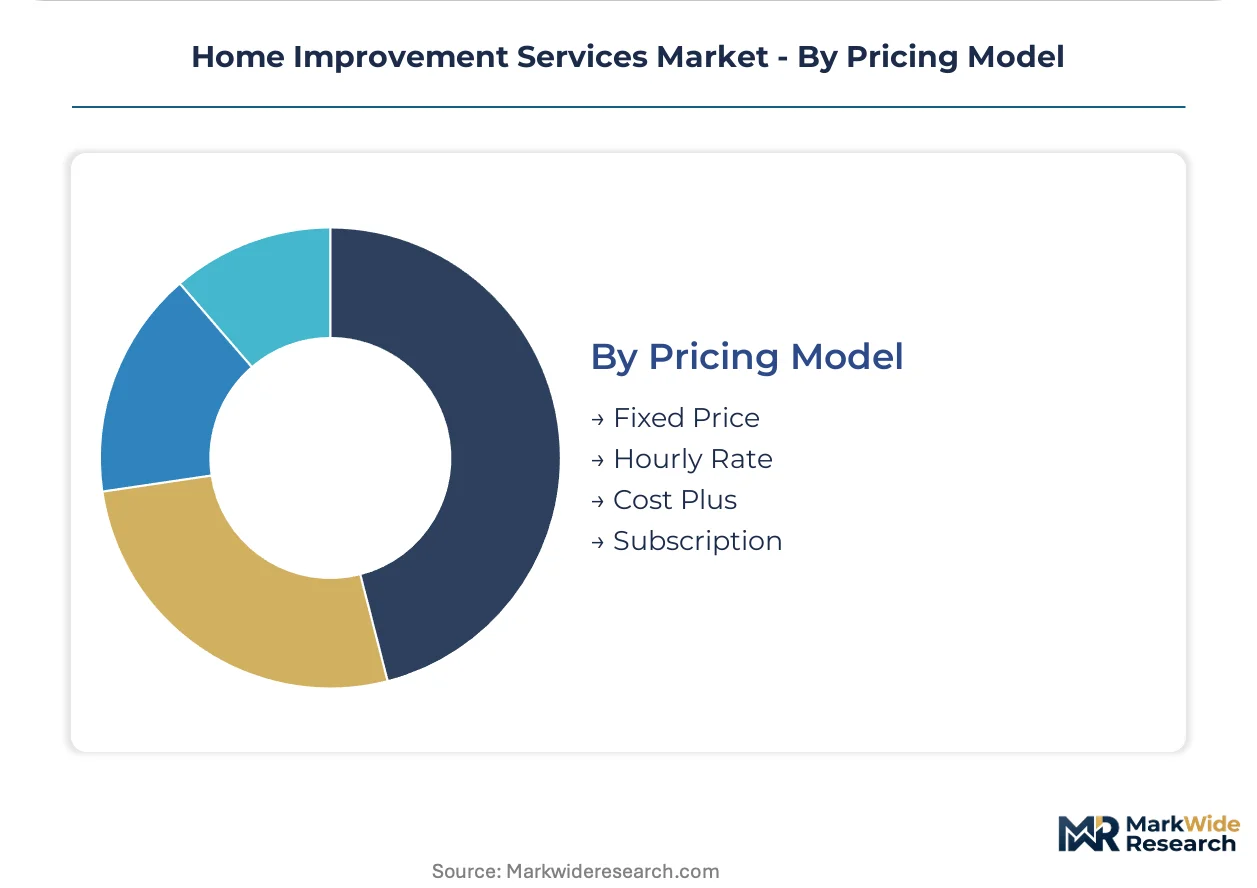
Pricing Model:
Revenue structure shapes risk allocation between contractor and customer while influencing working capital requirements.
- Fixed Price:Lump-sum contracts transfer cost overrun risk to contractors. Lumber and copper price volatility compress margin predictability without material hedging reserves.
- Hourly Rate:Time-and-materials billing aligns incentives for scope expansion and change orders. Skilled trade labor scarcity inflates rate structures for electrician and plumber categories.
- Cost Plus:Transparent markup arrangements build trust in complex projects with uncertain specifications. Administrative overhead for documentation and verification adds operational friction.
- Subscription:Recurring maintenance agreements generate predictable revenue streams. Property manager portfolio contracts represent the primary adoption channel for this emerging structure.
Risk transfer favors Fixed Price; revenue predictability favors Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home improvement service consumption patterns diverge sharply between aging-housing markets prioritizing system rehabilitation and high-growth metros emphasizing new construction finishing and outdoor living upgrades.
United States
Over half of owner-occupied homes predate 1980, generating sustained demand for electrical panel upgrades and plumbing rehabilitation. EPA lead-safe certification requirements compress informal labor channels in pre-1978 housing stock. Sun Belt metros including Houston, Dallas, and Phoenix face contractor capacity constraints from rapid household formation.
Germany
Building energy efficiency mandates under the EU Green Deal accelerate facade insulation and window replacement cycles. KfW development bank subsidies reduce homeowner payback periods for heat pump installations. Industrial clusters in North Rhine-Westphalia concentrate HVAC contractor capacity serving the Ruhr metropolitan corridor.
United Kingdom
Stamp duty incentives and permitted development rights expansion stimulate residential extension projects. Gas boiler phase-out regulations under the Future Homes Standard redirect demand toward heat pump and solar thermal specialists. Greater London and Southeast England concentrate high-value kitchen and bathroom renovation activity.
Canada
Cold climate weatherization priorities elevate attic insulation and air sealing demand in Ontario and Quebec provinces. Natural Resources Canada EnerGuide rating requirements shape contractor qualification standards for federally subsidized retrofits. Vancouver and Toronto metropolitan areas face skilled trade labor scarcity extending project timelines.
Australia
Climate resilience priorities accelerate bushfire-rated roofing and stormwater management system installations. Nationwide House Energy Rating Scheme compliance requirements elevate glazing and insulation specifications for renovation projects. Sydney and Melbourne construction booms strain licensed electrician and plumber availability.
Home Improvement Services Market Key Industry Players
Capability concentration sits with specialized trade contractors holding EPA, OSHA, and state-level certifications; scale advantage sits with national retail platforms commanding material procurement leverage and contractor loyalty programs. The vendor base stratifies across three tiers: big-box retailers anchoring material flows, digital aggregators capturing homeowner search traffic, and regional trade specialists executing complex remodeling. Dominant competitive moves include loyalty program expansion to lock contractor recurring spend and geographic density building in high-migration Sun Belt metros.
Within the retail platform tier, The Home Depot and Lowe's occupy positions defined by Pro-desk staffing and localized inventory positioning. Among digital intermediaries, Angi Inc. exemplifies the lead-generation archetype through vetted contractor aggregation. These three companies represent the primary competitive anchors shaping how homeowners discover, vet, and contract improvement services across suburban markets.
| Leading Market Players |
|---|
| The Home Depot |
| Lowe's |
| Menards |
| ABC Supply Co. |
| Builders FirstSource |
| Angi Inc. |
| Frontdoor Inc. |
| ServiceMaster Brands |
| Power Home Remodeling Group |
| Others |
Cost & Logistics Intelligence
Lumber and copper concentrate in North American and Chilean extraction zones, anchoring margin pools with specialty contractors who hedge material exposure through Pro-desk relationships with national retailers. This upstream concentration forces pricing discipline downstream, where fixed-bid contractors absorb volatility or pass escalation through change-order mechanisms.
Pricing Analysis
Project-based contracts dominate residential remodeling, though subscription maintenance agreements are emerging through property manager portfolios. Price differentiation rests on EPA lead-safe certification tier and smart home integration capability, with certified installers commanding premiums in pre-1978 housing stock. Cost compression in standard painting and basic repair segments is intensifying because informal labor channels persist despite regulatory elevation. Residential homeowners exhibit highest price sensitivity on discretionary cosmetic projects, while real estate developers show lowest sensitivity on pre-sale renovation timelines.
Supply Chain Analysis
Export-control scrutiny on engineered stone fabrication equipment from Italy and Germany constrains countertop specialty expansion in North American markets. Geographic supply concentration centers on China for lighting fixtures and hardware, Canada for softwood lumber, and Chile for copper cathode. Raw material dependencies include dimensional lumber, copper wire, and quartz surfacing. Single-source vulnerability runs through Italian CNC stone-cutting machinery. Distribution runs through big-box retail Pro desks and regional lumberyard networks serving contractor loyalty programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern homeowner-contractor matching as Angi and Thumbtack aggregators capture search traffic that previously flowed to direct referral networks, with interoperability between smart home device ecosystems becoming the new lock-in battleground.
For Market Incumbents: Entrench contractor loyalty through exclusive Pro-desk staffing and localized inventory positioning that reduces job-site delivery friction. Deepen EPA RRP certification training infrastructure to accelerate workforce deployment against informal labor substitutes. Anchor material flow relationships with multi-year rebate structures that raise switching costs for high-volume trade specialists.
For New Entrants and Emerging Players: Sun Belt metros including Houston, Dallas, and Phoenix present contractor capacity gaps where rapid household formation outpaces local skilled trade availability. Target residential solar-plus-storage bundling as the most penetrable segment, where electrical and roofing capability convergence creates cross-sell economics. Pursue direct-to-property-manager subscription maintenance agreements as the primary go-to-market angle for predictable recurring revenue.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional specialists with captive electrical and plumbing trades serving aging-housing rehabilitation corridors. Long-term viability hinges on regulatory compliance infrastructure that informal operators cannot replicate. Watch municipal permit automation investments as the signal for timeline compression and contractor capacity expansion inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Pro-Desk Staffing Expansion | Dedicated contractor service desks at The Home Depot and Lowe's reduce procurement friction and deepen loyalty program lock-in. |
| EPA RRP Certification Investment | Lead-safe renovation training infrastructure accelerates workforce deployment in pre-1978 housing rehabilitation markets. |
| Smart Home Integration Capability | Low-voltage wiring and connected device installation skills capture bundled project economics with traditional remodeling. |
| Sun Belt Geographic Density Build | Rapid household formation in Texas and Florida metros outpaces local contractor capacity, enabling first-mover scale advantages. |
| Property Manager Subscription Contracts | Multi-unit maintenance agreements generate superior repeat-service frequency compared to one-off homeowner transactions. |
Research Approach
Operator-level perspectives from residential contractors, property management executives, Pro-desk managers at national retailers, and municipal building department officials anchored the qualitative base. These primary insights combined with secondary validation from EPA enforcement records, state contractor licensing board databases, OSHA compliance documentation, and building permit issuance statistics. Bottom-up project pipeline analysis and top-down housing stock demographic modeling provided triangulation across the estimation framework.
Scenario-bracketing around IRA tax credit extension assumptions and skilled trade labor availability shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include service type complexity tier, end-user contract structure, project scope scale, and pricing model risk allocation. CAGRs derived from housing age demographics, renovation frequency elasticity, and regulatory compliance cost pass-through coefficients. Forecast inputs incorporated lumber futures volatility patterns and electrician apprenticeship completion rates by census region.
Practitioners should monitor IRA energy efficiency subsidy renewal negotiations and EPA RRP certification backlog durations for early signals of demand elasticity shifts. Forecasts reflect assumptions regarding persistent skilled trade scarcity and stable municipal permitting throughput. Material shifts in federal weatherization incentive structures or state-level contractor licensing reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
External Blinds Market