
 Photointerrupter Market | 2026-2036
Photointerrupter Market Size, Share, and Industry Trends Forecast 2026-2036
Photointerrupter Market Analytics
Buyer concentration among industrial automation OEMs is broadening as mid-tier robotics manufacturers enter the supply base alongside established electronics assemblers. Omron Corporation leverages its factory automation channel dominance to bundle photointerrupters with motion control systems. ROHM Semiconductors anchors its position through captive infrared LED sourcing and discrete component integration. Hamamatsu Photonics differentiates via photodiode sensitivity specifications that exceed standard industrial grades.
A photointerrupter is an optoelectronic sensor comprising an infrared emitter and photodetector arranged across a mechanical gap or reflective path, detecting object presence by beam interruption or reflection with response times typically under one millisecond. The device serves primarily as a non-contact position encoder, limit switch replacement, and safety interlock in precision machinery. Slot-type products occupy the highest volume tier due to standardized mounting in printer mechanisms and conveyor systems, while reflective variants capture expanding margin pools in robotic end-effector applications. Infrared technology leads unit shipments, though photoelectric architectures gain traction in medical device sterilization environments where ultraviolet compatibility becomes essential.
FDA device classification rules in the United States and EU MDR technical documentation requirements in Europe compel medical device photointerrupter suppliers to maintain biocompatibility and electromagnetic compatibility traceability across component lots. Japan's METI mandates industrial sensor efficiency benchmarks that filter lower-performance imports from Southeast Asian assembly operations. Stakeholders must monitor how regional certification divergence between North American and European safety standards affects platform design costs for multinational OEMs.
Market Dynamics
Industrial automation OEMs are consolidating sensor procurement around integrated motion control platforms, compressing standalone photointerrupter margins while elevating specification requirements for precision positioning subsystems.
Growth Catalysts
- China's MIIT dual carbon goals:Energy-efficiency mandates are accelerating replacement cycles in Shenzhen manufacturing clusters, forcing upgrades to low-power infrared architectures.
- Robotic end-effector sensing:Reflective photointerrupter demand is expanding in precision gripping applications where slot-type units cannot physically access detection zones.
- Medical device sterilization:Ultraviolet-compatible photoelectric architectures are displacing legacy infrared units in autoclave-compatible instrumentation, opening new certification pathways.
Market Restraints
- Infrared LED supply concentration:Captive sourcing by Japanese and Korean integrated manufacturers limits second-source availability for mid-tier assemblers.
- Technical performance ceiling:Response times below one millisecond are approaching physical limits of discrete optoelectronic architectures without monolithic integration.
- EU MDR documentation burden:Biocompatibility traceability requirements for medical device components are extending qualification timelines by 8-14 months for non-captive suppliers.
Strategic Opportunities
- India's PLI scheme for electronics:Component-level incentives are attracting photointerrupter module assembly to Noida and Chennai industrial corridors.
- Automotive lidar convergence:Photodiode sensitivity specifications developed for industrial photointerrupters are transferring to short-range automotive optical sensing applications.
- Direct OEM contracting:Mid-tier robotics manufacturers are bypassing traditional electronics distributors, creating channel compression and margin recapture potential.
Industry Challenges
- Optoelectronics packaging expertise:Hermetic sealing capabilities for medical-grade units are concentrated among legacy Japanese suppliers, constraining capacity expansion.
- Legacy system integration friction:Retrofitting photointerrupters into existing PLC architectures requires custom signal conditioning, complicating aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photointerrupter Market |
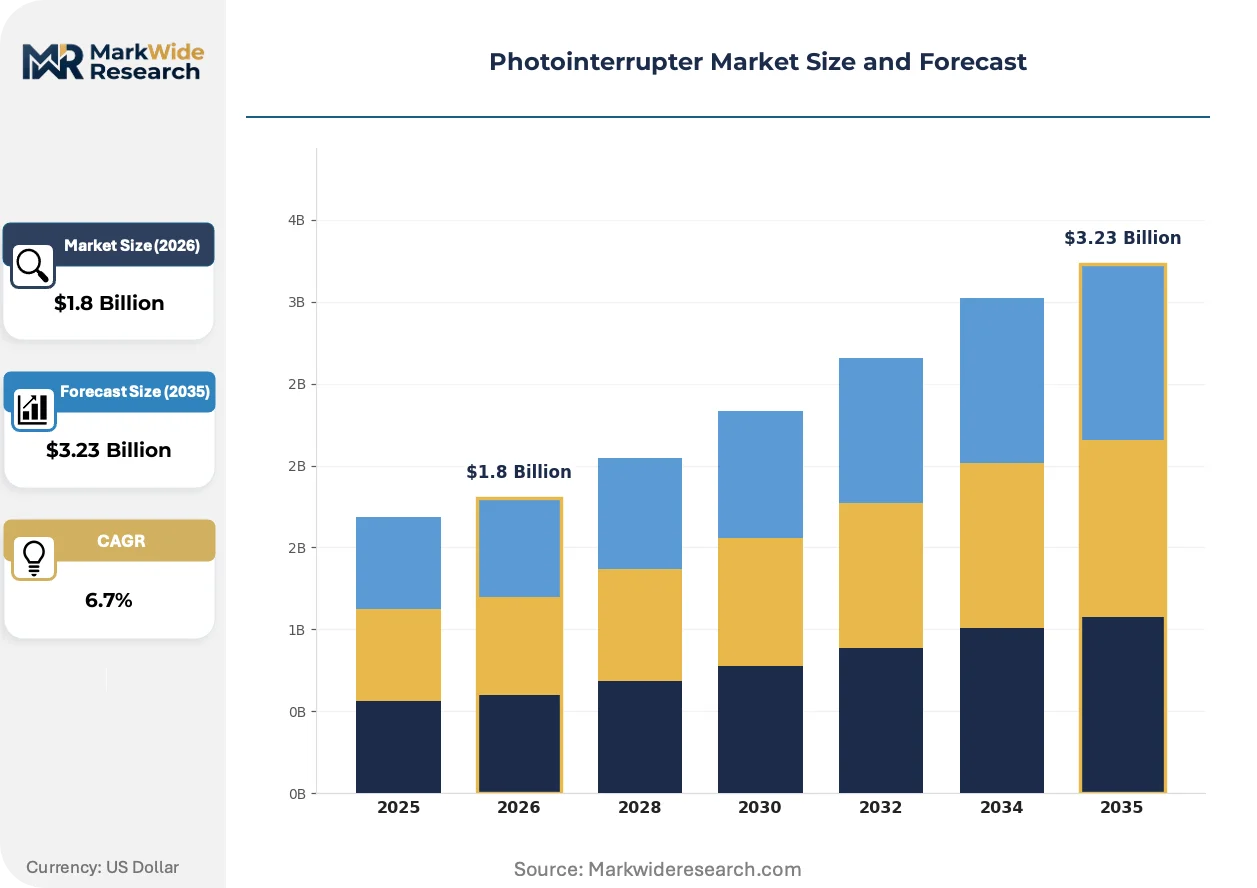
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slot, Small, Reflective, Optical Technology: Infrared, Laser, Photoelectric, Ultraviolet Application: Consumer Electronics, Industrial Automation, Medical Devices, Robotics End User: Manufacturers, OEMs, Distributors, Retailers |
| Companies Covered | Omron Corporation, ROHM Semiconductors, Hamamatsu Photonics, Panasonic Holdings Corporation, Vishay Intertechnology, Lite-On Technology Corporation, Honeywell International Inc., Broadcom Inc., Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photointerrupter Market Evolving Landscape
Monolithic integration of emitter-detector pairs is compressing form factors while elevating performance consistency, reshaping competitive differentiation around semiconductor process capabilities rather than discrete component sourcing.
Silicon photonics is unifying emitter and detector functions onto single substrates for sub-millimeter gap applications. Medical device manufacturers in Germany and Switzerland are piloting these architectures for catheter position sensing. The technology is unifying previously separate supply chains for infrared LEDs and photodiodes into captive foundry relationships.
Japan's METI industrial sensor efficiency benchmarks are filtering lower-performance imports from Southeast Asian assembly operations. Domestic manufacturers are accelerating JIS-compliant product development to maintain public procurement eligibility. Korean suppliers are responding with dedicated efficiency testing facilities in Gyeonggi-do to preserve access.
Specification-driven procurement is displacing price-first vendor selection among precision machinery OEMs. Motion control system integrators are consolidating photointerrupter sourcing with encoder and servo motor contracts. This pattern is most visible in Nagoya's automotive component manufacturing cluster, where tier-one suppliers are reducing qualified vendor lists by 40-60 percent.
Photointerrupter Market Segmentation
Photointerrupter procurement patterns diverge sharply across product architectures and end-use environments. Component selection hinges on response time requirements, physical mounting constraints, and sterilization compatibility rather than unit cost alone.
Product Type:
Supply concentration in precision molding and infrared LED sourcing favors manufacturers with captive optical component production.
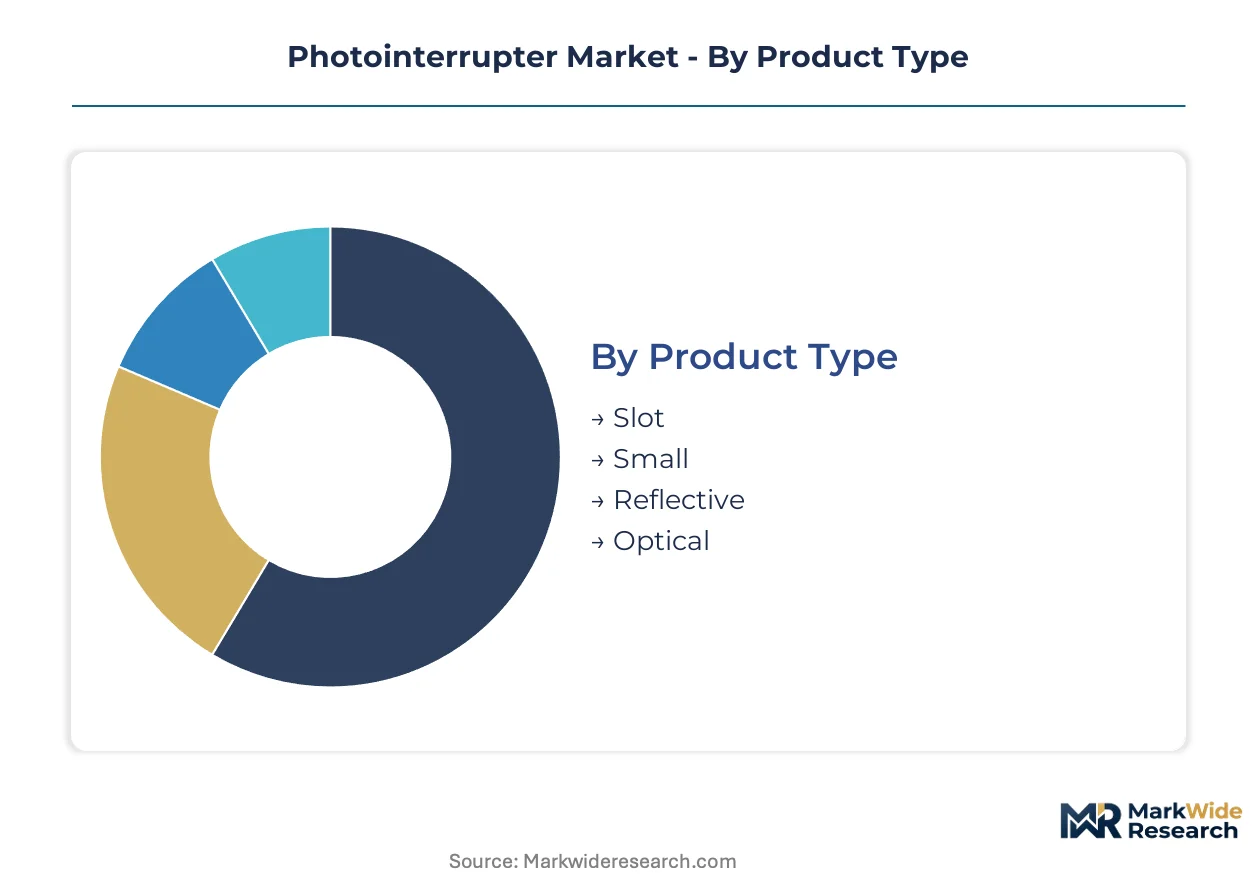
- Slot:Emitter-detector pairs mounted across a fixed mechanical gap detect object presence through beam interruption. Shenzhen printer mechanism manufacturers and Nagoya conveyor system integrators account for the dominant procurement volumes, driven by standardized DIN rail mounting and sub-millisecond response specifications.
- Reflective:Single-package units emit and detect reflected infrared light, eliminating the physical gap requirement. Robotic end-effector manufacturers in Seoul and Stuttgart are expanding orders for precision gripping applications where slot-type geometries cannot access confined detection zones.
- Small:Miniaturized surface-mount packages target wearable device and portable medical instrument producers. Korean component distributors report tightening allocation for sub-2mm height variants.
- Optical:Broad-spectrum detection architectures accommodate visible and near-infrared wavelengths. German laboratory equipment OEMs specify these for multi-wavelength sensing protocols.
Slot-type units absorb the bulk of installed capacity; Reflective variants are expanding most quickly.
Technology:
Cost tier differentiation separates commodity infrared architectures from premium photoelectric and ultraviolet-compatible platforms.
- Infrared:Gallium arsenide emitters paired with silicon photodiodes dominate unit economics. Japanese integrated manufacturers leverage captive LED foundries to control input costs for industrial automation OEMs.
- Photoelectric:Advanced signal conditioning circuits enable detection through translucent or colored media. Swiss medical device sterilization equipment producers specify these for autoclave-compatible instrumentation requiring electromagnetic immunity.
- Laser:Collimated beam sources achieve extended detection ranges with minimal divergence. Chinese lithium battery manufacturing lines deploy these for web tension monitoring in electrode coating operations.
- Ultraviolet:Mercury-free LED sources compatible with UV sterilization cycles. FDA device classification rules compel biocompatibility traceability for catheter position sensing applications.
Infrared architectures absorb the bulk of installed capacity; Photoelectric platforms are expanding most quickly.
Application:
Volume concentration in consumer electronics assembly contrasts with margin expansion in medical device and robotics verticals.
- Industrial Automation:Position encoders and safety interlocks for CNC machinery and packaging equipment. METI efficiency mandates in Japan are accelerating replacement cycles in legacy Mitsubishi and Fanuc control systems.
- Consumer Electronics:Paper path detection in printers and copier mechanisms. Shenzhen contract manufacturers consolidate sourcing around slot-type units with standardized 5mm gap specifications.
- Medical Devices:Sterilizable position sensing for surgical instruments and diagnostic equipment. EU MDR technical documentation requirements extend qualification timelines for non-captive suppliers.
- Robotics:Collision detection and joint position feedback for collaborative robot arms. Stuttgart automotive component plants specify reflective units for end-of-line quality inspection stations.
Industrial Automation absorbs the bulk of installed capacity; Robotics is expanding most quickly.
End User:
Customer type determines channel structure, with direct OEM contracting displacing traditional electronics distribution in precision machinery segments.
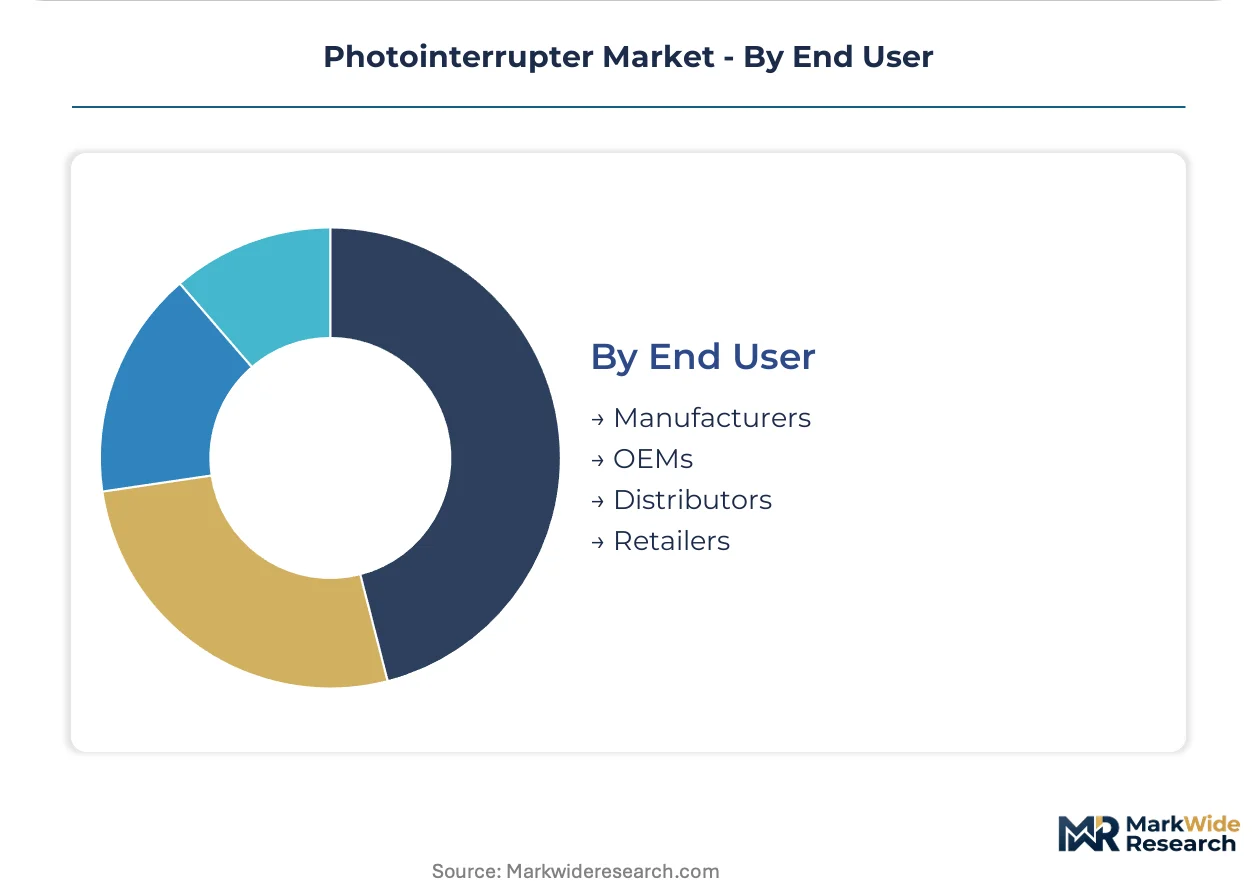
- OEMs:Original equipment manufacturers in motion control and medical device verticals. Nagoya automotive tier-one suppliers are reducing qualified vendor lists by 40-60 percent, consolidating photointerrupter contracts with encoder and servo motor procurement.
- Manufacturers:Electronics assemblers and contract manufacturers building finished goods. Noida and Chennai industrial corridors under India's PLI scheme are attracting module assembly capacity.
- Distributors:Arrow, Avnet, and regional Japanese trading houses. Mid-tier robotics manufacturers are bypassing these channels entirely, creating margin compression for traditional intermediaries.
- Retailers:Component resellers serving prototype and repair markets. Online platforms capture hobbyist and educational institution demand for breadboard-compatible through-hole packages.
OEMs absorb the bulk of installed capacity; Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photointerrupter procurement concentrates in East Asian manufacturing corridors where precision machinery OEMs and electronics assemblers co-locate. Shenzhen, Nagoya, and Seoul industrial clusters absorb the dominant share of slot-type and reflective unit volumes.
China
Industrial automation OEMs in Shenzhen and Dongguan are accelerating replacement cycles for legacy photointerrupter installations. MIIT dual carbon goals mandate energy-efficiency benchmarks that filter lower-performance imports from Southeast Asian assembly operations. Pearl River Delta contract manufacturers consolidate sourcing around standardized 5mm gap slot-type units for printer mechanisms.
Japan
Motion control system integrators in Nagoya's automotive component cluster are reducing qualified vendor lists by 40-60 percent. METI industrial sensor efficiency mandates compel domestic manufacturers to accelerate JIS-compliant product development for public procurement eligibility. Hamamatsu and surrounding precision optics regions maintain hermetic sealing capabilities for medical-grade units.
South Korea
Robotic end-effector manufacturers in Seoul and Gyeonggi-do are expanding orders for reflective photointerrupter architectures. Korean suppliers have established dedicated efficiency testing facilities to preserve access to Japanese industrial markets. Busan-Ulsan electronics corridors report tightening allocation for sub-2mm height small-package variants.
Germany
Stuttgart automotive component plants specify reflective units for end-of-line quality inspection stations. EU MDR technical documentation requirements extend qualification timelines for non-captive medical device component suppliers. Bavarian laboratory equipment OEMs specify broad-spectrum optical architectures for multi-wavelength sensing protocols.
United States
FDA device classification rules compel biocompatibility and electromagnetic compatibility traceability across photointerrupter component lots. Midwest industrial automation distributors serve CNC machinery and packaging equipment retrofit markets. Greater Boston medical device clusters pilot silicon photonics architectures for catheter position sensing applications.
Photointerrupter Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ultraviolet-compatible and silicon photonics architectures for medical sterilization and sub-millimeter gap applications. The vendor base stratifies across integrated manufacturers with captive infrared LED sourcing, discrete component specialists, and semiconductor foundries offering monolithic emitter-detector integration. Two dominant competitive moves define current positioning: strategic partnerships between motion control OEMs and sensor suppliers for bundled procurement contracts, and backward integration into photodiode sensitivity specification development for automotive lidar convergence.
Among Japanese precision optics manufacturers, Hamamatsu Photonics occupies a position exemplifying photodiode sensitivity differentiation for industrial and medical applications. Omron Corporation anchors the factory automation channel tier through motion control system bundling relationships with Nagoya automotive tier-one suppliers. ROHM Semiconductors represents the integrated manufacturing archetype with captive infrared LED sourcing and discrete component integration capabilities.
| Leading Market Players |
|---|
| Omron Corporation |
| ROHM Semiconductors |
| Hamamatsu Photonics |
| Panasonic Holdings Corporation |
| Vishay Intertechnology |
| Lite-On Technology Corporation |
| Honeywell International Inc. |
| Broadcom Inc. |
| Sharp Corporation |
| Others |
Value Network & Pricing Analysis
China's MIIT dual carbon goals gate qualified supply and premium-tier pricing access, compelling component manufacturers to absorb efficiency certification costs or forfeit public procurement eligibility in Shenzhen manufacturing clusters. Japanese METI mandates and EU MDR documentation requirements create parallel certification barriers that stratify pricing tiers by compliance burden rather than unit cost alone.
Pricing Analysis
Slot-type photointerrupters absorb the bulk of procurement volume at compressed margins, while reflective and ultraviolet-compatible architectures command premium positioning in robotic end-effector and medical sterilization applications. Price differentiation hinges on JIS/METI efficiency certification grade and captive infrared LED sourcing, with Japanese integrated manufacturers extracting margin premiums unavailable to Southeast Asian assemblers. Cost compression in standard infrared tiers is intensifying as mid-tier robotics manufacturers consolidate encoder and servo motor contracts with bundled sensor procurement. Contract manufacturers in Shenzhen demonstrate highest price sensitivity, whereas Nagoya automotive tier-one suppliers prioritize specification compliance over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian precision optics hubs to European medical device OEMs elevates landed costs for hermetically sealed medical-grade units beyond raw component value. Supply concentrates in Japan, South Korea, and China, with Hamamatsu and Nagoya regions maintaining captive photodiode sensitivity capabilities and hermetic sealing expertise. Input dependencies span gallium arsenide infrared emitters, silicon photodiode substrates, and precision-molded mechanical gaps. Single-source vulnerability concentrates in legacy Japanese suppliers for medical-grade hermetic packaging. Distribution runs through Arrow and Avnet for standard industrial tiers, while direct OEM contracting displaces traditional channels in precision machinery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics monolithic integration is displacing discrete optoelectronic architectures, compressing form factors and unifying previously separate emitter-detector supply chains into captive foundry relationships.
For Market Incumbents: Lock in motion control bundling contracts with Nagoya automotive tier-one suppliers before qualified vendor list consolidation completes. Deepen backward integration into photodiode sensitivity specification development for automotive lidar convergence, defending against semiconductor foundries offering monolithic emitter-detector integration.
For New Entrants and Emerging Players: Mid-tier robotics manufacturers bypassing traditional electronics distributors represent the most penetrable buyer archetype. Target ultraviolet-compatible photoelectric architectures for German and Swiss medical device sterilization equipment producers, where EU MDR documentation requirements extend qualification timelines for non-captive suppliers. Pursue direct OEM contracting models to capture margin compression from traditional distribution channels.
For Investors and Strategic Acquirers: Korean suppliers establishing dedicated METI efficiency testing facilities in Gyeonggi-do is the leading indicator that Japanese market access preservation commands strategic premium. Long-term viability favors semiconductor process capabilities over discrete component sourcing expertise. Target acquisition archetypes include silicon photonics foundries and ultraviolet LED packaging specialists. Watch for JIS-compliant product development acceleration among domestic Japanese manufacturers as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Monolithic integration unifies emitter-detector supply chains for sub-millimeter gap medical applications. |
| METI Efficiency Certification Acceleration | JIS-compliant product development preserves public procurement eligibility in Nagoya industrial clusters. |
| Direct OEM Contracting Expansion | Mid-tier robotics manufacturers in Seoul bypass Arrow and Avnet to consolidate encoder-sensor procurement. |
| Ultraviolet LED Packaging Capability | Autoclave-compatible architectures open FDA device classification pathways for catheter position sensing. |
| Automotive Lidar Sensitivity Transfer | Industrial photodiode specifications migrate to short-range optical sensing in Stuttgart component plants. |
Research Methodology
Document review covered SEC filings from optoelectronics manufacturers, METI efficiency benchmark disclosures, and EU MDR technical documentation requirements, complemented by interviews with factory automation procurement directors, medical device biomedical engineers, and precision machinery OEM technical directors. Secondary validation drew from JIS standard publications, FDA device classification databases, and customs trade data for infrared LED and photodiode components. Bottom-up demand modeling from Shenzhen printer mechanism and Nagoya conveyor system integrators was cross-referenced against top-down market sizing from industrial automation capital expenditure disclosures.
Historical shipment data from slot-type and reflective product architectures was cross-referenced against panel input from motion control system integrators and robotics end-effector manufacturers across the analysis window. Segmentation dimensions modeled include product architecture, detection technology, end-use application, and customer channel structure. CAGRs were derived from unit economics trajectories in infrared versus photoelectric technology tiers, incorporating replacement cycle acceleration from China's MIIT dual carbon mandates and Japan's METI efficiency benchmarks. Industry-specific inputs included hermetic sealing capacity constraints in Hamamatsu precision optics regions and silicon photonics pilot deployment timelines in Greater Boston medical device clusters.
Revisions become necessary when semiconductor foundries achieve cost parity in monolithic emitter-detector integration, or when EU MDR documentation requirements extend qualification timelines beyond current modeling assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Fiber Preform Market
Optical Components
Prism Coupler Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Ellipsometer Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Pancake Optical Module Market
Optical Components
Bio-Optics Market
Optical Components
Optical Isolator Market
Optical Components
Optical Modulators Market
Optical Components
Optical Cross Connect Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Europe Tunable Laser Market