
 North America Lithium Niobate Modulator Market | 2026-2036
North America Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium Niobate Modulator Market Analytics
Software-defined reconfigurability is broadening what customers purchase beyond discrete hardware. THORLABS leverages vertically integrated crystal growth to control substrate quality from ingot to finished device. iXblue Group anchors its position through specialized fabrication for defense and quantum research applications. Lumentum Operations LLC competes by extending its telecom laser portfolio into matched modulator-transceiver subsystems.
Lithium niobate modulators are electro-optic devices fabricated from LiNbO3 crystals that convert electrical signals into optical phase or intensity modulation through the Pockels effect, typically operating at wavelengths near 1550 nm with bandwidths exceeding 40 GHz for coherent communication systems. The coherent modulator type dominates current revenue as 400G/800G fiber deployments multiply across carrier networks. High-speed variants are displacing legacy alternatives in data center interconnects where power efficiency and footprint constraints tighten. Silicon photonics integration represents the fastest-growing technology trajectory as heterogeneous packaging matures for co-packaged optics architectures.
FCC spectrum allocations and NIST quantum technology standards shape product roadmaps and testing protocols for domestic suppliers. FDA device regulations influence medical imaging and sensing applications where lithium niobate modulators enable optical coherence tomography systems. EPA hazardous material rules affect crystal doping chemistries and wafer processing waste streams throughout the manufacturing chain. Stakeholders must monitor thin-film process yields and foundry capacity commitments as the technology transitions from research to volume production.
Market Dynamics
Thin-film lithium niobate on insulator platforms are compressing design cycles and forcing foundry capacity commitments as telecommunications carriers accelerate 400G/800G coherent deployment timelines.
Growth Catalysts
- FCC Spectrum Allocations:Mid-band 5G spectrum releases in the United States are accelerating fiber backhaul buildouts that require high-bandwidth electro-optic modulation.
- Data Center Interconnect Scaling:Texas and California hyperscale clusters are driving procurement of compact, power-efficient modulators for intra-campus optical links.
- Silicon Photonics Heterogeneous Integration:Co-packaged optics architectures are absorbing thin-film lithium niobate modulators as standard building blocks for next-generation transceivers.
Market Restraints
- Foundry Concentration Risk:Thin-film lithium niobate wafer processing capacity concentrates among a limited set of North American specialty foundries.
- EPA Hazardous Material Rules:Crystal doping chemistries and wafer processing waste streams face escalating compliance costs throughout the manufacturing chain.
- Silicon Photonics Substitution:Silicon-based modulators threaten to displace lithium niobate in cost-sensitive, lower-bandwidth data center applications.
Strategic Opportunities
- NIST Quantum Technology Standards:Federal quantum research funding is creating dedicated demand channels for specialized lithium niobate modulators in quantum sensing and computing testbeds.
- Defense and Aerospace Applications:Secure communication programs across the United States and Canada are sourcing radiation-hardened, wide-temperature-range modulator variants.
- Coherent Optical Sensing:Lidar and optical coherence tomography systems in automotive and medical verticals represent underpenetrated end-use categories for high-speed modulation.
Industry Challenges
- Thin-Film Process Yield Optimization:Etching and bonding processes for sub-micron lithium niobate films require specialized equipment and process control expertise that remains scarce.
- Packaging Integration Complexity:Thermal expansion mismatches between lithium niobate, silicon substrates, and organic interposers complicate reliability qualification for co-packaged optics.
- Multi-Physics Simulation Talent Gap:Electro-optic-mechanical co-design capabilities are concentrated among a small pool of specialists with experience in both photonics and RF engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium Niobate Modulator Market |
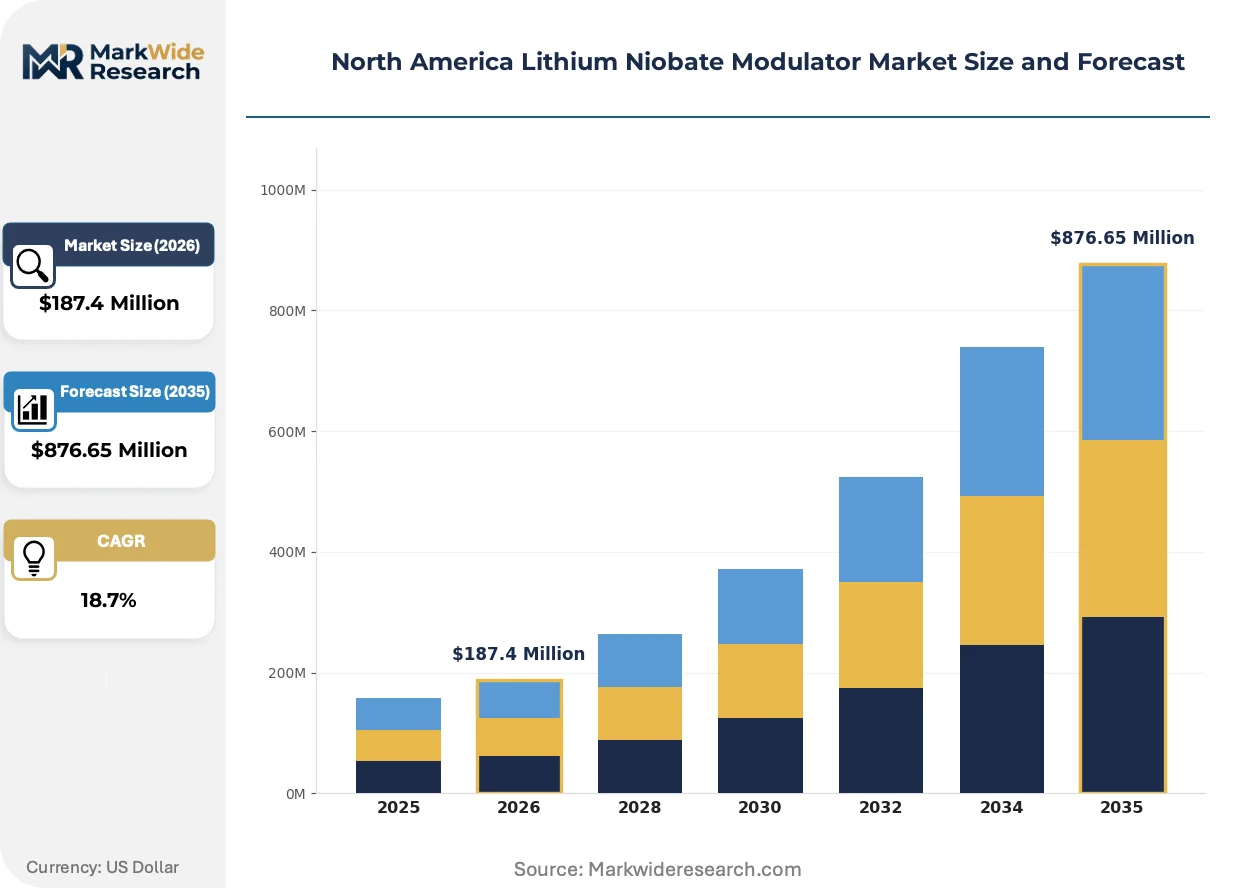
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Modulator Type: Coherent, High-Speed, Electro-Optic, Integrated End User: Telecommunications, Data Centers, Aerospace, Medical Devices Application: Optical Communication, Signal Processing, Quantum Computing, RF Systems Technology: Silicon Photonics, Fiber Optics, Free-Space Optics, Digital Signal Processing |
| Companies Covered | THORLABS, iXblue Group, Gooch & Housego plc, Fujitsu Optical Components Ltd, Lumentum Operations LLC, EOSPACE, Inc., Fabrinet Inc., Beijing Panwoo Integrated Optoelectronic Inc., HyperLight Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium Niobate Modulator Market Evolving Landscape
Modulator architectures are converging with semiconductor packaging roadmaps, creating new performance tiers that separate defense-qualified, telecom-grade, and sensing-optimized product lines.
Thin-film lithium niobate on insulator is absorbing the functional requirements previously served by bulk titanium-diffused devices while enabling 100 GHz-class bandwidth in footprints compatible with silicon photonics interposers. Hyperscale data center operators and coherent DSP vendors are validating these platforms for 800G and 1.6T transceiver generations. The structural consequence is absorption of legacy supply chains into vertically integrated photonics foundry models.
NIST quantum technology standards are mandating specific electro-optic performance benchmarks for quantum key distribution and squeezed light generation systems. Domestic suppliers are redesigning bias stability and extinction ratio specifications to meet these federal testing protocols. Defense and research laboratory procurement now prioritizes modulators with documented traceability to NIST-calibrated reference systems.
Carrier procurement of discrete modulator components is contracting in favor of matched modulator-transceiver subsystems from integrated photonics vendors. This bundling trend compresses the addressable market for standalone modulator suppliers while expanding the value captured by subsystem integrators. The shift is most visible in California's Silicon Valley photonics corridor where coherent optical engine vendors dominate vendor selection processes.
North America Lithium Niobate Modulator Market Segmentation
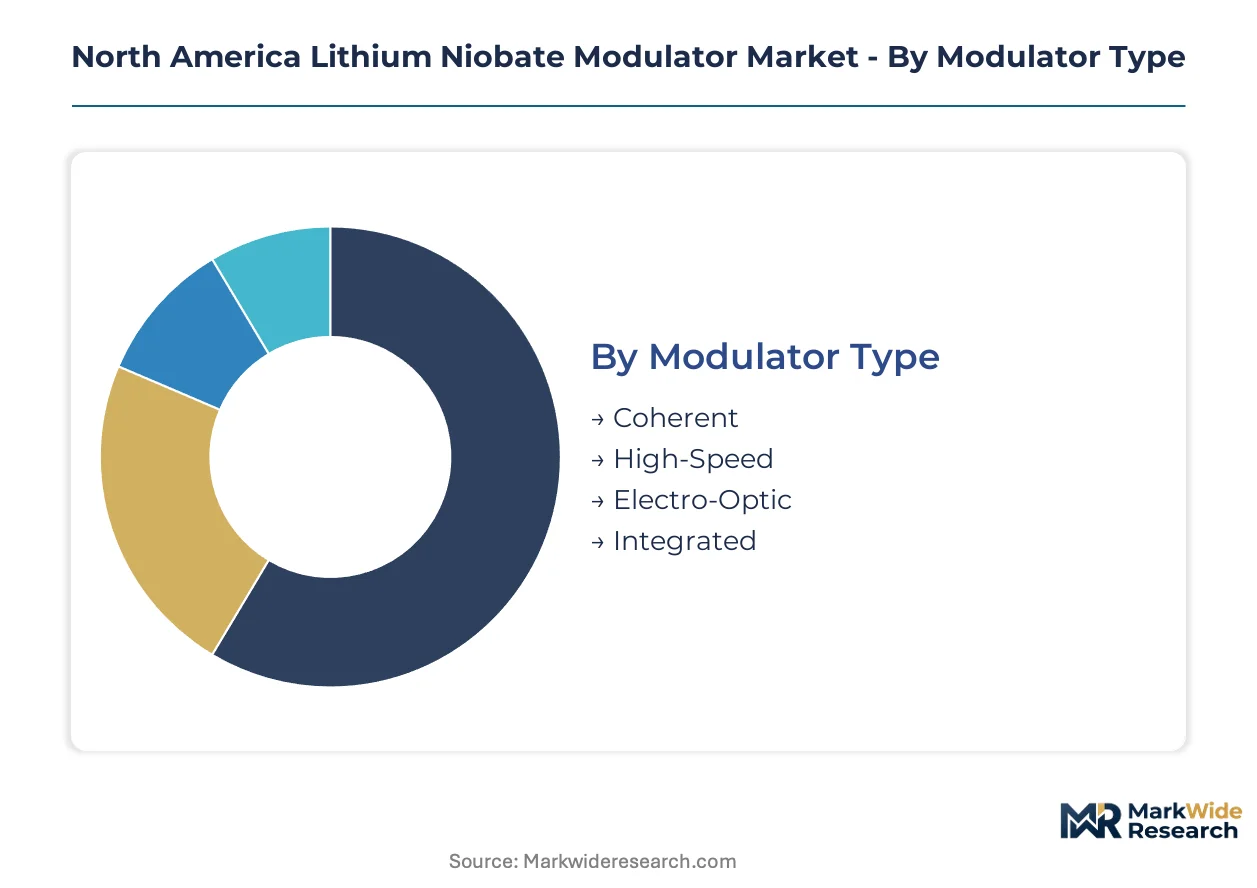
Segmentation in the North America lithium niobate modulator market reveals how thin-film process capabilities and foundry specialization concentrate supply among distinct performance tiers. Procurement patterns diverge sharply between telecom carriers seeking coherent modulation and defense contractors requiring radiation-hardened variants.
Modulator Type:
Supply concentration among specialty foundries in California and Texas favors high-bandwidth architectures with proven heterogeneous integration pathways.
- Coherent:These modulators encode phase and amplitude information simultaneously for 400G/800G fiber systems. Demand clusters with telecommunications carriers deploying C-band coherent transceivers across FCC-licensed spectrum allocations. The Pockels effect in lithium niobate enables the linear electro-optic response that dense wavelength-division multiplexing requires.
- High-Speed:Devices exceeding 40 GHz bandwidth address intra-data-center interconnects where power efficiency and footprint constraints tighten. Texas hyperscale clusters are absorbing these variants for campus-scale optical switching fabrics.
- Electro-Optic:Standard intensity modulators serve test and measurement equipment with lower bandwidth requirements.
- Integrated:Co-packaged modulator-DSP combinations are gaining traction among subsystem vendors in Silicon Valley.
Coherent modulators absorb the bulk of installed capacity; high-speed variants are expanding most quickly.
End User:
Cost tier differentiation separates defense-qualified products from commercial-grade alternatives, with certification overhead driving 3-5x price multiples.
- Telecommunications:Carriers building 5G backhaul networks procure coherent modulators in volume for mid-band spectrum deployments. Verizon, AT&T, and T-Mobile fiber buildouts across the United States concentrate demand with integrated photonics vendors.
- Data Centers:Hyperscale operators in California and Texas prioritize power efficiency and thermal stability for co-packaged optics architectures. Microsoft, Amazon, and Google procurement specifications are standardizing thin-film lithium niobate interfaces.
- Aerospace:Radiation-hardened variants serve secure satellite communication programs with extended temperature range requirements.
- Medical Devices:FDA-regulated optical coherence tomography systems employ precision modulators for biomedical imaging applications.
Telecommunications absorbs the bulk of installed capacity; data centers are climbing the fastest.
Application:
Volume concentration tracks the 400G/800G coherent upgrade cycle, with emerging applications requiring specialized bias stability specifications.
- Optical Communication:Fiber backhaul and data center interconnects dominate procurement volumes. Carrier network upgrades and hyperscale campus expansions across the United States and Canada absorb the majority of coherent modulator output.
- Signal Processing:RF-over-fiber systems for antenna remoting and electronic warfare applications require wideband linearity. Defense contractors in California and Massachusetts specify these for radar and communication testbeds.
- Quantum Computing:NIST-traceable squeezed light generation and quantum key distribution systems demand ultra-low noise performance.
- RF Systems:Microwave photonic links for satellite ground stations and military platforms utilize intensity modulation with direct detection.
Optical communication absorbs the bulk of installed capacity; quantum computing represents the steepest expansion trajectory.
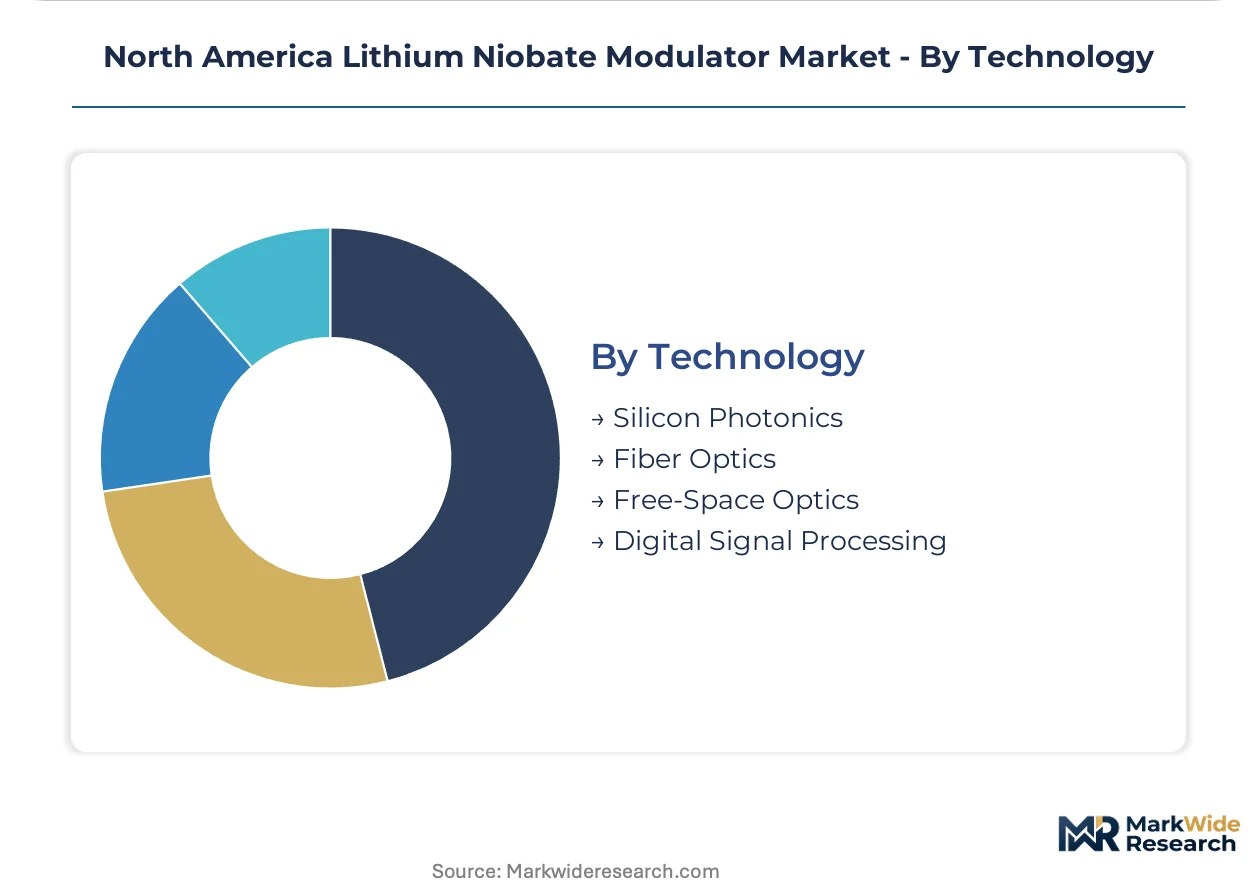
Technology:
Integration maturity separates volume-production platforms from emerging architectures still qualifying for commercial deployment.
- Silicon Photonics:Heterogeneous integration of thin-film lithium niobate on silicon interposers enables co-packaged optics at 800G and 1.6T data rates. Foundry partnerships between specialty lithium niobate processors and CMOS fabs in California and Texas are scaling this platform.
- Fiber Optics:Conventional pigtailed modulators with fiber-coupled input/output remain standard for laboratory and test equipment applications.
- Free-Space Optics:Lidar and optical sensing systems employ bulk crystal modulators with free-space beam paths.
- Digital Signal Processing:Coherent DSP integration with modulator front-ends is converging into single-package optical engines.
Silicon photonics absorbs the bulk of installed capacity; free-space optics is gaining share fastest in automotive lidar applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of lithium niobate modulator output across North America, while Canada and Mexico contribute specialized manufacturing capabilities and emerging demand channels respectively.
United States
Telecommunications carriers and hyperscale data center operators drive procurement volumes. FCC mid-band 5G spectrum allocations accelerate fiber backhaul buildouts requiring high-bandwidth electro-optic modulation. California's Silicon Valley photonics corridor anchors thin-film lithium niobate foundry capacity, with Texas data center clusters absorbing high-speed variants for campus-scale optical switching.
Canada
Defense contractors and quantum research laboratories generate specialized demand for radiation-hardened and NIST-traceable devices. Health Canada regulations govern medical imaging applications where lithium niobate modulators enable optical coherence tomography systems. Ontario and Quebec host precision photonics manufacturing serving secure satellite communication programs.
Mexico
Nearshoring trends in electronics assembly create emerging demand for fiber-optic components in manufacturing corridors. The country's national telecommunications regulator oversees spectrum policy affecting fiber deployment timelines. Baja California and Mexico City metro areas concentrate contract manufacturing partnerships with U.S. subsystem integrators.
North America Lithium Niobate Modulator Market Competitive Landscape
Top-tier vendors anchor the integrated photonics segment, while specialized crystal growers and defense-qualified fabricators occupy distinct competitive tiers. The vendor base stratifies across three archetypes: vertically integrated photonics foundries controlling substrate-to-device production, subsystem integrators bundling modulators with transceiver engines, and boutique specialists serving quantum and aerospace applications. Dominant competitive moves include foundry capacity commitments for thin-film lithium niobate processing and strategic partnerships between specialty crystal growers and CMOS packaging houses.
Within the integrated photonics tier, Lumentum Operations LLC and THORLABS represent contrasting scale positions, while iXblue Group exemplifies the defense-specialist archetype. These three entities collectively illustrate how competitive positioning diverges between volume-driven telecom supply and mission-qualified research applications.
| Leading Market Players |
|---|
| THORLABS |
| iXblue Group |
| Gooch & Housego plc |
| Fujitsu Optical Components Ltd |
| Lumentum Operations LLC |
| EOSPACE, Inc. |
| Fabrinet Inc. |
| Beijing Panwoo Integrated Optoelectronic Inc. |
| HyperLight Corporation |
| Others |
Value Network & Pricing Analysis
Thin-film lithium niobate on insulator migration is compressing unit economics while concentrating bargaining power among California and Texas foundries with qualified sub-micron etching capabilities. The shift from titanium-diffused bulk crystals to bonded nanoscale films simultaneously raises processing yields and locks procurement into multi-year capacity commitments with specialty photonics foundries.
Pricing Analysis
Margin tightening in defense-qualified tiers reflects NIST calibration traceability requirements and radiation-hardening certification overhead. Three-tier pricing structure across mission-qualified, telecom-grade, and sensing-optimized levels separates products by bias stability specifications and temperature range validation. Cost compression in commercial coherent modulators accelerates because hyperscale data center operators are standardizing thin-film interfaces and consolidating vendor lists. Telecommunications carriers exhibit highest price sensitivity due to volume procurement of matched modulator-transceiver subsystems, while quantum research laboratories demonstrate lowest sensitivity given federal funding insulation and ultra-low noise performance requirements.
Supply Chain Analysis
Dual-sourcing mandates from defense contractors and hyperscale operators are forcing qualification of secondary thin-film lithium niobate foundries beyond California's primary cluster. Geographic supply concentration centers on the United States for specialty photonics foundries, Japan for high-purity lithium niobate crystal ingots, and Germany for precision dicing and polishing equipment. Raw material dependencies include congruent lithium niobate boules, platinum electrode metallization, and silicon-on-insulator carrier wafers. Single-source vulnerability concentrates in sub-micron bonding equipment qualified for lithium niobate films. Distribution runs through direct OEM contracts for volume tiers and specialized distributors for research and test equipment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA hazardous material compliance for crystal doping chemistries creates a barrier-to-entry moat that favors incumbents with established waste stream management and documented environmental permits.
For Market Incumbents: Hedge against silicon photonics substitution by deepening captive supply of thin-film lithium niobate wafers through foundry partnerships in Texas. Lock in multi-year capacity reservations with specialty etching houses before qualification backlogs extend. Reinforce position in NIST-traceable quantum applications where federal standards create sticky demand channels resistant to price erosion. For New Entrants and Emerging Players: Enter via automotive lidar free-space optics applications where incoherent modulation requirements lower the performance threshold for thin-film qualification. Target Mexico's nearshoring corridors for contract assembly partnerships with U.S. subsystem integrators seeking geographic diversification. Pursue direct sales to quantum computing testbeds as the most penetrable vertical given fragmented procurement and performance-driven selection criteria. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated photonics vendors seeking modulator-transceiver bundling capabilities. Long-term viability hinges on foundry capacity access rather than discrete device IP, favoring targets with qualified thin-film process flows and existing CMOS packaging partnerships. Watch thin-film process yield inflection at 8-inch wafer scale as the signal separating research-stage from volume-production valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Foundry Partnership | Secures sub-micron etching capacity for 800G coherent transceiver roadmaps at Texas and California facilities. |
| NIST Traceability Certification | Unlocks federal quantum research funding channels requiring documented electro-optic performance benchmarks. |
| Co-Packaged Optics Integration | Aligns modulator architectures with DSP vendor roadmaps for 1.6T generation transceiver engines. |
| Defense Qualification Investment | Captures radiation-hardened procurement from secure satellite programs with 3-5x price premiums. |
| Automotive Lidar Qualification | Expands addressable market into free-space modulation for next-generation autonomous vehicle sensing. |
Research Methodology
Document review covered SEC filings from photonics component vendors, FCC spectrum allocation records, and NIST quantum technology standards documentation, complemented by interviews with thin-film process engineers at specialty foundries, procurement managers at hyperscale data center operators, and program officers at federal research laboratories. Secondary validation drew from EPA hazardous material compliance databases, telecommunications carrier capex disclosures, and photonics industry association technical reports. Bottom-up unit economics for modulator production were triangulated against top-down market sizing from carrier deployment schedules and data center interconnect scaling plans.
Cross-referencing historical thin-film lithium niobate adoption curves against panel input from coherent DSP vendors and subsystem integrators anchored the projection framework. Segmentation dimensions modeled include modulator type, end user vertical, application category, and technology platform across the analysis window. CAGRs were derived from weighted capacity expansion timelines and foundry yield improvement trajectories. Industry-specific forecast inputs incorporated FCC mid-band 5G deployment schedules and hyperscale data center campus expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry yield stagnation or accelerated silicon photonics substitution in data center interconnects. Deviation in EPA enforcement intensity for crystal processing waste streams would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Global Optical Diode Market
Optical Components
Optical Transmitter Market
Optical Components
Ring Panel Filters Market
Optical Components
Photointerrupter Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Europe Optical Film Market
Optical Components
Optical Sensor Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
North America Optical Film Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market