
 Spectroradiometers Market | 2026-2036
Spectroradiometers Market Size, Share, and Industry Trends Forecast 2026-2036
Spectroradiometers Market Intelligence
Compliance with the ISO/IEC 17025 standard for calibration laboratory competence is reorganizing the competitive landscape for spectroradiometer manufacturers. Instrument Systems GmbH leverages its specialization in high-end display and LED measurement to meet stringent client requirements. Konica Minolta, Inc. sustains its market position through a broad portfolio covering multiple applications, from lighting to color science. HORIBA, Ltd. competes on the basis of its advanced grating and detector technologies for research-grade instrumentation.
A spectroradiometer is an instrument designed to measure the spectral power distribution of a light source, quantifying absolute radiometric values like irradiance or radiance. These devices operate across specific wavelength ranges, often 380-780 nm, using a diffraction grating to disperse light onto a sensor. While bench-top units serve research laboratories, the portable and handheld product types are expanding rapidly for field use. Demand from lighting quality control and display calibration applications continues to anchor the market.
Product compliance with the EU's CE marking directives, particularly for electromagnetic compatibility, is a prerequisite for market access in Europe. Traceability to national standards, such as those maintained by the US National Institute of Standards and Technology (NIST) or compliance with China's GB standards, dictates instrument credibility for quality assurance applications. Vendor selection will increasingly hinge on the ability to provide accredited, in-house calibration services and documented measurement uncertainty.
Market Dynamics
The spectroradiometer market's structure is being defined by the dual pressures of advanced manufacturing and regulatory oversight. Demand for absolute radiometric accuracy in micro-LED display calibration and horticultural lighting is converging with stringent compliance mandates like the EU's RoHS directive.
Growth Catalysts
- Solid-State Lighting:The proliferation of LED lighting mandates precise spectral measurement for quality control, ensuring color consistency and validating performance across global supply chains.
- Advanced Display Metrology:Production of OLED and micro-LED panels in South Korea and Taiwan requires high-accuracy instruments for color gamut verification and uniformity testing.
- EU Regulatory Compliance:The RoHS directive influences sensor material selection, pushing manufacturers toward compliant designs for access to the European market.
Market Restraints
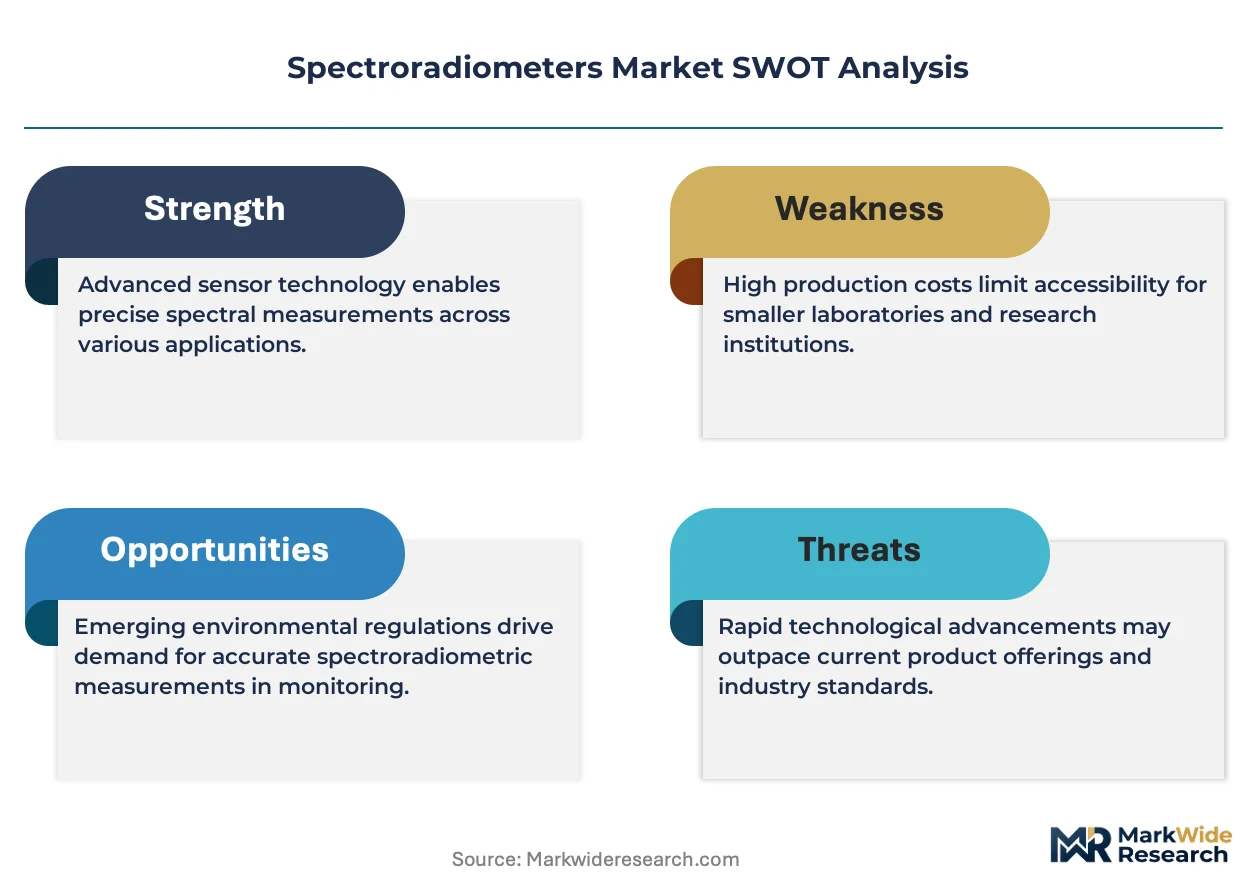
- High Instrument Cost:The capital expenditure for research-grade spectroradiometers with low measurement uncertainty limits adoption by smaller labs and manufacturers with constrained budgets.
- Complex Calibration Requirements:Maintaining traceability to national standards, such as those from NIST or Germany's PTB, necessitates frequent and costly recalibration by accredited laboratories.
- Threat from Colorimeters:For non-critical color assessment, lower-cost colorimeters offer a sufficient alternative, capping spectroradiometer demand in less demanding quality control applications.
Strategic Opportunities
- Biomedical Applications:New uses in medical diagnostics, including non-invasive tissue analysis and fluorescence measurements for point-of-care testing, represent a significant growth frontier.
- AI-Powered Analytics:Integrating machine learning for automated spectral data analysis and anomaly detection can create value-added software services and improve operational efficiency for end-users.
- Automotive Sector Expansion:Growth in advanced automotive lighting manufacturing in India and Mexico creates demand for field-portable and in-line spectroradiometers for quality assurance.
Industry Challenges
- Metrology Talent Scarcity:A shortage of technicians and engineers with expertise in optical metrology and ISO/IEC 17025 accredited calibration hinders effective instrument operation and data interpretation.
- Standardization for Novel Sources:Developing consensus-based measurement standards for emerging technologies like micro-LEDs is slow, creating uncertainty for instrument design and data comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectroradiometers Market |
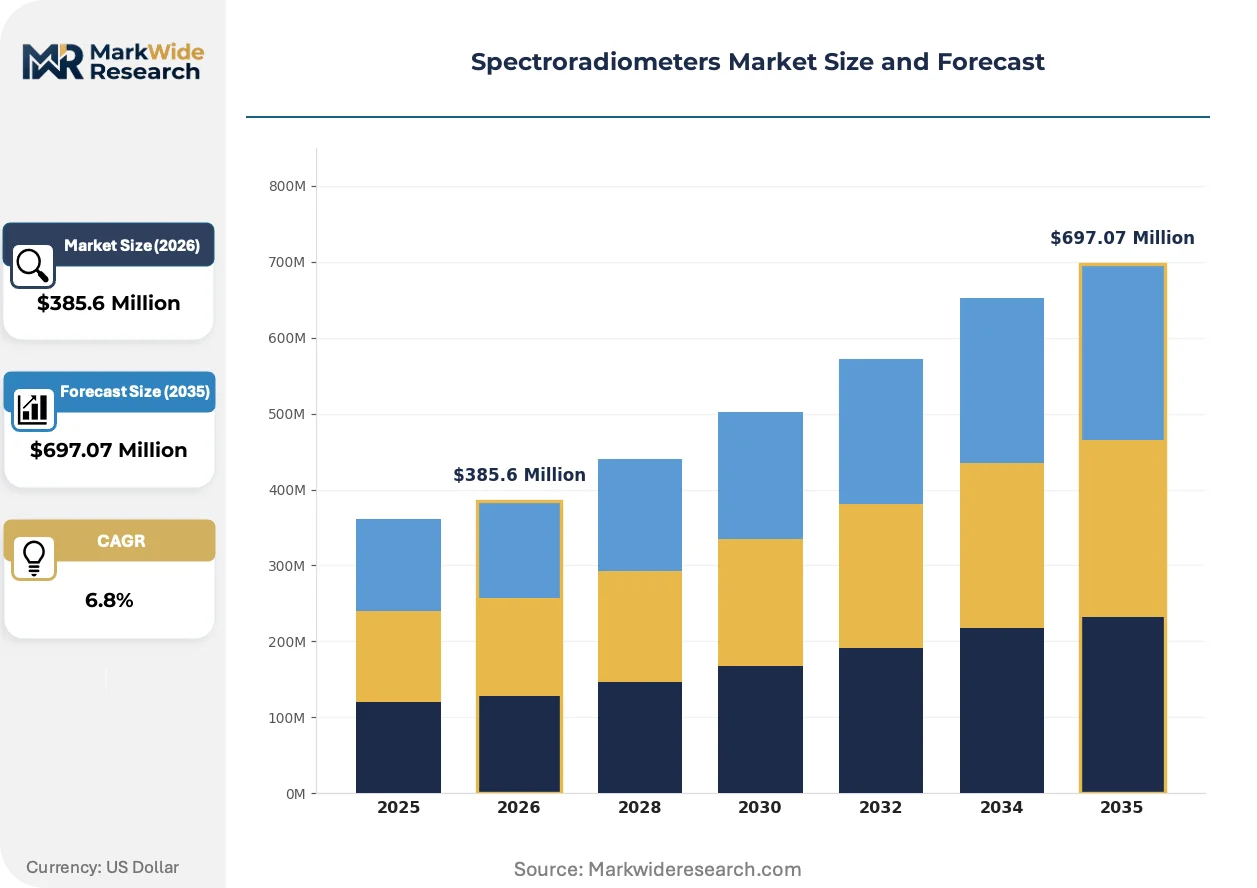
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Handheld, Portable, Imaging, Fiber Optic Technology: Grating, Fourier Transform, Filter-based, CCD Array, CMOS Sensor Application: Lighting Quality Control, Display Calibration, Solar Energy Research, Environmental Monitoring, Color Matching End User: Research Laboratories, Quality Assurance Labs, Photonics Manufacturers, Optical Component Producers, Academic Institutions |
| Companies Covered | Konica Minolta, Inc., Instrument Systems GmbH, ABB Ltd., HORIBA, Ltd., Apogee Instruments, Inc., Delta Ohm, EKO Instruments, Topcon Technohouse Corporation, Malvern Panalytical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectroradiometers Market Strategic Shifts & Innovations
The evolution of spectroradiometers reflects a pivot toward application-specific instrumentation and greater portability. This enables sophisticated spectral analysis to move from dedicated laboratories to manufacturing floors and field environments, altering traditional workflows.
Cooled CMOS image sensors are the preferred detector technology in many new instrument designs, offering performance and cost balance. Manufacturers of portable and inline systems adopt these sensors for fast measurement speeds and compact size. This solid-state technology is displacing older scanning monochromator designs in high-volume industrial and field-based applications.
Compliance with the ISO/IEC 17025 standard for calibration laboratory competence is a key purchasing criterion. This mandate ensures traceable measurement results with documented uncertainty, critical for quality management systems. The standard affects vendors targeting automotive and display manufacturing, forcing investment in accredited in-house calibration services.
Vendor selection increasingly depends on the availability of accredited, in-house calibration services. End-users in high-volume manufacturing are consolidating suppliers, preferring providers that offer a complete package of hardware, software, and ongoing calibration. This preference is most pronounced in Germany's photonics industry and South Korea's display sector.
Spectroradiometers Market Segmentation
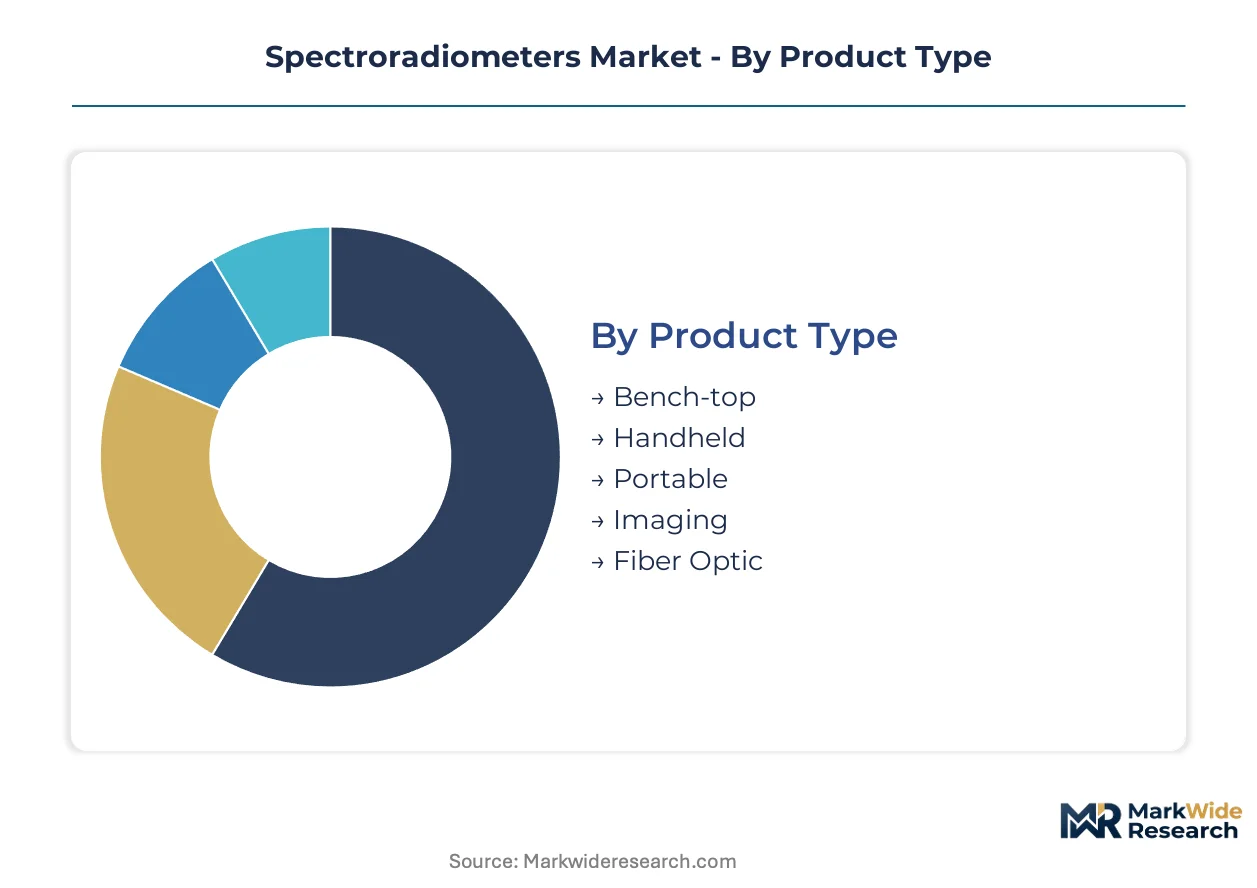
The spectroradiometers market is structured across diverse product types, core technologies, distinct applications, and varied end-user segments. Understanding these distinctions reveals specific demand patterns and areas of intense innovation. This segmentation highlights where value creation and competitive differentiation primarily occur within the industry.
Product Type:
Margin pools within the product type category often concentrate in specialized, high-precision instruments that cater to demanding scientific and industrial requirements.
- Bench-top:Bench-top units provide the highest accuracy and stability, typically featuring robust optical designs and advanced detector cooling. Demand is concentrating in research laboratories and national metrology institutes for fundamental spectral characterization and primary calibration.
- Handheld:Handheld spectroradiometers offer portability and convenience for field measurements and quick quality checks. Their demand is accelerating in lighting quality control for solid-state lighting installations across diverse commercial and industrial settings.
- Portable:Portable devices balance accuracy with mobility for on-site quality assurance in manufacturing environments.
- Imaging:Imaging spectroradiometers capture spatial spectral data, essential for advanced display metrology and material analysis.
- Fiber Optic:Fiber optic units allow remote sensing in harsh or inaccessible environments, common in industrial process monitoring.
Bench-top units hold installed capacity. Handheld devices are rotating up the share rankings.
Technology:
Cost tiering across technologies reflects the complexity of optical design and detector sophistication, influencing market accessibility and performance benchmarks.
- Grating:Grating-based spectroradiometers use diffraction gratings to disperse light into spectral components, forming the foundational technology for most research-grade instruments. Their demand is concentrating in applications requiring high spectral resolution and accuracy, such as advanced material characterization.
- CMOS Sensor:CMOS sensors are increasingly preferred for their fast measurement speeds, compact size, and cost-effectiveness in portable and inline systems. Demand is accelerating for these sensors in high-volume industrial quality control and field-based applications.
- Fourier Transform:Fourier Transform spectroradiometers deliver high resolution and broad spectral coverage, primarily for scientific research.
- Filter-based:Filter-based systems offer simplicity and cost efficiency for less demanding spectral analysis tasks.
- CCD Array:CCD array detectors provide good sensitivity and are widely used in many established spectroradiometer designs.
Grating technology maintains a strong presence in high-end instrumentation. CMOS sensor technology exhibits the steepest expansion trajectory.
Application:
Application volume largely drives innovation, particularly in areas requiring stringent quality assurance and compliance with evolving industry standards.
- Lighting Quality Control:Lighting quality control applications demand precise spectral measurements to ensure color consistency and validate performance of LED sources. Demand here is concentrating due to the proliferation of solid-state lighting across global supply chains.
- Display Calibration:Display calibration for OLED and micro-LED panels necessitates high-accuracy instruments for color gamut verification and uniformity testing. This application's demand is accelerating in manufacturing hubs like South Korea and Taiwan.
- Solar Energy Research:Solar energy research uses spectroradiometers to characterize solar simulators and photovoltaic cell efficiency.
- Environmental Monitoring:Environmental monitoring employs spectral analysis for atmospheric composition and water quality assessment.
- Color Matching:Color matching applications ensure consistency in industrial processes, such as paint and textile manufacturing.
Lighting quality control represents a foundational market segment. Display calibration is gaining share fastest due to new panel technologies.
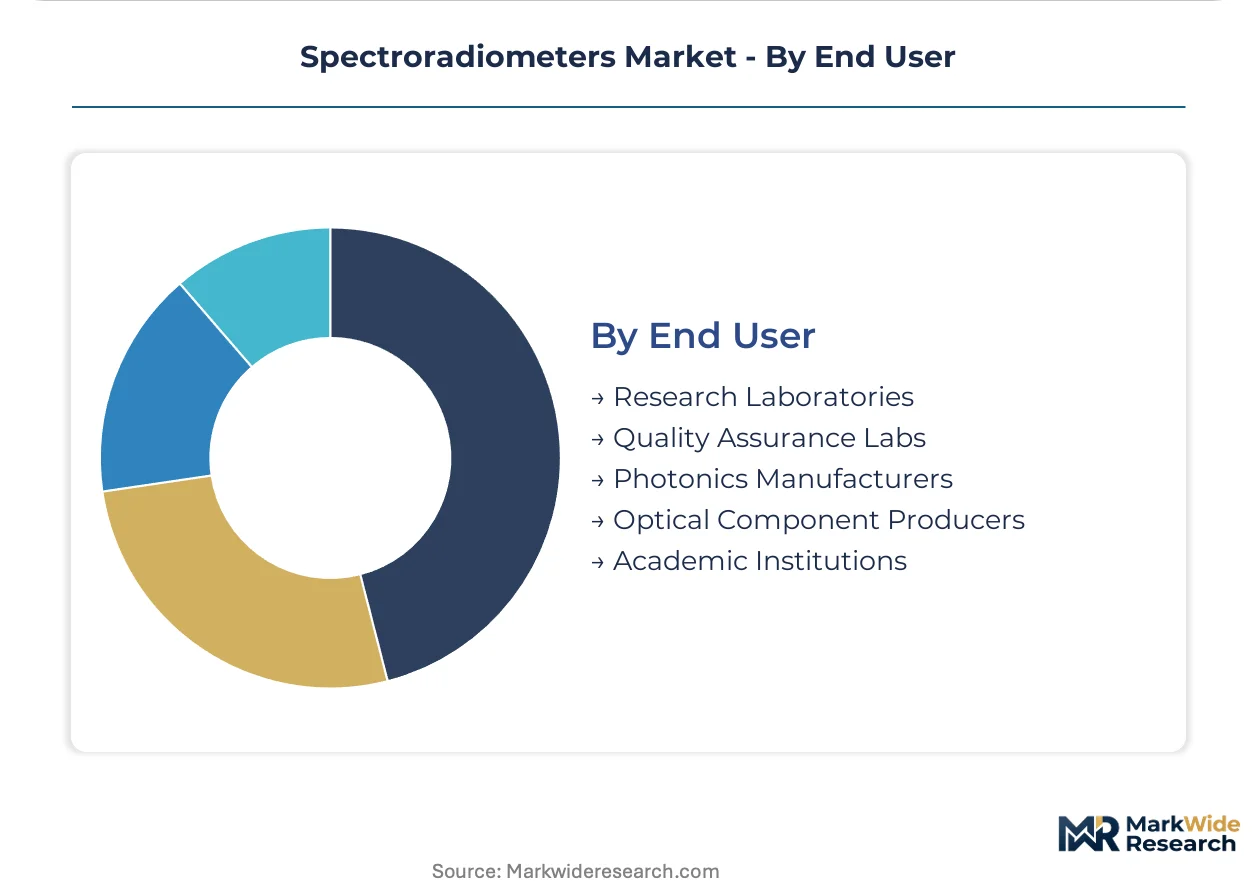
End User:
Customer type dictates instrument specifications, with research institutions requiring maximum flexibility and manufacturers demanding speed and robustness for production environments.
- Research Laboratories:Research laboratories require highly accurate, often bench-top spectroradiometers for fundamental studies and advanced material characterization. Their demand focuses on instruments with broad spectral range and high resolution for scientific discovery.
- Quality Assurance Labs:Quality assurance labs utilize spectroradiometers for product verification and compliance testing in manufacturing environments. Demand from these labs is concentrating on instruments that offer traceable measurements and rapid throughput for production lines.
- Photonics Manufacturers:Photonics manufacturers integrate spectroradiometers for in-line quality control of optical components.
- Optical Component Producers:Optical component producers use these devices to verify filter characteristics and coating performance.
- Academic Institutions:Academic institutions employ spectroradiometers for teaching, student projects, and basic scientific inquiry.
Research laboratories remain a stable demand source. Photonics manufacturers are increasingly integrating these instruments into production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU's RoHS directive and CE marking compliance reshape material choices and market access for spectroradiometer components. National standards like NIST and China's GB dictate instrument credibility for quality assurance globally. This regulatory environment drives demand for high-precision calibration instruments in key manufacturing hubs.
Germany
Germany's advanced manufacturing sector drives demand for high-precision spectroradiometers in photonics and automotive lighting. The Physikalisch-Technische Bundesanstalt (PTB) ensures metrological traceability for critical calibration services. Photonics clusters around Jena and Berlin integrate these instruments for stringent quality control.
South Korea
South Korea's dominant display panel industry generates significant demand for spectroradiometers in OLED and micro-LED metrology. The country's focus on export-oriented electronics necessitates adherence to international display calibration standards. Manufacturing centers in Gyeonggi Province adopt imaging spectroradiometers for precise color gamut verification.
United States
The United States market sees robust demand from research laboratories and solid-state lighting quality control. NIST provides essential traceability for spectroradiometer calibration, critical for scientific and industrial accuracy. Major research institutions and tech companies in California integrate advanced bench-top units for fundamental spectral characterization.
China
China's vast manufacturing base, particularly in LED lighting and display production, fuels substantial spectroradiometer demand. Adherence to China's GB standards is mandatory for market access and product quality assurance. Industrial zones in the Pearl River Delta integrate inline spectroradiometers for high-volume quality control of optical components.
India
India's expanding automotive lighting manufacturing sector and electronics production drive new demand for portable spectroradiometers. The Bureau of Indian Standards (BIS) promotes quality control in manufacturing, influencing instrument procurement. Automotive hubs in Chennai and Pune adopt these devices for in-line quality assurance of lighting systems.
Spectroradiometers Market Key Industry Players
Listed leaders compete with private specialists across technology sophistication, application breadth, and geographic footprint. The market exhibits a tiered structure, from highly specialized research-grade instrument providers to broader industrial solution suppliers. Key archetypes include precision metrology experts, diversified industrial measurement providers, and application-specific innovators focusing on emerging fields. Companies are increasingly engaging in portfolio diversification, strategic partnerships, and targeted M&A to expand their market reach and technological capabilities.
Specialists in high-end display and LED measurement include Instrument Systems GmbH, which focuses on meeting stringent client requirements. Konica Minolta, Inc. occupies a position as a diversified provider, sustaining its market presence through a broad portfolio spanning multiple applications from lighting to color science. HORIBA, Ltd. represents advanced grating and detector technologies, anchoring research-grade instrumentation for scientific applications. These entities exemplify the diverse approaches to product development and market penetration within the spectroradiometer sector, influencing competitive dynamics across various end-user segments.
| Leading Market Players |
|---|
| Konica Minolta, Inc. |
| Instrument Systems GmbH |
| ABB Ltd. |
| HORIBA, Ltd. |
| Apogee Instruments, Inc. |
| Delta Ohm |
| EKO Instruments |
| Topcon Technohouse Corporation |
| Malvern Panalytical Ltd. |
Cost & Logistics Intelligence
Extended lead times for specialized optical components often reflect concentrated supply chains, which in turn grant pricing power to a few key manufacturers of spectroradiometers. This dynamic influences both instrument cost and market accessibility for end-users.
Pricing Analysis
Certification level (ISO/IEC 17025-grade) creates the primary spread in spectroradiometer pricing, particularly for instruments used in accredited calibration laboratories. The dominant pricing model is per-unit transactional, with high-end research-grade instruments often involving project-based customization and support. Price differentiation stems from technical specifications like spectral resolution and accuracy, alongside bundled after-sales calibration services. Pricing softness runs through portable and handheld segments due to increasing cost-effectiveness of CMOS sensor technology, making smaller labs and manufacturers with constrained budgets the most price-sensitive buyers.
Supply Chain Analysis
Germany and Japan anchor the production of high-precision optical components and specialized diffraction gratings essential for spectroradiometers. The supply chain draws from critical raw materials like rare earth elements for detector manufacturing and high-purity glass for optical lenses. A structural risk is single-source vulnerability for advanced detector technologies, particularly for cooled CMOS sensors. Distribution typically runs through direct sales channels for research-grade systems and established distributor networks for portable and handheld units serving industrial quality control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for a cyclical recovery, driven by the ongoing upgrade cycles in advanced display manufacturing and solid-state lighting infrastructure globally. Opportunities exist for both established players and agile new entrants to capitalize on evolving metrology requirements.
For Market Incumbents:Fortify existing market positions by increasing in-house control over specialized optical component manufacturing, mitigating supply chain risks. Invest heavily in accredited in-house calibration services to meet stringent ISO/IEC 17025 requirements, countering the threat from less precise, lower-cost alternatives. Expanding software analytics platforms with AI capabilities will also enhance instrument value and operational efficiency. Focus R&D on next-generation micro-LED metrology to maintain a competitive edge against emerging display technologies.
For New Entrants and Emerging Players:Lead with application-specific solutions tailored for underpenetrated segments like biomedical diagnostics and advanced automotive lighting quality assurance. The most penetrable segment for new players remains portable and handheld devices, particularly for field use in emerging markets. Focus on integrated AI-powered spectral analysis software to offer differentiated value, simplifying complex data interpretation for end-users. Develop cost-effective, compliant designs for the EU market, bypassing high capital expenditure barriers.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across the high-precision display metrology sub-segment, signaling long-term growth potential. The market remains viable over a 5-10 year window due to persistent demand for quality control in advanced manufacturing. Acquisition targets should include specialists in advanced detector technology or firms offering AI-driven spectral data analytics platforms. The signal to watch is increased M&A activity among software and sensor integration firms, indicating consolidation around key technological capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Accredited Calibration Services | Ensures compliance with ISO/IEC 17025, critical for quality management systems. |
| Develop AI-Powered Software Suites | Enhances operational efficiency for end-users through automated data analysis. |
| Invest in Micro-LED Metrology R&D | Addresses the specific high-accuracy needs of next-generation display panels. |
| Target Emerging Automotive Markets | Captures demand from advanced lighting manufacturing in India and Mexico. |
| Diversify into Biomedical Diagnostics | Unlocks new growth frontiers in non-invasive tissue analysis and point-of-care testing. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. Primary insights were gathered from R&D directors, quality assurance managers, metrology engineers, and procurement specialists across various end-user segments. Secondary data sources included industry association reports, patent databases, company financial filings, and technical journals. This approach enabled bottom-up aggregation and top-down triangulation for comprehensive market sizing.
The forecast period spans across the analysis window, integrating quantitative models with qualitative market intelligence. Segmentation dimensions modeled include product type, core technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected market expansion scenarios. Key industry-specific forecast inputs included global LED adoption rates and advanced display panel production forecasts from major manufacturing hubs.
The analysis sits within stated boundaries; outcomes outside sustained macroeconomic stability or regulatory continuity would require recalibration. Forecasts reflect assumptions regarding technological evolution and market dynamics. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transmitter Market
Optical Components
Optical Dome Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Optical Interconnect Market
Optical Components
Optical Lens Edger Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Microchannel Plates Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Global Tunable Filter Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Europe Optical Imaging Market
Optical Components
ROADM WSS Component Market
Optical Components
Erbium Oxide Market