
 Digital Sensor Sleeves Market | 2026-2036
Digital Sensor Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Sensor Sleeves Market Insights
Dental supply distribution is fragmenting as group purchasing organizations and direct-to-practice e-commerce platforms erode traditional distributor control. Dentsply Sirona leverages its integrated equipment-and-consumables portfolio to lock in recurring sleeve purchases with imaging system leases. Crosstex International sustains brand loyalty among infection-control officers through transparent lot-traceability documentation. Kerr Totalcare competes on cost-per-procedure metrics that appeal to high-volume dental service organizations.
Digital sensor sleeves are thin, single-use polymeric barriers engineered to enclose intraoral radiographic sensors without compromising image resolution or tactile feedback, typically manufactured from latex-free polyethylene or thermoplastic elastomer via blown-film extrusion with controlled thickness tolerances. The wearable segment dominates unit volumes as chairside clinicians require frequent barrier changes between patients, while the connected sub-category captures expanding margin pools through RFID-enabled inventory tracking that integrates with practice management software. Optical technology leads current installations due to its compatibility with CMOS and PSP sensor architectures, though pressure-sensitive variants are gaining traction in orthodontic practices requiring bite-force measurement during imaging.
FDA 510(k) clearance pathways and EU MDR Class I classification rules govern material biocompatibility and sterility assurance levels for dental barrier products, with ISO 10993 cytotoxicity testing now baseline for market access in both jurisdictions. The EPA maintains oversight of ethylene oxide sterilization residues, pushing manufacturers toward gamma irradiation or electron-beam alternatives. Stakeholders must monitor evolving state-level dental board mandates on single-use versus reprocessable barriers, as California and New York have introduced stricter infection-control audit protocols that favor disposable sleeve adoption.
Market Dynamics
Digital radiography conversion is compressing replacement cycles for infection-control barriers as dental service organizations standardize procurement across multi-site networks, forcing sleeve manufacturers to align production with equipment refresh timelines rather than traditional consumable reorder patterns.
Growth Catalysts
- EU MDR Class I conformity requirements:Stricter biocompatibility documentation is locking out low-cost Asian suppliers and expanding market share for ISO 10993-certified domestic manufacturers in Germany and France.
- CMOS sensor architecture proliferation:Optical-compatible sleeve designs are capturing incremental volume as practices retire phosphor plate systems requiring different barrier geometries.
- California infection-control audit protocols:State dental board mandates on single-use documentation are accelerating disposable sleeve adoption among Los Angeles and San Francisco clinic chains.
Market Restraints
- Ethylene oxide sterilization residue limits:EPA enforcement actions are forcing costly process conversions to gamma irradiation or electron-beam alternatives, compressing margins for mid-tier producers.
- Latex-free elastomer feedstock concentration:Thermoplastic elastomer supply clusters in Southeast Asia create vulnerability to regional logistics disruptions and tariff volatility.
- Reprocessable barrier substitution:Autoclavable silicone sheaths retain foothold in cost-sensitive rural practices and federally qualified health centers despite longer chairside turnaround.
Strategic Opportunities
- RFID-enabled inventory tracking:Connected sleeve sub-categories are integrating with practice management software to capture recurring SaaS revenue streams alongside consumable sales.
- Orthodontic bite-force measurement applications:Pressure-sensitive sensor sleeves are opening procedural expansion beyond diagnostic radiography into treatment monitoring workflows.
- Direct-to-practice e-commerce channels:Platform bypass of traditional dental distributors is enabling margin recovery and customer data ownership for specialized barrier manufacturers.
Industry Challenges
- ISO 10993 cytotoxicity testing bottlenecks:Biocompatibility certification timelines extend six to nine months, delaying product launches and freezing R&D roadmaps during regulatory review.
- Legacy phosphor plate system compatibility:Sleeve manufacturers must maintain dual-format production lines as hybrid practices operate both digital sensors and film-based PSP systems simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Sensor Sleeves Market |
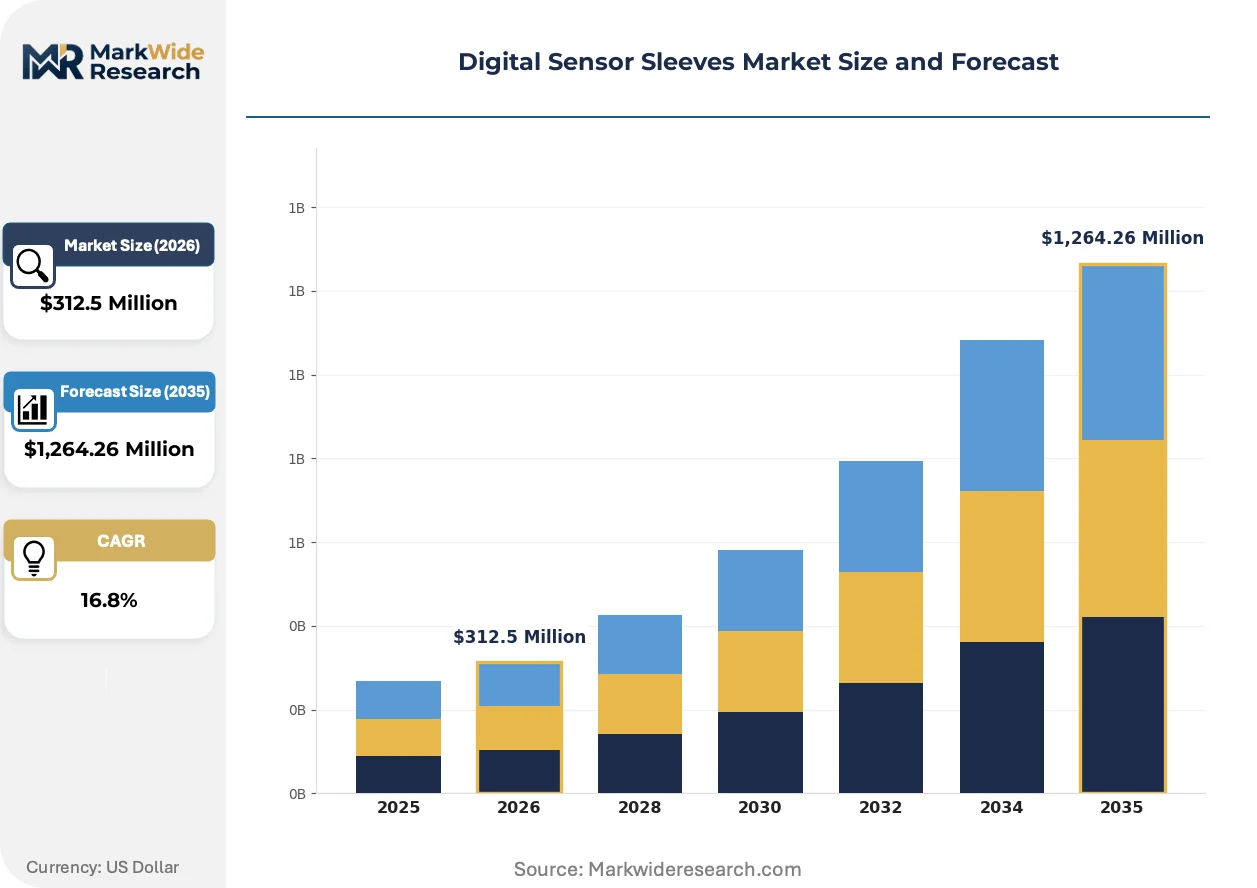
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,264.26 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Non-wearable, Embedded, Connected Technology: Optical, Thermal, Pressure, Chemical End User: Healthcare, Sports, Automotive, Industrial Application: Monitoring, Diagnostics, Tracking, Control |
| Companies Covered | Dentsply Sirona, Crosstex International, Kerr Totalcare, Mydent International, ClikTech, Flow Dental, Hager Worldwide, Brixton, SanaX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Sensor Sleeves Market Trends and Innovations
Material science advances are dissolving the boundary between passive barriers and active data-collection surfaces, while regulatory documentation requirements are shifting competitive advantage toward vertically integrated quality systems.
Thermoplastic elastomer formulations with embedded conductive traces are hybridizing the sensor sleeve from pure physical barrier into a data-capture interface. Orthodontic practices in Japan and Germany are piloting these hybrid designs for real-time bite-force mapping during imaging sequences. The technology is compressing the traditional separation between diagnostic radiography and biometric monitoring equipment categories.
FDA 510(k) clearance pathways are tightening material change notification requirements for polymer formulations used in intraoral devices. Manufacturers must now submit updated biocompatibility profiles for any resin supplier switch, extending qualification cycles. Small and mid-cap sleeve producers are responding by consolidating to single-source resin relationships and captive compounding capabilities.
Group purchasing organizations are consolidating contract authority over infection-control procurement decisions previously managed at the practice level. Dental service organizations with fifty-plus locations are displacing independent distributor relationships with direct manufacturer agreements. This concentration is most visible in Texas and Florida where DSO penetration exceeds national averages.
Digital Sensor Sleeves Market Segmentation
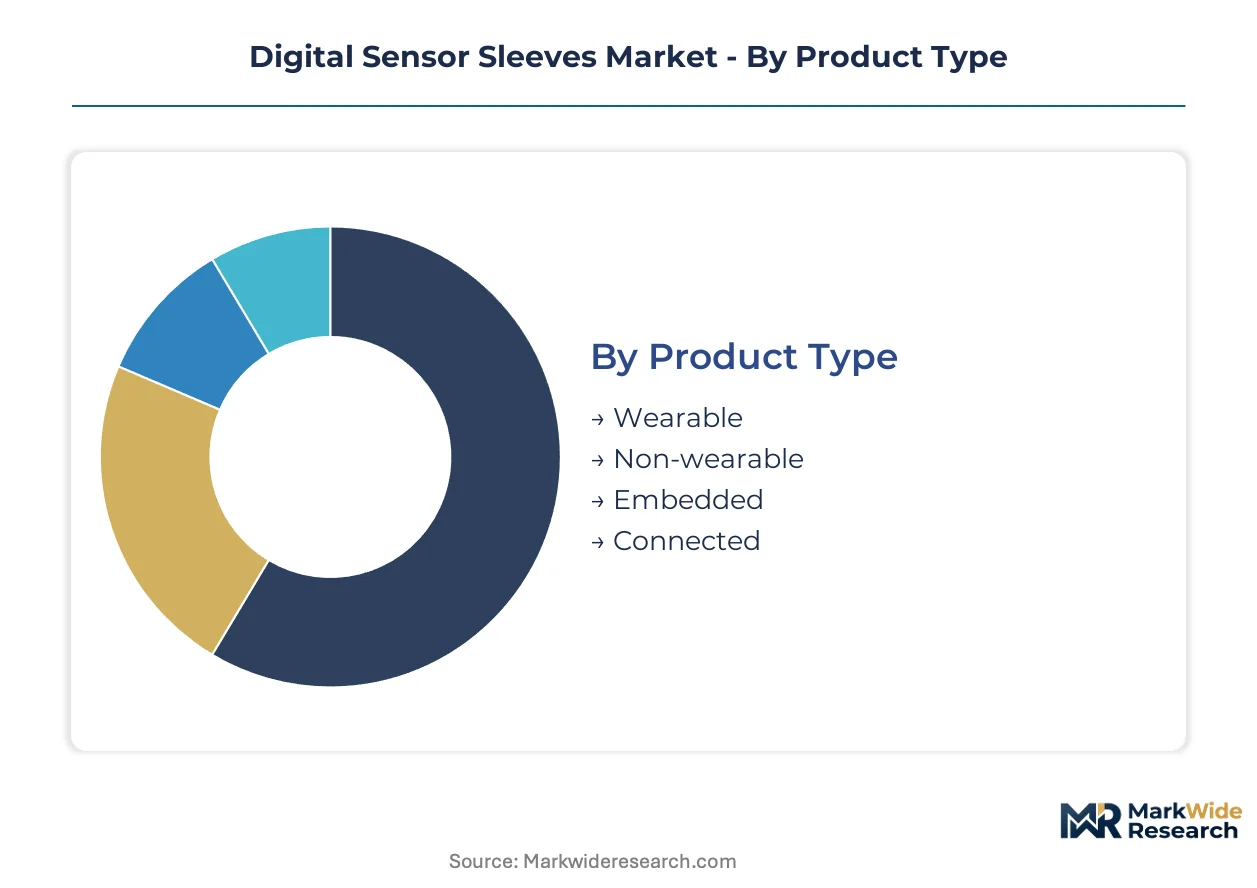
Segmentation in digital sensor sleeves reveals how material specifications and connectivity features align with distinct procurement patterns across dental equipment ecosystems. Manufacturers configure production lines around these divides to match the operational rhythms of high-volume clinic chains against smaller independent practices.
Product Type:
Cost tier determines procurement frequency and margin structure, with single-use disposables dominating recurring revenue against capital-intensive connected systems.
- Wearable:Thin polyethylene barriers designed for direct chairside handling by clinicians during intraoral imaging sequences. Dental service organizations in Germany and the United States standardize on these for infection-control compliance across multi-site networks, with procurement tied to patient volume metrics rather than equipment refresh cycles.
- Connected:RFID-enabled sleeves integrating with practice management software for automated inventory replenishment and usage tracking. These capture expanding margin pools through recurring SaaS revenue streams alongside consumable sales, particularly among Texas and Florida DSOs with centralized procurement authority.
- Non-wearable:Stationary barrier systems for fixed radiography installations requiring less frequent replacement.
- Embedded:Conductive trace formulations enabling bite-force measurement during orthodontic imaging workflows.
Wearable holds installed capacity. Connected is rotating up the share rankings.
Technology:
Application requirements dictate sensor compatibility, with optical designs serving CMOS architectures while pressure-sensitive variants address orthodontic measurement needs.
- Optical:Transparent polymer formulations engineered for minimal X-ray attenuation and unimpeded CMOS sensor signal transmission. Practices across Japan and France deploy these as phosphor plate systems retire, with sleeve geometry optimized for direct digital radiography sensors rather than legacy PSP plate dimensions.
- Pressure:Thermoplastic elastomer constructions with embedded conductive layers for real-time bite-force mapping. Orthodontic clinics in Germany pilot these for treatment monitoring beyond diagnostic imaging, compressing the traditional separation between radiography and biometric equipment categories.
- Thermal:Specialized barriers for temperature-sensitive sensor applications in industrial non-destructive testing environments.
- Chemical:Reactive polymer surfaces for specific diagnostic indicator applications in point-of-care settings.
Optical commands the current installed base. Pressure is climbing the fastest as orthodontic practices expand procedural adoption.
End User:
Customer type shapes volume concentration and regulatory exposure, with healthcare procurement subject to stringent biocompatibility documentation against lighter industrial requirements.
- Healthcare:Dental clinics, hospitals, and specialty imaging centers governed by FDA 510(k) and EU MDR Class I conformity requirements. These buyers prioritize ISO 10993-certified suppliers with transparent lot-traceability documentation, particularly in California where state dental board audit protocols mandate single-use barrier adoption.
- Sports:Athletic performance monitoring facilities utilizing bite-force measurement for occlusal analysis in custom mouthguard fitting.
- Automotive:Manufacturing quality control applications for non-destructive component testing with adapted sensor barrier geometries.
- Industrial:Non-destructive testing operations with less stringent material certification requirements and longer replacement cycles.
Healthcare dominates procurement volume. Sports is gaining share fastest as biometric monitoring expands beyond clinical settings.
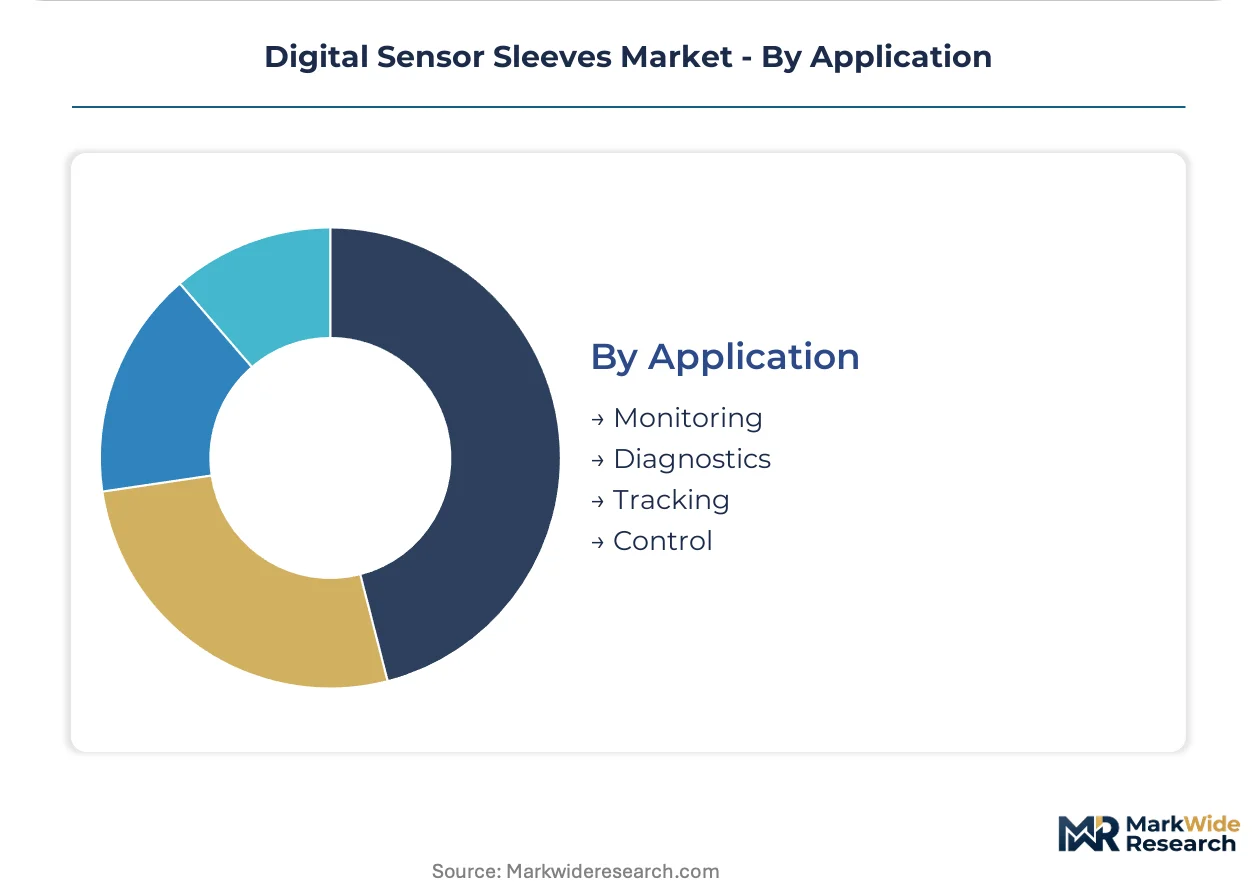
Application:
Volume patterns separate high-frequency monitoring use from episodic diagnostic procedures, with tracking applications enabling recurring data service revenue.
- Monitoring:Continuous or repeated imaging workflows requiring frequent barrier changes between patients. Chairside clinicians in high-volume Los Angeles and San Francisco clinic chains consume these at rates tied directly to appointment throughput, with RFID-enabled variants supporting automated reorder triggers.
- Tracking:Inventory and usage analytics integration with practice management software for procurement optimization. Dental service organizations leverage these capabilities to consolidate contract authority and displace independent distributor relationships.
- Diagnostics:Episodic imaging procedures with lower consumption velocity and less connectivity integration.
- Control:Automated equipment operation interfaces requiring specialized barrier durability specifications.
Monitoring holds the procedural volume base. Tracking is rotating up the share rankings as DSO consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's role in European dental supply chains, handling thermoplastic elastomer feedstocks and finished barrier products destined for Central European clinic networks.
United States
Dental service organizations in Texas and Florida drive procurement consolidation as multi-site chains displace independent distributor relationships. FDA 510(k) clearance pathways tighten material change notification requirements for polymer formulations. Los Angeles and San Francisco clinic chains accelerate disposable sleeve adoption under California dental board infection-control audit protocols.
Germany
EU MDR Class I conformity requirements lock out low-cost Asian suppliers and expand market share for ISO 10993-certified domestic manufacturers. EMA biocompatibility documentation mandates reshape procurement criteria for dental clinics across Bavaria and North Rhine-Westphalia. Stuttgart's industrial cluster hosts specialized blown-film extrusion operations serving orthodontic practices piloting pressure-sensitive sensor designs.
Japan
CMOS sensor architecture proliferation drives optical-compatible sleeve demand as practices retire phosphor plate systems. METI standards for medical device materials influence regional biocompatibility testing protocols. Osaka's Kansai region concentrates orthodontic clinics experimenting with bite-force measurement applications during imaging workflows.
France
ANSM oversight of intraoral device materials reinforces ISO 10993 cytotoxicity testing as baseline market access criteria. EU MDR transition timelines compress qualification cycles for resin supplier switches. Paris and Lyon dental service organizations consolidate infection-control procurement across suburban clinic networks.
United Kingdom
Post-Brexit regulatory alignment with EU MDR Class I rules maintains biocompatibility documentation requirements for barrier products. NHS procurement frameworks favor transparent lot-traceability documentation from ISO-certified suppliers. London's dental clinic chains accelerate digital radiography conversion, compressing replacement cycles for infection-control barriers.
Digital Sensor Sleeves Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated equipment-and-consumables providers leveraging system leases to lock in recurring sleeve purchases; infection-control specialists competing on lot-traceability documentation and regulatory compliance; and cost-focused manufacturers targeting high-volume dental service organizations with procedure-economics metrics. Dominant competitive moves include strategic partnerships with practice management software vendors and captive resin compounding capabilities to navigate FDA material change notification requirements.
Within the integrated equipment tier, Dentsply Sirona occupies a position exemplifying the system-lease-to-consumables model. Among infection-control specialists, Crosstex International and Kerr Totalcare represent archetypes competing on documentation transparency versus cost-per-procedure positioning respectively.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Crosstex International |
| Kerr Totalcare |
| Mydent International |
| ClikTech |
| Flow Dental |
| Hager Worldwide |
| Brixton |
| SanaX |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Southeast Asian thermoplastic elastomer compounding facilities is compressing feedstock pricing power while simultaneously triggering quality-tier bifurcation among sleeve manufacturers seeking ISO 10993 certification. This utilization dynamic forces mid-tier producers toward aggressive volume-discount structures to maintain throughput, whereas certified domestic manufacturers in Germany and the United States capture premium positioning through regulatory documentation bundling.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with dental service organizations leveraging multi-site contract consolidation to extract standard-tier pricing on premium-certified products. Price differentiation hinges on ISO 10993 cytotoxicity documentation completeness and RFID-enabled connectivity integration, with California clinic chains exhibiting lowest sensitivity due to state-mandated infection-control compliance costs, while rural independent practices drive economy-tier demand. Cost compression in standard-grade polyethylene barriers is intensifying as gamma irradiation sterilization investments amortize across thinner production runs.
Supply Chain Analysis
Export-control restrictions on advanced polymer compounding equipment limit technology transfer to uncertified Asian manufacturers, concentrating precision-grade production in Germany, Japan, and the United States. Raw material flows draw from Malaysian and Thai petrochemical feedstocks for base polyethylene, while conductive trace formulations for pressure-sensitive variants source from South Korean electronics-grade suppliers. Single-source vulnerability concentrates in blown-film extrusion tooling, where Stuttgart and Osaka equipment fabricators maintain eighteen-month order backlogs. Distribution runs through group purchasing organizations and direct-to-practice e-commerce platforms that displace traditional dental supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of captive resin compounding capabilities combined with extended ISO 10993 certification timelines creates defensive moats for incumbent manufacturers while raising capital barriers for prospective entrants. This capability gap favors consolidation among mid-tier producers unable to absorb qualification-cycle freezes.
For Market Incumbents: Insulate recurring revenue streams by embedding RFID-enabled sleeves within practice management software ecosystems, locking in multi-year procurement contracts before emerging connectivity standards commoditize inventory-tracking features. Accelerate backward integration into thermoplastic elastomer compounding to navigate FDA material change notification requirements without supplier-switch delays. For New Entrants and Emerging Players: Establish a beachhead in orthodontic bite-force measurement applications where pressure-sensitive sleeve adoption outpaces commoditized diagnostic radiography barriers. Target sports performance monitoring facilities in Japan and Germany for occlusal analysis equipment, bypassing entrenched dental distributor relationships through direct biomechanics laboratory partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected sleeve manufacturers with SaaS-integrated inventory platforms serving fifty-plus location dental service organizations. Acquisition candidates exhibiting captive compounding capabilities and transparent lot-traceability documentation command durable positioning across the analysis window. Monitor California and New York state dental board mandate expansions as inflection signals for accelerated disposable sleeve adoption.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Connectivity Integration | Captures recurring SaaS revenue alongside consumable sales through practice management software partnerships. |
| Captive Resin Compounding | Shortens FDA material change notification cycles and eliminates supplier-switch qualification bottlenecks. |
| Orthodontic Application Expansion | Opens procedural revenue beyond diagnostic radiography into treatment monitoring workflows in Germany and Japan. |
| Direct E-Commerce Channel Development | Bypasses distributor margin extraction and enables customer data ownership for specialized barrier manufacturers. |
| ISO 10993 Certification Investment | Locks out low-cost Asian competitors under EU MDR Class I conformity requirements in France and Germany. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body documentation, and dental supply trade association procurement surveys preceded structured interviews with infection-control officers at dental service organizations, biomedical engineers at sensor OEMs, and GPO contracts managers. Primary fieldwork with blown-film extrusion equipment operators and thermoplastic elastomer compounders validated secondary estimates of production capacity and feedstock cost structures. Bottom-up volume modeling triangulated against top-down expenditure analysis across the analysis window.
Assumptions held fixed include prevailing FDA and EU MDR classification frameworks, continued phosphor plate system retirement timelines, and group purchasing organization consolidation trajectories in Texas and Florida. Variables stress-tested encompass ethylene oxide sterilization regulatory enforcement intensity, Southeast Asian logistics disruption frequency, and state-level dental board mandate adoption rates beyond California and New York. CAGRs were derived from segment-level volume projections weighted by connectivity feature penetration and application mix shifts.
Stress conditions across sterilization technology transitions, resin supplier concentration, and DSO procurement centralization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable bounds. Material shifts in FDA material change notification requirements or EU MDR Class I reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Current Transducer Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market