
 United States (US) Industrial Sensors Market | 2026-2036
United States (US) Industrial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
United States (US) Industrial Sensors Market Insights
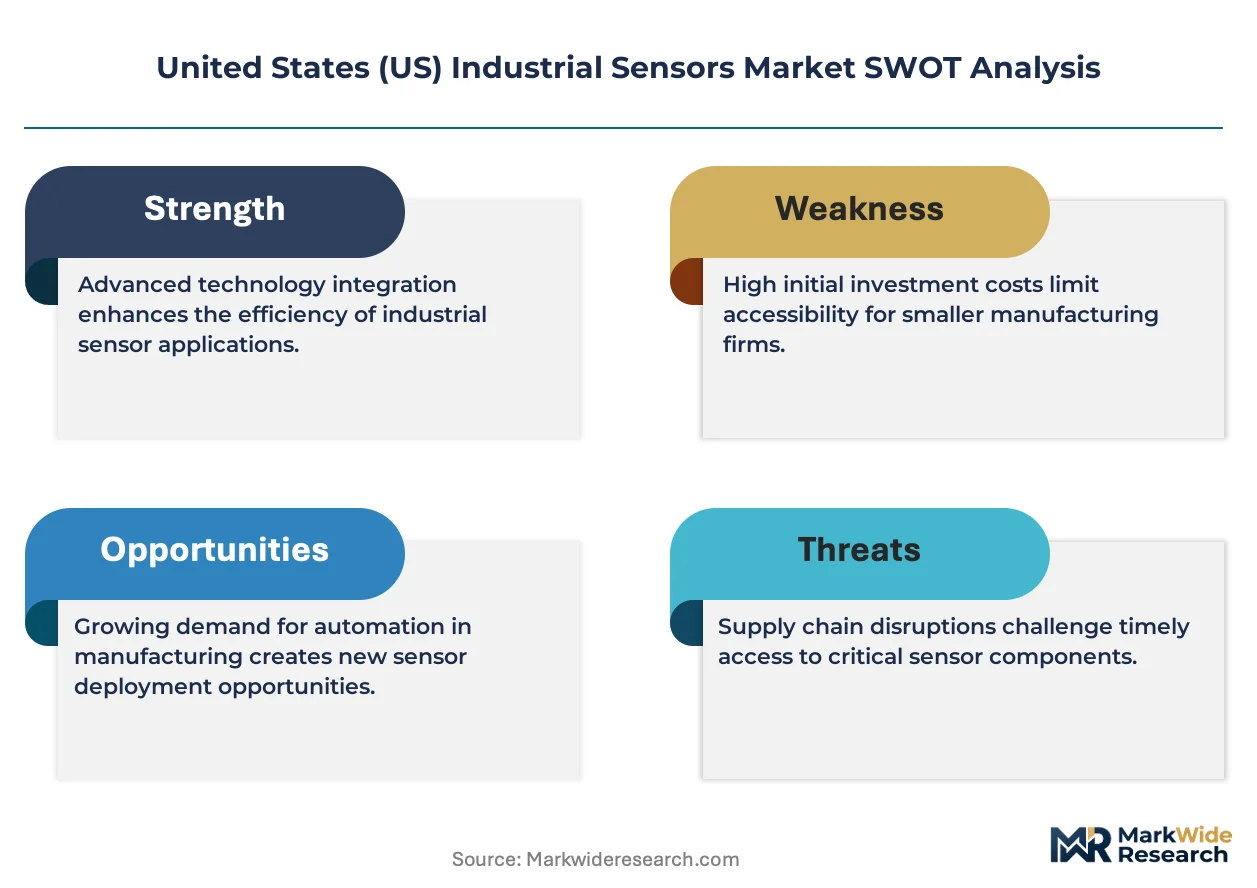
The US industrial sensors market is consolidating around a widening gap between precision-engineered premium tiers and cost-optimized commodity offerings. Texas Instruments Incorporated leverages its semiconductor fabrication depth to dominate high-accuracy signal conditioning chips for aerospace-grade deployments. TE Connectivity Ltd anchors its position through backward integration into specialized cable and connector assemblies that withstand extreme industrial environments. Honeywell International Inc. differentiates via embedded software stacks that turn raw sensor outputs into actionable diagnostics for predictive maintenance workflows.
Industrial sensors are electromechanical or solid-state devices that transduce physical quantities—temperature, pressure, proximity, or fluid level—into standardized electrical signals, typically 4-20 mA, 0-10 V, or digital protocols such as IO-Link and HART, for integration into programmable logic controllers and distributed control systems. Their primary purpose is real-time process monitoring, safety interlocking, and quality assurance across automated production environments. Pressure sensors command the largest revenue pool in mature oil and gas installations along the Gulf Coast, while proximity sensors are displacing mechanical limit switches fastest in automotive body-in-white robotics. Edge computing deployments are capturing margin from cloud-based alternatives by reducing latency for safety-critical loops in steel mills and chemical plants.
The NHTSA mandates functional safety validation for sensors deployed in autonomous vehicle testing fleets, while OSHA enforces exposure monitoring requirements that drive fixed gas-detection sensor density in refineries. The EPA's leak detection and repair rules for methane emissions are expanding demand for ultrasonic and infrared sensors across Permian Basin operations. Stakeholders must weigh the capital trade-offs between retrofitting legacy 4-20 mA loops against full digital-native architectures as federal infrastructure spending reshapes domestic manufacturing footprints.
Market Dynamics
The US industrial sensors market is bifurcating around the tension between legacy 4-20 mA analog infrastructure and digital-native architectures deploying IO-Link and HART protocols. Federal infrastructure spending and IRA manufacturing incentives are accelerating plant modernization timelines, forcing procurement teams to choose between incremental retrofit paths and greenfield digital deployments.
Growth Catalysts
- NHTSA Functional Safety Mandates:The National Highway Traffic Safety Administration now requires validated crash-detection sensors for autonomous vehicle testing fleets, compelling Tier-1 suppliers to expand domestic certification capacity.
- Petrochemical Retrofit Cycles:Gulf Coast refineries are replacing wired pressure and temperature monitoring with wireless sensor arrays to reduce maintenance shutdown frequency and improve real-time leak detection.
- Electric Vehicle Battery Management:Automotive OEMs in Michigan and Tennessee are procuring high-precision current and thermal sensors for battery pack monitoring systems as domestic EV production scales.
Market Restraints
- Semiconductor Supply Concentration:Signal conditioning ASICs for high-accuracy industrial sensors depend heavily on Taiwan and South Korea foundry capacity, exposing lead times to geopolitical friction.
- Legacy Integration Friction:Brownfield installations face technical debt from 1980s-era 4-20 mA loops that resist seamless integration with digital IO-Link backbones without costly gateway hardware.
- OSHA Calibration Burden:Fixed gas-detection sensors in refineries require quarterly recertification under Occupational Safety and Health Administration rules, inflating total cost of ownership.
Strategic Opportunities
- EPA Methane Monitoring Mandates:The Environmental Protection Agency's leak detection and repair rules for Permian Basin operations are expanding addressable market for ultrasonic and infrared emission sensors.
- Edge Computing Convergence:On-device inference chips combined with vibration sensors are opening predictive maintenance contracts that bypass cloud latency for steel mill safety loops.
- Texas Manufacturing Reshoring:IRA clean energy manufacturing credits are drawing sensor-integrated equipment suppliers to Houston and Austin industrial corridors.
Industry Challenges
- Embedded Firmware Talent Scarcity:Sensor OEMs struggle to hire engineers capable of writing deterministic code for safety-critical SIL-2 and SIL-3 certification paths.
- Multi-Protocol Certification Delays:Simultaneous validation against HART, IO-Link, and proprietary fieldbus standards stretches product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States (US) Industrial Sensors Market |
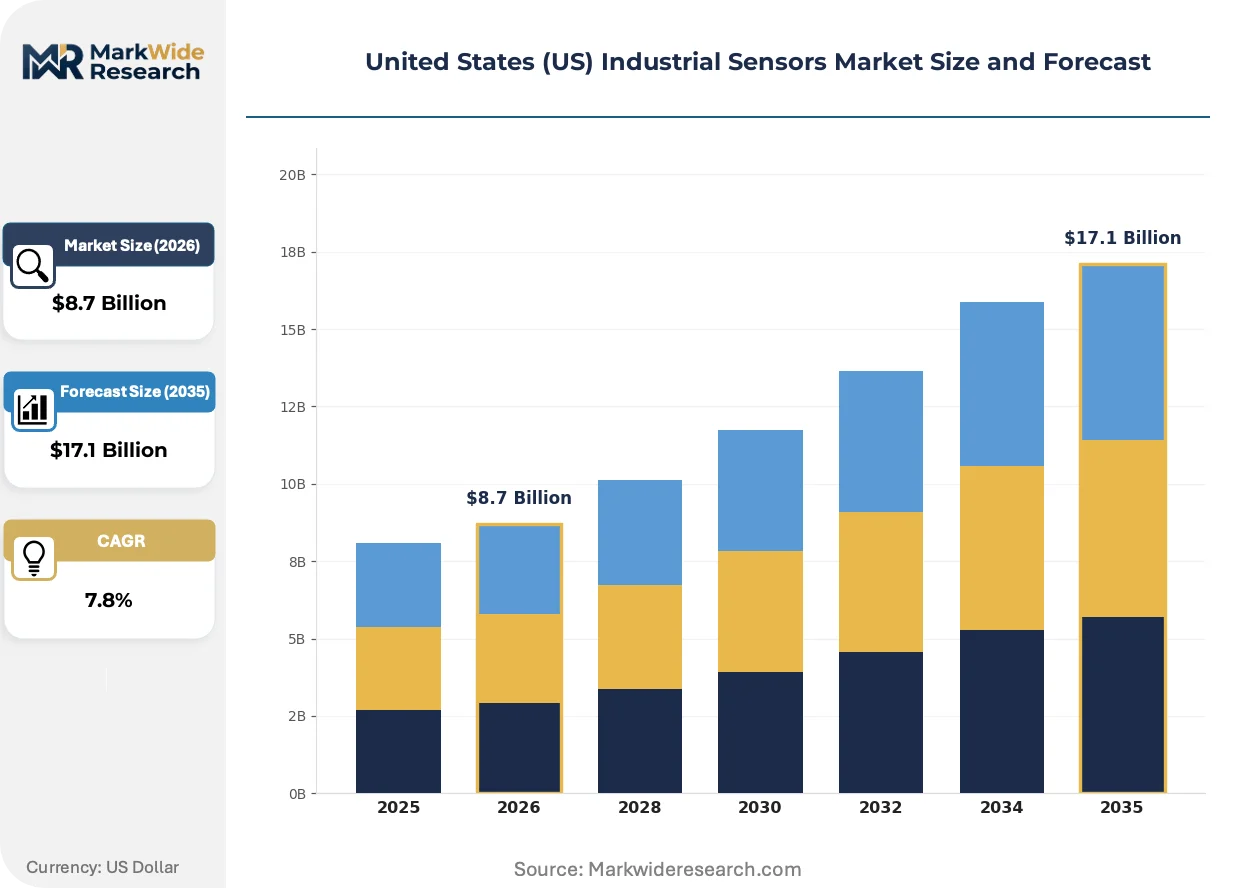
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Level Sensors Technology: Infrared, Capacitive, Ultrasonic, Magnetic End User: Manufacturing, Oil & Gas, Automotive, Aerospace Deployment: On-premises, Cloud-based, Edge Computing, Hybrid |
| Companies Covered | Texas Instruments Incorporated, TE Connectivity Ltd, Honeywell International Inc., Rockwell Automation Inc., Omega Engineering Inc., Siemens AG, ABB Ltd, Analog Devices, Inc., Emerson Electric Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States (US) Industrial Sensors Market Trends and Innovations
Digital protocol migration is compressing the traditional sensor-controller architecture, collapsing signal conditioning and edge processing into single-package devices. This shift is redrawing competitive boundaries between discrete component suppliers and integrated subsystem vendors.
Silicon carbide sensing elements are electrifying high-temperature measurement applications previously served by thermocouples and RTDs. Steel producers in Indiana and Ohio are adopting SiC pressure transducers for blast furnace monitoring. The technology is compressing maintenance windows from quarterly to annual cycles while extending sensor life in corrosive environments.
The EPA's methane emissions detection rules are forcing Permian Basin operators to deploy continuous monitoring sensor networks. Midstream pipeline companies are retrofitting compressor stations with infrared and ultrasonic arrays. The regulation is accelerating procurement of certified optical gas imaging sensors and triggering vendor consolidation around EPA-accepted calibration protocols.
Refinery procurement teams are unbundling sensor hardware from long-term service contracts. Buyers in Texas and Louisiana now source devices through distributor channels while negotiating predictive analytics separately with software vendors. This disintermediation is compressing hardware margins and shifting value capture toward diagnostic algorithm providers.
United States (US) Industrial Sensors Market Segmentation
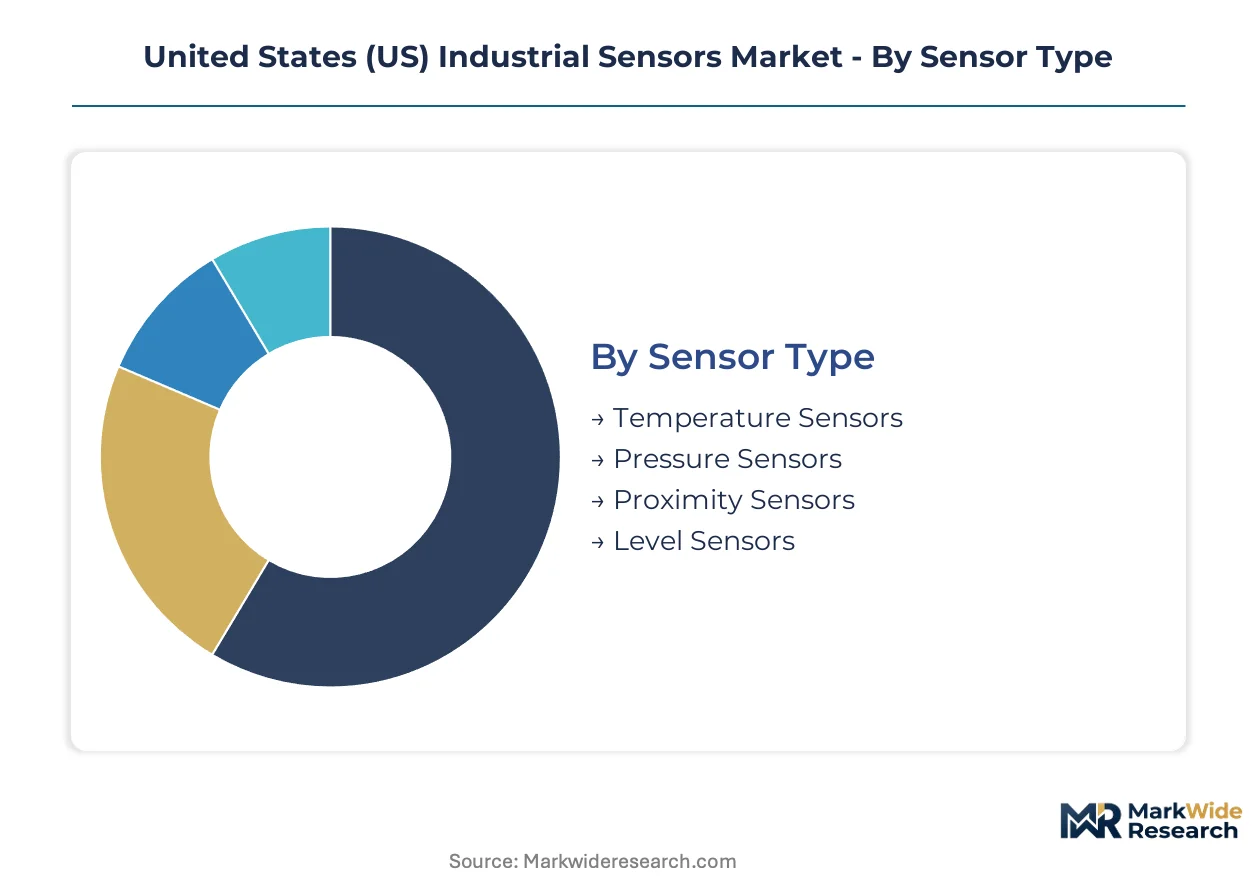
Industrial sensor procurement in the United States fragments across four distinct dimensions, each carrying different margin profiles and regulatory exposure. Understanding where volume concentrates versus where premium pricing holds determines supplier positioning and R&D allocation.
Sensor Type:
Volume deployment clusters in legacy process measurements, while precision-engineered variants command margin in safety-critical applications.
- Pressure Sensors:Piezoresistive and capacitive transducers dominate hydrocarbon processing along the Gulf Coast. Texas and Louisiana refineries are retrofitting wired installations with wireless arrays to satisfy EPA leak detection mandates while reducing maintenance shutdown frequency.
- Temperature Sensors:RTDs and thermocouples serve blast furnace monitoring in Indiana and Ohio steel mills. Silicon carbide sensing elements are displacing legacy technologies, extending calibration intervals from quarterly to annual cycles in corrosive high-temperature environments.
- Proximity Sensors:Inductive and capacitive variants replace mechanical limit switches in Michigan automotive body-in-white robotics.
- Level Sensors:Guided wave radar and ultrasonic technologies monitor bulk storage tanks across Permian Basin midstream operations.
Mature deployment sits with Pressure Sensors. Newer deployment is concentrated in Proximity Sensors.
Technology:
Signal transduction methods align with environmental constraints and measurement precision requirements rather than cost optimization alone.
- Ultrasonic:Time-of-flight and Doppler principles enable non-contact level and flow measurement in chemical processing. Permian Basin operators deploy ultrasonic arrays for continuous methane monitoring under EPA leak detection and repair rules, triggering vendor consolidation around accepted calibration protocols.
- Infrared:Thermal imaging and gas detection serve safety interlocks in hazardous area classifications. Optical gas imaging sensors are gaining share fastest in compressor station retrofits across Texas and New Mexico pipeline infrastructure.
- Capacitive:Dielectric measurement handles moisture-prone solids and liquid interface detection in agricultural processing.
- Magnetic:Hall effect and magnetostrictive technologies provide position feedback in hydraulic cylinder applications.
Volume manufacturing favors Capacitive solutions. Precision requirements drive Infrared adoption.
End User:
Customer concentration varies sharply between cyclical commodity producers and federally regulated safety-critical sectors.
- Oil & Gas:Upstream, midstream, and downstream operations span the Permian Basin, Gulf Coast refining corridor, and Appalachian shale plays. OSHA fixed gas-detection requirements and EPA methane rules are expanding sensor density per facility while quarterly recertification burdens inflate total cost of ownership.
- Automotive:OEMs and Tier-1 suppliers in Detroit and Tennessee are scaling procurement of current and thermal sensors for electric vehicle battery management systems. NHTSA functional safety mandates for autonomous vehicle testing fleets are compelling domestic certification capacity expansion.
- Manufacturing:Discrete automation and process industries drive replacement demand for legacy 4-20 mA devices.
- Aerospace:Defense and commercial aviation applications require MIL-SPEC and AS9100 certified components.
Procurement scale concentrates in Oil & Gas. Specification intensity peaks in Aerospace.
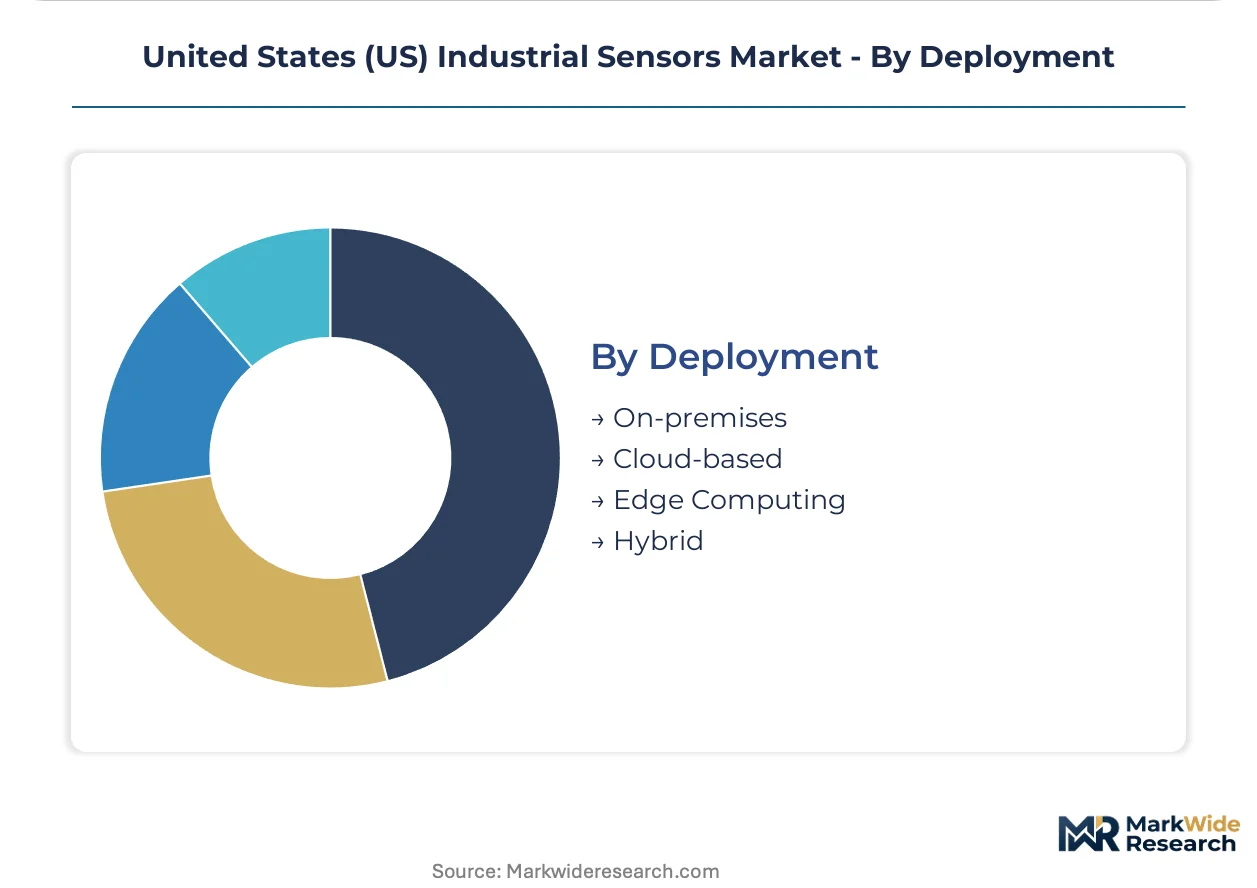
Deployment:
Architecture choices reflect latency tolerance, cybersecurity posture, and legacy infrastructure amortization schedules.
- Edge Computing:On-device inference chips combined with vibration sensors enable predictive maintenance contracts that bypass cloud latency. Steel mills in Indiana and chemical plants along the Gulf Coast are adopting edge architectures for safety-critical control loops where millisecond response times are mandatory.
- Hybrid:Mixed architectures preserve existing 4-20 mA field wiring while overlaying digital diagnostics. Brownfield installations in older Gulf Coast refineries favor this path to avoid full rip-and-replace capital commitments.
- On-premises:Traditional SCADA and DCS integration remains prevalent in air-gapped critical infrastructure.
- Cloud-based:Centralized analytics platforms serve non-time-sensitive optimization and long-term trend analysis.
Greenfield construction selects Edge Computing. Legacy retrofit gravitates toward Hybrid deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the densest concentration of industrial sensor demand in the United States, with Gulf Coast petrochemical corridors driving procurement volumes for pressure and temperature monitoring arrays. The analysis examines five sub-regional markets where deployment patterns diverge based on industrial base composition and regulatory exposure.
Texas Gulf Coast
Petrochemical refineries in Houston, Beaumont, and Corpus Christi are retrofitting wired sensor networks with wireless pressure and temperature arrays. EPA leak detection and repair rules are expanding ultrasonic and infrared sensor density across Permian Basin midstream operations. Dallas-Fort Worth semiconductor fabrication facilities are sourcing high-accuracy signal conditioning chips for advanced manufacturing equipment.
Michigan and Tennessee Automotive Belt
Detroit-area OEMs and Tennessee assembly plants are scaling procurement of current and thermal sensors for electric vehicle battery management systems. NHTSA functional safety mandates for autonomous vehicle testing fleets are compelling Tier-1 suppliers to expand domestic certification capacity. Nashville and Chattanooga industrial corridors are attracting sensor-integrated equipment suppliers under IRA clean energy manufacturing credits.
Indiana and Ohio Steel Region
Blast furnace operators in Gary and Cleveland are adopting silicon carbide pressure transducers for high-temperature monitoring applications. OSHA fixed gas-detection requirements are driving sensor density in coke oven and basic oxygen furnace operations. Pittsburgh-area steel mills are deploying edge computing architectures with vibration sensors for predictive maintenance contracts that bypass cloud latency.
California Technology Corridor
San Jose and San Francisco Bay Area semiconductor equipment manufacturers are sourcing precision proximity sensors for wafer handling robotics. California Air Resources Board emissions monitoring rules are expanding demand for optical gas imaging sensors in refinery and chemical processing installations. Los Angeles aerospace suppliers are procuring MIL-SPEC certified components for defense and commercial aviation applications.
Louisiana Chemical Processing
Baton Rouge and Lake Charles refineries are replacing legacy 4-20 mA loops with hybrid digital architectures to satisfy EPA methane monitoring mandates. OSHA quarterly recertification requirements for fixed gas-detection sensors are inflating total cost of ownership and driving procurement toward predictive analytics service contracts. New Orleans port logistics operators are deploying level sensors for bulk liquid storage tank monitoring.
United States (US) Industrial Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification-grade spectrum, with aerospace and automotive safety applications commanding price multiples over standard process instrumentation. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive semiconductor fabrication, specialized sensor OEMs with backward integration into cable and connector assemblies, and distributed component suppliers serving retrofit markets. Dominant competitive moves include capacity expansion in domestic signal conditioning chip fabrication and strategic partnerships between hardware vendors and predictive analytics software providers.
Among diversified industrial technology providers, Texas Instruments Incorporated, Honeywell International Inc., and TE Connectivity Ltd exemplify contrasting archetypes. Texas Instruments leverages semiconductor fabrication depth for high-accuracy signal conditioning. Honeywell differentiates through embedded software stacks that convert raw sensor outputs into diagnostic workflows. TE Connectivity anchors its position through in-house production of specialized cable and connector assemblies for extreme industrial environments. These three represent the dominant competitive positioning vectors in the United States market.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| TE Connectivity Ltd |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Omega Engineering Inc. |
| Siemens AG |
| ABB Ltd |
| Analog Devices, Inc. |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into specialized cable and connector assemblies anchors supply position for premium-tier suppliers while insulating their pricing power from commodity volatility in standard process instrumentation. Texas and Louisiana refinery procurement teams now unbundle hardware from service contracts, compressing margins for discrete component vendors while predictive analytics providers capture value.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and predictive maintenance outcomes dominates safety-critical deployments in Gulf Coast petrochemical corridors. Three-tier pricing structure across premium, standard, and economy levels separates MIL-SPEC aerospace components from industrial-grade process sensors and commodity proximity switches. Cost compression in standard-tier pressure transducers is intensifying because distributor channels disintermediate legacy vendor relationships. Automotive OEMs exhibit lowest price sensitivity due to NHTSA certification requirements, while brownfield manufacturing buyers drive hardest bargain on retrofit volumes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit automotive clusters and Houston refining corridors, while distributor networks serve fragmented maintenance-replacement procurement. Signal conditioning ASICs draw from Taiwan and South Korea foundry capacity, with MEMS sensing elements sourced from domestic fabrication in Texas and Arizona. Single-source vulnerability concentrates in advanced node semiconductor production. Distribution runs through authorized industrial distributors with calibration certification capabilities and direct field service arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in domestic signal conditioning chip fabrication prop pricing power for vertically integrated incumbents, while lead time exposure to Taiwan and South Korea foundries creates procurement risk for second-tier assemblers.
For Market Incumbents: Deploy captive semiconductor fabrication capacity to defend margin position against fabless competitors dependent on Asian foundry allocation. Expand domestic certification laboratory capacity to capture NHTSA functional safety validation demand from autonomous vehicle testing fleets. Secure long-term supply agreements with Permian Basin operators facing EPA methane monitoring mandates. For New Entrants and Emerging Players: Regional distributor partnerships with calibration service capabilities offer lowest-friction path to refinery maintenance-replacement procurement. Target brownfield hybrid deployment architectures in older Gulf Coast refineries resisting full digital-native retrofits. Develop edge computing firmware stacks that bypass cloud latency for steel mill safety loops. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking embedded software capabilities. Five-to-ten year viability hinges on firmware talent access for SIL-2 and SIL-3 certification paths. Watch EPA enforcement intensity on Permian Basin methane detection as inflection indicator for optical gas imaging sensor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Signal Conditioning Chip Fabrication | Captive production in Texas and Arizona reduces lead time exposure to Taiwan and South Korea foundry concentration. |
| EPA-Certified Calibration Protocol Development | Vendor consolidation around accepted methane detection standards accelerates Permian Basin procurement decisions. |
| Edge Computing Firmware Integration | On-device inference chips combined with vibration sensors bypass cloud latency for steel mill safety loops. |
| NHTSA Functional Safety Certification Expansion | Domestic validation capacity captures autonomous vehicle testing fleet sensor demand from Detroit and Tennessee. |
| Predictive Analytics Service Unbundling | Separate software contracts from hardware procurement shift value capture toward diagnostic algorithm providers. |
Research Methodology
Document review covered SEC 10-K filings from diversified industrial technology providers, NHTSA regulatory dockets, and EPA enforcement records, complemented by interviews with plant engineers at Gulf Coast refineries, procurement managers at Detroit automotive OEMs, and aftermarket service heads at industrial distributors. Secondary sources included customs trade data, OSHA calibration compliance databases, and semiconductor equipment bill-of-materials disclosures. Bottom-up sensor deployment estimates triangulated against top-down industrial capital expenditure patterns.
Historical production volumes from vehicle registration databases and refinery maintenance schedules cross-referenced against panel input from Tier-1 supplier procurement teams. Segmentation dimensions modeled include sensor type, signal transduction technology, end-use industry vertical, and deployment architecture across the analysis window. CAGRs derived from regression analysis of capital equipment replacement cycles and regulatory compliance timelines. Industry-specific inputs incorporated IRA manufacturing incentive disbursement patterns and EPA methane rule implementation phasing.
Several conditions sit outside the modeled scope, including unannounced foundry capacity expansions in Taiwan, geopolitical disruption to South Korea semiconductor exports, and abrupt NHTSA regulatory revisions. Forecasts reflect assumptions regarding continued IRA credit availability and EPA enforcement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Calibrator Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
APAC Proximity Sensors Market