
 Test and Measurement Market | 2026-2036
Test and Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Test and Measurement Market Insights
Software-defined instrumentation is narrowing the gap between hardware-bound legacy architectures and cloud-native test workflows. Keysight Technologies leverages its PXI and modular instrument portfolio to anchor high-frequency validation workflows for 5G and 6G research. Rohde & Schwarz competes through deep specialization in spectrum analysis and electromagnetic compatibility testing for defense and aerospace contractors. National Instruments sustains its position in automated test systems by extending software-defined data acquisition platforms into semiconductor validation labs.
Test and measurement encompasses electronic instruments and systems that characterize, verify, and certify physical, electrical, or RF parameters against specified tolerances, typically resolving signals from DC to millimeter-wave frequencies with precision ranging from parts-per-million to sub-picosecond timing accuracy. These tools serve industrial and commercial purposes spanning product validation, regulatory compliance certification, and manufacturing yield optimization. Oscilloscope demand concentrates in semiconductor and automotive debug applications where mixed-signal capture bandwidth determines design cycle speed. Spectrum analyzer procurement accelerates within telecommunications as millimeter-wave deployment drives over-the-air validation requirements. Software-based instrumentation captures expanding margin pools as vendors shift from perpetual hardware sales toward subscription analytics and remote calibration services.
FCC equipment authorization rules and EU Radio Equipment Directive compliance frameworks shape product development priorities for RF test equipment sold into North American and European markets. FDA quality system regulations and ISO 17025 laboratory accreditation standards further constrain how manufacturers and service providers document measurement traceability and calibration intervals. Stakeholders must weigh capital intensity against test-as-a-service models as cloud connectivity and AI-driven anomaly detection redefine where value accumulates in the instrumentation stack.
Market Dynamics
Software-defined instrumentation is compressing hardware refresh cycles while forcing legacy vendors to rebuild revenue models around subscription analytics and remote calibration services.
Growth Catalysts
- Foundry capacity expansion:Taiwan and South Korea semiconductor manufacturers sustain procurement of wafer test systems and probe stations as fabrication node migration accelerates.
- EU AI Act:Critical infrastructure operators across Europe must deploy certified automated test equipment, creating compliance-driven replacement demand for legacy instrumentation.
- Millimeter-wave validation:5G and 6G research programs in telecommunications laboratories require over-the-air test capabilities that obsolete sub-6 GHz equipment.
Market Restraints
- Precision component concentration:Specialized ADCs and high-frequency mixers source from a narrow supplier base in East Asia, exposing lead time volatility.
- FCC equipment authorization:North American RF test equipment faces extended certification timelines that delay product commercialization and compress margin recovery windows.
- Technical bandwidth ceiling:Sub-picosecond timing accuracy demands strain thermal management and signal integrity engineering, limiting portable instrument form factors.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives attract semiconductor packaging and testing facilities that require localized metrology tool deployment.
- Cloud-native test workflows:Convergence of containerized software architectures with modular PXI hardware enables remote diagnostic services for distributed manufacturing sites.
- Automotive electrification:Battery management system validation and power electronics testing create new application verticals beyond traditional RF and semiconductor segments.
Industry Challenges
- Calibration technician scarcity:ISO 17025 laboratory accreditation standards demand documented measurement traceability that outpaces trained personnel supply in emerging manufacturing clusters.
- Legacy system integration:Decades-old GPIB and LXI instrument fleets resist seamless incorporation into API-driven test orchestration platforms without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test and Measurement Market |
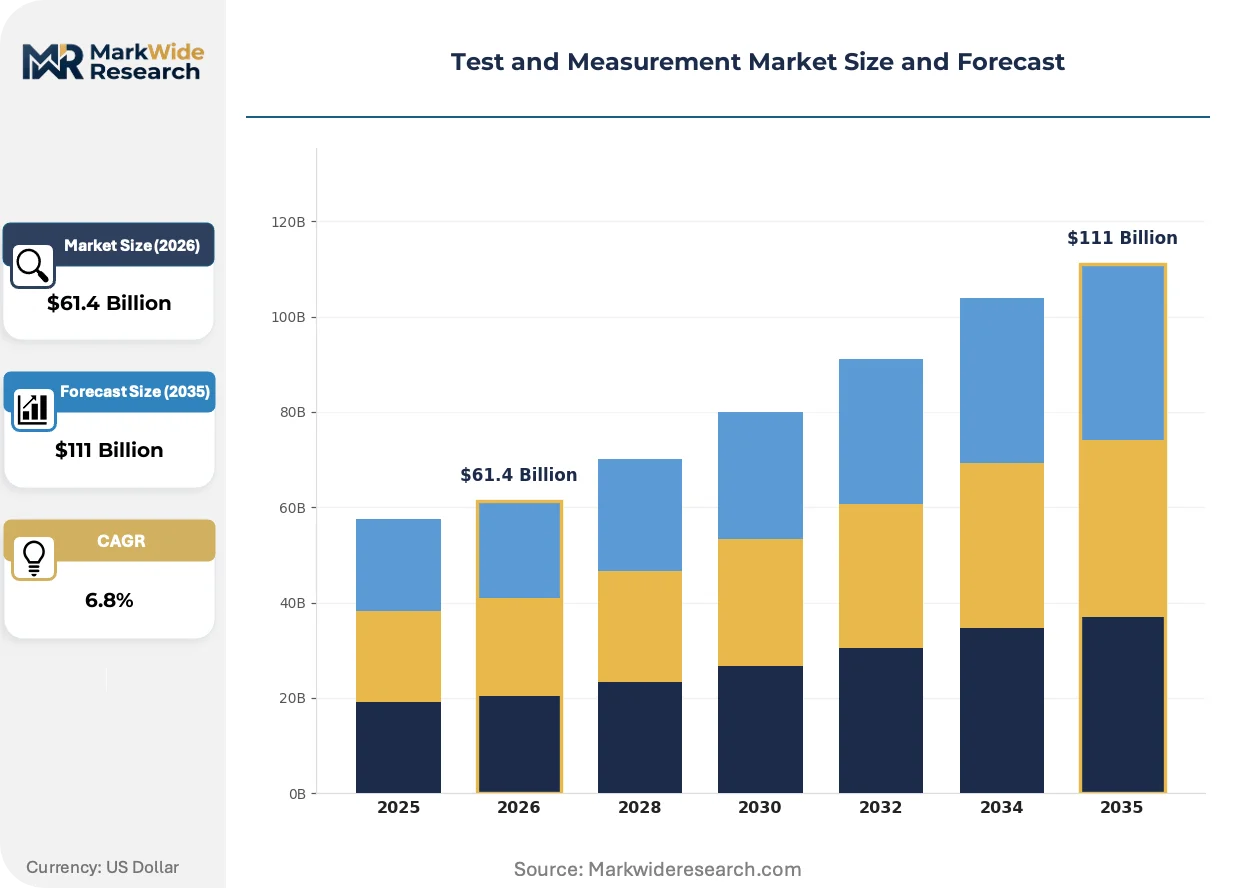
| Market Size in 2026 | $61.4 Billion |
| Market Size in 2035 | $111 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
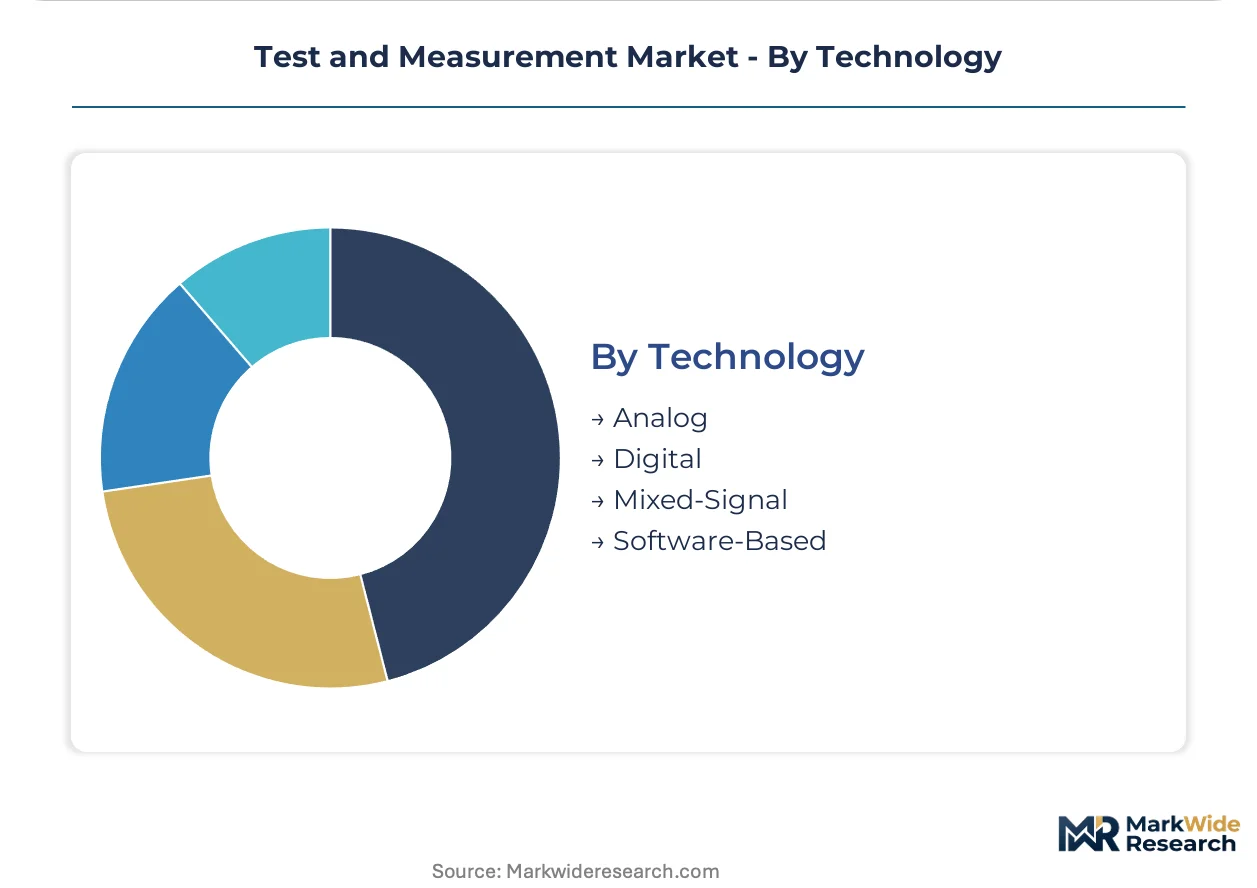
| Segmentation | Product Type: Oscilloscope, Multimeter, Spectrum Analyzer, Signal Generator Application: Automotive Testing, Telecommunications, Aerospace, Research & Development End User: Manufacturers, Laboratories, Educational Institutions, Service Providers Technology: Analog, Digital, Mixed-Signal, Software-Based |
| Companies Covered | Keysight Technologies, Fortive, AMETEK, Rohde & Schwarz, National Instruments, Teledyne Technologies, VIAVI Solutions, Anritsu, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test and Measurement Market Trends and Innovations
Instrumentation vendors face pressure to decouple hardware margins from software value as buyers demand consumption-based pricing and predictive maintenance capabilities.
Modular PXI architectures are digitizing test workflows by replacing fixed-function boxes with reconfigurable FPGA-based signal processing. Semiconductor validation labs in Taiwan and South Korea now deploy these platforms for protocol-aware debugging that adapts to evolving interface standards without hardware replacement. This digitization compresses capital expenditure cycles while expanding recurring revenue from software feature licensing.
EU Radio Equipment Directive enforcement is tightening electromagnetic compatibility documentation requirements for RF equipment sold into European markets. Manufacturers must maintain test traceability records spanning product lifecycles, forcing investment in data management infrastructure. Medical device and automotive suppliers face the steepest compliance burdens as notified body scrutiny intensifies for connected products.
Test-as-a-service contracts are displacing perpetual instrument purchases among mid-sized electronics manufacturers. Contract manufacturers in Vietnam and Mexico now source validation capacity from third-party metrology providers rather than owning depreciating capital equipment. This preference shift concentrates demand among service providers with multi-site calibration networks and accelerates consolidation among regional instrument lessors.
Test and Measurement Market Segmentation
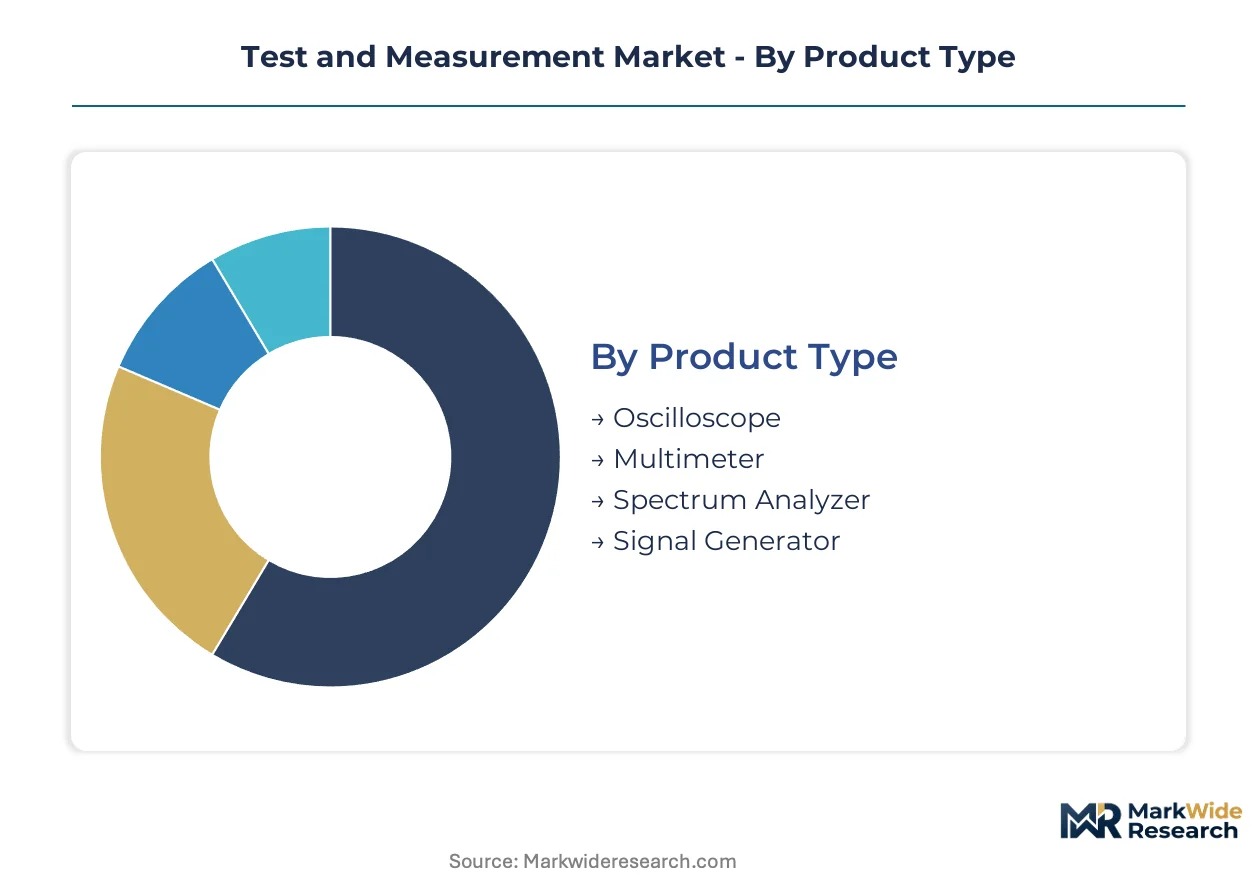
Test and measurement instrumentation fragments across multiple technical and commercial dimensions that determine procurement patterns and margin structures. Product architecture, end-use environment, and technology generation each create distinct competitive arenas with different pricing power and replacement cycles.
Product Type:
Cost tier separates benchtop instruments from modular systems, with specification bandwidth and channel density driving price stratification.
- Oscilloscope:Mixed-signal capture platforms with bandwidth exceeding 50 GHz serve semiconductor debug workflows in Taiwan and South Korea foundry labs. Real-time sampling density determines design cycle velocity for advanced node validation. Oscilloscope holds installed capacity. Spectrum Analyzer is rotating up the share rankings.
- Spectrum Analyzer:Electromagnetic signal characterization instruments resolve millimeter-wave emissions for 5G base station conformance testing. Over-the-air validation requirements in telecommunications laboratories accelerate procurement of 110 GHz-plus architectures.
- Multimeter:Precision voltage and current measurement devices anchor calibration workflows across manufacturing floors and ISO 17025 laboratories.
- Signal Generator:Arbitrary waveform and vector signal sources stimulate device-under-test responses for protocol verification and stress testing.
Application context determines environmental ruggedization, portability requirements, and certification documentation intensity.
- Automotive Testing:Battery management system validation and power electronics characterization absorb expanding instrument capacity as electrification programs multiply test points per vehicle platform. EMC compliance documentation under EU Radio Equipment Directive intensifies data management infrastructure investment. Automotive Testing holds installed capacity. Research & Development is rotating up the share rankings.
- Telecommunications:Millimeter-wave over-the-air test chambers and conducted conformance systems validate 5G and 6G radio equipment against FCC equipment authorization and EU Radio Equipment Directive specifications.
- Aerospace:Defense contractors deploy specialized spectrum analyzers and signal generators for radar cross-section measurement and electronic warfare system verification.
- Research & Development:University and national laboratory facilities source software-defined instrumentation for protocol research and standards development.
Customer organizational structure shapes contract terms, service attachment rates, and replacement cycle predictability.
- Manufacturers:Electronics assembly and semiconductor fabrication facilities deploy automated test systems for production yield monitoring and outgoing quality assurance. Taiwan and South Korea foundry expansion sustains capital deployment into wafer probe and final test instrumentation. Manufacturers hold installed capacity. Service Providers are rotating up the share rankings.
- Laboratories:ISO 17025 accredited calibration and testing facilities maintain traceable measurement chains for regulatory compliance certification.
- Educational Institutions:Engineering programs source entry-level instrumentation for undergraduate laboratory instruction and graduate research.
- Service Providers:Third-party metrology contractors in Vietnam and Mexico deliver test-as-a-service capacity to mid-sized electronics manufacturers avoiding capital ownership.
Technology generation defines software upgradeability, integration architecture, and long-term vendor lock-in characteristics.
- Software-Based:FPGA-powered PXI modular platforms enable remote reconfiguration and subscription feature licensing, compressing hardware replacement intervals while expanding recurring revenue. Containerized test orchestration supports distributed manufacturing diagnostics. Software-Based holds installed capacity. Mixed-Signal is rotating up the share rankings.
- Mixed-Signal:Integrated analog and digital capture channels serve embedded system debug where microcontroller peripherals require simultaneous voltage and protocol analysis.
- Digital:Logic analyzers and digital pattern generators verify high-speed serial interfaces in consumer electronics and computing platforms.
- Analog:Legacy benchtop instruments persist in maintenance and repair workflows where precision DC measurement suffices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test and measurement equipment flows from South Korean and Taiwanese fabrication hubs into semiconductor validation labs across Germany, the United States, and Japan. This trade corridor concentrates high-value metrology procurement within three dominant manufacturing ecosystems.
South Korea
Memory and logic foundry expansion in Pyeongtaek and Hwaseong sustains capital deployment into wafer probe systems and parametric test platforms. MFDS medical device regulations and K-Battery certification requirements shape electromagnetic compatibility documentation for battery management system instrumentation. Seoul Capital Area hosts concentrated procurement from Samsung and SK Hynix validation facilities.
Taiwan
Advanced node migration at TSMC fabs in Hsinchu and Tainan accelerates demand for sub-picosecond timing analysis and protocol-aware debug platforms. Bureau of Standards, Metrology and Inspection (BSMI) calibration traceability mandates govern export-bound test equipment documentation. Taichung precision machinery corridor supplies probe station mechanical subassemblies to domestic instrument integrators.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen multiply power electronics test points per vehicle platform. EU AI Act critical infrastructure provisions and CE marking under Radio Equipment Directive constrain automated test system deployment in connected manufacturing. Bavaria's Munich-Stuttgart industrial corridor concentrates EMC test chamber installations and calibration laboratory accreditation.
United States
5G and 6G research at DARPA-funded telecommunications laboratories drives millimeter-wave over-the-air validation equipment procurement. FCC equipment authorization rules extend certification timelines for RF test systems sold into North American markets. Silicon Valley and Greater Boston host concentrated software-defined instrumentation development for cloud-native test orchestration platforms.
Japan
Automotive semiconductor and industrial sensor manufacturers sustain demand for mixed-signal oscilloscopes and precision multimeter calibration chains. METI industrial standards and JIS measurement traceability requirements govern laboratory accreditation for export-oriented electronics suppliers. Nagoya automotive cluster and Tokyo-Yokohama electronics corridor concentrate high-frequency instrument deployment.
Test and Measurement Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive strata. The vendor base organizes around three strategic archetypes: diversified instrumentation conglomerates with broad portfolio coverage, frequency-domain specialists with defense-aerospace anchoring, and modular platform providers with software-centric revenue models. Competitive moves concentrate on strategic partnerships for 5G/6G validation workflows and geographic expansion into India electronics manufacturing corridors.
Within the diversified instrumentation tier, Keysight Technologies and Fortive occupy positions spanning RF, semiconductor, and automotive test verticals. Rohde & Schwarz exemplifies the frequency-domain specialist archetype with spectrum analysis and electromagnetic compatibility testing concentration. National Instruments anchors the modular platform segment with PXI-based software-defined instrumentation for automated test system deployment.
| Leading Market Players |
|---|
| Keysight Technologies |
| Fortive |
| AMETEK |
| Rohde & Schwarz |
| National Instruments |
| Teledyne Technologies |
| VIAVI Solutions |
| Anritsu |
| Yokogawa Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on specialized ADC and high-frequency mixer suppliers in East Asia compresses margin recovery windows for instrument vendors while simultaneously widening pricing spreads between hardware-bound legacy systems and software-defined modular platforms. This concentration forces buyers into extended lead time commitments that privilege subscription-based service contracts over perpetual equipment purchases, reshaping how value accumulates across the instrumentation stack.
Pricing Analysis
Next-generation FPGA-based PXI modular platforms command substantial premiums over prior-generation benchtop instruments, while legacy analog oscilloscopes and multimeters face accelerating price erosion in maintenance-heavy segments. Three-tier pricing structure across premium software-defined systems, standard mixed-signal platforms, and economy analog instruments reflects differentiation by calibration certification tier and remote service bundling rather than raw specification bandwidth alone. Cost compression in economy tiers intensifies as contract manufacturers in Vietnam and Mexico shift procurement toward test-as-a-service providers, reducing direct instrument ownership. Semiconductor validation labs in Taiwan and South Korea exhibit lowest price sensitivity due to foundry capacity expansion timelines, while mid-sized electronics manufacturers in emerging clusters demonstrate highest elasticity.
Supply Chain Analysis
Export-control regimes limiting high-frequency semiconductor test technology flows constrain component sourcing for millimeter-wave spectrum analyzers and vector signal generators above 110 GHz. Precision ADC fabrication concentrates in Taiwan, South Korea, and Japan, with specialized mixer assemblies drawing from Japanese and German component specialists. Supply chain vulnerability centers on single-source wafer probe station mechanical subassemblies from the Taichung precision machinery corridor. Distribution runs through authorized regional distributors with calibration service networks rather than direct vendor-to-manufacturer relationships, privileging incumbents with established ISO 17025 laboratory footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test and measurement instrumentation is undergoing a platform-economics inflection as software-defined architectures decouple hardware margins from analytics value, with interoperability standards around PXI and LXI enabling ecosystem substitution that threatens vendor lock-in.
For Market Incumbents: Pre-empt modular platform commoditization by deepening backward integration into FPGA silicon and signal processing IP rather than relying on third-party chip vendors. Anchor high-frequency validation workflows for 6G research through exclusive partnerships with DARPA-funded telecommunications laboratories. Defend against test-as-a-service disintermediation by acquiring regional calibration networks in Vietnam and Mexico before third-party metrology providers consolidate.
For New Entrants and Emerging Players: India's electronics manufacturing corridors under PLI scheme incentives represent the most penetrable geography for localized probe station and wafer test system deployment. Target automotive electrification segments in Germany's Munich-Stuttgart corridor where battery management system validation demand outpaces incumbent capacity. Pursue cloud-native test orchestration partnerships with contract manufacturers seeking distributed diagnostics without capital ownership.
For Investors and Strategic Acquirers: EU AI Act critical infrastructure certification requirements reshape the acquisition landscape toward automated test equipment vendors with pre-certified compliance documentation. Long-term viability favors modular platform specialists with recurring software revenue over hardware-dependent legacy instrument manufacturers. Watch for inflection signals in India semiconductor packaging facility announcements that trigger localized metrology tool procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized software architectures with PXI hardware enable remote diagnostics for distributed manufacturing sites. |
| Strategic Partnership | Exclusive 6G validation collaborations with DARPA-funded laboratories anchor millimeter-wave spectrum analyzer demand. |
| Acquisition of Specialist Firm | Regional calibration networks in Vietnam and Mexico secure test-as-a-service channel control before consolidation. |
| Geographic Expansion | Localized probe station deployment in India's PLI-incentivized corridors captures packaging facility capital spending. |
| Product Launch | Pre-certified EU AI Act compliant automated test systems accelerate replacement cycles in European critical infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor validation engineers, automotive test system procurement managers, calibration laboratory directors, and contract manufacturing operations executives, and refined through secondary validation across SEC filings of diversified instrumentation conglomerates, Bureau of Standards Metrology and Inspection export documentation, EU Radio Equipment Directive compliance registries, and FCC equipment authorization databases. Bottom-up demand modeling from foundry capital expenditure disclosures and top-down triangulation against automated test system vendor revenue allocations converged on segment-level estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, end-use environment, customer organizational structure, and technology generation. CAGRs were derived from instrument replacement cycle compression rates and software subscription attach rate trajectories. Forecast inputs incorporated foundry node migration timelines and EU AI Act enforcement phase transitions without specifying implementation dates.
Practitioners should monitor export control list revisions, foundry capacity expansion announcements, and calibration technician certification pipeline capacity for early signals of forecast deviation. Material shifts in semiconductor fabrication geographic distribution or electromagnetic compatibility documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Destructive Testing Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Insulation Testing Instrument Market