
 Test and Measurement Sensors Market | 2026-2036
Test and Measurement Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Test and Measurement Sensors Market Analytics
Market Dynamics
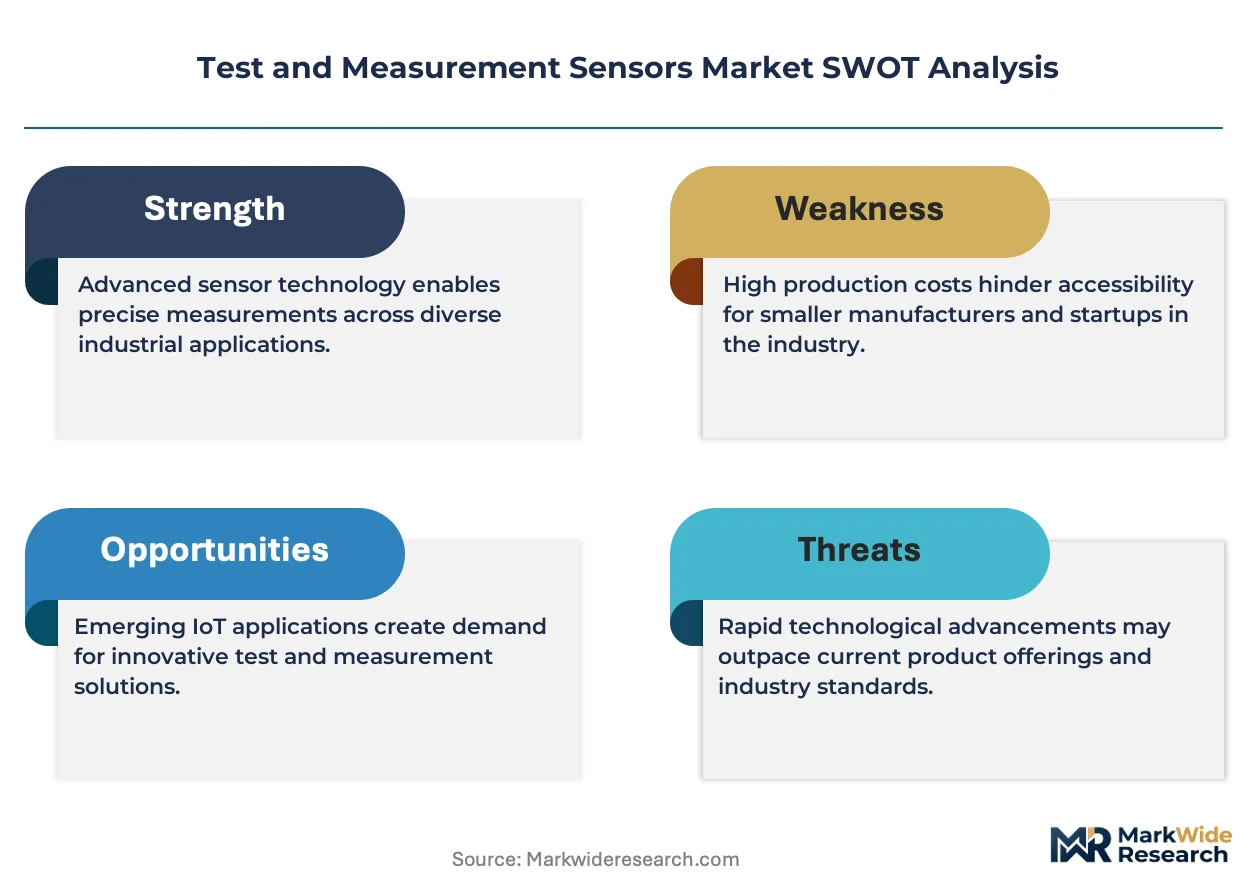
REACH compliance is recalibrating the cost-of-entry calculus for European sensor suppliers, forcing reformulation of bonding agents and encapsulants. TE Connectivity leverages its vertical integration in MEMS fabrication to sustain margin structures amid these material shifts. Kistler Group anchors its competitive position through specialized force and torque measurement systems for automotive crash testing. PCB Piezotronics differentiates via piezoelectric accelerometer technology leadership in aerospace vibration monitoring.
Technology and Segmentation
Test and measurement sensors are transducer devices that convert physical quantities—pressure, temperature, force, acceleration, or flow—into electrical signals with specified accuracy classes, typically calibrated to ISO 17025 traceability standards, serving industrial process control, product validation, and safety-critical monitoring functions. Pressure sensors dominate volume within the sensor type dimension, driven by hydraulic and pneumatic system diagnostics across manufacturing plants. Industrial automation applications command the largest application share, though medical devices represent the fastest-expanding margin pool as wearable diagnostics and surgical robotics multiply calibration requirements.
Regulatory Environment
FDA quality system regulations govern sensor integration into medical devices and diagnostic equipment in the United States, while the EU AI Act introduces conformity obligations for autonomous measurement systems deployed in critical infrastructure. OSHA machine safety standards mandate periodic sensor verification in heavy manufacturing environments, creating recurring aftermarket demand for calibration services and replacement units. Stakeholders must monitor how converging cybersecurity requirements for connected industrial sensors reshape product development roadmaps and certification timelines.
Market Dynamics
Automotive electrification programs are recalibrating sensor procurement priorities, with battery management systems and powertrain validation protocols demanding higher channel counts and faster sampling rates than legacy internal combustion test benches.
Growth Catalysts
- Battery Management System Deployment:Electric vehicle manufacturers in Germany and South Korea are scaling validation test cells for lithium-ion thermal runaway detection, requiring multi-point temperature and pressure sensor arrays.
- EU F-Gas Regulation:Refrigeration and HVAC equipment servicing mandates are tightening leak detection calibration standards, expanding demand for refrigerant-specific pressure transducers with traceable ISO 17025 certificates.
- Surgical Robotics Certification:FDA quality system regulations for force-torque sensors in minimally invasive instruments are multiplying pre-market validation requirements across Boston and Minneapolis medical device clusters.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium dependencies for high-performance torque sensors concentrate processing capacity in Chinese refining operations, exposing European sensor assemblers to input volatility.
- REACH Compliance Costs:ECHA substance restrictions on bonding agents and encapsulants are forcing reformulation of MEMS packaging materials, elevating qualification timelines for new sensor designs.
- Optical Interferometry Substitution:Non-contact displacement measurement systems are capturing precision positioning applications previously served by capacitive and inductive proximity sensors in semiconductor fabrication equipment.
Strategic Opportunities
- Indian Industrial Automation:PLI scheme incentives for electronics manufacturing are attracting sensor packaging investments to Tamil Nadu and Karnataka, creating localized supply for domestic machine tool builders.
- Wearable Diagnostic Integration:Continuous glucose monitoring and cardiac rhythm patch devices are opening miniature force and pressure sensor applications with specialized biocompatibility requirements.
- Digital Twin Convergence:Real-time sensor data streams feeding physics-based simulation models are creating bundled hardware-software procurement opportunities for aerospace structural health monitoring programs.
Industry Challenges
- Metrology Talent Scarcity:ISO 17025 calibration laboratory accreditation requires specialized personnel for uncertainty budgeting and inter-laboratory comparisons, constraining service network expansion.
- Cybersecurity Certification Overhead:IEC 62443 conformity assessments for connected industrial sensors are extending product development cycles and fragmenting engineering resources across hardware and software validation tracks.
- Legacy System Integration Friction:Analog-output sensors in established manufacturing lines resist replacement by digital IO-Link variants without costly programmable logic controller reprogramming and production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test and Measurement Sensors Market |
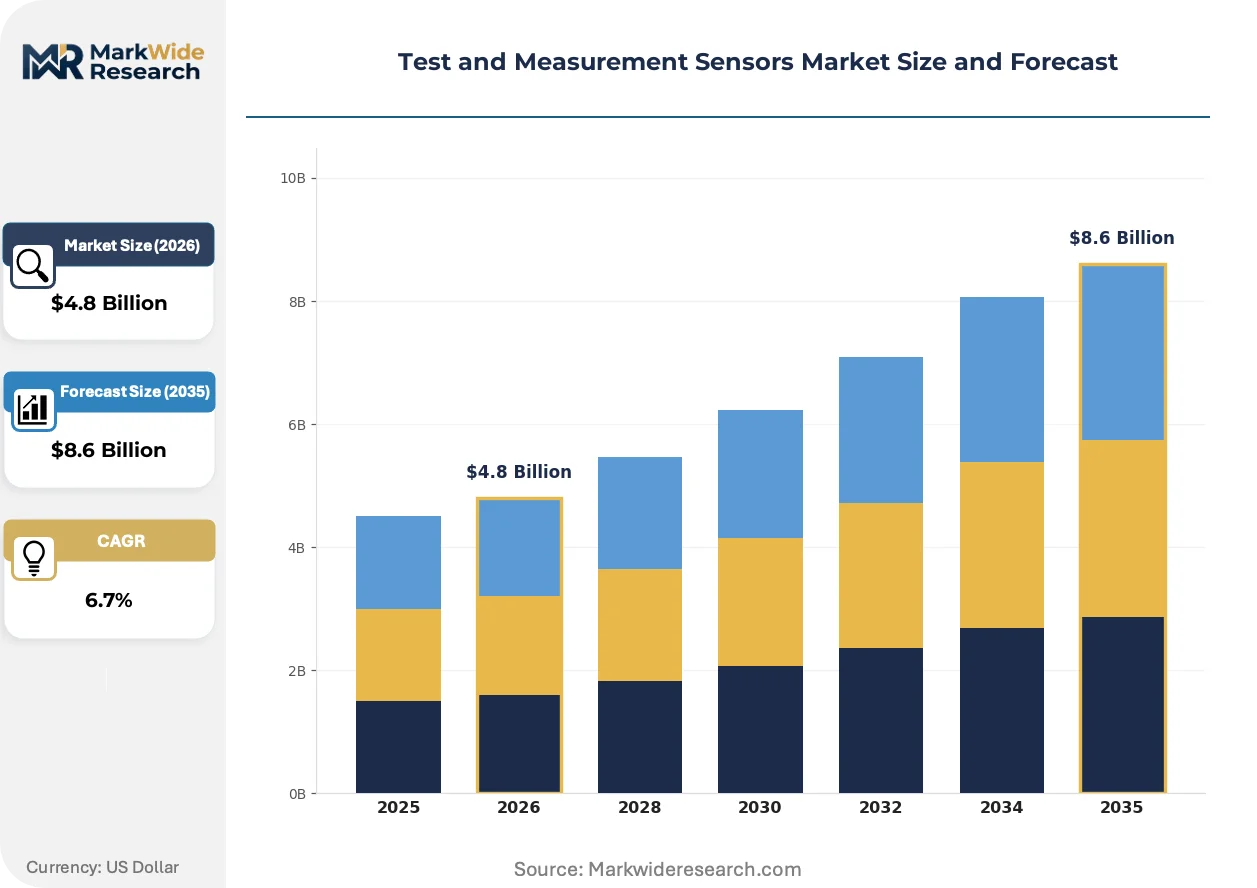
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Pressure Sensors, Temperature Sensors, Flow Sensors, Humidity Sensors Application: Industrial Automation, Environmental Monitoring, Medical Devices, Consumer Electronics End User: Manufacturing, Healthcare, Automotive, Aerospace Technology: Piezoresistive, Thermocouples, Capacitive, Optical |
| Companies Covered | Honeywell International Inc., Kistler Group, TE Connectivity, FUTEK Advanced Sensor Technology, PCB Piezotronics, KEYENCE Corporation, Spectris PLC, Hoskin Scientific, Tekscan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test and Measurement Sensors Market Evolving Landscape
Silicon carbide fabrication processes and edge-native signal processing architectures are compressing sensor response latencies while expanding operating temperature envelopes for electrified powertrain testing.
MEMS-based piezoresistive pressure transducers are absorbing validation workloads previously handled by bonded strain gauge configurations in automotive brake system test rigs. Tier 1 suppliers in Stuttgart are qualifying these devices for 150°C continuous operation. The shift is compressing per-channel costs while demanding higher initial capital outlays for wafer-level calibration equipment.
EU AI Act conformity obligations for autonomous measurement systems deployed in critical infrastructure are mandating explainability documentation for sensor fusion algorithms. Industrial automation OEMs must now maintain version-controlled calibration datasets alongside hardware traceability records. German machine safety inspectors are prioritizing audit resources toward predictive maintenance sensor networks in chemical processing plants.
Subscription-based calibration service models are displacing transactional aftermarket purchases among precision manufacturing clusters in Switzerland and Japan. Sensor OEMs are unbundling hardware warranties from metrology service contracts, creating recurring revenue streams tied to ISO 17025 certificate renewal cycles. This restructuring is most visible in pharmaceutical packaging line installations where FDA process analytical technology mandates drive strict verification schedules.
Test and Measurement Sensors Market Segmentation
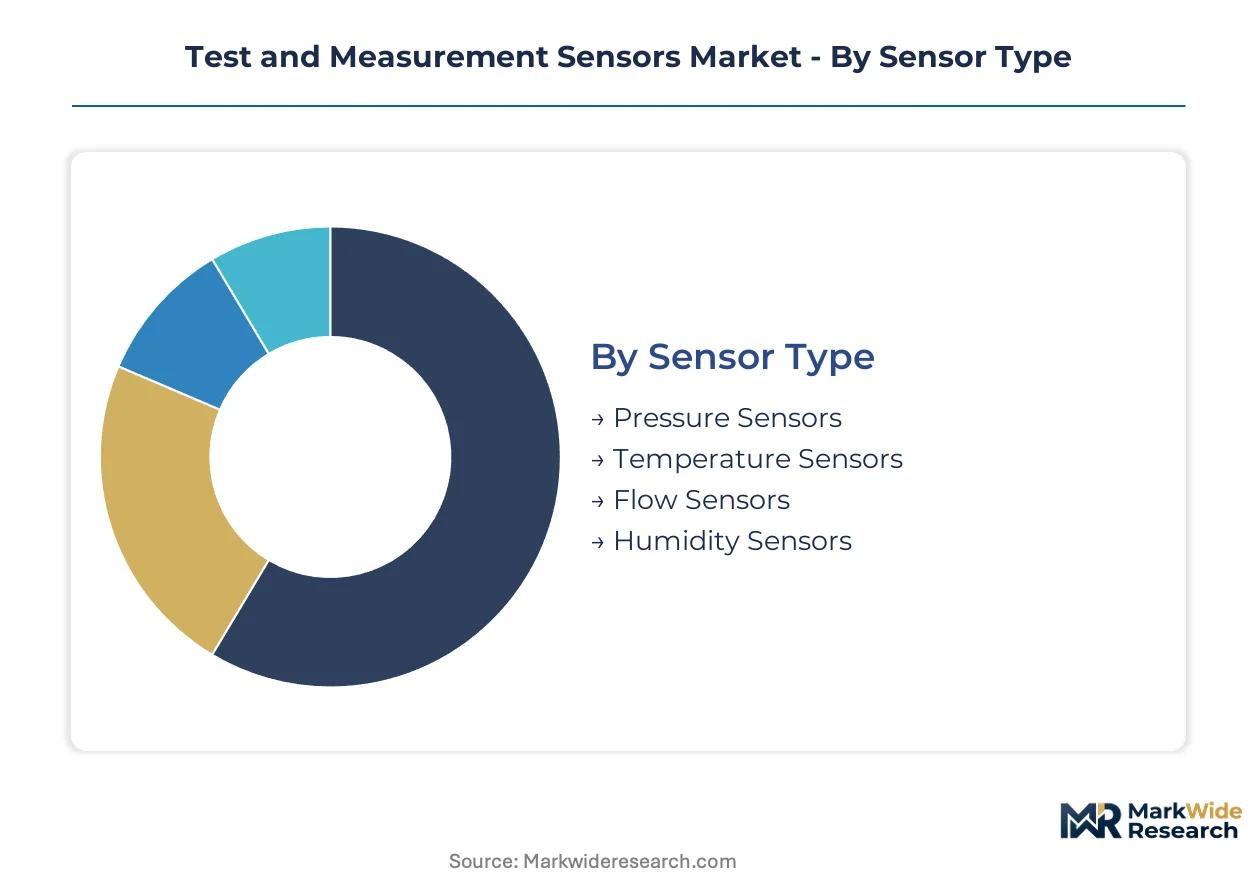
Test and measurement sensors serve heterogeneous validation requirements across automotive crash testing, pharmaceutical process control, and aerospace structural health monitoring. Segmentation reveals how sensor specifications diverge between high-volume industrial automation procurement and low-volume, high-precision medical device integration. Procurement patterns cluster around calibration traceability tiers rather than raw performance metrics alone.
Sensor Type:
Pressure sensors command the highest shipment volumes, while temperature sensors capture premium pricing through specialized thermal runaway detection applications.
- Pressure Sensors:MEMS-based piezoresistive transducers dominate hydraulic and pneumatic system diagnostics in German automotive test cells. Stuttgart-based Tier 1 suppliers are qualifying these devices for 150°C continuous operation in electrified powertrain validation.
- Temperature Sensors:Multi-point thermocouple arrays serve lithium-ion battery thermal runaway detection protocols in South Korean and German electric vehicle manufacturing. FDA process analytical technology mandates in pharmaceutical packaging lines drive strict ISO 17025 verification schedules for these components.
- Flow Sensors:Coriolis and thermal mass configurations meter process fluids in chemical manufacturing plants across the US Gulf Coast.
- Humidity Sensors:Thin-film capacitive elements monitor cleanroom environments in semiconductor fabrication facilities in Taiwan and South Korea.
Mature deployment sits with pressure sensors in established manufacturing lines. Newer deployment is concentrated in temperature sensor arrays for battery management system validation.
Application:
Industrial automation absorbs the highest sensor volumes, though medical devices generate the steepest expansion trajectory through surgical robotics certification requirements.
- Industrial Automation:Force-torque sensors in robotic welding cells and vibration monitoring accelerometers on rotating machinery constitute the baseline demand pool. OSHA machine safety standards mandate periodic verification, creating recurring aftermarket demand for calibration services.
- Environmental Monitoring:EU F-Gas Regulation compliance is tightening leak detection calibration standards for refrigeration and HVAC equipment servicing. Refrigerant-specific pressure transducers with traceable ISO 17025 certificates are expanding in German and French industrial clusters.
- Medical Devices:Force-torque sensors in minimally invasive surgical instruments face multiplying pre-market validation requirements under FDA quality system regulations. Boston and Minneapolis medical device clusters are driving specialized biocompatibility qualification for miniature pressure and force sensing elements.
- Consumer Electronics:MEMS accelerometers and pressure sensors in wearable fitness trackers and smartphones represent high-volume, low-margin procurement with compressed calibration requirements.
Established revenue concentration rests with industrial automation. Margin expansion is climbing the fastest in medical devices as surgical robotics and continuous glucose monitoring multiply certification complexity.
End User:
Manufacturing procurement prioritizes channel density and sampling speed, while healthcare buyers emphasize traceability documentation and biocompatibility certification.
- Manufacturing:Machine tool builders in Germany and Japan deploy multi-axis force sensors for tool condition monitoring and predictive maintenance. Analog-output sensors in legacy production lines resist replacement by digital IO-Link variants without costly programmable logic controller reprogramming.
- Healthcare:Surgical robotics OEMs in the US and Switzerland source specialized force-torque sensors with FDA and Swissmedic conformity documentation. Continuous glucose monitoring and cardiac rhythm patch devices are opening miniature sensor applications with specialized biocompatibility requirements.
- Automotive:Battery management system and powertrain validation protocols demand higher channel counts and faster sampling rates than legacy internal combustion test benches. Electric vehicle manufacturers in Germany and South Korea are scaling validation test cells for lithium-ion thermal runaway detection.
- Aerospace:Structural health monitoring programs are creating bundled hardware-software procurement opportunities as real-time sensor data streams feed physics-based simulation models. Piezoelectric accelerometer technology from specialized suppliers serves vibration monitoring in airframe testing.
Volume concentration remains with manufacturing end users. Technology migration is most pronounced in automotive as electrification programs recalibrate sensor procurement priorities.
Technology:
Piezoresistive technology dominates cost-sensitive applications, while optical methods capture displacement measurement precision previously served by contact-based alternatives.
- Piezoresistive:Silicon MEMS fabrication enables high-volume production of pressure and force sensors with compressed per-channel costs. Wafer-level calibration equipment demands higher initial capital outlays but sustains margin structures amid material cost shifts.
- Thermocouples:Type K and Type T configurations provide wide temperature range measurement in industrial process control and aerospace engine testing. Standardized outputs simplify integration with established data acquisition systems.
- Capacitive:Proximity and displacement sensors serve precision positioning in semiconductor fabrication equipment, though optical interferometry substitution is capturing some precision applications.
- Optical:Fiber Bragg grating and laser interferometry systems deliver non-contact displacement measurement for semiconductor wafer alignment and precision metrology. These configurations command premium pricing through sub-micron resolution capabilities.
Cost-optimized deployment clusters around piezoresistive technology. Performance-critical displacement measurement is migrating toward optical methods in advanced manufacturing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Tamil Nadu and Karnataka are concentrating sensor packaging investments under India's PLI scheme, drawing contract manufacturers away from traditional ASEAN assembly bases.
Germany
Automotive electrification programs in Stuttgart and Munich are scaling battery management system validation test cells. ECHA REACH compliance is forcing MEMS packaging material reformulations, extending qualification timelines. Industrial automation OEMs cluster around Stuttgart for force-torque sensor procurement.
United States
FDA quality system regulations for surgical robotics are multiplying pre-market validation requirements in Boston and Minneapolis medical device clusters. OSHA machine safety standards mandate periodic sensor verification in heavy manufacturing environments. Aerospace structural health monitoring programs in Seattle and Wichita are creating bundled hardware-software procurement opportunities.
South Korea
Electric vehicle manufacturers are scaling lithium-ion thermal runaway detection protocols requiring multi-point temperature and pressure sensor arrays. MFDS medical device regulations govern diagnostic equipment integration. Busan-Ulsan industrial corridors host automotive Tier 1 suppliers qualifying MEMS devices for 150°C continuous operation.
Japan
Subscription-based calibration service models are displacing transactional aftermarket purchases among precision manufacturing clusters in Nagoya and Osaka. METI industrial standards shape sensor traceability requirements. Kanto region machine tool builders deploy multi-axis force sensors for predictive maintenance applications.
Switzerland
Swissmedic conformity documentation requirements govern surgical robotics OEM sourcing of specialized force-torque sensors. ISO 17025 calibration laboratory accreditation concentrates in Zurich and Basel metrology service networks. Pharmaceutical packaging line installations drive strict verification schedules under FDA process analytical technology mandates.
Test and Measurement Sensors Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold premium positioning in precision calibration services. The vendor base distributes across three structural tiers: diversified industrial conglomerates with captive sensor divisions, mid-scale specialists focused on single sensing modalities, and regional calibration service providers. Competitive moves center on backward integration into MEMS fabrication and geographic expansion through localized packaging investments in India and Southeast Asia.
Among diversified industrial technology groups, Honeywell International Inc. and TE Connectivity exemplify scale-driven archetypes with broad sensing portfolios spanning multiple physical measurement domains. Kistler Group occupies a position within the specialized force and torque measurement tier, representing the mid-scale specialist model focused on automotive and aerospace validation applications. These three anchors illustrate how competitive positioning stratifies between conglomerate breadth and focused technical depth.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Kistler Group |
| TE Connectivity |
| FUTEK Advanced Sensor Technology |
| PCB Piezotronics |
| KEYENCE Corporation |
| Spectris PLC |
| Hoskin Scientific |
| Tekscan |
| Others |
Value Network & Pricing Analysis
Wafer-level calibration equipment deployment is compressing per-channel sensor costs while concentrating capital requirements among German and Japanese MEMS fabricators. This production-method transition simultaneously elevates entry barriers for packaging specialists and reshapes procurement economics for automotive Tier 1 suppliers qualifying devices for 150°C continuous operation.
Pricing Analysis
Short lead-time premiums distinguish urgent replacement orders from standard contract schedules in industrial automation procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 certification tier and volume scale. Cost compression in MEMS-based pressure transducers is intensifying because Stuttgart-based suppliers absorb validation workloads previously handled by bonded strain gauge configurations. Manufacturing end users exhibit highest price sensitivity, while surgical robotics OEMs in Boston and Minneapolis accept premium positioning for FDA conformity documentation.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for sensor packaging investments toward Tamil Nadu and Karnataka special economic zones. German and Japanese MEMS fabrication anchors upstream supply, while Chinese refining operations concentrate neodymium and dysprosium processing for high-performance torque sensors. Single-source vulnerability in rare earth magnet supply exposes European sensor assemblers to input volatility. Distribution runs through Tier 1 automotive suppliers and industrial automation OEMs with captive calibration service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH compliance costs and cybersecurity certification overhead that weaker players cannot absorb. ECHA substance restrictions and IEC 62443 conformity assessments are forcing exits among regional calibration service providers lacking capital for reformulation and software validation tracks.
For Market Incumbents: Anchor competitive position through backward integration into MEMS fabrication and geographic expansion through localized packaging investments in India. TE Connectivity's vertical integration model demonstrates how captive wafer-level calibration sustains margin structures amid material cost shifts. Defend against optical interferometry substitution by embedding edge-native signal processing architectures that compress response latencies for electrified powertrain testing.
For New Entrants and Emerging Players: Begin with wearable diagnostic integration in continuous glucose monitoring and cardiac rhythm patch devices, where specialized biocompatibility requirements create qualification barriers for established industrial sensor suppliers. India's PLI scheme incentives offer the most penetrable geography for contract manufacturing entry. Pursue hospital system partnerships and Swissmedic conformity documentation as the primary go-to-market angle for surgical robotics sensor qualification.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists possessing ISO 17025 calibration laboratory accreditation and force-torque measurement depth given subscription-based service model adoption in Swiss and Japanese precision manufacturing clusters. Long-term viability favors targets with bundled hardware-software procurement capabilities for aerospace structural health monitoring programs. Watch digital twin convergence adoption rates in Seattle and Wichita as the inflection indicator for physics-based simulation model integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive wafer-level calibration sustains margins amid REACH-driven material reformulation costs. |
| Geographic Expansion to India PLI Zones | Tamil Nadu and Karnataka packaging investments localize supply for domestic machine tool builders. |
| Subscription-Based Calibration Service Model | Recurring ISO 17025 certificate renewal revenue displaces transactional aftermarket purchases in pharmaceutical packaging. |
| Edge-Native Signal Processing Architecture | Silicon carbide fabrication compresses latencies for 150°C electrified powertrain validation applications. |
| Cybersecurity Certification Investment | IEC 62443 conformity assessments extend product development cycles but lock out undercapitalized competitors. |
Research Methodology
Multi-period observation of MEMS fabrication capacity expansion, REACH compliance timelines, and automotive electrification program procurement patterns anchored the trend analysis, supplemented by interviews with MEMS fabrication engineers, automotive Tier 1 supplier procurement directors, calibration laboratory accreditation specialists, pharmaceutical packaging line engineers, and industrial automation OEM platform architects. Secondary validation drew from ECHA substance restriction databases, FDA quality system regulation filings, SEC 10-K disclosures from diversified industrial technology groups, and METI industrial standard publications. Bottom-up sensor shipment tracking across pressure, temperature, and force-torque categories triangulated against top-down automotive and medical device end-use demand estimates.
Input-output matrix modeling connected raw material flows through neodymium refining operations, MEMS wafer fabrication, and final sensor packaging to end-use demand segments. Segmentation dimensions included sensor type, application category, end-user industry, and technology platform across the projection horizon. CAGRs derived from least-squares fitting of annual shipment data adjusted for qualification timeline delays and regulatory implementation schedules. Industry-specific forecast inputs incorporated electric vehicle thermal runaway detection protocol adoption rates and surgical robotics FDA pre-market validation pipeline status.
Underlying measurement precision varies by segment; medical device and aerospace applications carry tighter precision than consumer electronics procurement. Forecasts reflect documented assumptions regarding REACH implementation timelines, PLI scheme incentive continuity, and rare earth supply chain stability. Cybersecurity certification overhead, metrology talent scarcity, and legacy system integration friction constitute specific risk factors that could revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Roughness Tester Market
Test and Measurement
Mechanical Testing Equipment Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Production Testing Market
Test and Measurement
LAN Tester Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Calibration Management Software Market