
 Atomic Clock Market | 2026-2036
Atomic Clock Market Size, Share, and Industry Trends Forecast 2026-2036
Atomic Clock Market Analysis
Switzerland is rewriting the competitive map for atomic clock manufacturing through Oscilloquartz's specialized focus on telecom-grade rubidium and cesium standards. Safran leverages its aerospace heritage to anchor European defense and satellite positioning contracts. Frequency Electronics, Inc. sustains its position through in-house production of precision quartz oscillators that feed into integrated atomic timing systems.
An atomic clock maintains time by measuring the electromagnetic signal that electrons in atoms emit when they change energy levels, achieving stability to within one second over millions of years using cesium-133 or rubidium-87 hyperfine transitions. Its primary purpose is to provide the foundational frequency standard for GPS navigation, telecommunications synchronization, and scientific measurement infrastructure. Embedded atomic clocks dominate telecommunications deployments where rack-mounted synchronization units integrate directly into base station equipment. Optical lattice technology represents the fastest-growing segment as national metrology laboratories and defense agencies pursue next-generation precision beyond microwave-based standards.
The U.S. Commerce Department's Bureau of Industry and Security regulates atomic clock exports through the Commerce Control List, while the International Telecommunication Union sets synchronization standards that shape telecom procurement specifications. The European Union's Radio Equipment Directive and CE marking requirements govern market access for timing devices deployed in critical infrastructure. Stakeholders must monitor how quantum technology national security classifications in major economies reshape supply chain access for optical and trapped-ion clock components.
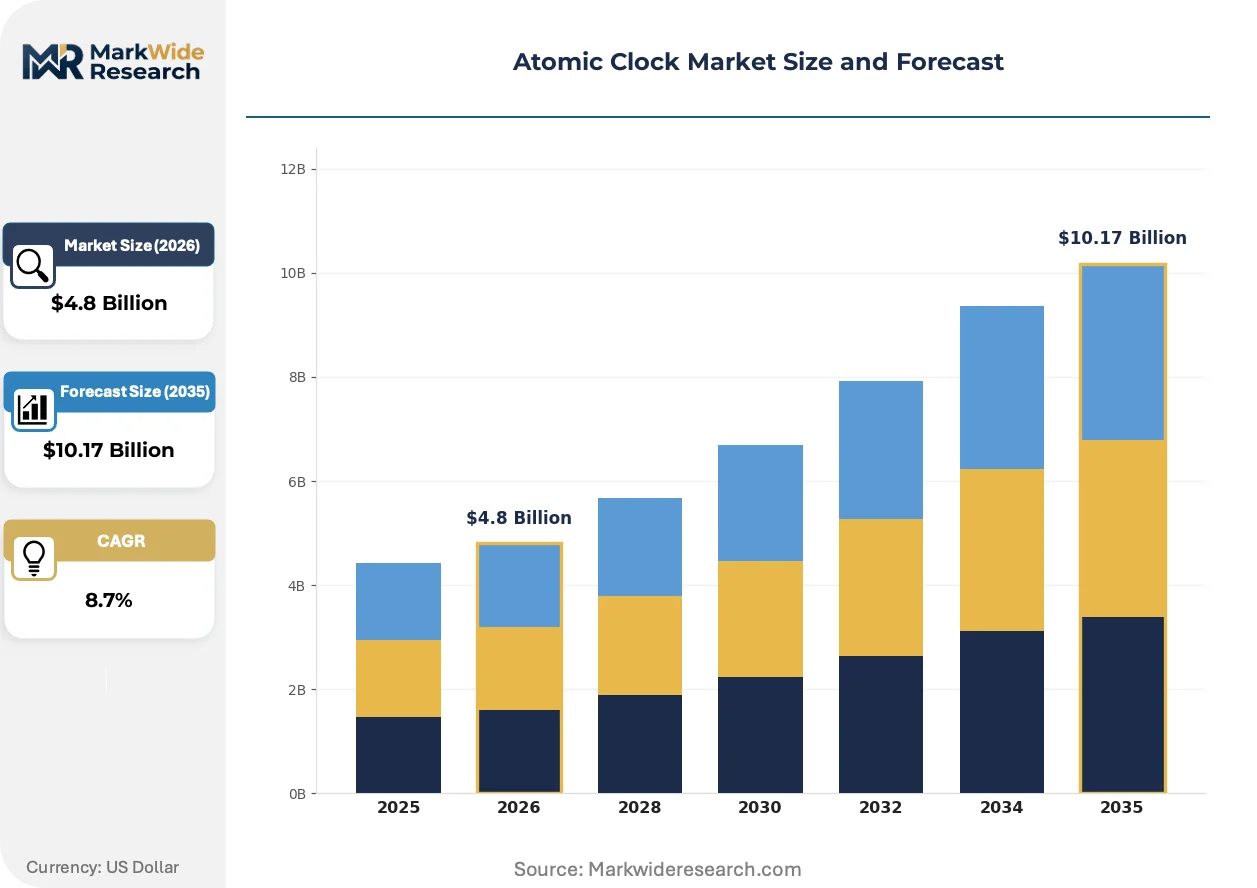
Market Dynamics
The transition from microwave-based cesium and rubidium standards to optical lattice and trapped-ion architectures is fragmenting established supplier hierarchies and forcing capital reallocation across defense, telecom, and metrology procurement channels.
Growth Catalysts
- 5G Network Synchronization Mandates:Telecommunications infrastructure operators require embedded atomic clocks for base station timing precision, with the International Telecommunication Union setting synchronization standards that shape procurement specifications.
- Export Control Tightening:The U.S. Department of Commerce Bureau of Industry and Security regulates frequency source exports through the Commerce Control List, creating captive demand for domestic and allied-nation suppliers.
- Optical Lattice Clock Maturation:National metrology laboratories are pursuing next-generation precision beyond microwave standards, accelerating investment in ytterbium and strontium-based systems for scientific and defense applications.
Market Restraints
- Cesium Fountain Construction Costs:Laboratory-grade primary frequency standards require specialized vacuum chambers and laser systems, with input cost volatility in high-purity cesium-133 and precision optical components constraining deployment scale.
- Optical Component Supply Concentration:Frequency-doubled lasers and ultrastable cavities concentrate among specialized photonics manufacturers in Germany, Switzerland, and the United States, creating single-source vulnerability for next-generation clock builders.
- Technical Limitation in Miniaturization:Chip-scale atomic clocks sacrifice stability for size, with physics package volume constraints preventing their use in submarine navigation and deep-space missions requiring 10^-14 fractional frequency uncertainty.
Strategic Opportunities
- Underpenetrated Satellite Constellation Timing:China's investment in domestic optical lattice clock programs for BeiDou navigation independence creates alternative procurement pathways for non-Western satellite operators seeking timing autonomy.
- Quantum Technology National Security Classifications:Major economies are reshaping supply chain access for trapped-ion and optical clock components, creating regulatory tailwinds for cleared domestic manufacturers.
- Integration with Quantum Sensors:Atomic clock technology is converging with cold-atom gravimeters and gyroscopes, enabling unified inertial navigation platforms for submarine and aircraft applications without GPS dependency.
Industry Challenges
- Atomic Physics Talent Scarcity:The specialized skill set spanning laser cooling, optical frequency combs, and ultra-high vacuum systems concentrates among national laboratories and elite university programs, constraining workforce expansion for commercial manufacturers.
- ITAR and EAR Compliance Timelines:Defense-grade atomic clocks require months-long export licensing through the U.S. State Department's International Traffic in Arms Regulations or Commerce Department's Export Administration Regulations, compressing contract execution windows.
- Legacy System Integration Complexity:Microwave-based cesium standards deployed in telecommunications and aviation infrastructure use proprietary interfaces, forcing costly adapter development for optical clock retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atomic Clock Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Embedded, Portable, Networked End User: Telecommunications, Aerospace, Defense, Research Technology: Optical, Microwave, Quantum, Atomic Beam Application: GPS, Timekeeping, Synchronization, Frequency Standard |
| Companies Covered | Microchip Technology Inc., Safran, Excelitas Technologies Corp., Leonardo S.p.A., Oscilloquartz, Frequency Electronics, Inc., AccuBeat Ltd., Thermo Fisher Scientific Inc., Stanford Research Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atomic Clock Market Emerging Trajectories
Optical frequency comb technology is bridging the gap between optical and electronic domains, enabling practical deployment of lattice clocks outside laboratory environments while forcing established microwave-standard manufacturers to accelerate R&D timelines.
Optical lattice clocks using strontium and ytterbium atoms achieve 10^-18 fractional frequency uncertainty, surpassing cesium fountains by two orders of magnitude. National metrology institutes in the United States, Japan, and Germany are deploying these systems for redefining the SI second. The technology is digitizing precision time distribution by enabling direct optical fiber links that eliminate intermediate microwave conversion stages.
The European Union's Radio Equipment Directive and CE marking requirements now govern timing devices deployed in critical infrastructure, with specific electromagnetic compatibility and safety testing protocols. This regulatory framework is forcing non-European manufacturers to establish notified body relationships and local technical documentation capabilities. Telecom-grade atomic clock vendors serving European 5G rollouts face the most immediate compliance pressure.
Defense agencies are consolidating atomic clock procurement under multi-year platform contracts rather than component-level purchases. This behavioral shift is displacing traditional spot-market sales with integrated subsystem sourcing that bundles timing, inertial navigation, and anti-jam capabilities. The United States Department of Defense and China's People's Liberation Army Strategic Support Force are most visible in this transition, with prime contractors absorbing supplier selection risk.
Atomic Clock Market Segmentation
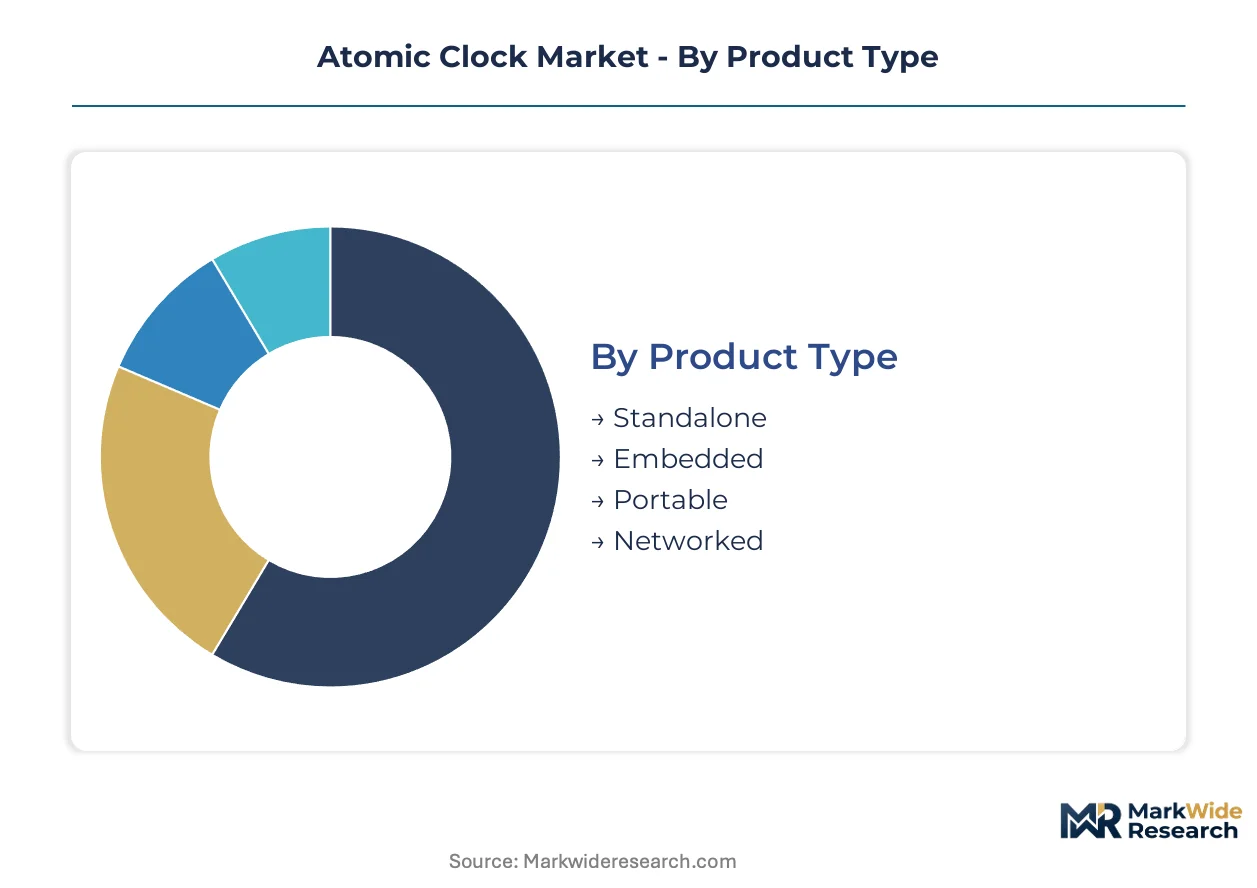
Atomic clock procurement patterns diverge sharply across deployment contexts. Product architecture, end-use security classification, and underlying physics package determine pricing tiers, compliance pathways, and supplier qualification requirements.
Product Type:
Cost tier separates rack-mounted infrastructure investments from field-deployable units and integrated subsystems.
- Standalone:Laboratory-grade cesium fountains and hydrogen masers occupy climate-controlled facilities. National metrology institutes in the United States, Germany, and Japan anchor procurement for primary frequency standard maintenance.
- Embedded:Telecom base stations integrate rubidium or miniaturized cesium oscillators directly into synchronization equipment. 5G network densification across South Korea and Switzerland concentrates demand for temperature-compensated physics packages with holdover stability.
- Portable:Battery-operated units serve calibration teams and temporary deployment scenarios. Field service organizations prioritize reduced warmup time over absolute stability.
- Networked:Distributed timing architectures enable redundant time distribution across financial trading floors and broadcast facilities. Ethernet-based precision time protocol compatibility governs specification sheets.
Embedded holds installed capacity. Optical-cooled portable units are rotating up the share rankings.
End User:
Application security classification drives procurement channel segmentation and regulatory overlay intensity.
- Telecommunications:ITU-T synchronization standards govern base station timing hierarchy. European operators under the Radio Equipment Directive face accelerated compliance timelines for 5G standalone core deployments.
- Aerospace:Satellite constellations require radiation-hardened oscillators with decade-long operational lifetimes. China's BeiDou expansion and European Galileo refresh programs concentrate contract awards.
- Defense:ITAR and EAR licensing constrain supplier pools for submarine navigation and strategic aircraft platforms. U.S. Department of Defense multi-year platform contracts displace component-level purchasing.
- Research:National laboratories pursue optical lattice systems for SI second redefinition. German and Japanese metrology institutes lead ytterbium-based fountain construction.
Telecommunications dominates volume throughput. Defense is climbing the fastest on contract value metrics.
Technology:
Maturity gradient separates established microwave standards from emerging optical architectures requiring specialized component supply.
- Optical:Strontium and ytterbium lattice clocks achieve 10^-18 fractional uncertainty. Frequency-doubled lasers from German and Swiss photonics suppliers constrain production scaling.
- Microwave:Cesium-133 and rubidium-87 hyperfine transitions anchor GPS and telecom synchronization. Cesium fountain construction costs limit deployment to national standards laboratories.
- Quantum:Trapped-ion systems target navigation applications without GPS dependency. U.S. and Chinese defense agencies classify related supply chains under emerging quantum technology controls.
- Atomic Beam:Traditional cesium beam tubes persist in legacy aviation and telecommunications infrastructure. Replacement part demand sustains limited manufacturing lines.
Microwave retains installed base dominance. Optical is gaining share fastest on precision benchmarks.
Application:
Customer workflow integration determines interface requirements and stability thresholds.
- GPS:Satellite navigation payloads require space-qualified rubidium and passive hydrogen masers. Constellation timing autonomy drives China's domestic optical lattice investment.
- Timekeeping:Financial networks and power grid synchronization demand traceability to UTC. U.S. NIST and German PTB serve as reference distribution anchors.
- Synchronization:5G fronthaul and backhaul networks require sub-microsecond phase alignment. European operators face CE marking compliance for critical infrastructure deployment.
- Frequency Standard:Scientific instrumentation and calibration services anchor cesium fountain demand. Metrology laboratory procurement cycles extend across multi-year funding horizons.
GPS anchors satellite manufacturing pipelines. Synchronization is expanding most quickly on telecom capital expenditure cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors atomic clock deployment through GPS satellite infrastructure and Department of Defense navigation platforms. National metrology laboratories maintain primary frequency standards that cascade precision timing across telecommunications and financial networks worldwide.
United States
The U.S. Department of Defense multi-year platform contracts bundle atomic timing with inertial navigation subsystems, displacing component-level procurement. Bureau of Industry and Security export controls through the Commerce Control List restrict frequency source transfers to allied nations. Colorado hosts concentrated defense aerospace contracting activity for satellite payload timing systems.
Switzerland
Telecom-grade rubidium and cesium standards from specialized manufacturers serve European 5G network densification requirements. The country's national metrology institute maintains traceability to UTC while supporting optical lattice clock research programs. Geneva-area precision instrumentation clusters coordinate with CERN for ultra-stable frequency distribution infrastructure.
Germany
The Physikalisch-Technische Bundesanstalt leads ytterbium-based optical fountain construction for SI second redefinition initiatives. EU Radio Equipment Directive CE marking requirements govern timing device market access for critical infrastructure deployment. Munich and Stuttgart photonics manufacturing regions supply frequency-doubled lasers and ultrastable cavities to next-generation clock builders.
China
Domestic optical lattice clock programs target BeiDou navigation constellation timing autonomy independent of Western standards. The People's Liberation Army Strategic Support Force consolidates procurement under integrated platform contracts mirroring U.S. defense practices. Beijing and Shanghai host concentrated satellite manufacturing and metrology research facilities advancing strontium-based systems.
Japan
National Institute of Information and Communications Technology operates hydrogen maser networks supporting scientific and telecommunications applications. METI funding programs accelerate optical lattice clock commercialization beyond laboratory environments. Tokyo-Yokohama precision manufacturing corridors supply optical frequency comb components for time distribution digitization.
Atomic Clock Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying physics packages and precision oscillators. The supplier base fragments across defense prime contractors, telecom equipment vendors, and metrology instrument specialists with limited overlap in customer access. Three archetypes dominate: aerospace heritage primes bundling timing into navigation platforms, telecom-focused embedded clock manufacturers, and laboratory instrument builders serving research institutions. Competitive maneuvering concentrates on multi-year platform contract capture and optical technology licensing arrangements for next-generation standards.
Among established precision timing specialists, Microchip Technology Inc., Safran, and Oscilloquartz occupy positions spanning distinct application tiers. Microchip Technology represents the diversified semiconductor supplier archetype integrating atomic timing into broader frequency control portfolios. Safran exemplifies aerospace-defense platform integration, leveraging satellite and navigation heritage for bundled subsystem procurement. Oscilloquartz anchors the telecommunications-specialist position, with Swiss manufacturing concentration supporting European infrastructure compliance requirements.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Safran |
| Excelitas Technologies Corp. |
| Leonardo S.p.A. |
| Oscilloquartz |
| Frequency Electronics, Inc. |
| AccuBeat Ltd. |
| Thermo Fisher Scientific Inc. |
| Stanford Research Systems |
| Others |
Supply Flow & Price Mechanics
German and Swiss photonics manufacturers concentrate frequency-doubled laser and ultrastable cavity production, anchoring margin capture in optical lattice clock tiers while forcing downstream assemblers into long-term supply agreements or captive facility investments.
Pricing Analysis
The U.S. Commerce Control List and ITAR classification tiers dictate the pricing tier structure across defense, telecom, and research procurement channels. Three-tier pricing structure across ITAR-restricted, CE-marked infrastructure, and laboratory-grade levels separates compliance-burdened aerospace contracts from volume telecom deployments. Pricing pressure stems from cesium-133 purity volatility and optical component single-source vulnerability. Defense agencies show least price sensitivity given platform contract bundling, while telecommunications operators face acute pressure from 5G capital expenditure cycles.
Supply Chain Analysis
Extended payment terms from prime contractors now reach 90-120 days for physics package suppliers, compressing working capital for specialized vacuum chamber and laser system manufacturers. Germany, Switzerland, and the United States anchor precision optical component fabrication, while China concentrates rubidium oscillator and satellite payload integration. Cesium-133 isotope refinement and ytterbium/strontium atomic sourcing rest on limited metallurgical processing capacity. Single-source vulnerability in frequency-doubled laser supply creates procurement risk. Distribution runs through defense prime contractors, telecom equipment vendors, and metrology laboratory procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through U.S. Department of Defense and Chinese People's Liberation Army platform contract consolidation, fragmenting component-level vendor access while elevating subsystem integrators.
For Market Incumbents: Insulate aerospace and defense revenue streams through ITAR facility certification and captive optical component supply. Acquire photonics specialists in Germany or Switzerland to secure frequency-doubled laser access. Lock in multi-year BeiDou and Galileo refresh program participation before Chinese domestic suppliers achieve optical lattice independence. For New Entrants and Emerging Players: Establish a beachhead in portable field-calibration units where reduced warmup specifications lower physics package complexity barriers. Target European 5G standalone core deployments under Radio Equipment Directive compliance windows. Pursue white-label embedded clock supply to telecom equipment vendors lacking in-house timing expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrumentation platforms holding metrology laboratory relationships but lacking defense clearance. Five-to-ten year viability hinges on optical lattice commercialization timelines and quantum technology classification shifts. Watch for NIST or PTB SI second redefinition announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Lattice Clock Commercialization | NIST and PTB SI second redefinition programs validate strontium-based systems for defense and scientific markets. |
| ITAR Facility Certification Investment | U.S. Department of Defense platform contracts require cleared manufacturing for submarine navigation timing subsystems. |
| German Photonics Supplier Acquisition | Frequency-doubled laser concentration in Munich-Stuttgart corridor creates captive supply rationale for clock assemblers. |
| Telecom Embedded Clock Partnership | European 5G Radio Equipment Directive compliance windows concentrate procurement decisions through 2026-2027. |
| Quantum Sensor Platform Integration | Cold-atom gravimeter convergence enables unified inertial navigation for GPS-denied submarine and aircraft applications. |
Methodological Framework
A standing panel of atomic clock program managers at national metrology institutes, defense procurement officers, telecom network synchronization engineers, and precision photonics manufacturing executives provided ongoing calibration throughout the study period. Primary interview findings triangulated against secondary sources including U.S. Bureau of Industry and Security export classification rulings, EU Radio Equipment Directive technical documentation, ITU-T synchronization standards filings, and NIST/PTB research publication databases. Bottom-up physics package cost modeling and top-down defense contract award analysis converged on segment-level demand estimates.
Scenario-bracketing around optical lattice clock maturation timelines and quantum technology national security classification expansions bounded high-low demand cases across the projection horizon. Segmentation modeling incorporated product architecture, end-user security classification, underlying physics package technology, and regional regulatory framework dimensions. CAGRs derived from equipment procurement cycle analysis and metrology laboratory funding trajectory assessment. Forecast inputs included BeiDou constellation expansion schedules, European 5G standalone core deployment timelines, and cesium-133 supply chain capacity utilization.
Sensitivities concentrate around NIST optical lattice SI second redefinition timing, U.S.-China technology export control escalation, and European critical infrastructure timing device localization mandates. Forecasts reflect documented assumptions regarding defense budget continuity and telecommunications capital expenditure patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Area Sensor Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Doppler Wind Lidar System Market