
 Manifold Absolute Pressure Sensor Market | 2026-2036
Manifold Absolute Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Manifold Absolute Pressure Sensor Market Foresight
The EU Green Deal's embedded vehicle emissions targets is realigning procurement specifications across European powertrain suppliers. Robert Bosch GmbH leverages captive semiconductor fabrication to secure die supply for integrated pressure modules. Sensata Technologies anchors North American aftermarket distribution through direct Tier-1 relationships with Detroit-based OEMs. Continental AG dominates piezoresistive MEMS design for turbocharger boost sensing in high-compression gasoline engines.
A manifold absolute pressure sensor measures intake manifold vacuum or boost pressure, typically employing a piezoresistive silicon diaphragm bonded to a glass substrate with Wheatstone bridge circuitry outputting 0.5–4.5V analog or SENT-protocol digital signals to the engine control unit for air-fuel ratio optimization. Digital product variants command premium positioning where SENT and PSI5 protocol compliance enables direct ECU integration without external analog-to-digital conversion. MEMS technology leads unit volume through wafer-level packaging economies, while capacitive architectures occupy aerospace applications demanding radiation-hardened performance. Automotive end users consume the dominant share as turbocharger penetration and cylinder deactivation strategies multiply sensor count per powertrain.
EPA tailpipe standards and NHTSA corporate average fuel economy mandates compel U.S. manufacturers to embed precision MAP sensing for real-time volumetric efficiency calculation. EMA's MDR-aligned quality frameworks and REACH substance restrictions constrain European sensor material selections, particularly lead-free solder and halogen-free molding compounds. Stakeholders must monitor pending EPA Tier 4 off-road emissions rules and China's MIIT dual carbon implementation timelines to anticipate sensor specification shifts across heavy-duty and light-vehicle platforms.
Market Dynamics
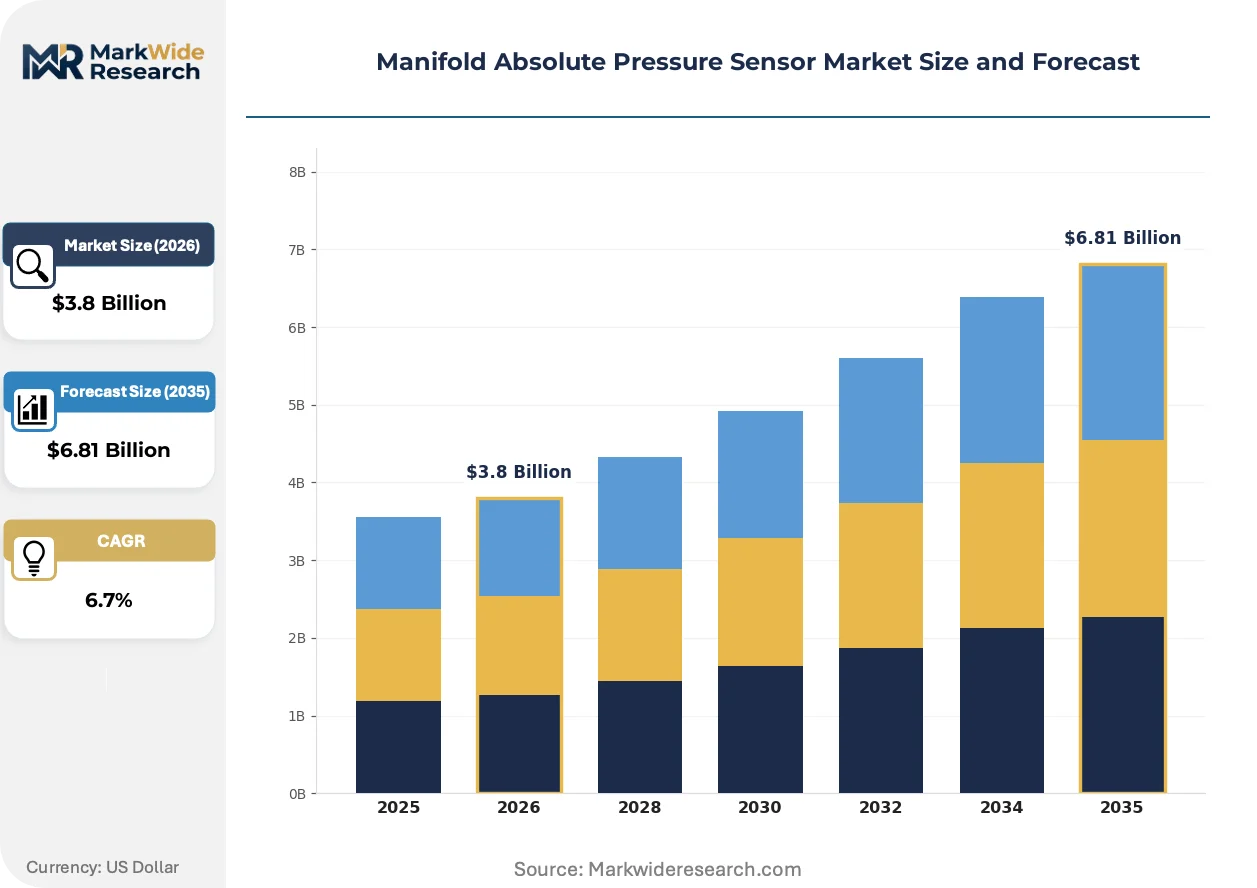
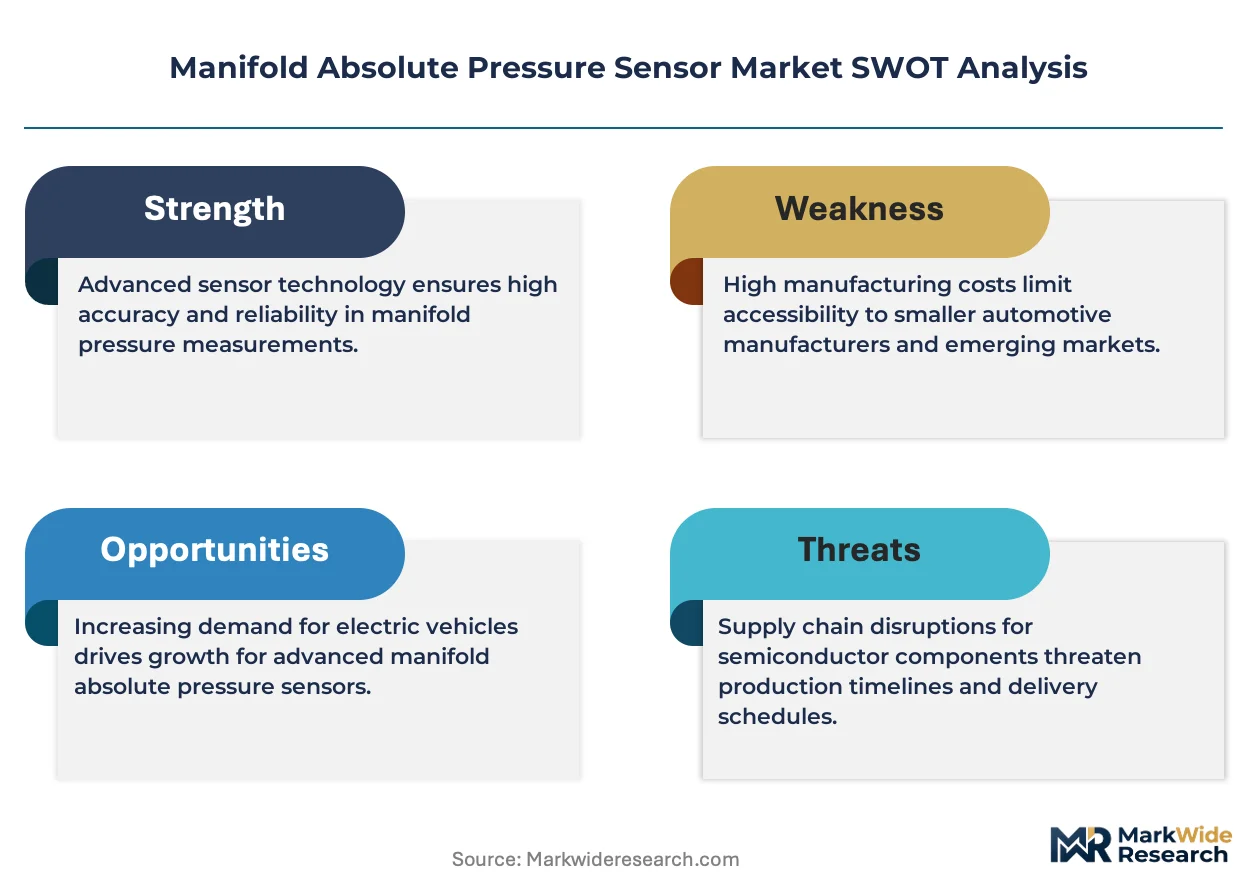
MEMS fabrication consolidation and silicon-on-insulator wafer processing economies are compressing unit costs while turbocharger penetration multiplies sensor count per powertrain, creating a volume-cost feedback loop that favors integrated module suppliers.
Growth Catalysts
- EPA Tier 4 Off-Road Emissions Rules:Pending U.S. mandates for heavy-duty diesel engines are expanding MAP sensor specification to real-time volumetric efficiency calculation in construction and agricultural equipment.
- Hybrid Powertrain Electrification:Passenger vehicle programs across Germany, China, and the United States are embedding precision boost control sensors in dual-mode combustion-electric architectures.
- SENT Protocol Standardization:Digital signal output eliminating external analog-to-digital conversion is commanding premium positioning in direct ECU integration applications.
Market Restraints
- Silicon Wafer Supply Concentration:Captive semiconductor fabrication capacity constraints in East Asian foundries create die supply vulnerability for non-integrated pressure module suppliers.
- REACH Substance Restrictions:ECHA-mandated lead-free solder and halogen-free molding compound transitions are elevating European sensor material qualification timelines.
- Capacitive Architecture Substitution:Aerospace radiation-hardened performance requirements divert high-reliability demand away from standard automotive piezoresistive MEMS platforms.
Strategic Opportunities
- China MIIT Dual Carbon Implementation:National carbon neutrality timelines are accelerating cylinder deactivation strategy adoption, multiplying sensor deployment per gasoline powertrain.
- Aftermarket Channel Disintermediation:Direct Tier-1 relationships with Detroit-based OEMs are anchoring North American service-part distribution outside traditional wholesale networks.
- Wafer-Level Packaging Convergence:MEMS thermal stability improvements combined with piezoresistive diaphragm advances are opening industrial process control applications beyond automotive.
Industry Challenges
- EMA MDR-Aligned Quality Frameworks:European medical device regulation cross-applicability to automotive sensor traceability is extending certification documentation burdens.
- Legacy Analog System Integration:0.5–4.5V Wheatstone bridge output compatibility requirements are complicating SENT-protocol digital product line rationalization.
- Specialized MEMS Process Engineering Talent:Deep expertise in silicon-glass anodic bonding and cavity sealing is concentrating within captive fabrication divisions, constraining external hiring pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manifold Absolute Pressure Sensor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Differential, Integrated Technology: Piezoresistive, Capacitive, MEMS, Strain Gauge End User: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Installation: Onboard, Offboard, Inline, Portable |
| Companies Covered | Honeywell International Inc., Sensata Technologies, Robert Bosch GmbH, TE Connectivity, BorgWarner Inc., DENSO Corporation, Infineon Technologies AG, Hitachi Automotive Systems, Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manifold Absolute Pressure Sensor Market Shifts & Advancements
Sensor architecture is fragmenting across analog-digital protocol divides while fabrication technology concentrates in wafer-level packaging platforms, reshaping competitive differentiation from performance specifications to supply security.
Silicon-on-insulator wafer processing with embedded temperature compensation is modularizing pressure module design, enabling automotive OEMs to standardize ECU interfaces across turbocharged gasoline and direct-injection diesel platforms without hardware redesign. Tier-1 suppliers adopting this substrate technology are collapsing development cycles for multi-platform powertrain programs.
EU Green Deal embedded vehicle emissions targets are realigning procurement specifications across European powertrain suppliers, forcing sensor material declarations and carbon footprint documentation into RFQ requirements. German OEMs are responding by qualifying only REACH-compliant, halogen-free molding compound variants for new platform awards.
Aftermarket procurement is consolidating around direct Tier-1 relationships that bypass traditional distribution intermediaries, compressing margin capture for wholesale channel incumbents. North American sensor buyers are shifting volume to authorized service-part programs with Detroit-based OEMs, leaving independent distributors to specialize in legacy platform coverage.
Manifold Absolute Pressure Sensor Market Segmentation
MAP sensor architecture fragments across signal protocol, fabrication method, and mounting topology. Each segmentation axis carries distinct margin profiles and supply security requirements that reshape supplier competitive positioning.
Product Type:
Signal output specification determines ECU integration complexity and module cost structure.
- Digital:SENT and PSI5 protocol compliance enables direct microcontroller interface without external ADC circuitry. German OEMs mandate digital variants for new turbocharged gasoline platforms to simplify wiring harness design.
- Analog:Wheatstone bridge outputting 0.5–4.5V dominates legacy powertrain calibration libraries. U.S. aftermarket channels retain substantial analog volume due to backward compatibility requirements in pre-2020 vehicle fleets.
- Differential:Dual-port measurement architecture cancels common-mode pressure errors in altitude-varying applications. Aerospace auxiliary power units specify differential construction for barometric reference stability.
- Integrated:Combined temperature-pressure sensing in single MEMS die reduces ECU pin count. Chinese hybrid powertrain programs are accelerating integrated module procurement for space-constrained engine bay packaging.
Digital leads on scale; integrated climbs the fastest as powertrain electrification compresses sensor real estate.
Technology:
Fabrication method governs thermal stability, radiation tolerance, and wafer-level unit economics.
- Piezoresistive:Boron-doped silicon diaphragm with implanted resistors dominates automotive volume through established foundry capacity. MEMS batch processing at 200mm wafer scale compresses die cost below capacitive alternatives for turbocharger boost sensing.
- MEMS:Wafer-level packaging with silicon-glass anodic bonding enables hermetic cavity sealing without discrete lid attach. East Asian foundry concentration creates supply vulnerability for non-captive sensor suppliers during capacity allocation cycles.
- Capacitive:Parallel-plate electrode geometry achieves radiation-hardened performance for geostationary orbit applications. Aerospace demand diverts high-reliability procurement away from standard automotive piezoresistive platforms.
- Strain Gauge:Metal foil or thin-film resistor networks on stainless steel substrates tolerate corrosive media exposure. Industrial process control applications in chemical plants specify strain gauge construction for compatibility with aggressive manifold environments.
MEMS leads on scale; capacitive commands premium positioning in radiation-hardened niches.
End User:
Application sector determines specification stringency, certification burden, and replacement cycle frequency.
- Automotive:Turbocharger penetration and cylinder deactivation strategies multiply sensor count per powertrain. EPA Tier 4 off-road rules are expanding MAP specification to construction and agricultural equipment beyond highway vehicles.
- Aerospace:DO-160G environmental qualification and TSO-C112 certification impose extended validation timelines. Auxiliary power unit and environmental control system applications drive demand for capacitive and piezoresistive variants with extended temperature ranges.
- Industrial Equipment:Hydraulics monitoring and pneumatic system control in manufacturing automation require pressure sensing with IP67 ingress protection. Food and beverage processing plants specify sanitary pressure transmitters with 3-A certification for clean-in-place compatibility.
- Consumer Electronics:Miniaturized barometric pressure sensing in smartphones and wearables leverages MEMS cost curves from automotive volume. Altitude measurement for fitness tracking and indoor navigation represents emerging demand outside traditional engine management.
Automotive leads on scale; industrial equipment shows steepest expansion trajectory as factory automation digitization accelerates.
Installation:
Mounting topology determines environmental exposure, service accessibility, and wiring harness routing.
- Onboard:Direct manifold port mounting exposes sensors to thermal cycling and vibration. Engine bay integration demands automotive-grade temperature compensation and EMI shielding for reliable boost pressure measurement.
- Offboard:Remote mounting with pressure tubing isolates electronics from extreme thermal transients. Heavy-duty diesel applications in mining equipment specify offboard installation to extend service life in high-soot environments.
- Inline:Flow-through housing design enables pressure tapping without dedicated manifold boss machining. Aftermarket retrofit applications favor inline mounting for compatibility with legacy engine architectures lacking OEM sensor provisions.
- Portable:Battery-powered handheld units with digital display serve diagnostic and calibration verification roles. Racing teams and engine builders utilize portable MAP sensors for dyno cell validation of volumetric efficiency maps.
Onboard leads on scale; offboard gains share fastest in severe-duty off-road equipment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized MEMS process engineers concentrate in German automotive clusters, Chinese semiconductor hubs, and U.S. Tier-1 supplier corridors, anchoring regional production capabilities.
United States
Detroit-based OEM procurement programs and EPA Tier 4 off-road rule implementation drive sensor specification for heavy-duty diesel platforms. NHTSA corporate average fuel economy mandates compel precision MAP integration across turbocharged gasoline fleets. Michigan's automotive corridor hosts captive semiconductor fabrication divisions serving integrated pressure module production.
Germany
Passenger vehicle electrification programs and turbocharger penetration multiply sensor deployment per hybrid powertrain. EU Green Deal embedded emissions targets force REACH-compliant material declarations into supplier RFQ requirements. Stuttgart and Munich clusters anchor piezoresistive MEMS design leadership for high-compression gasoline engine applications.
China
MIIT dual carbon implementation timelines accelerate cylinder deactivation strategy adoption in domestic gasoline powertrains. National carbon neutrality goals compress sensor real estate requirements in space-constrained engine bay packaging. Yangtze River Delta foundry concentration creates die supply leverage for integrated module suppliers serving hybrid programs.
Japan
METI industrial policy supports MEMS batch processing scale economies for automotive pressure sensing. Domestic OEM hybrid system integration demands precision boost control in dual-mode combustion-electric architectures. Nagoya and Tokyo corridors concentrate silicon-glass anodic bonding expertise for hermetic cavity sealing applications.
South Korea
Domestic automotive OEM turbocharger specification and export platform electrification expand MAP sensor procurement volumes. MFDS-aligned quality frameworks extend traceability documentation burdens for sensor suppliers targeting medical-adjacent industrial applications. Seoul Capital Area semiconductor packaging clusters enable wafer-level module assembly for regional powertrain programs.
Manifold Absolute Pressure Sensor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sensor value chain, creating a tiered supplier structure where captive foundry ownership determines supply security. The vendor base concentrates around integrated module specialists with in-house semiconductor fabrication and component suppliers dependent on external foundry allocation. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, pure-play sensor specialists with MEMS expertise, and semiconductor fabricators extending into pressure sensing modules. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure die supply and expand platform coverage.
Among diversified industrial conglomerates, Honeywell International Inc. and Robert Bosch GmbH exemplify the integrated archetype with captive fabrication capabilities, while Sensata Technologies occupies a position within the pure-play sensor specialist tier. These three anchors demonstrate how geographic origin and corporate structure map to competitive positioning across North American, German, and broader European supply corridors.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sensata Technologies |
| Robert Bosch GmbH |
| TE Connectivity |
| BorgWarner Inc. |
| DENSO Corporation |
| Infineon Technologies AG |
| Hitachi Automotive Systems, Ltd. |
| Continental AG |
| Others |
Supply & Pricing Matrix
EPA Tier 4 off-road emissions mandates and EU Green Deal procurement specifications are forcing sensor suppliers to absorb REACH-compliant material qualification costs while maintaining analog-digital hybrid product lines, compressing margin capture across integrated module producers and external foundry-dependent competitors alike.
Pricing Analysis
Bundled module-and-software calibration services command premium positioning against unbundled discrete sensor procurement. Three-tier pricing structure across premium SENT-protocol digital variants, standard analog Wheatstone bridge outputs, and economy-grade legacy replacements reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because Chinese domestic hybrid powertrain programs are consolidating procurement around integrated temperature-pressure dies. Aftermarket distributors exhibit highest price sensitivity due to wholesale channel disintermediation, while German OEMs demonstrate lowest sensitivity where wiring harness simplification justifies digital protocol premiums.
Supply Chain Analysis
China's MIIT domestic-content preferences and U.S. Buy American provisions for heavy-duty diesel platforms are reshaping sourcing patterns toward regional captive fabrication. Die supply concentrates in Taiwan, South Korea, and Germany where 200mm MEMS foundry capacity feeds automotive sensor demand. Silicon-on-insulator wafers, boron-doped silicon diaphragms, and halogen-free molding compounds constitute critical input dependencies. Single-source vulnerability runs through East Asian anodic bonding equipment suppliers. Distribution runs through direct Tier-1 OEM relationships anchoring North American aftermarket procurement outside traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value where European REACH compliance costs exceed U.S. material qualification burdens by a substantial margin, rewarding suppliers with dual-continent manufacturing footprints.
For Market Incumbents: To counter silicon wafer supply concentration in East Asian foundries, secure captive 200mm MEMS fabrication capacity or binding long-term die allocation agreements with Yangtze River Delta suppliers. Deepen backward integration into silicon-glass anodic bonding process engineering to reduce external talent dependency for hermetic cavity sealing operations. For New Entrants and Emerging Players: Begin with industrial process control applications beyond automotive, where wafer-level packaging thermal stability improvements enable pneumatic system monitoring in food and beverage automation. Target South Korean automotive OEM export platforms electrifying for European markets, leveraging Seoul Capital Area semiconductor packaging clusters for regional module assembly without German MEMS design leadership requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play sensor specialists possessing MEMS expertise but lacking captive foundry ownership, as tiered supplier consolidation favors integrated module producers with in-house semiconductor fabrication. Five-to-ten year viability hinges on SENT protocol standardization completion and hybrid powertrain sensor count multiplication. Watch EPA Tier 4 off-road implementation timelines as inflection indicator for heavy-duty diesel specification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Fabrication Acquisition | Secures die supply against East Asian foundry allocation cycles for integrated pressure module production. |
| SENT Protocol Certification Investment | Enables direct German OEM procurement for turbocharged gasoline platforms requiring simplified wiring harness design. |
| Wafer-Level Packaging Scale-Up | Opens industrial process control applications beyond automotive through thermal stability improvements. |
| REACH-Compliant Material Line Expansion | Qualifies halogen-free molding compound variants for EU Green Deal procurement specification compliance. |
| Direct Tier-1 OEM Relationship Development | Bypasses wholesale channel intermediaries to anchor North American aftermarket distribution outside traditional networks. |
Research Methodology
Bottom-up automotive end-use modeling reconciled against top-down MEMS fabrication capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and MEMS process engineering directors combined with secondary validation against EPA regulatory filings, NHTSA CAFE documentation, EU ETS vehicle emissions databases, and MIIT dual carbon policy releases. Trade data from semiconductor equipment customs records and IHS Markit vehicle production databases anchored supply-side triangulation.
Historical trendline analysis across piezoresistive MEMS cost curves, turbocharger penetration rates, and cylinder deactivation strategy adoption informed projection framework construction. Segmentation modeling spanned signal protocol, fabrication technology, end-user sector, and mounting topology dimensions. CAGRs derived from unit volume trajectories weighted by digital-analog product mix shifts and integrated module premium capture. Forecast inputs included hybrid powertrain electrification timelines and EPA Tier 4 off-road rule implementation scope.
Caveats apply where silicon wafer supply disruptions, REACH substance restriction expansions, or capacitive architecture substitution in aerospace radiation-hardened niches could materially shift the outlook. A small set of triggers—East Asian foundry capacity allocation decisions, German OEM digital mandate acceleration, and China MIIT dual carbon enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Digital Sensor Sleeves Market