
 Dissolved Gas Analyzer Market | 2026-2036
Dissolved Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolved Gas Analyzer Market Intelligence
EPA is decoupling dissolved gas analyzer procurement from traditional maintenance cycles by embedding emissions-linked transformer reliability into utility compliance frameworks. Qualitrol Company LLC leverages its North American installed base to sustain service revenue through predictive diagnostics platforms. Weidmann Electrical Technology AG anchors its European position with specialized dissolved gas analysis kits for high-voltage transformer fleets. Siemens Energy competes through integrated digital solutions that bridge dissolved gas data with asset management software.
Dissolved gas analyzers detect and quantify fault gases dissolved in transformer insulating oil, typically measuring hydrogen, methane, ethane, ethylene, and acetylene concentrations in parts per million to diagnose thermal and electrical faults before catastrophic failure. Online analyzers represent the fastest-growing product configuration as utilities shift from periodic laboratory sampling to real-time dissolved gas monitoring for critical transformers. Gas chromatography technology dominates laboratory-grade precision requirements while electrochemical sensors capture share in cost-sensitive portable deployments across manufacturing end users.
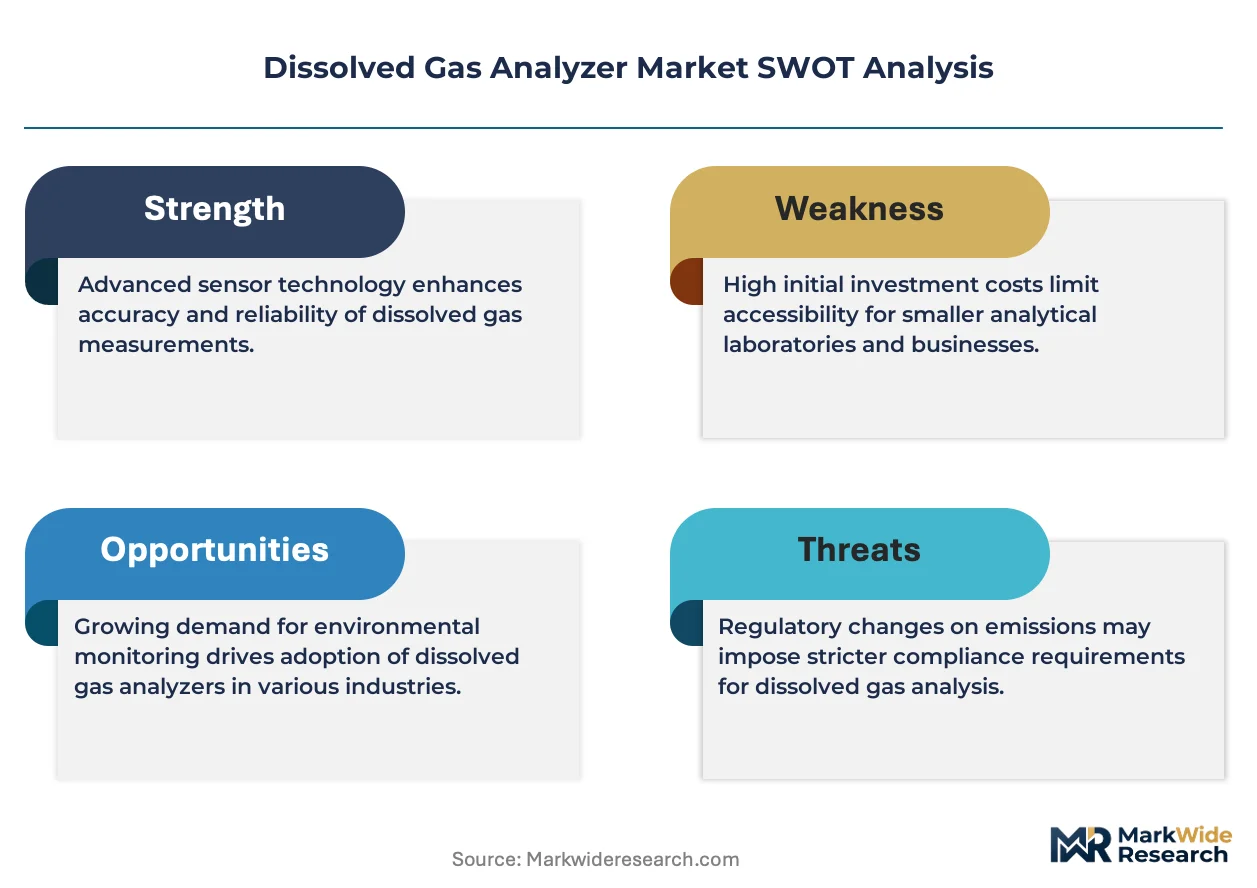
FERC reliability standards and IEEE C57.104 guidelines shape utility procurement specifications for dissolved gas monitoring equipment in the United States, while IEC 60599 governs dissolved gas ratio interpretation methodologies across European power grids. China's GB standards and dual carbon goals are accelerating domestic dissolved gas analyzer adoption for grid infrastructure efficiency improvements. Stakeholders must monitor evolving dissolved gas threshold interpretations across regulatory jurisdictions to align product roadmaps with shifting compliance baselines.
Market Dynamics
The transition from periodic laboratory sampling to continuous online monitoring is restructuring utility procurement patterns for transformer asset management. IEC 60599 threshold tightening and IEEE C57.104 guideline updates are compressing replacement cycles while elevating predictive maintenance budgets.
Growth Catalysts
- Regulatory threshold compression:FERC reliability standards and IEEE C57.104 guideline revisions in the United States are mandating tighter dissolved gas-in-oil interpretation limits. Asset owners must upgrade monitoring infrastructure to maintain compliance.
- Grid modernization capital flows:Power generation utilities in China, Germany, and the United States are expanding dissolved gas analyzer deployment across transformer fleets. State Grid Corporation of China and German transmission system operators are prioritizing real-time fault detection.
- Electrochemical sensor maturation:Portable dissolved gas analyzer configurations are penetrating manufacturing end-use segments previously excluded by gas chromatography cost barriers. Food processing and chemical plants are adopting simplified hydrogen detection for smaller transformer assets.
Market Restraints
- Helium supply volatility:Gas chromatography-based laboratory analyzers depend on helium carrier gas, with price instability concentrated in United States and Qatar supply corridors. Alternative carrier gas transitions require hardware retrofit investments.
- Specialized sensor supplier concentration:Electrochemical hydrogen sensors for dissolved gas detection source predominantly from Japanese and South Korean component manufacturers. Geographic concentration creates lead time vulnerability for analyzer assemblers.
- Calibration standard fragmentation:IEC 60599 and IEEE C57.104 employ divergent ratio interpretation methodologies, forcing manufacturers to maintain dual algorithm firmware. Regulatory friction elevates development overhead without technical differentiation.
Strategic Opportunities
- India grid infrastructure buildout:Central Electricity Authority mandates and state-level discom modernization programs are creating first-mover positioning for dissolved gas analyzer suppliers. The country's transmission expansion targets underserved monitoring penetration.
- Digital twin convergence:Dissolved gas data streams are integrating with transformer thermal modeling and load forecasting algorithms. Siemens Energy and ABB are bridging analyzer outputs with asset management platforms.
- Aftermarket service unbundling:Predictive diagnostics platforms are separating hardware sales from subscription-based interpretation services. Qualitrol Company LLC leverages its North American installed base for recurring revenue capture.
Industry Challenges
- Multi-standard firmware complexity:Analyzer manufacturers must support simultaneous IEC 60599, IEEE C57.104, and GB standard interpretations for global utility tenders. Software validation cycles extend product launch timelines.
- Field calibration skill scarcity:Electrochemical sensor drift correction and gas chromatography column maintenance require specialized technicians. Utility maintenance departments face recruitment gaps for dissolved gas analyzer servicing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolved Gas Analyzer Market |
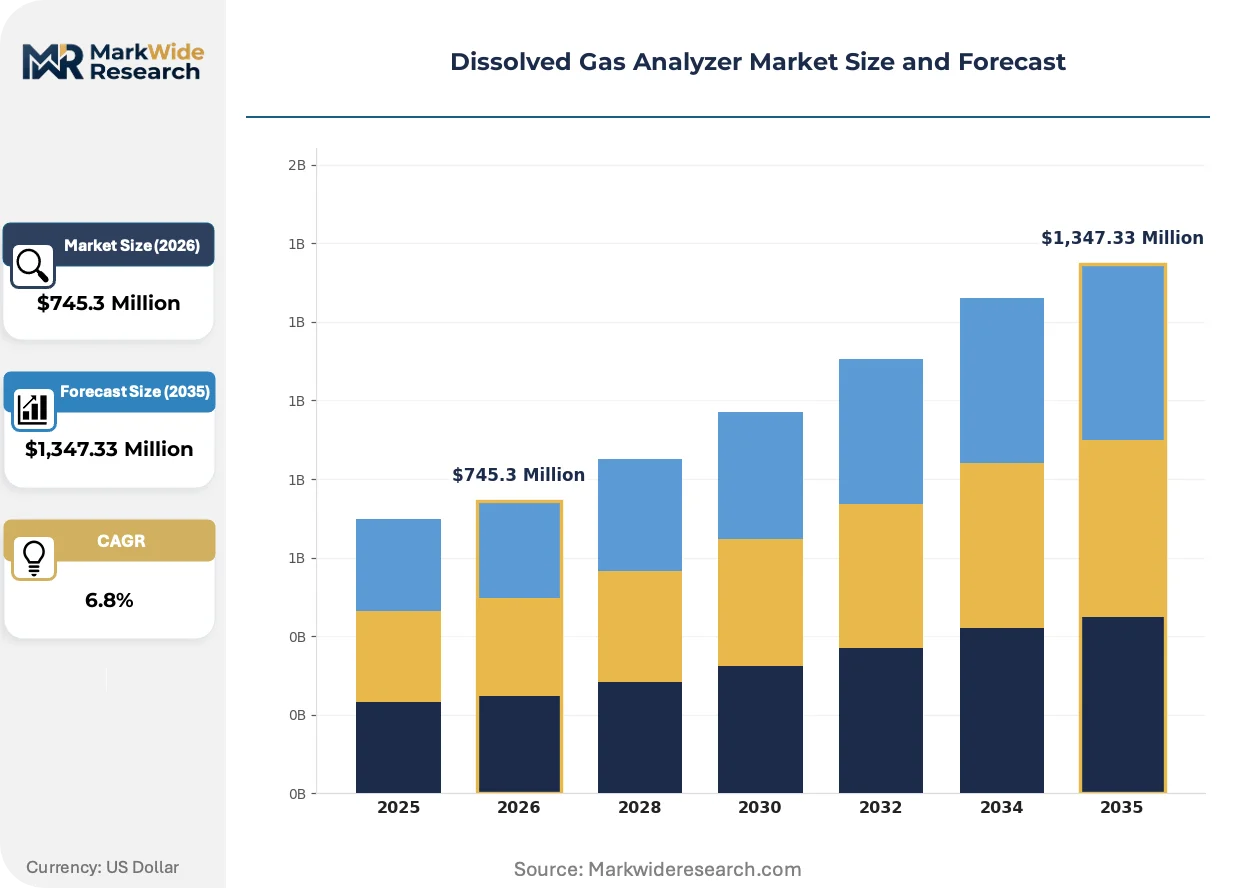
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,347.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Online Analyzers, Laboratory Analyzers, Multi-Gas Analyzers End User: Utilities, Oil & Gas Industry, Power Generation, Manufacturing Deployment: On-Premise, Cloud, Hybrid, Remote Monitoring Technology: Infrared Spectroscopy, Gas Chromatography, Mass Spectrometry, Electrochemical Sensors |
| Companies Covered | Qualitrol Company LLC, Weidmann Electrical Technology AG, Siemens Energy, Vaisala Oyj, LumaSense Technologies, Inc., ABB Ltd., Doble Engineering Company, Hitachi Energy Ltd., General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolved Gas Analyzer Market Strategic Shifts & Innovations
Sensor miniaturization and edge computing integration are dissolving the boundary between laboratory-grade precision and field-deployable dissolved gas monitoring. Real-time data transmission is compressing fault detection intervals from quarterly sampling to continuous surveillance.
Multi-gas electrochemical sensor arrays are modularizing dissolved gas analyzer architecture, enabling utilities to configure hydrogen-only monitoring for distribution transformers or full five-gas suites for critical transmission assets. Mid-sized utilities in Germany and the United States are adopting scalable sensor platforms to match monitoring intensity with asset criticality. This modularization is fragmenting the traditional dichotomy between portable spot-checkers and fixed online installations.
EPA emissions-linked transformer reliability frameworks are embedding dissolved gas monitoring into utility compliance infrastructure. The agency's evolving stance ties transformer failure prevention to methane and SF6 emission reduction accounting. United States power generators are responding by accelerating continuous monitoring deployment across medium-voltage fleets previously managed through periodic sampling.
Utility procurement departments are consolidating dissolved gas analyzer purchasing with broader transformer service contracts, unbundling hardware from diagnostic interpretation. European transmission system operators now specify data platform compatibility ahead of standalone analyzer specifications. This bundling is most visible in Germany, where TenneT and 50Hertz integrate dissolved gas feeds directly into enterprise asset management systems.
Dissolved Gas Analyzer Market Segmentation
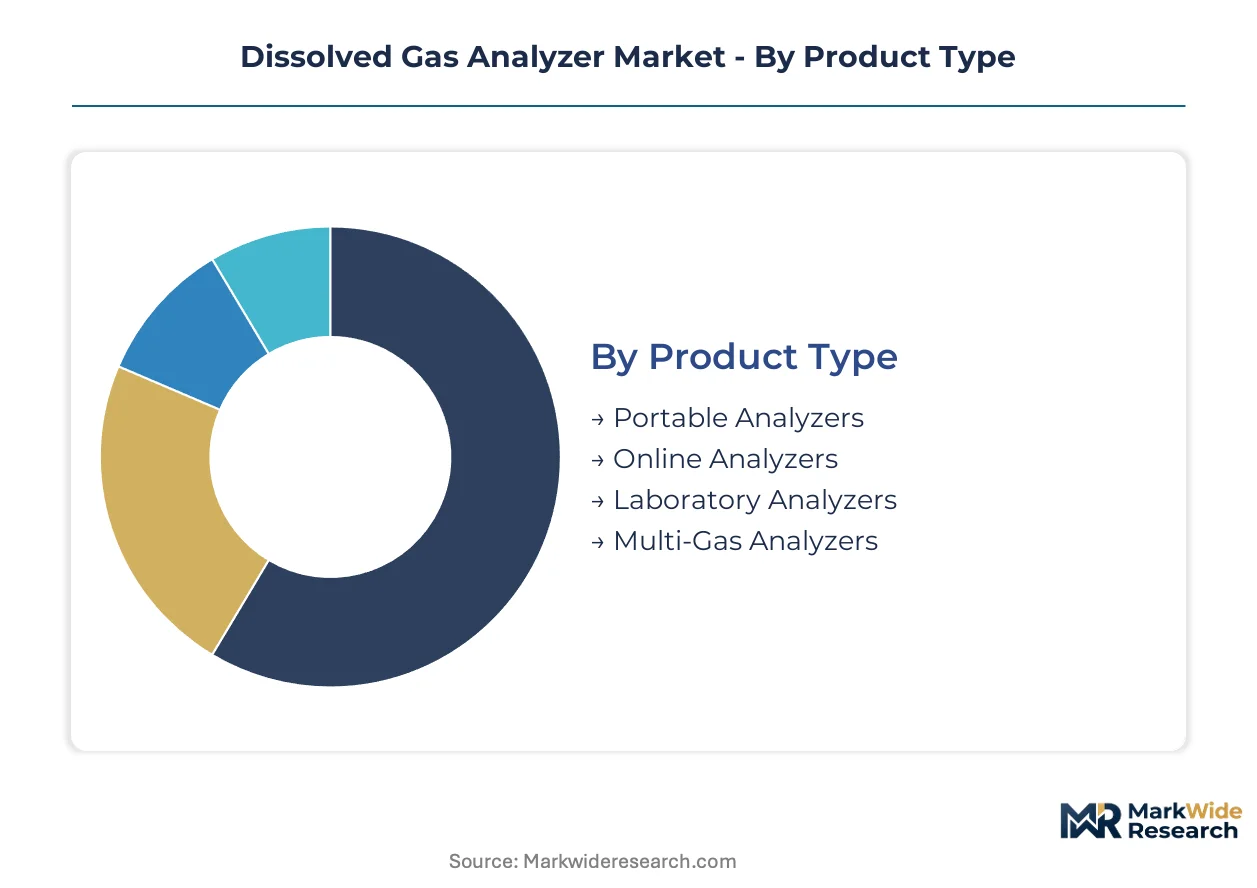
Dissolved gas analyzer procurement splits across four intersecting dimensions that determine price points, service intensity, and replacement cadence. Each segmentation layer reveals distinct upgrade pressures from regulatory threshold tightening and sensor technology maturation.
Product Type:
Replacement cycles vary dramatically by product configuration, with laboratory-grade systems facing the longest intervals and portable units experiencing accelerated refresh rates from electrochemical sensor improvements.
- Online Analyzers:Fixed installations provide continuous dissolved gas monitoring through direct transformer integration, sampling oil automatically at programmable intervals. United States utilities under FERC reliability mandates are prioritizing these systems for critical transmission assets exceeding 100 MVA capacity.
- Portable Analyzers:Handheld or cart-mounted units enable spot-checking across distributed transformer fleets without permanent installation. Manufacturing end users in Germany favor these for smaller substations where full online monitoring cannot be justified economically.
- Laboratory Analyzers:Bench-top gas chromatography systems deliver highest precision for forensic fault analysis and calibration verification.
- Multi-Gas Analyzers:Modular platforms allow field-configurable detection from single hydrogen to full five-gas suites.
Volume placements concentrate in Online Analyzers; the faster expansion belongs to Portable Analyzers.
End User:
Customer type determines procurement sophistication, with regulated utilities demanding predictive diagnostics integration while industrial users prioritize capital efficiency.
- Utilities:Transmission and distribution operators manage the largest transformer fleets and face strictest dissolved gas monitoring mandates. State Grid Corporation of China and German transmission system operators specify real-time data feeds into enterprise asset management platforms.
- Power Generation:Generator step-up transformers at thermal, nuclear, and renewable facilities require specialized monitoring given their direct revenue linkage. Independent power producers in the United States are deploying hybrid cloud configurations to centralize fleet visibility.
- Oil & Gas Industry:Refinery and pipeline substations operate in hazardous environments demanding explosion-proof analyzer housings.
- Manufacturing:Chemical plants, food processors, and heavy industry maintain smaller transformer populations with simpler monitoring needs.
Revenue concentration sits with Utilities; Manufacturing demonstrates the steepest expansion trajectory as electrochemical cost barriers fall.
Deployment:
Infrastructure architecture choices reflect cybersecurity posture, legacy system integration, and real-time responsiveness requirements.
- On-Premise:Data remains within utility control centers, satisfying critical infrastructure protection standards. European transmission operators under GDPR and NIS2 directives favor this model for transmission-level assets.
- Cloud:Centralized data lakes enable cross-fleet pattern recognition and vendor-managed algorithm updates. Chinese utilities leverage domestic cloud providers to meet data sovereignty requirements under GB standards.
- Hybrid:Edge processing with cloud archival balances latency and scalability, gaining traction among mid-sized United States cooperatives.
- Remote Monitoring:Third-party diagnostic services assume continuous surveillance responsibility, unbundling hardware from interpretation.
Current installations favor On-Premise; Hybrid configurations are climbing the fastest as utilities modernize without full cloud migration.
Technology:
Detection methodology trade-offs between precision, cost, and field ruggedness drive technology selection across use cases.
- Gas Chromatography:Separates dissolved gases through packed columns with flame ionization or thermal conductivity detection, achieving sub-ppm precision. Laboratory and reference-grade online systems in Germany and the United States depend on this gold-standard approach despite helium carrier gas supply vulnerabilities.
- Electrochemical Sensors:Solid-state or liquid electrolyte cells detect hydrogen and specific hydrocarbons through redox reactions. Japanese and South Korean component suppliers dominate sensor manufacturing, enabling cost breakthroughs for portable and single-gas applications.
- Infrared Spectroscopy:Non-dispersive or photoacoustic methods measure gas-specific absorption bands without consumable carrier gases.
- Mass Spectrometry:Ionization and mass-to-charge ratio detection provides universal gas identification with highest sensitivity.
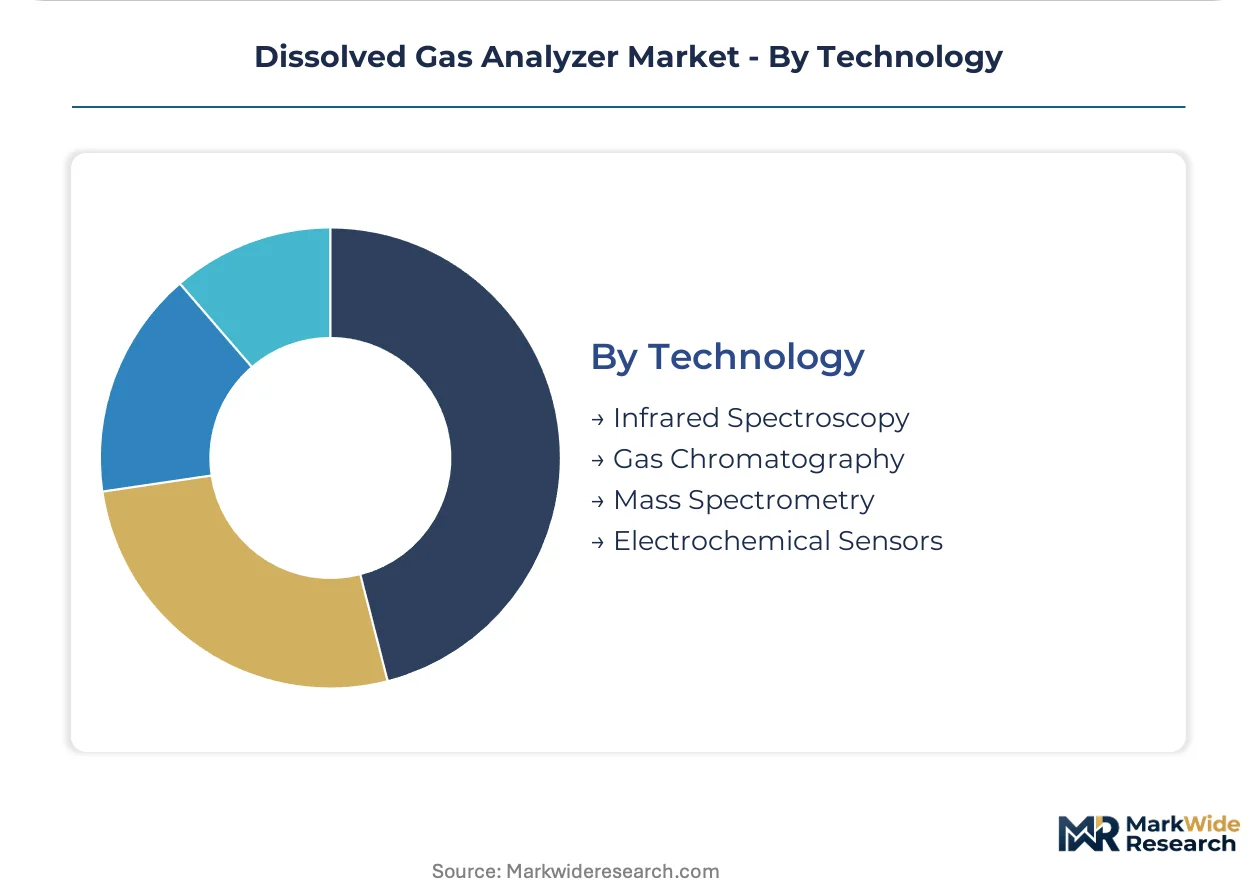
Installed base dominance rests with Gas Chromatography; Electrochemical Sensors are gaining share fastest through manufacturing segment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in coastal China and Germany's industrial heartland concentrate dissolved gas analyzer demand through grid modernization clusters. State-backed infrastructure funds and utility privatization programs reshape procurement patterns across key markets.
United States
FERC reliability standards and EPA emissions-linked transformer frameworks drive continuous monitoring mandates. IEEE C57.104 guideline revisions compress dissolved gas threshold interpretations. Texas and California transmission operators deploy online analyzers across critical transformer fleets exceeding 100 MVA capacity.
China
State Grid Corporation of China prioritizes real-time fault detection for transmission expansion targets. GB standards and dual carbon goals accelerate domestic analyzer adoption for grid efficiency improvements. Yangtze River Delta utilities integrate dissolved gas data with enterprise asset management platforms.
Germany
TenneT and 50Hertz transmission system operators mandate dissolved gas feed integration into enterprise systems. IEC 60599 governs ratio interpretation methodologies across European power grids. North Rhine-Westphalia and Bavaria host specialized dissolved gas analysis kit deployment for high-voltage transformer fleets.
India
Central Electricity Authority mandates and state-level discom modernization programs create first-mover positioning for suppliers. The country's transmission expansion targets underserved monitoring penetration. Maharashtra and Gujarat utilities adopt portable analyzers for distribution transformer spot-checking.
Japan
Electrochemical hydrogen sensor manufacturing concentrates among Japanese component suppliers serving portable analyzer assemblers. METI industrial efficiency programs support predictive maintenance technology adoption. Kanto and Kansai industrial corridors maintain specialized calibration and servicing capabilities.
Dissolved Gas Analyzer Market Key Industry Players
North American producers anchor one tier; European specialists hold precision-grade positioning. The vendor base separates into three distinct tiers: integrated energy technology conglomerates, dedicated electrical diagnostic specialists, and component-focused sensor manufacturers. Two dominant competitive moves reshape positioning: predictive diagnostics platform unbundling separates hardware from subscription services, and digital twin convergence integrates analyzer outputs with asset management software.
Within the integrated technology tier, Siemens Energy and ABB Ltd. occupy positions bridging analyzer hardware with enterprise software ecosystems. Qualitrol Company LLC exemplifies the dedicated diagnostic specialist archetype, leveraging installed base relationships for recurring service revenue. Weidmann Electrical Technology AG anchors European market presence through specialized kit configurations for high-voltage applications.
| Leading Market Players |
|---|
| Qualitrol Company LLC |
| Weidmann Electrical Technology AG |
| Siemens Energy |
| Vaisala Oyj |
| LumaSense Technologies, Inc. |
| ABB Ltd. |
| Doble Engineering Company |
| Hitachi Energy Ltd. |
| General Electric |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IEC 60599-compliant laboratory systems and portable electrochemical units manifests in both pricing premiums and supply chain sourcing strategies. Gas chromatography platforms command substantial markups tied to helium carrier gas logistics and precision component sourcing, while electrochemical assemblies leverage Japanese and South Korean sensor supply corridors for cost compression.
Pricing Analysis
Short lead-time premiums for electrochemical hydrogen sensors from Japanese suppliers compress margins for portable analyzer assemblers facing spot inventory discounts from South Korean alternatives. Pricing stratifies across premium laboratory-grade, standard online monitoring, and economy portable tiers, with differentiation driven by IEC 60599 calibration certification and geographic delivery cost from component hubs. Pricing pressure stems from helium supply volatility forcing gas chromatography hardware retrofits. Manufacturing end users exhibit highest price sensitivity; transmission utilities under FERC mandates show least.
Supply Chain Analysis
Refurbishment flows for gas chromatography columns and electrochemical sensor recalibration create reverse-logistics revenue streams for Qualitrol and Weidmann service networks. Component manufacturing concentrates in Japan, South Korea, and Germany, with raw material dependencies spanning palladium catalysts, solid-state electrolytes, and precision optical detectors. Single-source vulnerability sits with Japanese hydrogen sensor suppliers. Distribution runs through authorized electrical diagnostic distributors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium supply constraints on gas chromatography systems prop pricing power for electrochemical alternatives, creating a supply-constrained growth window for sensor-dependent portable configurations.
For Market Incumbents: Lock in long-term helium supply contracts or accelerate carrier gas transition R&D before Qatari export volatility spreads. Qualitrol's installed base service revenue model offers a defensive template; replicate predictive diagnostics platform unbundling to capture recurring income against emerging electrochemical entrants. Certification investment in dual-standard firmware (IEC 60599 and IEEE C57.104) maintains tender eligibility across regulatory jurisdictions. For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypass entrenched distributor relationships that favor Siemens Energy and ABB. Target India's state-level discom modernization programs where monitoring penetration remains underserved and procurement specifications favor cost-efficient electrochemical platforms over laboratory-grade systems. White-space opportunity sits with hydrogen-only modular configurations for distribution transformer fleets. For Investors and Strategic Acquirers: Re-rating potential sits with electrochemical sensor specialists given FERC reliability standard tightening and IEEE C57.104 threshold compression accelerating replacement demand. Five-to-ten-year viability favors component suppliers with backward integration into solid-state electrolyte production. Monitor helium price futures and Japanese export license policies for inflection signals on gas chromatography incumbent valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Platform Launch | Separates hardware sales from subscription interpretation services, following Qualitrol's recurring revenue model. |
| Electrochemical Sensor Backward Integration | Captive supply of solid-state hydrogen detectors reduces lead time vulnerability to Japanese component concentration. |
| Dual-Standard Firmware Certification | Simultaneous IEC 60599 and IEEE C57.104 compliance maintains global utility tender eligibility without algorithm fragmentation. |
| India Distribution Partnership | State Grid Corporation of China and German TSO procurement templates create referenceability for Central Electricity Authority mandates. |
| Helium Carrier Gas Transition R&D | Alternative carrier development mitigates Qatar supply corridor price volatility for laboratory-grade gas chromatography systems. |
Research Approach
Independent corroboration across dissolved gas analyzer procurement officers at State Grid Corporation of China, TenneT transmission planners, and predictive maintenance directors at U.S. independent power producers underwrites the qualitative findings. Secondary validation drew from FERC reliability filings, IEC 60599 technical committee documentation, and Japanese METI industrial efficiency program disclosures. Bottom-up segment sizing triangulated against top-down grid modernization capital flow estimates from national transmission expansion targets.
Comparable-period anchoring to historical transformer failure incident databases and dissolved gas monitoring adoption curves shaped the projection horizon. The analytical framework modeled product type, end user, deployment architecture, and detection technology segments across the analysis window. CAGRs derived from utility capital expenditure trajectories and electrochemical sensor cost learning curves. Forecast inputs included FERC mandate implementation timelines and Chinese dual carbon goal infrastructure commitments.
The model holds under stable helium supply conditions and continued IEC 60599 threshold tightening; deviation in Japanese sensor export restrictions or IEEE C57.104 guideline delays would shift replacement cycle assumptions. Forecasts reflect documented regulatory trajectories and technology maturation curves. Practitioners should monitor Qatari helium production quotas and South Korean electrochemical patent filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market