
 Laser Diffraction Analyzer Market | 2026-2036
Laser Diffraction Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Diffraction Analyzer Market Insights
German precision optics manufacturers is rebalancing laser diffraction production capacity toward pharmaceutical-grade systems. Malvern Panalytical leverages its long-standing dominance in particle characterization to sustain R&D intensity across European calibration labs. HORIBA anchors its position through backward integration into optical component supply, while Beckman Coulter competes on service density in North American life science accounts.
A laser diffraction analyzer measures particle size distribution by detecting angular scattering patterns from a coherent laser beam, typically spanning detection limits from nanometers to several millimeters through multi-element photodetector arrays. The instrument serves primary industrial purpose in quality control and formulation validation where particle geometry determines product performance. Laboratory instruments command the deepest margin pools due to recurring consumables and validation protocols, while industrial analyzers extend fastest across food processing lines where inline particle monitoring replaces offline sampling. Research equipment occupies a concentrated niche dominated by national laboratory procurement cycles in materials science.
FDA guidance on pharmaceutical particle characterization and EMA standards for inhalation product testing shape instrument specifications and validation requirements across regulated manufacturing environments. ISO 13320 laser diffraction methodology governs inter-laboratory comparability, while REACH compliance in Europe restricts certain optical coating chemistries used in detector assemblies. Stakeholders must monitor evolving pharmacopeial standards for biologics and complex generics where sub-micron aggregate detection demands next-generation optical architectures.
Market Dynamics
Digital signal processing architectures and multi-laser array configurations are displacing single-source legacy designs across pharmaceutical quality control laboratories, compressing validation timelines while tightening detection thresholds for sub-micron particle aggregates.
Growth Catalysts
- FDA Inhalation Product Guidance:Updated particle characterization mandates for orally inhaled and nasal drug products are forcing pharmaceutical manufacturers to upgrade analytical infrastructure with validated laser diffraction systems.
- Food Processing Automation:Inline particle monitoring systems are replacing offline sampling protocols across dairy, beverage, and ingredient manufacturing lines where real-time quality assurance reduces batch rejection rates.
- Advanced Materials Clusters:Precision manufacturing hubs in Germany, the United States, and Japan are anchoring procurement of research-grade instruments for nanomaterial and battery electrode development programs.
Market Restraints
- Optical Component Supply Concentration:High-precision photodetector arrays and specialized laser sources depend on a limited supplier base concentrated in German and Japanese optics manufacturing corridors.
- REACH Compliance Costs:European restrictions on certain optical coating chemistries used in detector assemblies are forcing reformulation of legacy component specifications and extending qualification timelines.
- Capital Equipment Intensity:Laboratory-grade systems require substantial upfront investment in climate-controlled installation environments and certified reference materials for validation protocols.
Strategic Opportunities
- Biologics Aggregate Detection:Next-generation optical architectures capable of sub-200 nanometer resolution are opening specification gaps in therapeutic protein and vaccine formulation validation workflows.
- Service Unbundling Models:Independent validation and calibration service providers are capturing recurring revenue streams from installed base maintenance, displacing captive manufacturer service organizations.
- ISO 13320 Harmonization:Expanding adoption of standardized laser diffraction methodology across emerging pharmaceutical manufacturing regions is reducing inter-laboratory comparability barriers and accelerating instrument procurement cycles.
Industry Challenges
- Specialized Optics Talent Scarcity:Design and calibration of multi-element photodetector arrays requires expertise in Fourier optics and Mie scattering theory that concentrates in legacy academic and national laboratory programs.
- Legacy System Integration Complexity:Pharmaceutical manufacturers with extensive installed bases of single-laser instruments face data continuity and method transfer validation burdens when migrating to multi-source architectures.
- Extended Pharmacopeial Certification Timelines:New instrument platforms require 18-24 month validation cycles against evolving USP and EP monographs for particle size distribution methodology.
Report Scope
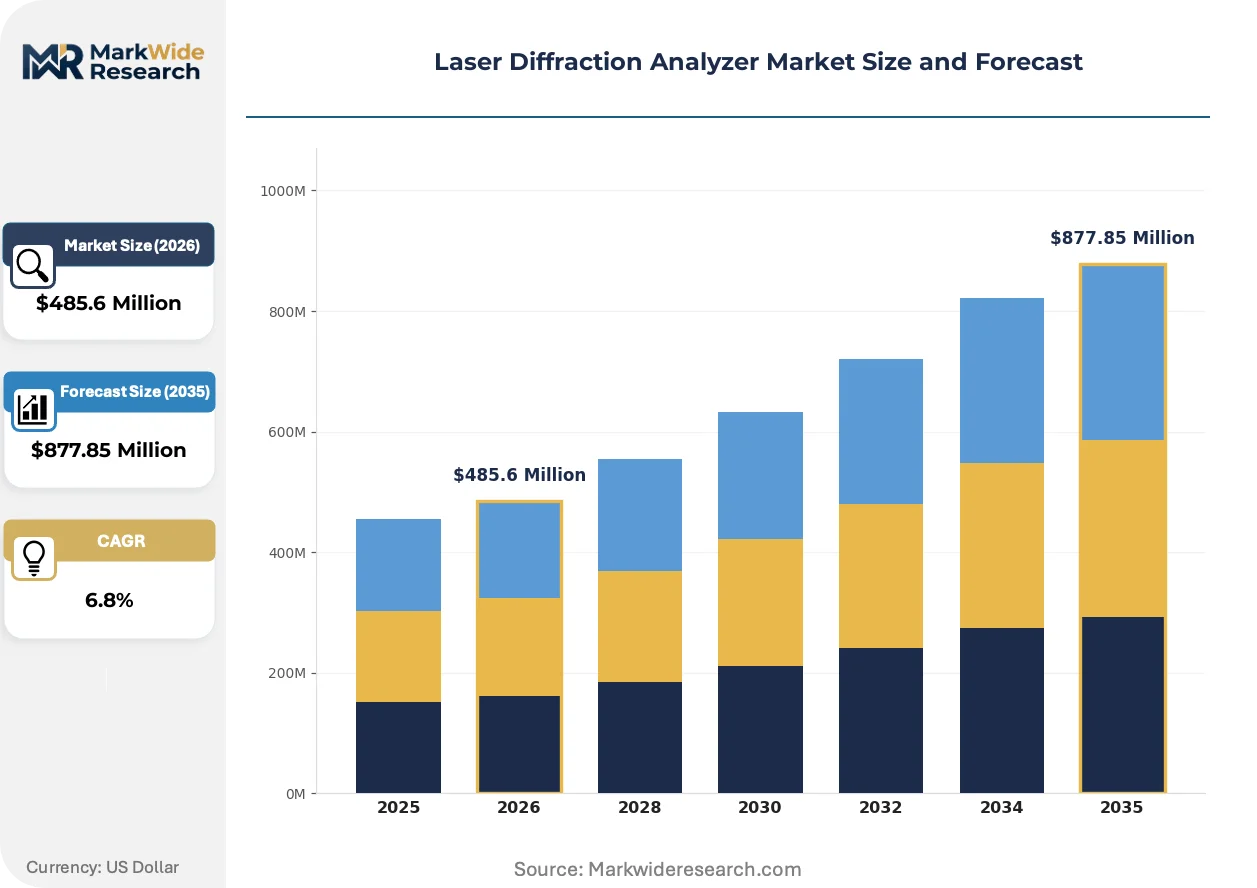
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Diffraction Analyzer Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Devices, Laboratory Instruments, Research Equipment, Industrial Analyzers Application: Particle Size Analysis, Material Characterization, Quality Control, Research & Development End User: Pharmaceuticals, Biotechnology, Food & Beverage, Materials Science Technology: Laser Scattering, Image Analysis, Optical Measurement, Digital Signal Processing |
| Companies Covered | Malvern Panalytical, HORIBA, Beckman Coulter, Anton Paar, Micromeritics Instrument Corporation, Shimadzu Corporation, Spectris, Sympatec, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Diffraction Analyzer Market Trends and Innovations
Multi-laser array architectures and embedded machine learning inference engines are compressing measurement cycle times while expanding dynamic range capabilities, fundamentally altering competitive positioning among instrument manufacturers.
Multi-angle laser scattering combined with polarization-differential detection is expanding into pharmaceutical bioprocessing applications where real-time aggregate monitoring replaces at-line analytical testing. Contract development and manufacturing organizations are adopting these systems at accelerated procurement cycles to support complex generic and biosimilar development programs. The technology is expanding into quality-by-design frameworks that integrate particle characterization data directly into process analytical technology control loops.
EMA standards for inhalation product testing and FDA guidance on nasal spray bioequivalence are mandating specific laser diffraction measurement ranges and data reporting formats that lock in instrument specifications for regulatory submissions. Pharmaceutical manufacturers must demonstrate method equivalence across development and commercial manufacturing sites, creating specification stickiness for validated platform technologies. European manufacturers are responding with enhanced software audit trails and electronic signature capabilities that anticipate MDR traceability requirements.
Equipment procurement committees are consolidating vendor relationships around single-source service agreements that bundle instrument validation, consumables supply, and regulatory documentation support. Large pharmaceutical accounts are displacing fragmented multi-vendor installations with standardized platform deployments that reduce training overhead and method transfer complexity. This concentration pattern is most visible in North American and European life science accounts where procurement functions report through centralized capital equipment governance structures.
Laser Diffraction Analyzer Market Segmentation
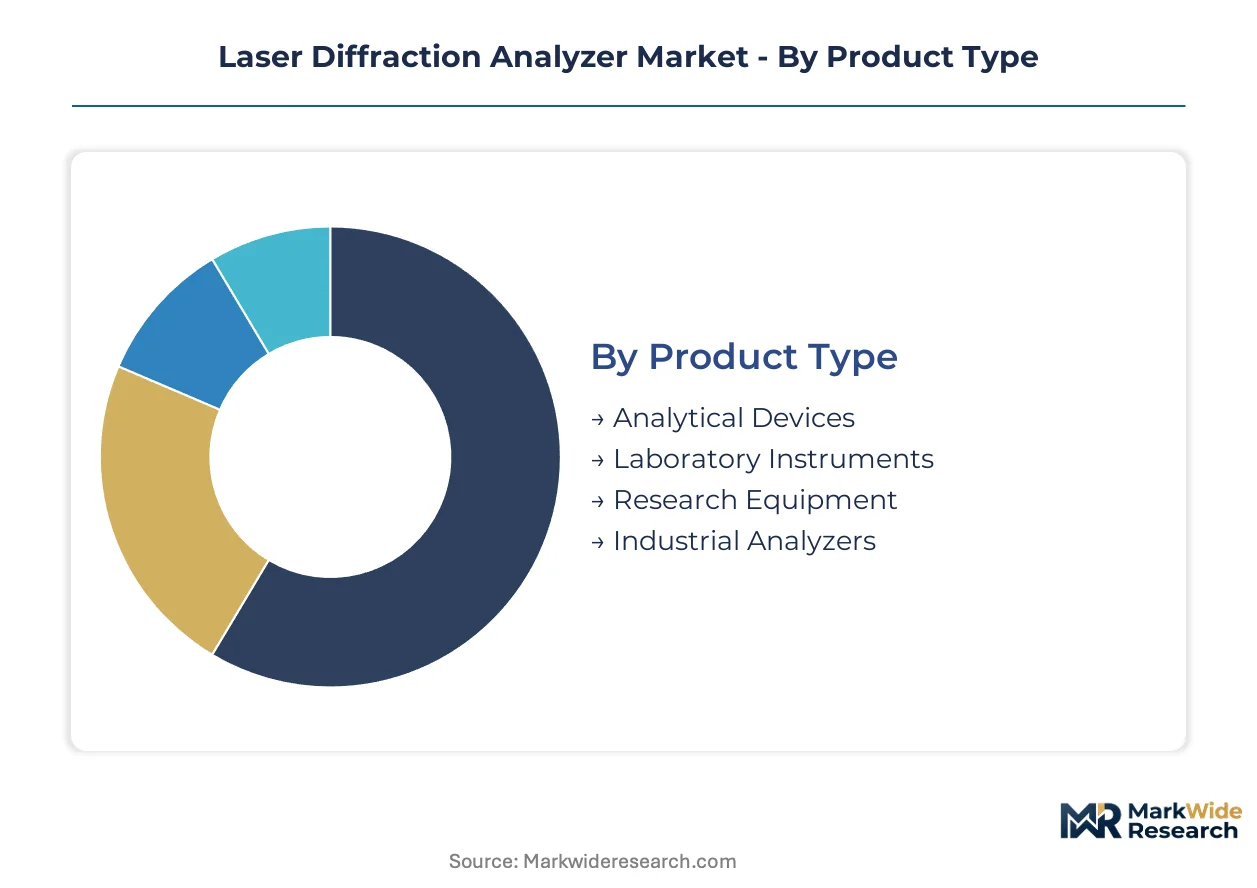
Laser diffraction analyzer procurement patterns diverge sharply across deployment contexts, with laboratory validation requirements driving premium configurations while inline industrial systems prioritize throughput economics. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume expansion occurs.
Product Type:
Purchasing priorities in this category split between facilities requiring pharmacopeial-grade validation documentation versus those optimizing for continuous process monitoring.
- Laboratory Instruments:These systems integrate multi-laser arrays and climate-controlled sample handling modules designed for FDA and EMA compliance workflows. Demand concentrates in German and United States pharmaceutical quality control laboratories where 21 CFR Part 11 electronic records mandates govern software specifications.
- Industrial Analyzers:Engineered for inline deployment across food processing and cement manufacturing lines, these units sacrifice detection range for environmental robustness and automated cleaning cycles. Japanese precision manufacturing clusters anchor procurement for battery electrode slurry monitoring applications.
- Analytical Devices:Portable or benchtop configurations serving routine quality assurance with simplified method libraries and reduced validation overhead.
- Research Equipment:Customizable architectures with extended dynamic range for nanomaterial and advanced ceramics development programs at national laboratories.
Laboratory instruments lead volumes today; industrial analyzers are gaining share fastest.
Application:
Functional requirements here map directly to regulatory exposure levels, with validated methodologies commanding price premiums over exploratory analytical workflows.
- Quality Control:Mandated particle size distribution verification for batch release decisions in pharmaceutical manufacturing, requiring full IQ/OQ/PQ documentation packages and audit trail capabilities. German and United States contract manufacturing organizations drive replacement cycles as EMA inhalation product standards tighten.
- Research & Development:Method development and formulation screening applications where flexibility outweighs validation rigor, prevalent in materials science institutes and biotech startup clusters.
- Particle Size Analysis:Core measurement function across all deployment contexts, differentiated by sample dispersion methodology and detection limit specifications.
- Material Characterization:Extended applications incorporating particle shape and surface area correlation for additive manufacturing feedstock qualification.
Quality control commands the deepest margins; research and development shows the steepest expansion trajectory among emerging biotech accounts.
End User:
Customer archetypes in this segmentation reflect fundamentally different procurement authority structures and total cost of ownership calculations.
- Pharmaceuticals:Multinational manufacturers with centralized capital equipment governance and captive validation teams demanding single-source service agreements. North American and European accounts displace fragmented vendor relationships for platform standardization.
- Biotechnology:Contract development organizations with accelerated procurement cycles and emphasis on method transferability between development and commercial manufacturing sites.
- Food & Beverage:Dairy and ingredient processors adopting inline monitoring to reduce batch rejection rates, with procurement decisions decentralized to plant engineering functions.
- Materials Science:National laboratory and university research programs with extended procurement timelines tied to grant funding cycles.
Pharmaceuticals anchor revenue concentration today; biotechnology is expanding most quickly as biosimilar development programs multiply.
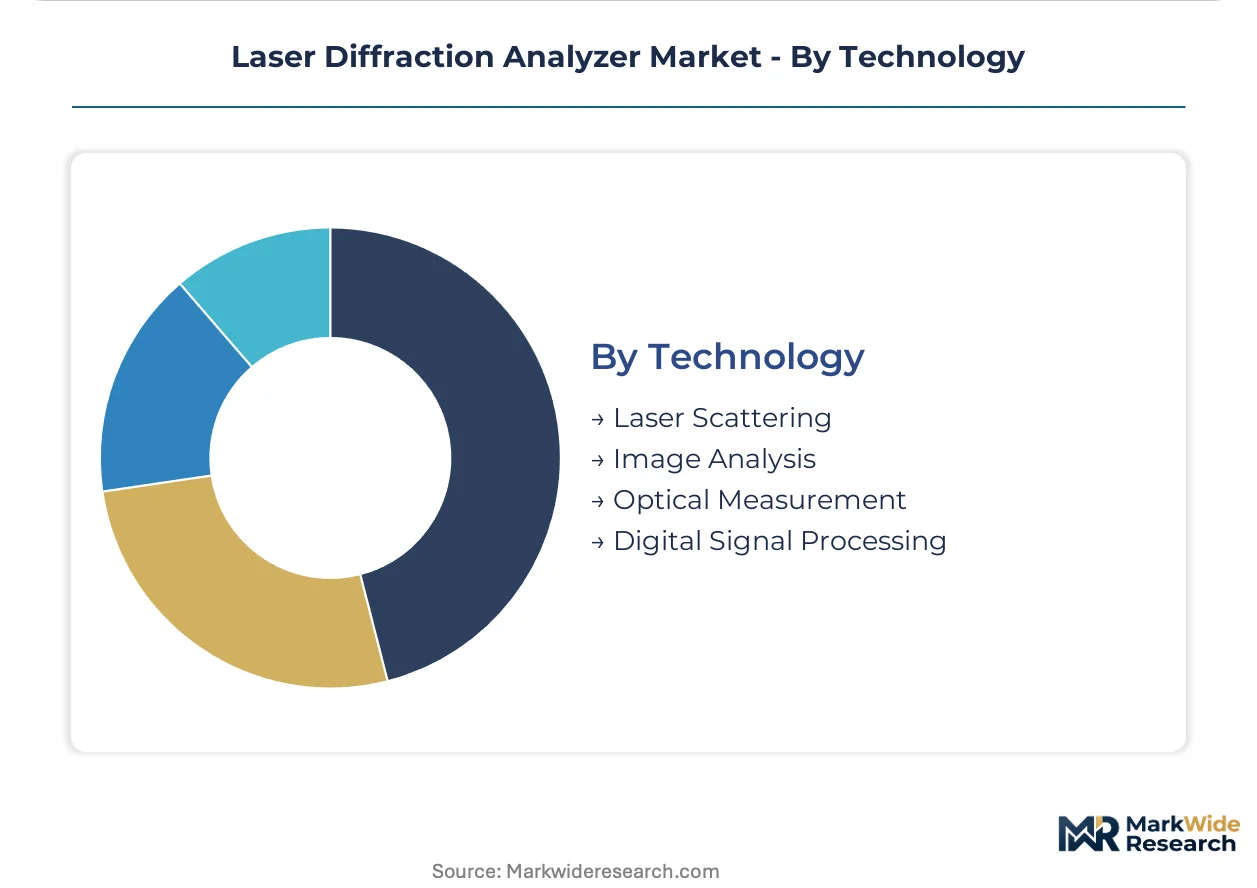
Technology:
Technology selection in this category determines detection limits, measurement cycle times, and compatibility with evolving pharmacopeial methodologies.
- Laser Scattering:Foundational Mie and Fraunhofer diffraction principles implemented through multi-element photodetector arrays, with German optics manufacturers supplying precision components for pharmaceutical-grade systems.
- Digital Signal Processing:Embedded inference engines compressing measurement cycles and enabling real-time aggregate detection in bioprocessing applications, displacing legacy single-source architectures.
- Image Analysis:Complementary particle shape characterization integrated with diffraction data for non-spherical particle populations.
- Optical Measurement:Conventional photon correlation and polarization-differential techniques serving specialized nanomaterial applications.
Laser scattering dominates installed base today; digital signal processing is climbing the fastest as multi-laser architectures displace legacy designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting laser diffraction analyzer procurement toward jurisdictions with streamlined validation protocols, even as EMA and FDA standards tighten method specifications for pharmaceutical-grade systems.
United States
FDA inhalation product guidance and 21 CFR Part 11 mandates drive quality control laboratory expansion across New Jersey and Massachusetts pharmaceutical corridors. The agency's particle characterization requirements for nasal spray bioequivalence lock in multi-laser array specifications for regulatory submissions. Greater Boston contract manufacturing organizations anchor accelerated replacement cycles as method transfer validation burdens intensify.
Germany
EMA standards for inhalation product testing and REACH compliance obligations shape instrument specifications across Baden-Württemberg precision optics clusters. The country's national pharmaceutical regulator enforces ISO 13320 methodology harmonization that reduces inter-laboratory comparability barriers. Bavarian calibration laboratories sustain R&D intensity through backward integration into optical component supply chains.
Japan
METI industrial policy and PMDA pharmaceutical manufacturing standards concentrate demand in Kanto and Kansai precision manufacturing belts. The ministry's advanced materials development programs anchor procurement of research-grade instruments for battery electrode slurry monitoring. Osaka-based optical component suppliers face reformulation pressures from REACH-aligned coating chemistry restrictions.
China
NMPA pharmacopeial standards and GB methodology adoption accelerate instrument procurement across Yangtze River Delta pharmaceutical manufacturing zones. The national medical products administration's biologics aggregate detection requirements open specification gaps for sub-200 nanometer resolution systems. Shanghai contract development organizations displace fragmented multi-vendor installations with standardized platform deployments.
India
CDSCO complex generic approval pathways and PLI scheme incentives for pharmaceutical manufacturing expand quality control infrastructure across Maharashtra and Gujarat. The central drugs standard control organization's tightening particle characterization guidelines force upgrade cycles in Mumbai formulation facilities. Hyderabad biotechnology clusters show steepest expansion trajectory as biosimilar development programs multiply.
Laser Diffraction Analyzer Market Competitive Landscape
German precision optics manufacturers anchor one tier; Japanese instrumentation specialists hold differentiated positions through captive photodetector array capabilities. The vendor base concentrates around three to four integrated platform providers with full validation documentation capabilities, while mid-scale specialists occupy service-intensive niches. Dominant competitive moves include backward integration into optical component supply and unbundling of validation services from hardware sales.
Among European-anchored platform providers, Malvern Panalytical and Sympatec exemplify archetypes built on long-standing particle characterization methodologies and regional calibration laboratory networks. HORIBA occupies a position reflecting Japanese optics manufacturing heritage and integrated detector assembly capabilities. These three represent distinct strategic postures: European methodology dominance, Asian component integration, and North American service density respectively.
| Leading Market Players |
|---|
| Malvern Panalytical |
| HORIBA |
| Beckman Coulter |
| Anton Paar |
| Micromeritics Instrument Corporation |
| Shimadzu Corporation |
| Spectris |
| Sympatec |
| Danaher |
| Others |
Pricing and Supply Chain Analysis
Multinational pharmaceutical manufacturers with centralized capital equipment governance command substantial volume leverage, compressing list prices for laboratory-grade laser diffraction systems while elevating after-sales service bundling as the primary margin pool. This buyer concentration rewards vendors with captive validation documentation capabilities and penalizes fragmented service organizations.
Pricing Analysis
Direct-to-OEM discounts of 15-25 points off list price dominate procurement for pharmaceutical accounts above five-unit annual commitments, with three-tier pricing structure across premium, standard, and economy levels stratifying by validation documentation depth and software audit trail sophistication. Price differentiation hinges on ISO 13320 certification tier and 21 CFR Part 11 electronic records compliance, with German and Japanese vendors commanding brand premiums for optical component provenance. Cost compression in mid-tier systems is intensifying because contract development organizations are consolidating vendor relationships around single-source service agreements. Biotechnology startups show highest price sensitivity, while national laboratories demonstrate lowest sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Specialized optics talent scarcity in Baden-Württemberg and Bavaria constrains production scaling for multi-element photodetector arrays, forcing German manufacturers to anchor capacity expansion in apprentice-trained technician pipelines rather than lateral hiring. High-precision laser sources and photodetector arrays draw from concentrated supplier bases in Germany and Japan, with optical coating chemistries tethered to REACH-compliant reformulation timelines. Single-source vulnerability runs through Japanese photodetector array foundries facing coating chemistry restrictions. Distribution runs through direct field service organizations for pharmaceutical accounts, with regional calibration laboratories serving research equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser diffraction analyzer procurement has shifted toward pharmacopeial-grade validation specifications as FDA and EMA tighten particle characterization mandates for inhalation products and biologics aggregate detection.
For Market Incumbents: Acquire captive optical component fabrication capabilities to secure photodetector array supply against Japanese foundry concentration risk. Consolidate service density in North American life science corridors where Beckman Coulter's installed base maintenance contracts face displacement from independent validation providers. Defensive priority centers on backward integration into precision optics manufacturing and unbundling of regulatory documentation support from hardware transactions. For New Entrants and Emerging Players: Digital signal processing architectures with embedded machine learning inference engines offer entry wedge into bioprocessing applications where real-time aggregate monitoring replaces at-line testing. Target Indian biotechnology clusters in Hyderabad and Mumbai where biosimilar development programs multiply and CDSCO guidelines force upgrade cycles in fragmented quality control infrastructure. Go-to-market angle should emphasize method transferability between development and commercial manufacturing sites for contract development organizations. For Investors and Strategic Acquirers: Precision manufacturing conglomerates with captive optics divisions are the most active acquirer in this space, seeking analytical instrumentation platforms to anchor recurring consumables revenue. Five-to-ten year viability rests on R&D intensity in sub-200 nanometer resolution architectures and service network density in pharmaceutical manufacturing corridors. Acquisition target archetype: mid-scale European specialists with ISO 13320 calibration laboratory networks and EMA validation documentation capabilities. Signal to monitor: NMPA biologics aggregate detection requirements accelerating procurement in Yangtze River Delta contract manufacturing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | HORIBA's captive photodetector array capabilities insulate against REACH coating chemistry disruptions in German supply corridors. |
| Service Unbundling and Independent Validation | Third-party calibration providers capture recurring revenue from Malvern Panalytical's European installed base maintenance contracts. |
| Multi-Laser Array Architecture Development | Digital signal processing platforms displace single-source legacy designs across FDA-regulated pharmaceutical quality control laboratories. |
| Geographic Expansion into Indian Biotechnology Clusters | CDSCO complex generic pathways and PLI scheme incentives expand quality control infrastructure demand in Maharashtra formulation facilities. |
| Regulatory Documentation Bundling | Single-source service agreements combining IQ/OQ/PQ packages reduce training overhead for centralized pharmaceutical procurement functions. |
Research Methodology
Direct dialogue with instrument engineering directors, pharmaceutical quality control managers, regulatory affairs specialists at EMA-notified bodies, and calibration laboratory technicians grounded qualitative assessment of technology migration patterns and validation burden evolution. Secondary validation drew from FDA guidance documents on inhalation product characterization, EMA standards for nasal spray bioequivalence, ISO 13320 methodology publications, and SEC filings of listed analytical instrumentation conglomerates. Bottom-up instrument procurement modeling triangulated against top-down pharmaceutical capital expenditure surveys.
Segment-level projections across laboratory instruments, industrial analyzers, and research equipment incorporated technology displacement curves for multi-laser architectures, application penetration rates in quality control versus research and development workflows, and end-user procurement authority structures spanning multinational pharmaceutical governance and decentralized food processing engineering functions. CAGRs were derived from instrument replacement cycle compression analysis and regulatory mandate timing across FDA, EMA, NMPA, and CDSCO jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial standard evolution for biologics aggregate detection and REACH-aligned coating chemistry restriction timelines. Forecasts reflect assumptions regarding EMA inhalation product testing standard adoption rates and METI advanced materials program funding continuity. Material deviation in FDA guidance timing for sub-micron particle characterization or photodetector array supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market