
 Global Scanning Probe Microscopes (Spm) Market | 2026-2036
Global Scanning Probe Microscopes (Spm) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scanning Probe Microscopes (Spm) Market Foresight
Multi-source procurement for precision nanopositioning components is shifting toward qualified dual-vendor strategies among SPM original equipment manufacturers. Bruker Corporation leverages captive piezoelectric actuator supply chains to sustain margin control across its atomic force microscope portfolio. Park Systems competes through specialized semiconductor fab-integrated systems that dominate inline wafer inspection workflows. Oxford Instruments anchors its position via cryogenic SPM variants that occupy niche quantum materials research segments.
Scanning probe microscopes employ nanoscale probes raster-scanned across specimen surfaces via piezoelectric scanners, achieving vertical resolution below 0.1 nanometer through optical lever deflection detection or tunneling current feedback. These instruments enable quantitative topography mapping, mechanical property measurement, and electrical characterization at atomic scales for semiconductor process control and materials discovery. Atomic force microscopes generate the largest revenue pool due to their versatility across conductive and insulating samples in both air and fluid environments. Scanning tunneling microscopes retain specialized demand in surface science and catalysis research where atomic lattice imaging remains essential. Semiconductor inspection applications command premium pricing as foundries impose stricter metrology protocols at sub-7 nanometer nodes.
Japan's METI enforces JIS standards for nanoscale dimensional metrology traceability, compelling domestic SPM vendors to maintain calibration protocols that downstream electronics manufacturers demand for process qualification. The EPA regulates hazardous material handling in US nanotechnology facilities, shaping instrument design requirements for enclosed sample environments and automated tip exchange systems. The EU AI Act and CE marking directives increasingly influence software-controlled SPM platforms with automated image analysis pipelines. Stakeholders must monitor how export control expansions on dual-use nanotechnology equipment reshape equipment deployment strategies across Chinese and Korean fabrication ecosystems.
Market Dynamics
EUV lithography node shrinkage below 7 nanometers is forcing foundries to deploy atomic-resolution metrology at every process step, compressing replacement cycles and expanding installed base requirements for multi-modal SPM platforms.
Growth Catalysts
- Sub-nanometer node verification:Semiconductor fabs in Taiwan and South Korea now mandate SPM-based defect mapping for advanced packaging and 3D NAND layer alignment, embedding these instruments into production workflows rather than relegating them to R&D.
- METI traceability mandates:Japan's JIS standardization push for nanoscale dimensional metrology compels domestic electronics manufacturers to upgrade legacy systems, creating replacement demand that ripples through East Asian supply chains.
- Piezoelectric scanner precision gains:Closed-loop capacitive sensor feedback in next-generation nanopositioning stages enables sub-angstrom vertical resolution, opening materials science applications previously reserved for synchrotron methods.
Market Restraints
- Single-source piezoelectric ceramic supply:High-purity lead zirconate titanate formulations rely on concentrated European and Japanese suppliers, exposing OEMs to input cost volatility and allocation risk during demand surges.
- Probe tip consumable economics:Silicon nitride and diamond-like carbon tip replacement runs 15-20% of instrument lifetime cost, with wear rates accelerating on hard samples common in compound semiconductor research.
- Facility infrastructure requirements:Vibration isolation and thermal stability specifications demand dedicated cleanroom real estate, limiting deployment flexibility in space-constrained university laboratories.
Strategic Opportunities
- Quantum materials cryogenic variants:Ultra-low temperature SPM platforms for topological insulator and superconductor research remain underpenetrated outside major national laboratories, with modular retrofit kits offering entry paths for mid-tier institutions.
- Automated inline wafer inspection:Fab-integrated SPM systems with robotic sample handling and machine-learning defect classification can displace slower electron microscopy checkpoints in high-volume manufacturing.
- EU AI Act compliance pathways:Software-controlled platforms with documented algorithmic transparency and CE-marked automated image analysis pipelines gain preferential access to European research funding streams.
Industry Challenges
- Interdisciplinary operator expertise:Effective SPM utilization demands synthesis of surface physics, control systems engineering, and sample preparation protocols, creating hiring bottlenecks as instrument proliferation outpaces specialized training programs.
- Legacy data format integration:Proprietary file structures from discontinued vendor platforms obstruct longitudinal studies and cross-institutional collaboration, forcing costly migration projects or archival isolation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scanning Probe Microscopes (Spm) Market |
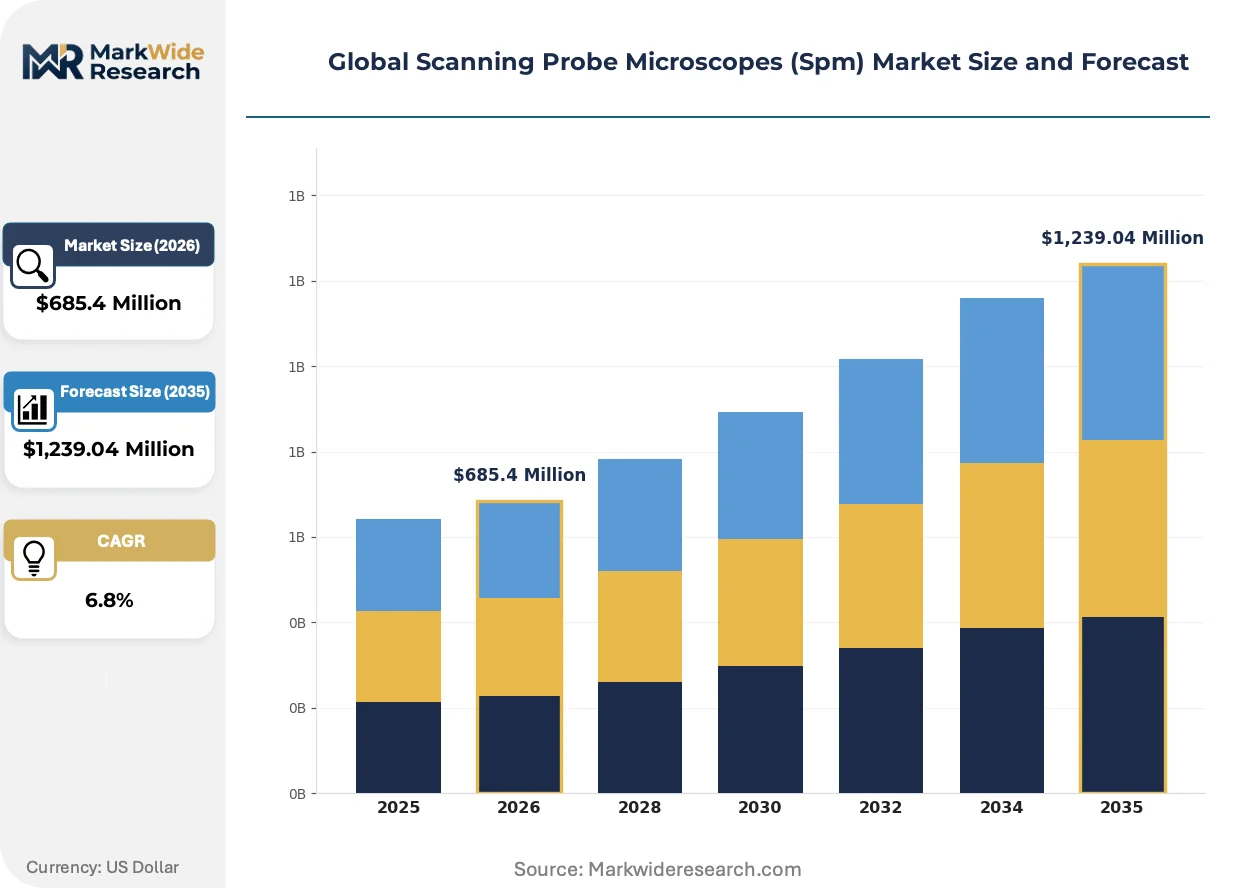
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomic Force Microscope, Scanning Tunneling Microscope, Near-field Scanning Optical Microscope, Magnetic Force Microscope, Electrochemical Scanning Probe Microscope Technology: Piezoelectric, Optical Lever, Capacitive, Tunneling, Magnetic Detection Application: Material Science Analysis, Semiconductor Inspection, Nanotechnology Research, Surface Characterization, Biological Sample Imaging End User: Research Laboratories, Academic Institutions, Electronics Manufacturers, Nanotech Companies, Quality Control Departments |
| Companies Covered | Bruker Corporation, Park Systems, Oxford Instruments, NT-MDT Spectrum Instruments, Nanosurf AG, Hitachi High-Tech Corporation, JEOL Ltd., RHK Technology, Nanonics Imaging Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scanning Probe Microscopes (Spm) Market Shifts & Advancements
SPM architecture is converging with computational microscopy and autonomous control systems, shifting competitive advantage from hardware specifications to software-enabled throughput and reproducibility.
High-speed amplitude modulation AFM is integrating real-time FPGA-based feedback controllers that maintain tracking bandwidth above 10 kHz, enabling video-rate imaging of dynamic biological processes. Pharmaceutical screening facilities in Switzerland and Massachusetts are adopting these platforms for mechanobiology studies. This speed threshold is integrating SPM into time-resolved experimental workflows previously dominated by optical super-resolution methods.
Japan's METI enforcement of JIS Q 17025-equivalent calibration protocols for nanoscale measurement traceability is compelling domestic vendors to maintain accredited service networks. Electronics manufacturers downstream now reject process qualification data from non-compliant instruments. South Korean foundries are responding by demanding equivalent documentation from imported equipment, elevating compliance costs for non-Japanese suppliers.
Consolidated procurement through multi-year framework agreements is displacing single-instrument purchasing at major research universities. German Max Planck Institutes and US National Laboratories now negotiate enterprise licenses spanning maintenance, training, and upgrade pathways. This concentration is most visible in Northern European markets where national research coordination bodies aggregate demand across previously autonomous institutions.
Global Scanning Probe Microscopes (Spm) Market Segmentation
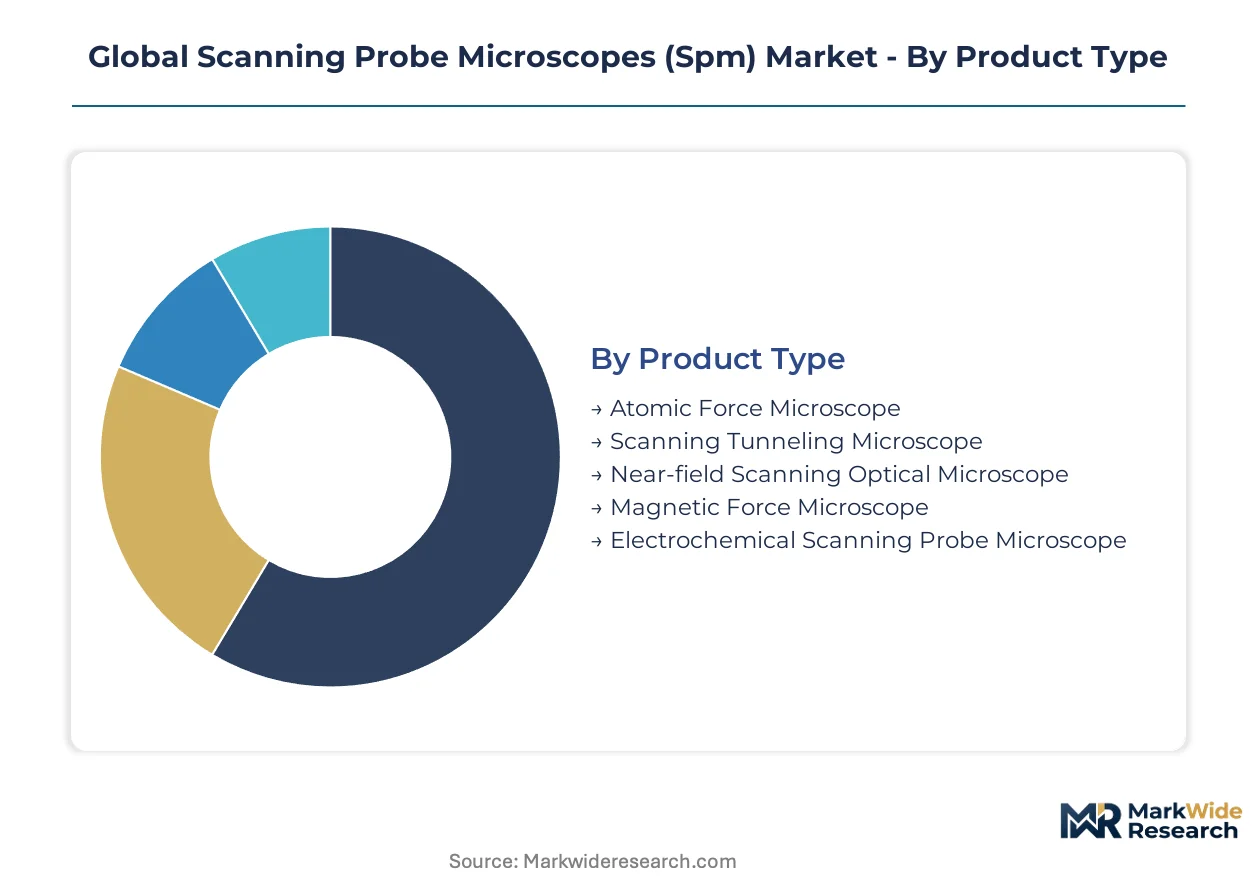
SPM purchasing decisions hinge on resolution requirements, sample environment constraints, and integration depth with existing metrology workflows. Semiconductor fabs prioritize throughput and automation, while materials science laboratories emphasize multi-modal flexibility and cryogenic compatibility.
Product Type:
Resolution thresholds and sample conductivity determine instrument selection across research and production environments.
- Atomic Force Microscope:Piezoelectric scanners raster nanoscale probes across conductive and insulating specimens in air, fluid, or vacuum, achieving sub-angstrom vertical resolution through optical lever deflection detection. Taiwan and South Korea foundries embed AFM systems inline for sub-7 nanometer node verification, compressing replacement cycles as EUV lithography demands intensify.
- Scanning Tunneling Microscope:Quantum tunneling current between conductive tip and sample surface enables atomic lattice imaging with lateral resolution below 0.1 nanometer. Surface science departments in Japan and Germany retain specialized demand for catalysis and superconductor research where direct orbital visualization remains essential.
- Near-field Scanning Optical Microscope:Sub-wavelength light confinement at aperture tips bypasses diffraction limits for spectroscopic mapping.
- Magnetic Force Microscope:Cantilever magnetization detects stray fields from magnetic domains in data storage media development.
- Electrochemical Scanning Probe Microscope:Bipotentiostat control enables localized corrosion and battery interface studies.
Volume sits with Atomic Force Microscope platforms; growth tilts toward Electrochemical Scanning Probe Microscope variants as solid-state battery research accelerates.
Technology:
Feedback mechanism precision directly constrains achievable resolution and scanning bandwidth.
- Piezoelectric:Lead zirconate titanate ceramic stacks deliver nanopositioning with angstrom-scale accuracy through voltage-induced strain, forming the mechanical backbone of virtually all commercial SPM platforms. High-purity formulations from concentrated European and Japanese suppliers expose OEMs to allocation risk during demand surges.
- Optical Lever:Laser deflection from cantilever backside enables sub-piconewton force sensitivity for soft biological samples.
- Capacitive:Parallel-plate sensors provide closed-loop position feedback immune to hysteresis drift.
- Tunneling:Exponential current-distance dependence delivers ultimate z-resolution for surface science.
- Magnetic Detection:Hall probes and SQUID sensors map field gradients without mechanical contact.
Installed base concentrates in Piezoelectric systems; Capacitive feedback architectures gain share fastest in next-generation semiconductor metrology.
Application:
Process control stringency versus exploratory research freedom shapes feature prioritization.
- Semiconductor Inspection:Automated defect classification and robotic wafer handling satisfy foundry throughput requirements at sub-7 nanometer nodes. South Korean and Taiwanese fabrication clusters command premium pricing for fab-integrated systems with machine-learning image analysis pipelines.
- Material Science Analysis:Multi-modal characterization spanning topography, mechanics, and electrochemistry supports battery and catalyst discovery.
- Nanotechnology Research:Graphene and quantum dot fabrication requires atomic-resolution verification.
- Surface Characterization:Thin-film tribology and adhesion studies drive industrial quality protocols.
- Biological Sample Imaging:Liquid-cell environments enable live-cell mechanobiology at pharmaceutical screening facilities.
Revenue pools deepest in Semiconductor Inspection; Biological Sample Imaging climbs the fastest as high-speed amplitude modulation AFM reaches video-rate acquisition.
End User:
Budget scale and technical staffing depth determine service contract complexity and training requirements.
- Electronics Manufacturers:Process qualification mandates from Japan's METI JIS traceability standards compel accredited calibration protocols, elevating compliance costs and favoring vendors with established service networks. Replacement cycles accelerate as dimensional metrology requirements tighten across East Asian supply chains.
- Research Laboratories:National facilities negotiate enterprise licenses spanning maintenance, training, and upgrade pathways.
- Academic Institutions:Space-constrained university laboratories struggle with vibration isolation infrastructure requirements.
- Nanotech Companies:Startup entities prioritize modular platforms with retrofit expansion capabilities.
- Quality Control Departments:Industrial metrology groups demand automated tip exchange and enclosed sample environments.
Procurement volume clusters with Electronics Manufacturers; Nanotech Companies expand most quickly as venture funding flows toward quantum materials commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity lead zirconate titanate deposits in Japan and South Korea anchor piezoelectric scanner supply chains for precision nanopositioning equipment. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster drive concentrated demand for atomic-resolution metrology systems.
Japan
Domestic electronics manufacturers accelerate replacement cycles for legacy SPM platforms under METI-enforced JIS Q 17025 calibration mandates. Tokyo and Osaka host accredited service networks that downstream process qualification protocols now require. Yokohama-based fabrication equipment suppliers integrate traceable nanoscale dimensional metrology into export-bound semiconductor tools.
South Korea
Samsung and SK Hynix impose stricter metrology protocols at sub-7 nanometer EUV nodes, embedding SPM systems inline for advanced packaging verification. The Ministry of Trade, Industry and Energy coordinates national nanotechnology infrastructure investments. Pyeongtaek and Hwaseong fabrication clusters command premium pricing for robotic wafer-handling platforms with machine-learning defect classification.
Taiwan
TSMC and United Microelectronics expand metrology budgets as 3D NAND layer alignment demands atomic-resolution defect mapping. The National Science and Technology Council funds nanoscale measurement traceability initiatives. Hsinchu Science Park concentrates fab-integrated SPM procurement for high-volume manufacturing workflows.
United States
Pharmaceutical screening facilities in Massachusetts and California adopt high-speed amplitude modulation AFM for live-cell mechanobiology studies. EPA regulations on hazardous material handling shape enclosed sample environment specifications for university nanotechnology facilities. Greater Boston and San Francisco Bay Area research clusters negotiate enterprise licenses spanning maintenance, training, and upgrade pathways.
Germany
Max Planck Institutes and Fraunhofer centers drive consolidated procurement through multi-year framework agreements replacing single-instrument purchasing. The EU AI Act and CE marking directives influence software-controlled SPM platforms with automated image analysis pipelines. Munich and Stuttgart host precision engineering suppliers serving cryogenic SPM variants for quantum materials research.
Global Scanning Probe Microscopes (Spm) Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs secure captive piezoelectric actuator supply chains against allocation risk. The vendor base stratifies across three tiers: diversified instrumentation conglomerates with metrology portfolios, specialized semiconductor fab-integration specialists, and cryogenic niche players serving national laboratories. Consolidation pressure intensifies as multi-year framework agreements concentrate procurement volume. Technology licensing and backward integration into high-purity ceramic formulations represent the dominant competitive moves.
Within the diversified instrumentation tier, Bruker Corporation exemplifies vertical control through captive supply chain strategies. Park Systems occupies a position among fab-integration specialists serving East Asian semiconductor clusters. Oxford Instruments anchors the cryogenic variant segment for quantum materials research infrastructure.
| Leading Market Players |
|---|
| Bruker Corporation |
| Park Systems |
| Oxford Instruments |
| NT-MDT Spectrum Instruments |
| Nanosurf AG |
| Hitachi High-Tech Corporation |
| JEOL Ltd. |
| RHK Technology |
| Nanonics Imaging Ltd. |
| Others |
Supply & Pricing Matrix
Closed-loop capacitive sensor feedback in next-generation nanopositioning stages simultaneously compresses manufacturing yields for piezoelectric scanner stacks and concentrates procurement power among East Asian foundries demanding sub-angstrom verification. This technical transition elevates input costs for high-purity lead zirconate titanate while embedding long-term service contracts into initial equipment sales.
Pricing Analysis
Warranty and calibration service bundling separates premium SPM platforms from economy-tier laboratory units, with accredited JIS Q 17025 protocols commanding substantial premiums in Japan. Price differentiation rests on automation depth and traceability certification, with semiconductor fabs in Taiwan and South Korea showing lowest price sensitivity due to EUV node compliance mandates. Cost compression in mid-tier academic systems is intensifying as vendors unbundle software modules and probe tip consumables.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand in Taiwan and South Korea, while distributor networks serve fragmented academic procurement in Europe and North America. High-purity lead zirconate titanate formulations draw from concentrated Japanese and European ceramic suppliers, with silicon nitride probe tips sourcing from German and Japanese precision manufacturers. Single-source vulnerability in piezoelectric ceramic feedstock exposes OEMs to allocation risk during semiconductor capital expenditure surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity piezoelectric ceramic capacity constraints prop pricing power for vendors with captive supply arrangements, creating durable margin structures despite downstream cost pressure.
For Market Incumbents: Acquire accredited calibration service networks to lock in replacement demand from Japan's METI-mandated traceability requirements. Defensive consolidation should prioritize backward integration into lead zirconate titanate formulations and FPGA controller intellectual property to neutralize emerging Chinese SPM vendors competing on scanner hardware cost.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in cryogenic SPM variants offers white-space entry for modular retrofit kits targeting mid-tier quantum materials laboratories. Target European research institutes with EU AI Act-compliant software pipelines and CE-marked automated analysis modules, leveraging service unbundling to undercut integrated OEM offerings.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified instrumentation conglomerates seeking metrology portfolio expansion. Long-term viability favors vendors with demonstrated fab-integration credentials and captive piezoelectric supply. Watch South Korean foundry capital expenditure announcements as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Ceramics | Captive supply of high-purity lead zirconate titanate insulates margins from Japanese ceramic allocation constraints. |
| Accredited Calibration Service Network Expansion | JIS Q 17025-compliant service capabilities lock in replacement cycles among Japan's electronics manufacturers. |
| Fab-Integrated System Development | Robotic wafer handling with machine-learning defect classification displaces electron microscopy checkpoints at TSMC and Samsung. |
| Cryogenic Platform Modularization | Retrofit kits for ultra-low temperature operation open quantum materials research segments outside national laboratories. |
| EU AI Act Compliance Pathway Investment | Documented algorithmic transparency and CE-marked pipelines secure European research funding access. |
Research Methodology
Document review covered SEC filings from metrology equipment manufacturers, Japanese METI standardization notices, and South Korean Ministry of Trade policy circulars, complemented by interviews with SPM original equipment manufacturer product managers, semiconductor fab metrology directors, and piezoelectric ceramic procurement leads. Secondary validation drew from EU AI Act implementation guidance, EPA nanotechnology facility regulations, and customs trade data for precision nanopositioning equipment. Bottom-up instrument shipment analysis triangulated against top-down semiconductor capital expenditure forecasts.
Historical shipment patterns cross-referenced against panel input from East Asian foundry engineering directors established baseline demand elasticity. Segmentation modeling spanned product type, feedback technology, application vertical, and end-user archetype across the projection horizon. CAGRs derived from instrument replacement cycle compression rates and EUV lithography node transition timelines, with semiconductor inspection intensity and materials science funding trajectories as primary demand drivers.
Inputs from Japanese electronics manufacturers and South Korean foundry operators were available through the study window; gaps in Chinese domestic SPM vendor shipment data introduce uncertainty bands around Asia-Pacific market share estimates. Forecasts reflect assumptions regarding EUV node transition pacing and METI enforcement consistency. Periodic stress-testing of base assumptions against foundry capital expenditure announcements and ceramic supplier allocation bulletins is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Headspace Gas Analyzers Market