
 Conductivity Analyzers Market | 2026-2036
Conductivity Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Conductivity Analyzers Market Outlook
German sensor manufacturers is repositioning production capacity toward smart sensor architectures. Emerson Electric Co. leverages its automation platform to bundle conductivity modules with distributed control systems. ABB Ltd. anchors its European installed base through service contracts on in-line analyzer fleets. Endress+Hauser Group specializes in hygienic designs that dominate food and beverage validation protocols.
Conductivity analyzers measure ionic concentration in aqueous solutions through electrode-based or inductive sensing, typically spanning ranges from ultrapure water at 0.055 microsiemens per centimeter to brine solutions exceeding 500 millisiemens per centimeter, with primary industrial purpose in process control and regulatory compliance verification. In-line analyzers command the largest installed base due to continuous monitoring requirements in chemical processing, while smart sensors represent the fastest-expanding technology segment as plants replace analog transmitters with digital diagnostics. Portable analyzers retain margin strength in environmental fieldwork and pharmaceutical validation audits where mobility outweighs automation.
EPA effluent limitation guidelines and FDA process analytical technology initiatives shape product specifications in the United States, while ECHA REACH restrictions on hazardous substances affect electrode material selection across Europe. China's MEE water pollution prevention standards mandate online monitoring at discharge points, creating specification pull for wireless transmission variants. Stakeholders must weigh calibration protocol standardization against the fragmentation of national certification requirements as digital sensor platforms proliferate.
Market Dynamics
Digital sensor platforms are compressing calibration cycles and forcing analog transmitter obsolescence across process industries, while electrode material regulations in Europe and Asia simultaneously reshape supply chains toward platinum-titanium alloys.
Growth Catalysts
- EPA effluent mandates:Water treatment plants in the United States deploy continuous monitoring systems to meet Clean Water Act compliance deadlines, pulling demand for in-line analyzer installations.
- China's MEE discharge protocols:Provincial environmental bureaus along coastal industrial zones mandate real-time monitoring at discharge points, accelerating specification for wireless transmission variants.
- Smart sensor architectures:German manufacturers reposition production capacity toward digital diagnostic platforms that replace legacy analog transmitters with predictive maintenance capabilities.
Market Restraints
- Electrode material cost volatility:Platinum and titanium alloy prices fluctuate with mining supply constraints, compressing margins on contact electrode designs.
- ECHA REACH compliance friction:Material disclosure requirements for hazardous substances extend certification timelines and limit supplier pools for European manufacturers.
- Optical sensing substitution:Turbidity and UV absorption analyzers encroach on conductivity's traditional stronghold in certain water quality verification applications.
Strategic Opportunities
- India's industrial corridor expansion:Chemical processing clusters in Gujarat and Maharashtra present underpenetrated demand for hygienic conductivity designs in pharmaceutical manufacturing.
- FDA process analytical technology:Validation protocol alignment creates specification pull for smart sensors with embedded diagnostics in United States bioprocessing facilities.
- Edge computing convergence:Integration of conductivity modules with plant-level analytics platforms enables real-time process optimization without centralized control system dependency.
Industry Challenges
- Calibration technician scarcity:Specialized expertise in electrode maintenance and buffer solution protocols remains concentrated among aging workforces in mature markets.
- Legacy system integration complexity:Digital sensor deployment requires protocol translation layers to communicate with existing distributed control architectures in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductivity Analyzers Market |
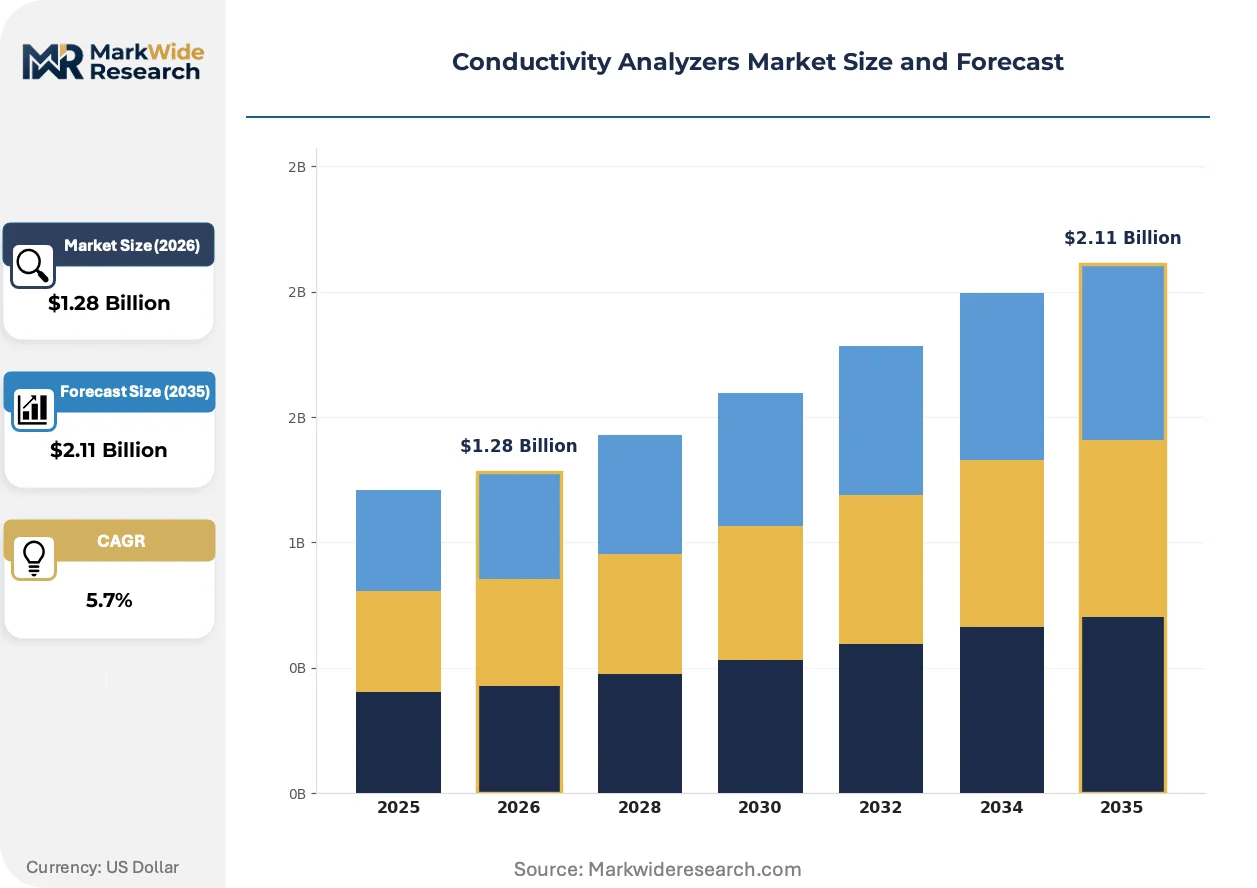
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Bench-top Analyzers, In-line Analyzers, Flow-through Analyzers End User: Chemical Industry, Water Treatment Plants, Food & Beverage, Pharmaceuticals Technology: Digital Conductivity, Analog Conductivity, Wireless Transmission, Smart Sensors Application: Quality Control, Environmental Monitoring, Research & Development, Process Automation |
| Companies Covered | Emerson Electric Co., ABB Ltd., Endress+Hauser Group, Yokogawa Electric Corporation, Mettler-Toledo International Inc., Thermo Fisher Scientific Inc., Hach Company, Metrohm, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductivity Analyzers Market Strategic Shifts
Inductive sensing architectures and wireless transmission protocols are redefining installation economics, while regulatory pressure on electrode materials accelerates materials science investment across the supplier base.
Inductive conductivity sensors eliminate electrode fouling through toroidal coil designs that measure solution conductivity without direct fluid contact. Food and beverage processors in dairy and brewing applications adopt these designs to reduce cleaning validation downtime. The technology is overtaking contact electrode systems in hygienic applications where CIP/SIP cycles previously degraded sensor longevity.
ECHA REACH restrictions on nickel and cobalt compounds in contact electrodes force European manufacturers toward platinum-iridium and titanium alloy formulations. The regulation extends material qualification timelines by eight to fourteen months for new product introductions. German and Swiss sensor suppliers absorb these costs through premium positioning in pharmaceutical validation markets where material traceability commands price tolerance.
Service contract unbundling separates hardware procurement from calibration and maintenance agreements in mature installed bases. Chemical processors in the United States now source analyzers through capital budgets while contracting aftermarket services to third-party specialists or OEM service divisions. This bifurcation concentrates in the Gulf Coast petrochemical corridor where analyzer fleet sizes justify dedicated technical service outsourcing.
Conductivity Analyzers Market Segmentation
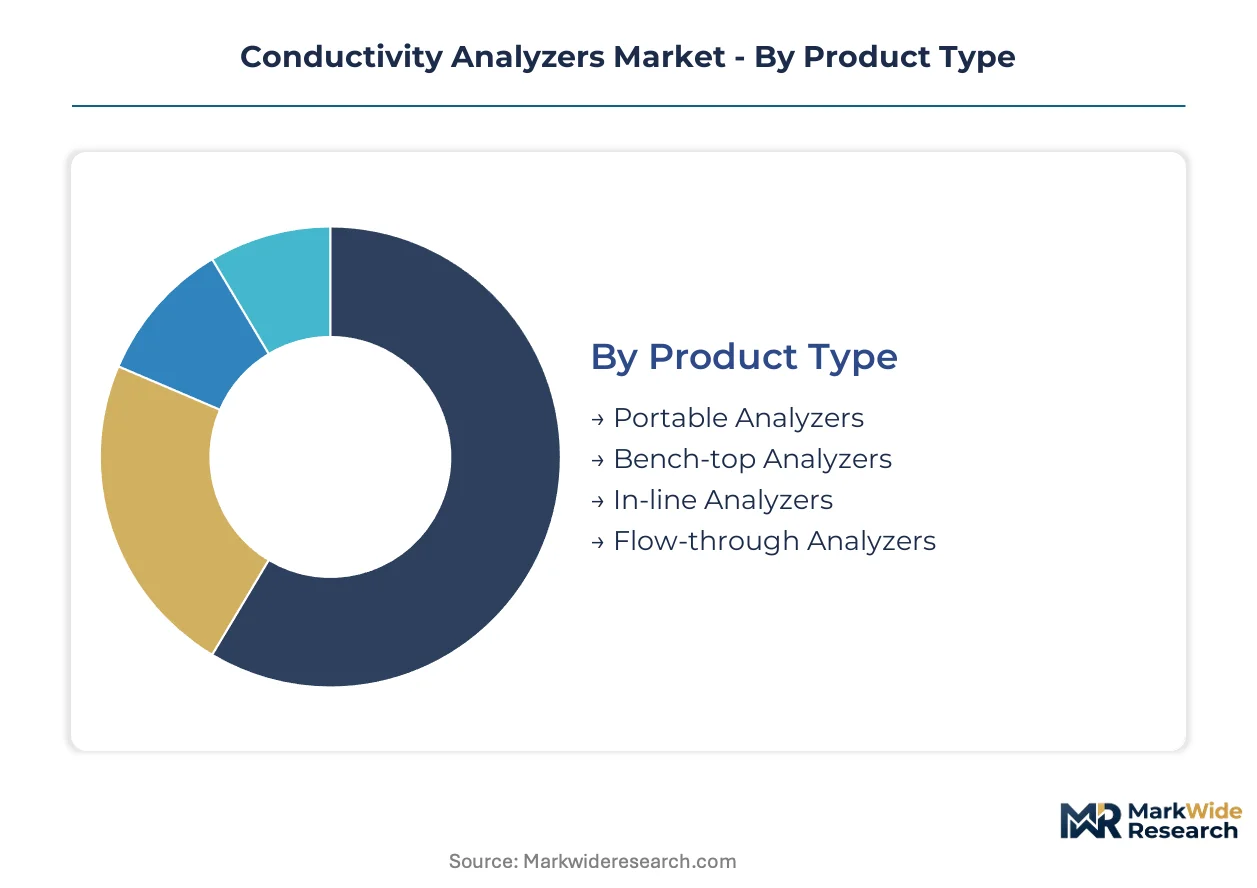
Conductivity analyzer purchasing decisions split sharply between continuous process integration and discrete validation requirements. Buyers weigh installation permanence, calibration frequency, and regulatory documentation burden against capital recovery timelines.
Product Type:
Buyers differentiate primarily by installation permanence and maintenance labor intensity rather than analytical precision.
- In-line Analyzers:Permanent installation within process piping enables real-time ionic concentration monitoring without sampling delays. Chemical processors along the United States Gulf Coast deploy these for EPA effluent compliance, accepting higher upfront capital for reduced technician labor.
- Portable Analyzers:Battery-powered handheld units with electrode-based or inductive sensing support field validation audits and multi-site deployment. Pharmaceutical manufacturers in Germany leverage these for GMP documentation during batch release testing.
- Bench-top Analyzers:Laboratory-grade instruments with temperature compensation and automated calibration routines serve quality control workflows. Research institutions specify these for method development requiring traceable certification.
- Flow-through Analyzers:Compact sampling systems integrate with existing process streams for intermittent monitoring. Water treatment utilities deploy these at secondary clarification stages where continuous measurement is unnecessary.
Volume sits with in-line configurations; growth tilts toward portable units as distributed manufacturing expands validation requirements.
End User:
Regulatory stringency and contamination risk tolerance separate buyers across process industries.
- Chemical Industry:Harsh process chemistries and elevated temperatures demand corrosion-resistant electrode materials and inductive sensing architectures. Chlor-alkali producers in China specify titanium-alloy contact electrodes for brine concentration monitoring.
- Water Treatment Plants:Continuous discharge monitoring mandates drive specification for wireless transmission and digital diagnostic platforms. United States municipal utilities deploy smart sensors to meet EPA Clean Water Act reporting deadlines.
- Food & Beverage:Hygienic design requirements and CIP/SIP cycle compatibility dominate procurement criteria. Dairy processors in Bavaria prioritize inductive sensors to eliminate fouling and reduce cleaning validation downtime.
- Pharmaceuticals:Material traceability and embedded diagnostics support FDA process analytical technology initiatives. Bioprocessing facilities in Massachusetts specify smart sensors with predictive maintenance capabilities for upstream cell culture monitoring.
Revenue concentrates in chemical processing; expansion accelerates fastest in pharmaceutical validation protocols.
Technology:
Digital maturity and integration architecture determine replacement cycles and total cost of ownership.
- Smart Sensors:Embedded diagnostics, predictive maintenance algorithms, and digital communication protocols replace legacy analog transmitters. German manufacturers reposition production capacity toward these architectures as brownfield facilities modernize.
- Digital Conductivity:Microprocessor-based signal processing with automated temperature compensation and self-diagnostics reduces calibration labor. Water treatment plants specify these for remote monitoring stations with limited technician access.
- Wireless Transmission:Battery-powered or energy-harvesting communication eliminates cabling costs in retrofit installations. China's coastal industrial zones mandate these for discharge point monitoring under MEE protocols.
- Analog Conductivity:Traditional 4-20 mA output signals persist in legacy distributed control system integrations. Aging installed bases in mature markets delay replacement due to protocol translation complexity.
Installed base remains analog-heavy; replacement demand shifts decisively toward smart sensor platforms.
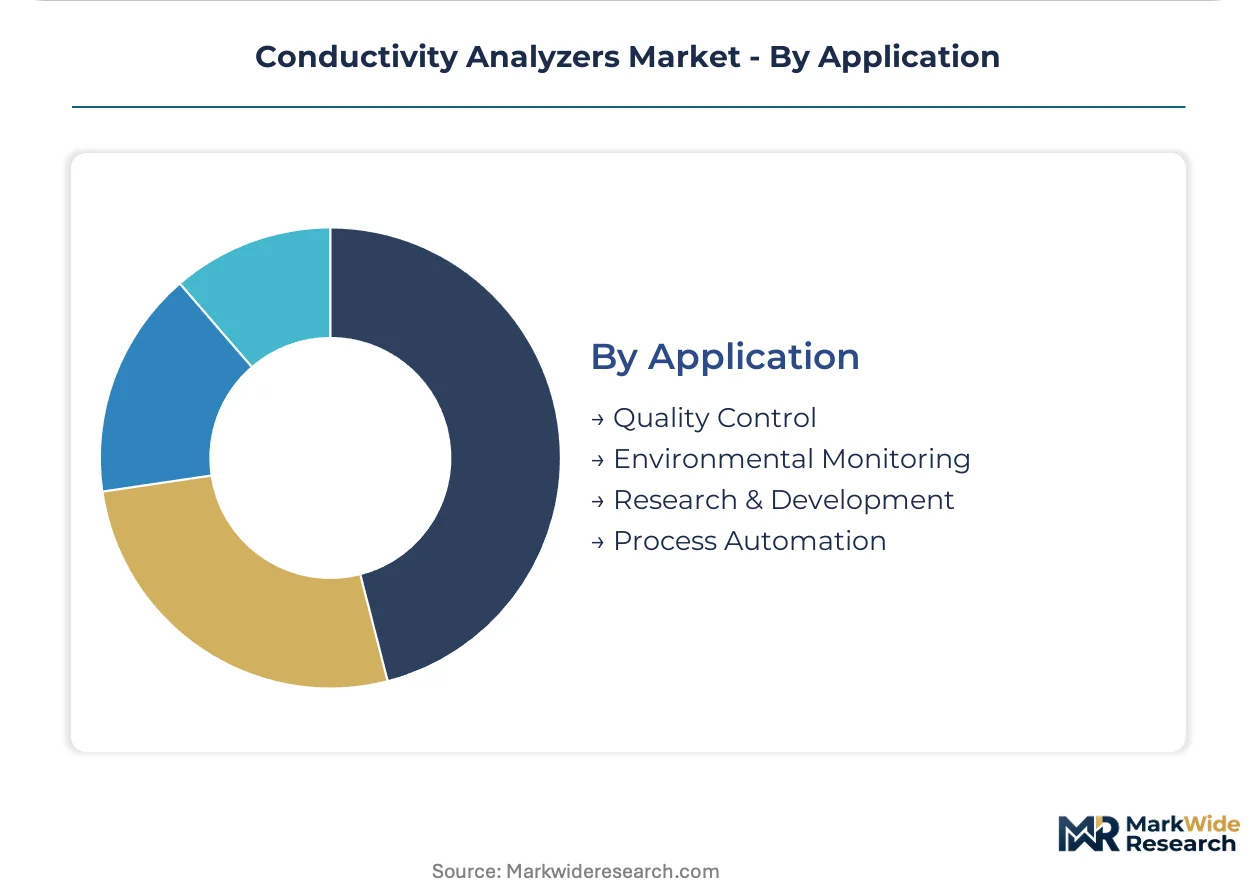
Application:
Documentation requirements and decision latency separate real-time process control from retrospective quality verification.
- Process Automation:Closed-loop control integration with distributed control systems enables real-time chemical dosing adjustments. Petrochemical refineries specify in-line analyzers for cooling water treatment optimization.
- Quality Control:Batch release testing and certificate of analysis generation demand traceable calibration records. Pharmaceutical quality laboratories in Switzerland deploy bench-top units with automated documentation.
- Environmental Monitoring:Regulatory discharge reporting and watershed protection drive continuous or grab-sample measurement. United States EPA enforcement actions accelerate specification for tamper-evident data logging.
- Research & Development:Method flexibility and multi-parameter capability support formulation exploration and sensor validation. Academic institutions and contract research organizations prioritize modular architectures.
Deployment volume favors process automation; specification growth concentrates in environmental compliance verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum and titanium mining districts in South Africa and Russia anchor electrode material supply chains for conductivity analyzer manufacturing. Water treatment infrastructure expansion and chemical processing cluster development drive regional demand differentiation.
United States
Municipal utilities along the Gulf Coast petrochemical corridor deploy in-line analyzers for cooling water optimization. EPA effluent limitation guidelines mandate continuous discharge monitoring at 16,000 publicly owned treatment works. Massachusetts bioprocessing facilities specify smart sensors with predictive maintenance for upstream cell culture applications.
Germany
Bavarian dairy processors prioritize inductive sensors to eliminate fouling and reduce cleaning validation downtime. ECHA REACH restrictions on nickel and cobalt compounds extend material qualification timelines by eight to fourteen months. Swiss and German sensor suppliers absorb compliance costs through premium positioning in pharmaceutical validation markets.
China
Provincial environmental bureaus in Jiangsu and Zhejiang mandate real-time discharge monitoring at coastal industrial zones. MEE water pollution prevention standards accelerate specification for wireless transmission variants. Chlor-alkali producers in Shandong specify titanium-alloy contact electrodes for brine concentration monitoring.
India
Chemical processing clusters in Gujarat and Maharashtra present underpenetrated demand for hygienic conductivity designs. The country's national pharmaceutical regulator tightens validation protocol requirements for active pharmaceutical ingredient manufacturing. Maharashtra's pharmaceutical corridor expands quality control laboratory infrastructure for export compliance.
Japan
Semiconductor fabrication facilities in Kyushu deploy ultrapure water monitoring systems at 0.055 microsiemens per centimeter sensitivity. METI industrial efficiency standards promote predictive maintenance integration in process control systems. Osaka-based automation integrators bundle conductivity modules with distributed control architectures.
Conductivity Analyzers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital diagnostic platforms and wireless transmission protocols. The supplier base concentrates among industrial automation conglomerates with sensor divisions and specialized analytical instrument manufacturers. Three archetypes dominate: diversified automation platforms, hygienic design specialists, and laboratory-grade precision instrument makers. Capacity repositioning toward smart sensor architectures and service contract unbundling represent the primary competitive vectors.
Among diversified automation platforms, Emerson Electric Co. and ABB Ltd. represent the integrated-systems archetype, leveraging control system bundling to secure analyzer placement. Endress+Hauser Group exemplifies the hygienic design specialist tier, occupying a position in food and beverage validation protocols where material traceability commands price tolerance. These three anchors illustrate how competitive positioning splits between scale-driven platform integration and premium specialization in regulated verticals.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Endress+Hauser Group |
| Yokogawa Electric Corporation |
| Mettler-Toledo International Inc. |
| Thermo Fisher Scientific Inc. |
| Hach Company |
| Metrohm |
| HORIBA |
| Others |
Value Chain & Pricing Dynamics
Water treatment utilities concentrated along the United States Gulf Coast petrochemical corridor negotiate capital-budget procurement for in-line analyzer hardware while outsourcing calibration services to third-party specialists, establishing a bifurcated pricing model that separates upfront equipment acquisition from recurring technical service contracts.
Pricing Analysis
Warranty and calibration service bundling distinguishes premium-tier suppliers from economy competitors, with German and Swiss manufacturers absorbing ECHA REACH compliance costs through extended material-traceability documentation that justifies 40-60% price premiums over standard-tier analog transmitters. Pricing stratifies across premium, standard, and economy tiers based on certification grade for FDA process analytical technology validation and embedded predictive diagnostics capability. Cost compression in the analog transmitter segment is intensifying because brownfield facilities delay digital migration due to protocol translation complexity. Municipal utilities exhibit highest price sensitivity, while pharmaceutical bioprocessing facilities demonstrate lowest sensitivity due to batch-release documentation requirements.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States maintain finished-goods inventory for rapid deployment to chemical processing clusters and municipal utilities. Electrode material supply draws from South African platinum mining districts and Russian titanium feedstock, creating dependency on geopolitically concentrated raw material sources. Single-source vulnerability in platinum-iridium alloy supply chains exposes European manufacturers to eight-to-fourteen-month material qualification delays. Distribution runs through automation integrators and direct OEM service divisions serving installed-base fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductivity analyzers market sits in a technology-transition phase as smart sensor architectures with embedded diagnostics displace legacy analog transmitters across process industries.
For Market Incumbents: Deepen vertical integration into platinum-titanium alloy electrode supply chains to mitigate ECHA REACH-driven material cost volatility and qualification timeline extensions. Anchor installed-base positions through unbundled service contracts that capture recurring calibration revenue from municipal utilities facing technician scarcity. Prioritize predictive maintenance algorithm development to defend against optical sensing substitution in water quality verification applications. For New Entrants and Emerging Players: System integrators in India's Gujarat and Maharashtra chemical corridors represent the most penetrable channel for hygienic conductivity designs targeting underpenetrated pharmaceutical manufacturing validation requirements. Wireless transmission variants for China's coastal industrial zones offer specification alignment with MEE discharge monitoring mandates without competing head-to-head against entrenched automation platform bundling. Pursue edge computing convergence partnerships to bypass centralized control system dependency in brownfield facility retrofits. For Investors and Strategic Acquirers: The window for entry favors smart sensor technology specialists with FDA process analytical technology validation credentials and embedded diagnostic software stacks. Long-term viability hinges on capturing pharmaceutical and bioprocessing verticals where material traceability commands sustained price tolerance. Monitor EPA effluent limitation guideline enforcement intensity as the signal indicating acceleration in United States municipal utility replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Platform Development | Embedded diagnostics displace analog transmitters in FDA-regulated bioprocessing facilities. |
| Platinum-Titanium Alloy Backward Integration | In-house electrode material supply mitigates ECHA REACH qualification timeline compression. |
| Wireless Transmission Certification | MEE discharge protocol alignment accelerates specification in China's coastal industrial zones. |
| Service Contract Unbundling | Recurring calibration revenue captures value from municipal utility technician scarcity. |
| Edge Computing Convergence | Plant-level analytics integration bypasses legacy distributed control system retrofit barriers. |
Study Parameters
Independent corroboration across instrument manufacturer technical directors, water treatment plant maintenance supervisors, and pharmaceutical quality assurance managers underwrites the qualitative findings in this study. Primary fieldwork with automation platform engineers, calibration service technicians, and regulatory compliance officers at EPA-regulated facilities combined with secondary validation from FDA process analytical technology guidance documents, ECHA REACH substance restriction databases, and MEE water pollution prevention standards. Bottom-up demand modeling from end-user procurement patterns and top-down supply-side capacity assessments triangulate volume estimates.
Comparable historical reference periods spanning analog-to-digital transmitter replacement cycles anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, end-use industry vertical, technology architecture, and regional regulatory framework dimensions. CAGRs derived from installed-base replacement velocity, brownfield modernization timelines, and greenfield chemical processing capacity additions. Industry-specific inputs included EPA effluent limitation guideline enforcement schedules and ECHA REACH material qualification timeline extensions.
Caveats apply where platinum-titanium alloy supply disruptions, optical sensing technology substitution acceleration, or calibration technician labor pool contraction could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and digital sensor adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Absorption Spectrometers Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Modular Instruments Market