
 Universal Probe Library Market | 2026-2036
Universal Probe Library Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Probe Library Market Analytics
REACH is recalibrating the cost-of-entry calculus for probe manufacturers selling into European research channels. Thermo Fisher Scientific leverages its CE-IVD infrastructure to sustain compliant distribution across EEA member states. Qiagen anchors its position through ISO 13485-certified production lines that satisfy notified body scrutiny. Roche Life Science differentiates by controlling end-to-end oligonucleotide synthesis from design to stabilized shipping formats.
Universal probe libraries are collections of predesigned, labeled oligonucleotide pairs optimized for real-time PCR quantification across transcriptomes, typically featuring locked nucleic acid modifications for thermal stability and single-mismatch discrimination. They serve as off-the-shelf reagents that eliminate probe-design bottlenecks in gene-expression analysis and pathogen detection. Multiplex probes capture the dominant share of product-type revenue because high-throughput screening programs prioritize reaction-economy over customization flexibility. Diagnostic Testing applications are expanding fastest among the four tracked segments, driven by liquid-biopsy assay development and infectious-disease panel rollouts where turnaround time determines contract awards.
FDA 510(k) pathways and EMA IVD performance standards jointly shape product-development timelines for any manufacturer targeting clinical translation. EPA guidelines on nucleic acid detection in environmental matrices create ancillary demand channels outside human diagnostics. WHO prequalification benchmarks for tuberculosis and HIV viral-load assays extend addressable volume into procurement programs across low-income country networks. Stakeholders must monitor how emerging pharmacogenomic labeling requirements from FDA and EMA redirect probe-library design priorities toward clinically actionable variant coverage.
Market Dynamics
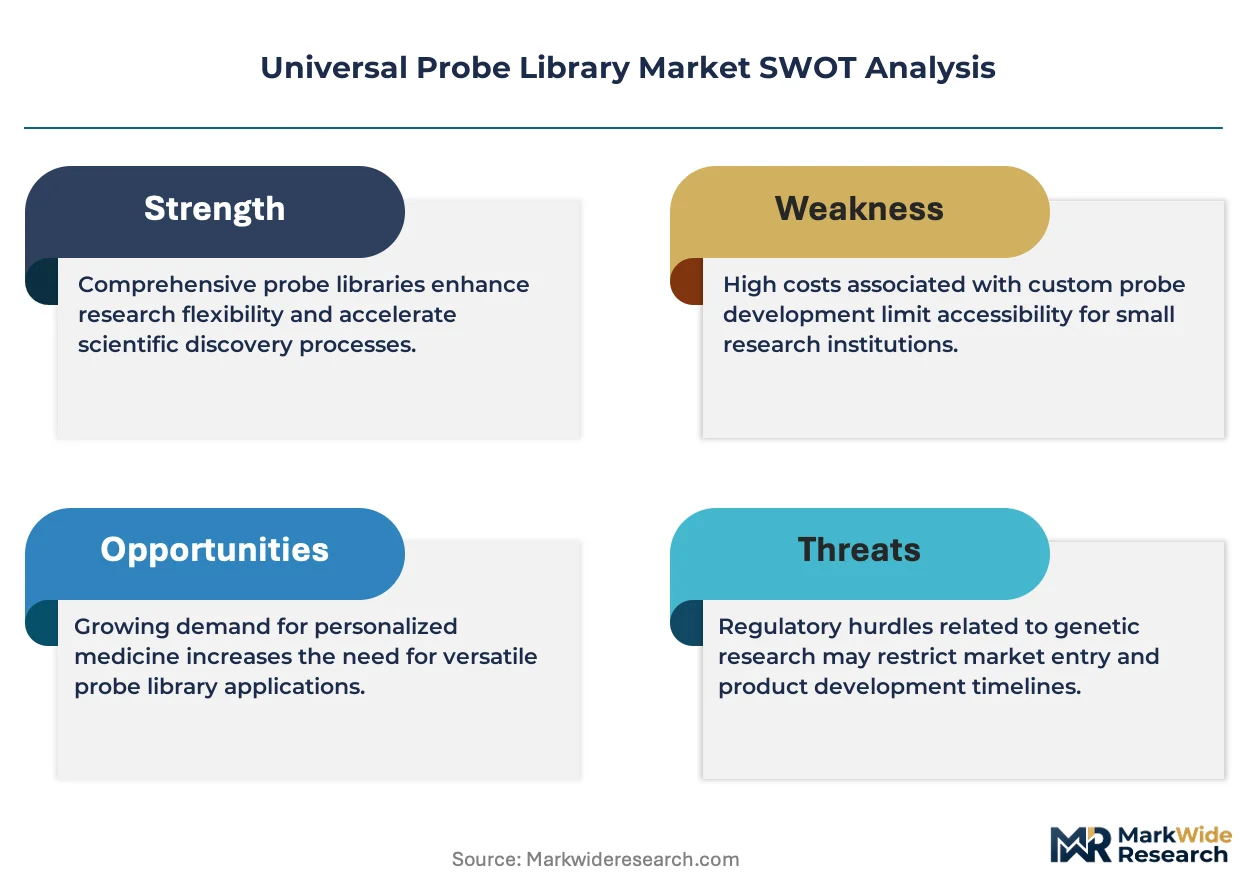
Companion diagnostic programs are consolidating probe procurement around pre-designed libraries, compressing design-to-validation timelines and locking out smaller assay developers lacking ISO 13485 certification pathways.
Growth Catalysts
- Liquid-biopsy assay development:Circulating tumor DNA panels require standardized probe sets that eliminate design variability across clinical sites. Contract research organizations in Germany's Rhine-Main cluster are scaling qPCR workflows to meet this demand.
- EU In Vitro Diagnostic Regulation:Tightened performance-documentation requirements for probe-based assays favor suppliers with pre-validated probe libraries and established CE-IVD technical files.
- Locked nucleic acid modifications:These chemical modifications enhance thermal stability and single-mismatch discrimination, enabling multiplexed pathogen detection in infectious-disease panel rollouts.
Market Restraints
- Oligonucleotide synthesis input concentration:Phosphoramidite supply chains concentrate among three specialized chemical manufacturers, exposing probe producers to price volatility and allocation constraints.
- REACH compliance costs:ECHA substance registration and downstream user obligations recalibrate cost-of-entry for manufacturers selling into European research channels, particularly for novel modified nucleotides.
- CRISPR-based diagnostic substitution:Guide RNA approaches for nucleic acid detection are displacing probe-dependent qPCR in certain research screening applications where customization flexibility outweighs standardization benefits.
Strategic Opportunities
- WHO prequalification procurement:Tuberculosis and HIV viral-load assay benchmarks extend addressable volume into procurement programs across low-income country networks lacking in-house probe design capability.
- Pharmacogenomic labeling convergence:FDA and EMA emerging requirements for clinically actionable variant coverage redirect probe-library design priorities toward CYP450 and pharmacodynamic gene panels.
- Digital PCR platform integration:Absolute quantification workflows are absorbing probe libraries as consumable anchors, creating new placement channels beyond traditional qPCR installed bases.
Industry Challenges
- CE-IVD technical file compilation:Notified body scrutiny of analytical and clinical performance data extends certification timelines to 18-24 months, straining R&D-to-revenue conversion.
- Multiplex assay integration complexity:Combining 4-6 probe pairs per reaction well requires sophisticated primer-probe interaction modeling that exceeds legacy bioinformatics team capabilities at mid-tier assay developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Probe Library Market |
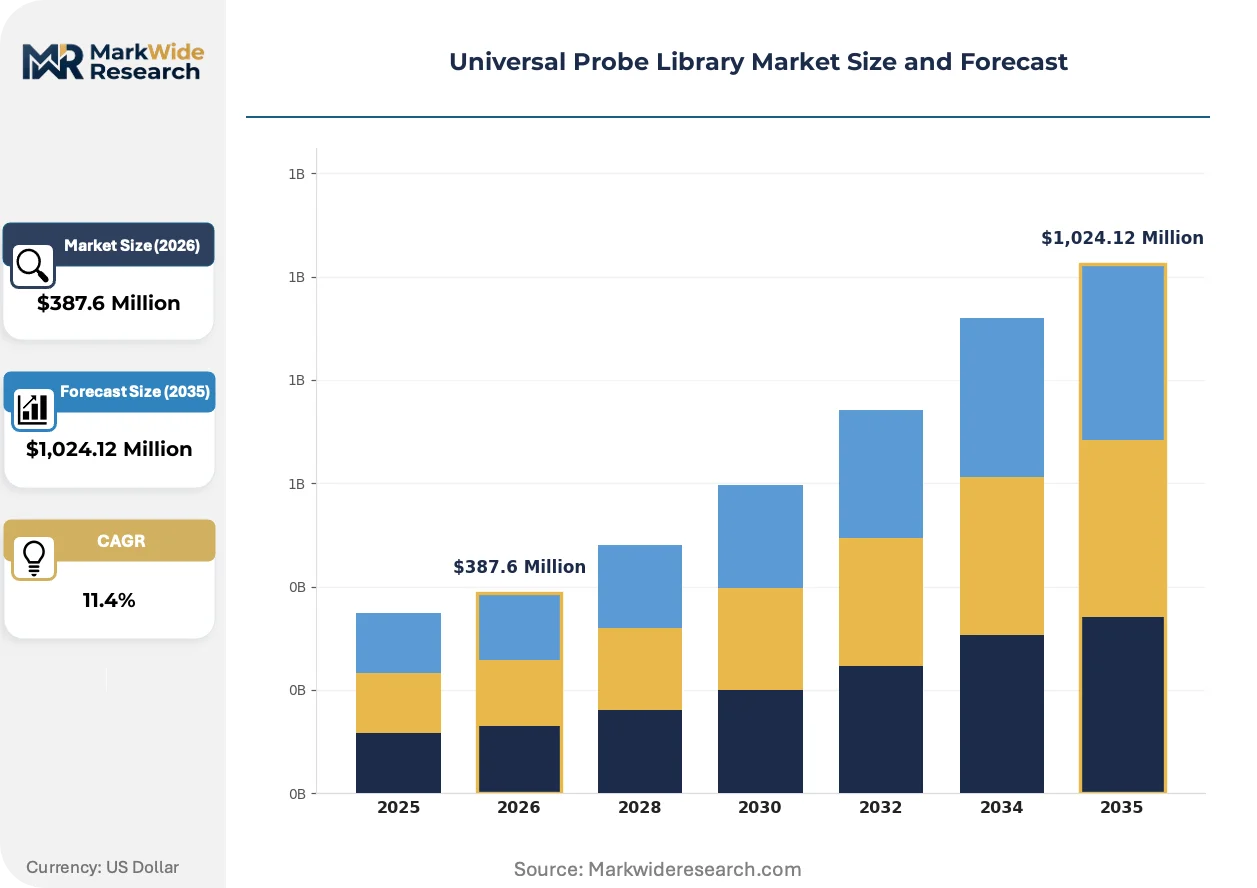
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiplex Probes, Singleplex Probes, Custom Probes, Pre-designed Probes Application: Genetic Research, Diagnostic Testing, Environmental Monitoring, Drug Development End User: Research Laboratories, Diagnostic Laboratories, Pharmaceutical Companies, Academic Institutions Technology: Real-time PCR, Next-Generation Sequencing, Microarrays, In-Situ Hybridization |
| Companies Covered | Roche Life Science, Sigma-Aldrich, Biocompare, SABiosciences, Thermo Fisher Scientific, Qiagen, Takara, New England Biolabs, Applied Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Probe Library Market Evolving Landscape
Real-time PCR quantification workflows are absorbing automation and artificial intelligence at the design-validation boundary, compressing development cycles while elevating performance documentation requirements.
Locked nucleic acid chemistry is absorbing multiplexing demands from high-throughput screening programs. Pharmaceutical toxicology groups deploy these modified probes to compress reaction-economy metrics across 384-well formats. The technology is absorbing design-standardization pressure that previously forced custom probe synthesis for each transcriptome project.
REACH substance evaluation is forcing reformulation of certain fluorophore conjugates used in hydrolysis probe architectures. ECHA authorization requirements for persistent organic pollutant candidates are redirecting R&D investment toward alternative dye chemistries. European diagnostic manufacturers are responding by accelerating technical file updates ahead of sunset date deadlines.
Assay developers are unbundling probe procurement from full kit sourcing, creating direct purchasing relationships with oligonucleotide suppliers. This disintermediation compresses per-reagent costs for high-volume operators while fragmenting vendor management overhead. The pattern is most visible among US-based reference laboratories scaling liquid-biopsy test menus.
Universal Probe Library Market Segmentation
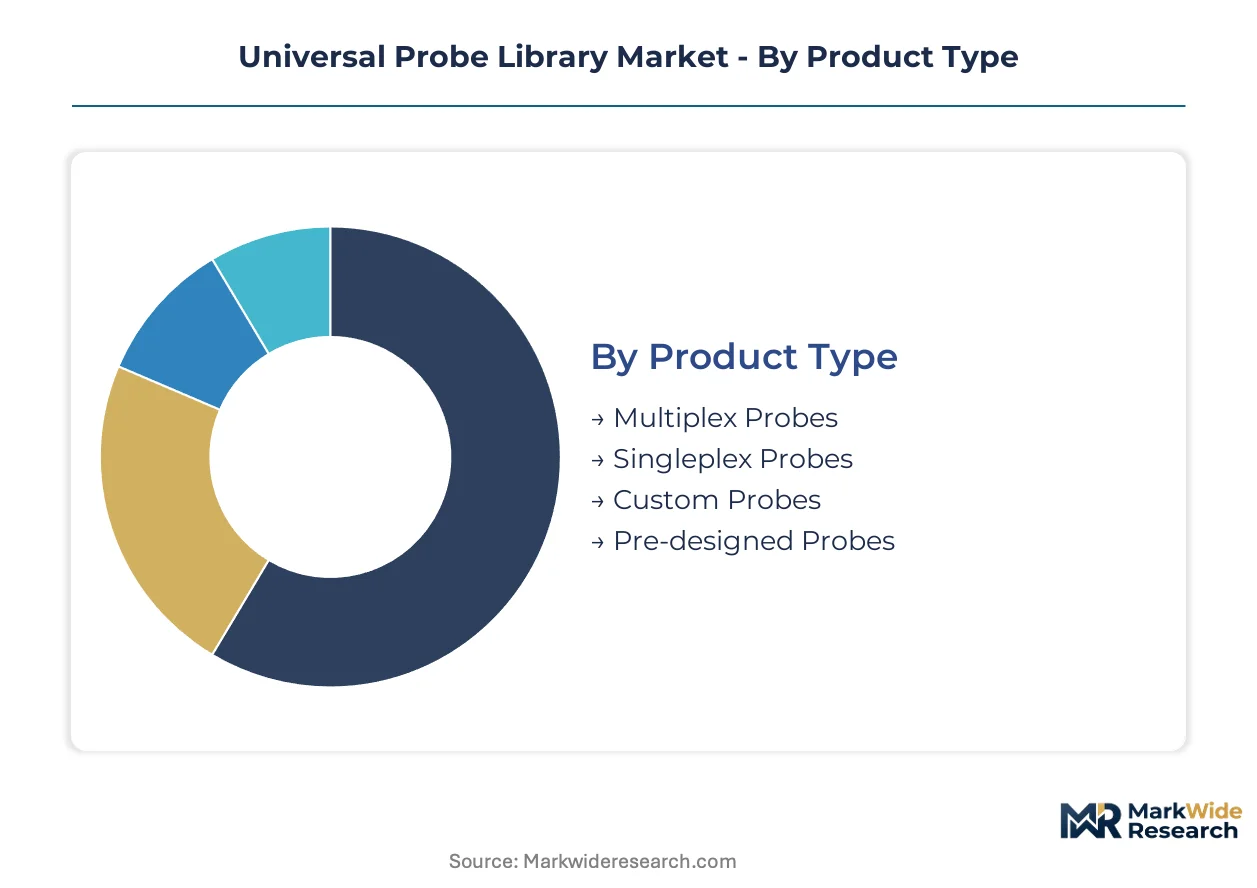
Probe library procurement patterns diverge sharply across research versus clinical workflows, with regulatory certification status determining price premiums and supplier eligibility. Pharmaceutical toxicology groups prioritize multiplex formats for high-throughput screening, while diagnostic laboratories demand pre-validated probe sets with established analytical performance files.
Product Type:
Phosphoramidite supply chains concentrate among three specialized chemical manufacturers, forcing probe producers to align product portfolios with synthesis batch economics and allocation priorities.
- Multiplex Probes:These configurations combine 4-6 labeled oligonucleotide pairs per reaction well, optimized for locked nucleic acid modifications that enhance thermal stability and single-mismatch discrimination. Demand concentrates in Germany's Rhine-Main biotech cluster, where contract research organizations are scaling qPCR workflows for pharmaceutical toxicology screening programs.
- Pre-designed Probes:Off-the-shelf reagent collections eliminate probe-design bottlenecks in gene-expression analysis and pathogen detection, featuring standardized fluorophore conjugates and validated hydrolysis architectures. Pharmaceutical companies are expanding procurement for companion diagnostic programs, compressing design-to-validation timelines and locking out smaller assay developers lacking ISO 13485 certification pathways.
- Singleplex Probes:Individual probe-target pairs serve specialized research applications requiring maximum customization flexibility.
- Custom Probes:Bespoke oligonucleotide synthesis accommodates novel transcriptome targets and proprietary assay architectures.
Multiplex probes absorb the bulk of installed capacity; pre-designed probes are expanding most quickly.
Application:
Margin structures vary substantially across research-funded versus reimbursement-backed workflows, with clinical diagnostic applications commanding price premiums tied to CE-IVD technical file investments.
- Diagnostic Testing:Circulating tumor DNA panels and infectious-disease rollouts require standardized probe sets that eliminate design variability across clinical sites. Liquid-biopsy assay development in the US and EU is absorbing probe libraries as consumable anchors, with turnaround time determining contract awards in reference laboratory networks.
- Genetic Research:Transcriptome quantification and gene-expression profiling drive volume demand from academic consortia and government-funded initiatives. Research laboratories in the US and Germany prioritize reaction-economy metrics across 384-well formats, favoring locked nucleic acid chemistry for thermal stability.
- Drug Development:Toxicology screening and pharmacogenomic biomarker validation create demand from pharmaceutical sponsors.
- Environmental Monitoring:EPA guidelines on nucleic acid detection in environmental matrices create ancillary demand channels outside human diagnostics.
Genetic research absorbs the bulk of installed capacity; diagnostic testing is gaining share fastest.
End User:
Procurement authority is shifting toward centralized purchasing functions as assay developers unbundle probe procurement from full kit sourcing.
- Pharmaceutical Companies:Companion diagnostic programs are consolidating probe procurement around pre-designed libraries, with toxicology groups deploying multiplex formats to compress reaction-economy metrics. REACH compliance costs are recalibrating supplier selection criteria for European research channels.
- Diagnostic Laboratories:Reference laboratories scaling liquid-biopsy test menus are establishing direct purchasing relationships with oligonucleotide suppliers. US-based operators are fragmenting vendor management overhead to compress per-reagent costs.
- Research Laboratories:Contract research organizations anchor demand in Germany's Rhine-Main cluster.
- Academic Institutions:Grant-funded investigators prioritize cost efficiency over certification status.
Research laboratories absorb the bulk of installed capacity; diagnostic laboratories are climbing the fastest.
Technology:
Platform integration requirements are reshaping probe design specifications, with absolute quantification workflows creating new placement channels.
- Real-time PCR:Quantitative amplification workflows dominate current installed base, with locked nucleic acid modifications enabling standardized pathogen detection and gene-expression analysis. Digital PCR platform integration is absorbing probe libraries as consumable anchors beyond traditional qPCR bases.
- Next-Generation Sequencing:Hybridization-capture workflows and amplicon-based target enrichment create demand for probe libraries with modified backbone chemistries. CRISPR-based diagnostic substitution is displacing probe-dependent approaches in certain research screening applications.
- Microarrays:Legacy transcriptome profiling platforms maintain steady replacement demand.
- In-Situ Hybridization:Tissue-based spatial transcriptomics applications require specialized probe architectures.
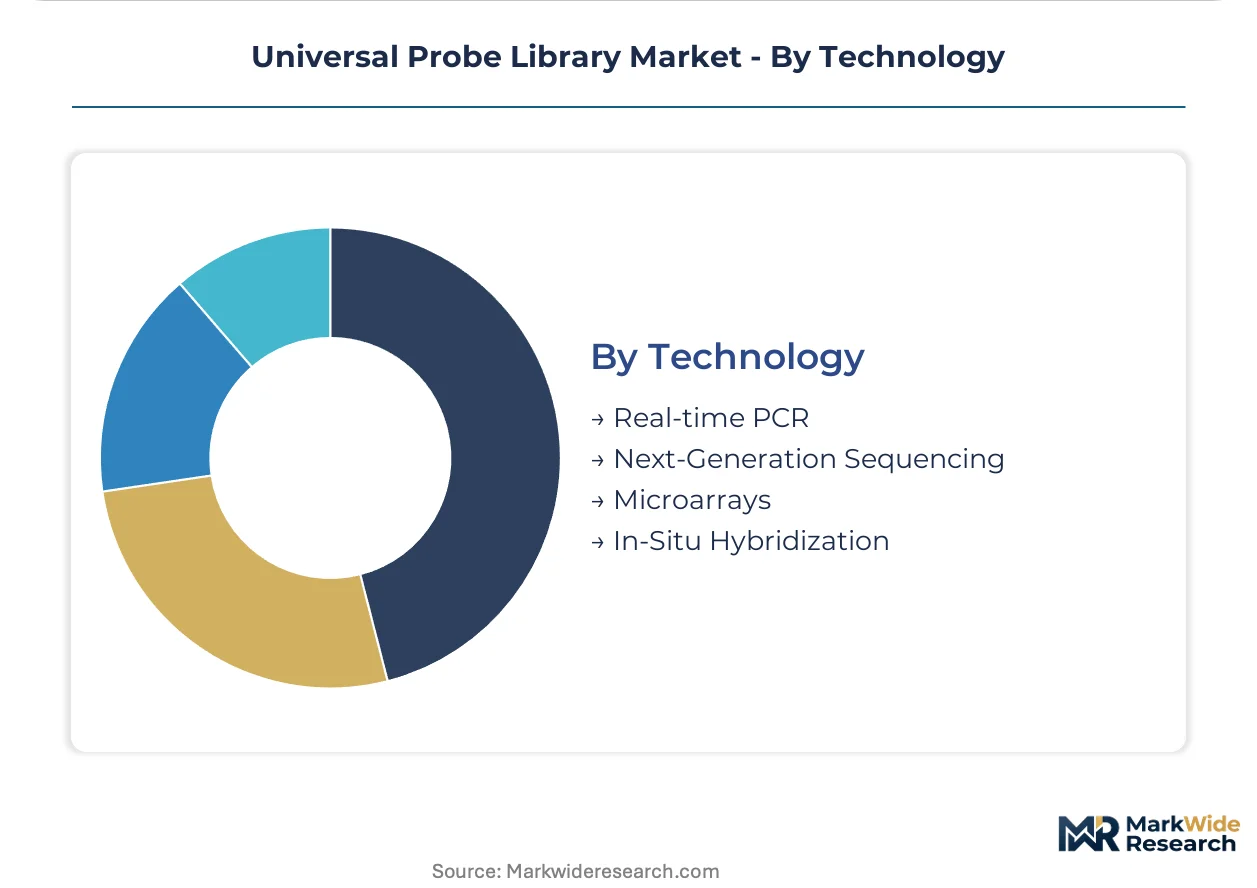
Real-time PCR absorbs the bulk of installed capacity; next-generation sequencing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main biotech cluster concentrates European probe library demand through contract research organization scaling and pharmaceutical toxicology screening programs.
United States
Liquid-biopsy assay development and circulating tumor DNA panel rollouts drive probe procurement from reference laboratories. FDA 510(k) pathways shape product-development timelines for clinical translation. The Greater Boston corridor anchors demand from academic medical centers and precision medicine consortia.
Germany
REACH compliance costs and ECHA substance registration obligations recalibrate supplier selection criteria for research channels. EU In Vitro Diagnostic Regulation tightens performance-documentation requirements for probe-based assays. The Rhine-Main cluster hosts contract research organizations scaling qPCR workflows for pharmaceutical toxicology.
China
Phosphoramidite supply chain concentration among specialized chemical manufacturers exposes probe producers to allocation constraints. NMPA regulatory frameworks for in vitro diagnostics create certification requirements for clinical-grade probe libraries. Yangtze River Delta biotech parks absorb multiplex probe demand from domestic pharmaceutical sponsors.
United Kingdom
Academic consortia and government-funded transcriptome initiatives sustain research-grade probe consumption. MHRA post-Brexit regulatory alignment with EMA IVD performance standards affects import certification. The Cambridge-Oxford-London golden triangle concentrates gene-expression profiling demand.
Japan
PMDA quality management system requirements for IVD reagents elevate documentation burdens for foreign suppliers. METI industrial biotechnology programs subsidize domestic probe manufacturing capacity. The Kanto region around Tokyo anchors pharmaceutical company companion diagnostic programs.
Universal Probe Library Market Competitive Landscape
German and Swiss producers anchor one tier through ISO 13485-certified infrastructure; US specialists hold another via CE-IVD technical file capabilities and FDA submission experience. The vendor base stratifies across three tiers: diversified life science conglomerates with end-to-end synthesis control, mid-scale reagent specialists with regional certification depth, and niche oligonucleotide houses serving custom design workflows. Dominant competitive moves include backward integration into phosphoramidite supply and strategic partnerships with digital PCR platform developers.
Within the diversified conglomerate tier, Roche Life Science and Thermo Fisher Scientific exemplify archetypes with captive oligonucleotide synthesis infrastructure. Qiagen occupies a position representing mid-scale specialists with notified body certification pathways. These three anchors illustrate how regulatory compliance capabilities, rather than chemistry alone, determine supplier eligibility for clinical procurement channels.
| Leading Market Players |
|---|
| Roche Life Science |
| Sigma-Aldrich |
| Biocompare |
| SABiosciences |
| Thermo Fisher Scientific |
| Qiagen |
| Takara |
| New England Biolabs |
| Applied Biosystems |
| Others |
Value Network & Pricing Analysis
Reference laboratories scaling liquid-biopsy test menus concentrate procurement authority and compress per-reagent costs through direct purchasing relationships, anchoring the dominant contract-based pricing model for high-volume probe library consumption.
Pricing Analysis
Short lead-time premiums apply to CE-IVD certified probe sets required for companion diagnostic programs facing 18-24 month notified body scrutiny timelines. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with diagnostic laboratories least price-sensitive due to reimbursement-backed workflows. Cost compression in research-grade multiplex probes is intensifying because assay developers unbundle procurement from full kit sourcing.
Supply Chain Analysis
Direct-to-diagnostic-laboratory channels handle high-volume demand from US reference networks, while distribution through specialized life science distributors serves mid-tier research institutions. Phosphoramidite synthesis concentrates in Germany, Switzerland, and the United States, with probe production drawing from locked nucleic acid modifications and fluorophore conjugates. Single-source vulnerability in phosphoramidite allocation exposes producers to price volatility from three specialized chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ISO 13485-certified infrastructure, with EU In Vitro Diagnostic Regulation compliance costs forcing smaller assay developers without notified body pathways toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into phosphoramidite supply and captive oligonucleotide synthesis infrastructure. Deepen CE-IVD technical file capabilities to defend against CRISPR-based diagnostic substitution threatening probe-dependent qPCR in research screening applications.
For New Entrants and Emerging Players: Launch via digital PCR platform integration partnerships targeting absolute quantification workflows beyond traditional qPCR installed bases. White-space opportunity concentrates in WHO prequalification procurement for tuberculosis and HIV viral-load assays across low-income country networks lacking in-house probe design capability.
For Investors and Strategic Acquirers: The window for entry favors mid-scale reagent specialists with regional certification depth and established notified body relationships. Acquisition target archetypes include niche oligonucleotide houses with proprietary locked nucleic acid chemistries. Watch FDA and EMA pharmacogenomic labeling convergence as the signal indicating probe-library design priority shifts toward CYP450 and pharmacodynamic gene panels.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Technical File Expansion | Notified body certification extends supplier eligibility for clinical procurement channels across EEA member states. |
| Phosphoramidite Backward Integration | In-house synthesis control insulates probe producers from allocation constraints and price volatility. |
| Digital PCR Platform Partnership | Absolute quantification workflows create consumable anchor placement beyond traditional qPCR bases. |
| WHO Prequalification Pursuit | Tuberculosis and HIV viral-load benchmarks extend addressable volume into low-income country procurement networks. |
| Pharmacogenomic Panel Development | FDA and EMA emerging requirements redirect design priorities toward clinically actionable variant coverage. |
Research Methodology
Document review covered FDA 510(k) filings, EMA IVD performance standards, and WHO prequalification benchmarks, complemented by interviews with oligonucleotide synthesis directors, diagnostic laboratory procurement managers, regulatory affairs leads at probe manufacturers, and contract research organization toxicology heads. Secondary sources included EU In Vitro Diagnostic Regulation technical documentation, REACH substance registration databases, and phosphoramidite supply chain trade data. Bottom-up segment sizing and top-down market triangulation validated volume estimates.
Segment-level projections across product type, application, end user, and technology dimensions informed value outputs across the analysis window. CAGRs were derived from regression analysis against qPCR and digital PCR platform installation trajectories, liquid-biopsy assay development pipelines, and companion diagnostic program expansion rates. Modeled inputs incorporated locked nucleic acid chemistry adoption curves and multiplex probe penetration by pharmaceutical toxicology screening programs.
Regulatory timeline delays, phosphoramidite supply allocation disruptions, and CRISPR-based diagnostic substitution acceleration are the dominant revision risks to base-case forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
ICP-OES Spectrometer Market