
 Network Analyzers Market | 2026-2036
Network Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Network Analyzers Market Foresight
Market Context
ISO/IEC 17025 accreditation is bifurcating the competitive landscape into certified laboratories and uncertified equipment vendors. Keysight Technologies leverages its in-house calibration traceability to sustain premium positioning across aerospace and defense accounts. Rohde & Schwarz anchors European demand through its Munich-based R&D and manufacturing footprint. Tektronix competes aggressively in the education segment with entry-level vector network analyzer portfolios.
Technical Definition and Segment Structure
Network analyzers are electronic test instruments that measure network parameters of electrical networks, typically operating across frequency ranges from kilohertz to terahertz using s-parameter characterization to quantify reflection and transmission coefficients. Rack-mounted units dominate telecommunications backbone deployments where continuous monitoring of fiber-optic and microwave infrastructure demands fixed-installation precision. Portable analyzers are gaining traction in field service applications where technicians require battery-operated signal analysis at 5G base stations and satellite ground terminals. Modular architectures from National Instruments and Copper Mountain Technologies allow users to reconfigure measurement channels through PXI or USB interfaces, concentrating margin pools in software-defined instrumentation ecosystems.
Regulatory Environment
FCC Part 15 equipment authorization rules in the United States and EU EMC Directive compliance requirements shape product design cycles, forcing manufacturers to pre-certify emission profiles before market release. Japan's METI technical standards for radio law conformity and China's MIIT network access licensing add parallel approval pathways for instruments targeting Asian manufacturing hubs. Stakeholders must monitor evolving 6G research band allocations and corresponding test specification drafts from IEEE and 3GPP working groups.
Market Dynamics
ISO/IEC 17025 accreditation requirements are compressing procurement timelines as defense contractors and automotive OEMs mandate traceable calibration chains, forcing vendors to restructure service architectures around certified metrology workflows.
Growth Catalysts
- 5G Infrastructure Deployment:Telecommunications carriers in Germany, Japan, and the United States are expanding base station rollouts, requiring continuous signal validation and s-parameter characterization for antenna arrays.
- FCC Part 15 Compliance:Equipment authorization rules mandate pre-certification emission testing, creating mandatory procurement cycles for RF component manufacturers supplying consumer electronics.
- Terahertz Research Expansion:Academic and government laboratories are investing in 6G prototype development, driving demand for vector network analyzers operating above 100 GHz.
Market Restraints
- Gallium Arsenide Substrate Costs:Precision microwave components depend on GaAs semiconductors, where supply concentrates among specialty foundries in Asia-Pacific, creating input price volatility.
- Calibration Labor Scarcity:Certified metrology engineers with traceable standards expertise are concentrated in Munich, Santa Rosa, and Tokyo, limiting service expansion.
- Modular Substitution Threat:USB-based and PXI instruments from software-defined vendors are capturing price-sensitive education and startup segments.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for electronics production are attracting test instrument procurement from contract manufacturers establishing local assembly.
- Automotive Radar Convergence:77-81 GHz frequency-modulated continuous-wave modules for ADAS require network analysis during design validation, opening automotive electronics workflows.
- Cloud-Connected Instrumentation:Remote calibration and measurement data streaming through secure enterprise networks enables subscription-based service models for distributed engineering teams.
Industry Challenges
- ISO/IEC 17025 Certification Timelines:Laboratory accreditation processes extend 12-18 months, delaying market entry for regional service providers.
- Legacy GPIB Integration Complexity:Aerospace and defense facilities maintain decades-old test stations, requiring backward-compatible interfaces that increase firmware development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Analyzers Market |
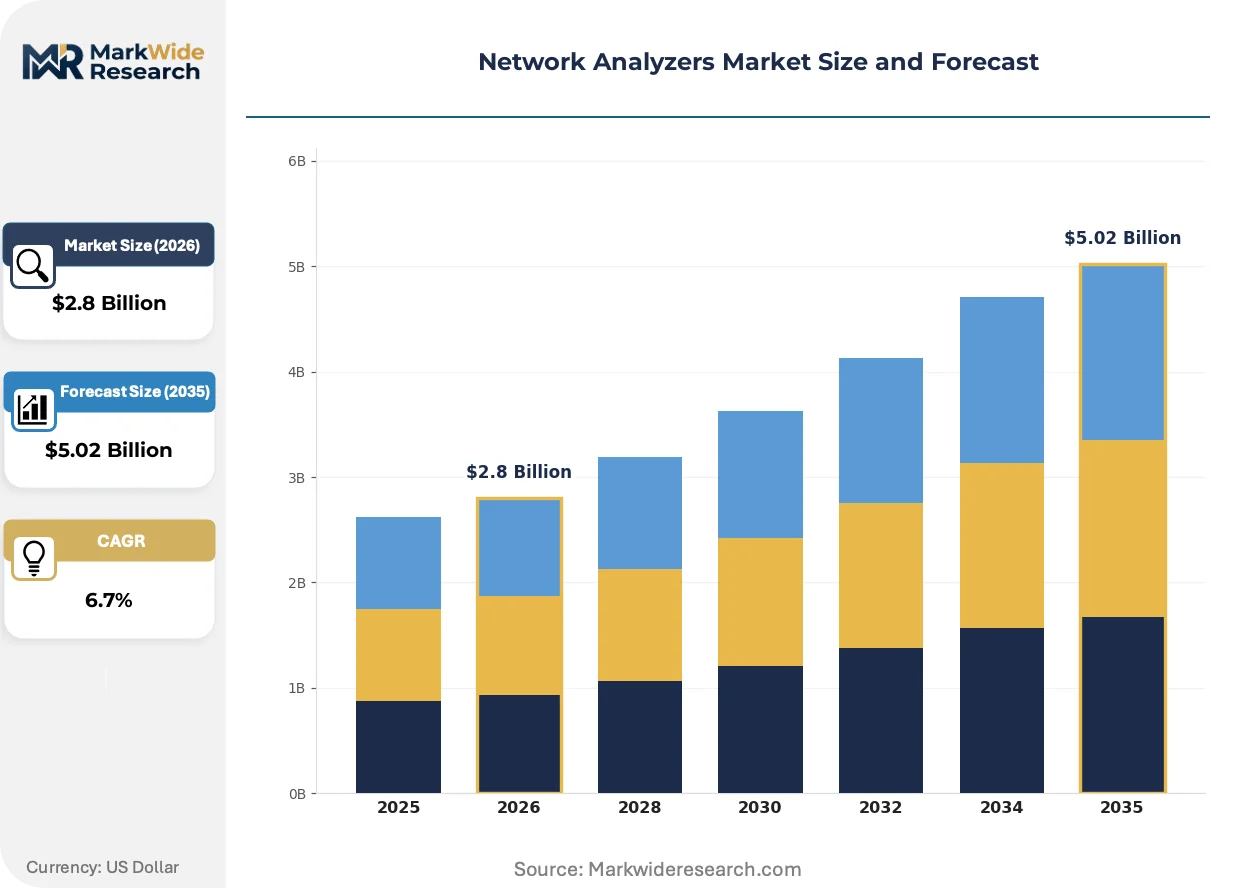
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Rack-mounted, Modular, Integrated Technology: Digital, Analog, Mixed Signal, Waveform End User: Telecommunications, IT Services, Government, Education Application: Network Monitoring, Signal Analysis, Troubleshooting, Performance Testing |
| Companies Covered | Tektronix, Transcom Instruments, Keysight Technologies, Advantest Corporation, Teledyne, Rohde & Schwarz, National Instruments, Copper Mountain Technologies, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Analyzers Market Shifts & Advancements
Software-defined architectures are dismantling traditional hardware-centric business models, redirecting value capture toward measurement automation platforms and analytics subscriptions rather than instrument sales alone.
Non-linear vector network analysis is bifurcating the high-frequency segment. This technology characterizes amplifier distortion and mixer intermodulation products under realistic drive conditions. Aerospace and defense primes in the United States and satellite manufacturers in Japan are adopting these capabilities for payload verification. The capability gap is bifurcating vendor tiers into those with native non-linear measurement engines and those dependent on external simulation tools.
EU EMC Directive 2014/30/EU enforcement is tightening emission test tolerances for industrial equipment. Manufacturers must now document measurement uncertainty budgets for conducted and radiated disturbance tests. Medical device and industrial automation producers in Germany and France are responding by upgrading to analyzers with built-in uncertainty calculation firmware, compressing upgrade cycles for mid-tier instrumentation.
Service unbundling is altering how enterprises acquire test capabilities. Large technology firms in California and Texas are separating hardware procurement from calibration and repair contracts, awarding multi-year service agreements to third-party metrology laboratories. This behavior concentrates instrument purchasing authority within centralized procurement functions while fragmenting aftermarket service relationships across specialized regional providers.
Network Analyzers Market Segmentation
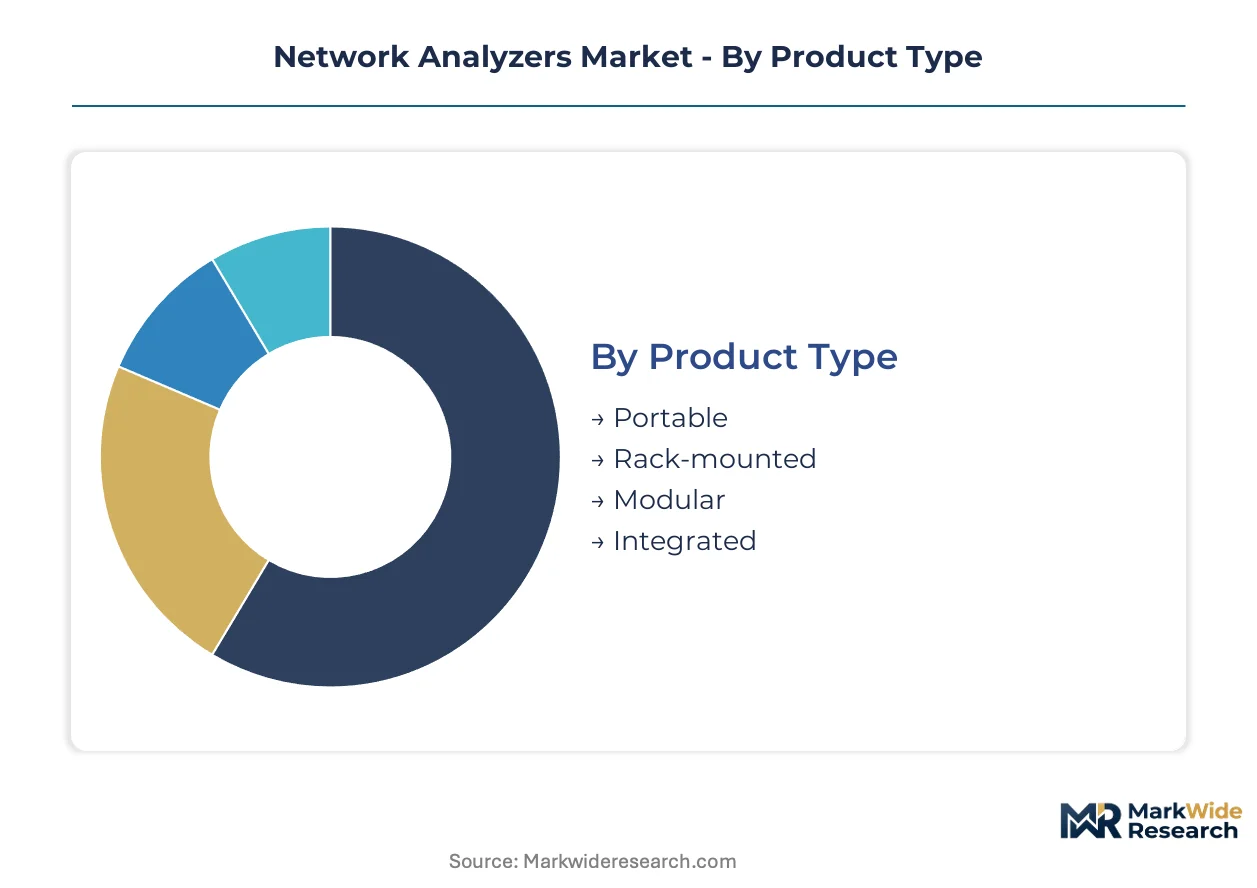
Network analyzer procurement patterns diverge sharply across installation environments, signal processing architectures, and compliance workflows. Understanding these segment boundaries reveals where ISO/IEC 17025 certification requirements concentrate and where modular substitution threatens incumbent hardware margins.
Product Type:
Rack-mounted units dominate export-led procurement cycles bound for telecommunications backbone deployments, while portable and modular formats serve domestic field service and education markets with shorter replacement cadences.
- Portable:Battery-operated instruments with integrated displays enable 5G base station commissioning and satellite ground terminal verification. Demand clusters with field service technicians in Germany and Japan where dense urban infrastructure requires rapid on-site s-parameter validation.
- Rack-mounted:Fixed-installation precision instruments with embedded cooling and redundant power supplies anchor continuous fiber-optic and microwave infrastructure monitoring. Telecommunications carriers in the United States deploy these for backbone signal integrity surveillance with 10-year amortization horizons.
- Modular:PXI and USB-interfaced architectures from National Instruments and Copper Mountain Technologies allow channel reconfiguration through software-defined ecosystems.
- Integrated:Combined test systems bundle network analysis with spectrum monitoring and power measurement for consolidated metrology workflows.
Rack-mounted holds the largest share; momentum sits with Modular formats capturing price-sensitive education and startup segments.
Technology:
Cost tier stratification separates premium digital architectures from analog legacy systems, with mixed-signal instruments occupying the mid-tier procurement band where defense contractors balance precision against upgrade budgets.
- Digital:FPGA-based signal processing engines with real-time s-parameter computation and embedded uncertainty calculation firmware. Aerospace primes in the United States specify these for payload verification where traceable calibration chains are mandatory.
- Analog:Traditional swept-frequency architectures using heterodyne conversion maintain presence in legacy test stations. Universities in Japan retain these for undergraduate laboratory instruction where capital constraints override performance requirements.
- Mixed Signal:Hybrid architectures combining analog front-ends with digital back-ends for intermediate performance tiers.
- Waveform:Arbitrary waveform generation capabilities for non-linear device characterization under realistic drive conditions.
Digital captures the premium tier; mixed-signal instruments are climbing fastest as automotive radar developers seek 77-81 GHz validation capabilities without full aerospace-grade specifications.
End User:
Customer type determines procurement authority concentration, with government and telecommunications accounts centralizing purchasing through dedicated metrology procurement functions while education and IT services fragment across departmental budgets.
- Telecommunications:Carrier procurement departments mandate ISO/IEC 17025 traceable calibration for all base station validation equipment. Verizon, Deutsche Telekom, and NTT maintain approved vendor lists restricting sourcing to accredited laboratories.
- Government:Defense contractors and national metrology institutes operate under procurement regulations requiring domestic content preferences and security-cleared service personnel.
- IT Services:Data center operators and cloud infrastructure providers purchase network analyzers for fiber-optic link certification.
- Education:Universities and technical colleges prioritize USB-based and entry-level vector instruments for student laboratory access.
Telecommunications holds the largest share; momentum sits with Government accounts as 6G research programs expand terahertz-frequency instrumentation budgets.
Application:
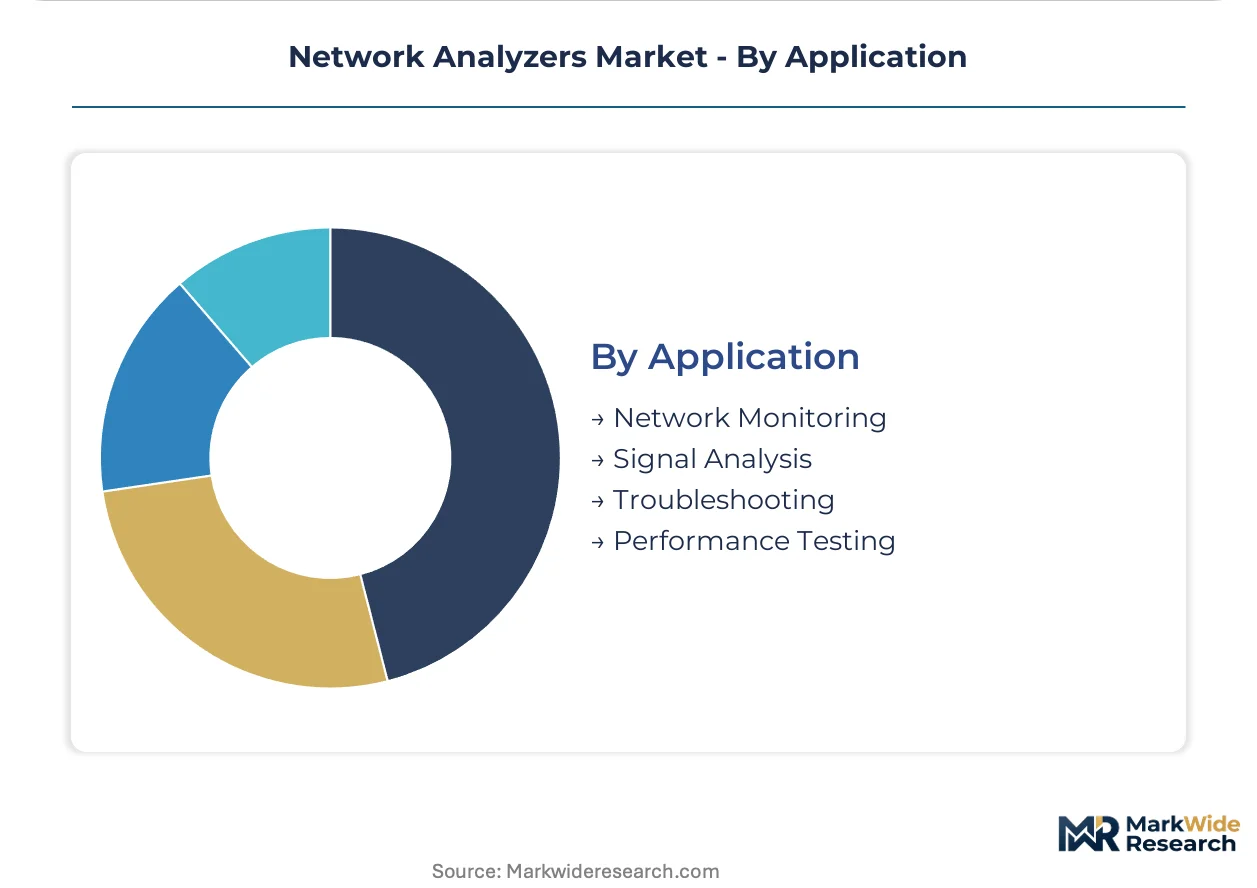
Maturity gradients separate established network monitoring workflows from emerging performance testing protocols, with signal analysis and troubleshooting occupying intermediate adoption phases across industrial and automotive verticals.
- Network Monitoring:Continuous surveillance of fiber-optic and microwave infrastructure for degradation detection and preventive maintenance. German industrial automation producers deploy these for production line communication link verification.
- Signal Analysis:Characterization of modulation quality, harmonic distortion, and spurious emissions for RF component validation. Japanese automotive electronics suppliers use these for 77-81 GHz radar module design verification.
- Troubleshooting:Fault isolation in distributed antenna systems and cable plant infrastructure.
- Performance Testing:Compliance verification against FCC Part 15 and EU EMC Directive emission limits.
Network Monitoring holds the largest share; performance testing is expanding most quickly as pre-certification requirements tighten for consumer electronics manufacturers supplying European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and telecommunications carriers concentrate procurement authority in Germany, the United States, and Japan, where precision manufacturing clusters anchor metrology investment cycles and ISO/IEC 17025 accreditation requirements.
United States
Aerospace primes and 5G infrastructure deployers drive demand for rack-mounted precision instruments. FCC Part 15 equipment authorization rules mandate pre-certification emission testing, compressing procurement timelines for RF component manufacturers. Santa Rosa, California hosts concentrated calibration expertise serving defense accounts with traceable metrology chains.
Germany
Industrial automation producers and automotive radar developers seek 77-81 GHz validation capabilities for ADAS module design. EU EMC Directive 2014/30/EU enforcement tightens emission test tolerances, forcing documentation of measurement uncertainty budgets. Munich anchors European R&D and manufacturing footprints for precision instrument vendors.
Japan
Satellite manufacturers and automotive electronics suppliers invest in terahertz-frequency instrumentation for 6G prototype development. METI technical standards for radio law conformity shape product design cycles for instruments targeting Asian manufacturing hubs. Tokyo concentrates certified metrology engineers with traceable standards expertise.
China
Contract manufacturers establishing local electronics assembly under MIIT network access licensing drive procurement of validation equipment. Dual carbon goals and domestic semiconductor self-sufficiency programs redirect investment toward captive test capabilities. Yangtze River Delta industrial clusters absorb modular instrumentation for production line integration.
India
Electronics manufacturing services firms expanding under PLI scheme subsidies generate procurement for contract manufacturers. TRAI spectrum allocation frameworks for 5G deployment create parallel demand for base station validation instruments. Karnataka and Tamil Nadu host emerging precision manufacturing clusters requiring localized calibration services.
Network Analyzers Market Competitive Landscape
Player mix skews toward diversified electronic test and measurement conglomerates with in-house calibration traceability. Market structure concentrates around three strategic archetypes: premium-tier precision instrument vendors leveraging accredited laboratory networks, modular architecture specialists capturing price-sensitive segments through software-defined ecosystems, and regional service providers fragmenting aftermarket relationships. Dominant competitive moves include vertical integration into calibration services and geographic expansion through certified metrology partnerships.
Within the premium-tier precision segment, Keysight Technologies and Rohde & Schwarz exemplify archetypes anchored by in-house traceability and regional R&D footprints. Tektronix occupies a position representing aggressive education-segment competition through entry-level portfolio strategies. National Instruments and Copper Mountain Technologies sit within the modular substitution tier, capturing momentum in software-defined instrumentation ecosystems through PXI and USB-interfaced architectures.
| Leading Market Players |
|---|
| Tektronix |
| Transcom Instruments |
| Keysight Technologies |
| Advantest Corporation |
| Teledyne |
| Rohde & Schwarz |
| National Instruments |
| Copper Mountain Technologies |
| Anritsu Corporation |
| Others |
Supply & Pricing Matrix
USB-based modular architectures displacing rack-mounted precision instruments are simultaneously redrawing supply geography toward software-defined ecosystems and compressing pricing premiums in education and startup segments where buyers prioritize reconfigurability over traceable calibration chains.
Pricing Analysis
Cost-plus contracts with gallium arsenide substrate indexation dominate procurement for aerospace-grade instruments, embedding raw material volatility directly into final equipment pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 17025-certified laboratories from uncertified vendors and entry-level education suppliers. Price differentiation hinges on calibration traceability depth and domestic content compliance. Cost compression in mid-tier mixed-signal instruments is intensifying because automotive radar developers seek 77-81 GHz capabilities without full aerospace specifications. Education buyers exhibit highest price sensitivity, while defense contractors prioritize traceable metrology chains regardless of premium.
Supply Chain Analysis
Strait of Malacca transit underwrites precision microwave component flows from Asian specialty foundries to German and United States assembly facilities. Manufacturing concentrates in China, Japan, and South Korea for GaAs semiconductors, FPGA signal processors, and precision connectors. Raw material dependencies span gallium arsenide substrates, high-frequency PCB laminates, and cryogenic cooling systems. Single-source vulnerability concentrates in specialty foundry capacity for sub-6 GHz and terahertz-grade components. Distribution runs through authorized metrology laboratories and direct OEM channels to telecommunications carriers and defense primes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent instrument vendors face a substitution defense against software-defined modular architectures that threaten hardware-centric revenue models through reconfigurable measurement platforms.
For Market Incumbents: Shield premium positioning by deepening backward integration into accredited calibration services and captive GaAs semiconductor sourcing. ISO/IEC 17025 certification timelines extending 12-18 months create defensive moats against uncertified competitors. Prioritize Munich, Santa Rosa, and Tokyo service hub expansion to address certified metrology engineer scarcity. For New Entrants and Emerging Players: Cloud-connected calibration service gaps where incumbents under-serve distributed engineering teams offer white-space entry points. Target India's PLI-subsidized contract manufacturers establishing localized test capabilities with USB-interfaced entry portfolios. Pursue subscription-based remote calibration partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular architecture specialists holding software-defined instrumentation platforms. Five-to-ten-year viability hinges on capturing automotive radar validation workflows before incumbent precision vendors adapt pricing downward. Monitor 6G research band allocation announcements from IEEE and 3GPP as the signal indicating terahertz instrumentation budget inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | ISO/IEC 17025 accreditation locks in defense and telecommunications accounts requiring traceable metrology chains. |
| GaAs Semiconductor Backward Integration | Captive substrate supply insulates pricing from Asian specialty foundry volatility and allocation risk. |
| Automotive Radar Validation Portfolio | 77-81 GHz capability capture opens ADAS module design workflows at German and Japanese automotive electronics suppliers. |
| Cloud-Connected Instrumentation Platform | Remote measurement data streaming enables subscription revenue models for distributed California and Texas engineering teams. |
| India Manufacturing Localization | PLI scheme alignment positions vendors for contract manufacturer procurement in Karnataka and Tamil Nadu clusters. |
Research Methodology
A spread of perspectives from test and measurement procurement officers, certified metrology laboratory directors, semiconductor foundry planning leads, and telecommunications carrier network engineers converged on the working assumptions shaping demand forecasts. Primary field engagement combined with secondary validation from FCC equipment authorization databases, EU EMC Directive compliance filings, SEC 10-K instrument segment disclosures, and customs trade data for RF test equipment. Bottom-up channel checks across PXI and USB modular vendors triangulated against top-down telecommunications capex projections.
Segmentation dimensions modeled include product type, signal processing architecture, end-user procurement authority concentration, and application maturity gradient across the analysis window. CAGRs derived from instrument shipment volumes weighted by average selling price tiers and replacement cycle assumptions. Forecast inputs incorporated 5G base station rollout schedules, 6G research funding trajectories, and automotive radar module production ramps.
Forecasts assume regulatory continuity in FCC Part 15 equipment authorization rules and EU EMC Directive enforcement regimes; material policy shifts would require re-modeling emission testing mandate timelines. Practitioners should keep alternative scenarios live as 6G spectrum allocation decisions and GaAs substrate supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Laser-Based Gas Analyzers Market