
 Dioxin Analyzer Market | 2026-2036
Dioxin Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Dioxin Analyzer Market Analysis
A shortage of certified chromatography technicians is unwinding laboratory expansion timelines across the environmental monitoring sector. Thermo Fisher Scientific leverages its installed base of high-resolution MS platforms to sustain service contract renewal rates above industry norms. Agilent Technologies competes through modular benchtop architectures that reduce operator training burdens. Shimadzu Corporation anchors its position in East Asian municipal procurement through localized application support centers.
Dioxin analyzers are precision instruments that quantify polychlorinated dibenzo-p-dioxins and dibenzofurans at parts-per-trillion detection thresholds, typically employing magnetic-sector mass spectrometry coupled with gas chromatography separation to meet EPA Method 23 and EN 1948 protocol requirements. Benchtop analyzers occupy the core revenue pool given their dominance in permanent laboratory installations, while portable analyzers are gaining traction in emergency response and field screening applications where rapid deployment outweighs absolute sensitivity. Automated systems command premium positioning by integrating robotic sample prep with unattended overnight runs, reducing labor intensity for high-throughput food safety and industrial waste compliance programs.
EPA Method 23 and the Stockholm Convention on Persistent Organic Pollutants shape product specifications by mandating isomer-specific quantification and rigorous quality assurance protocols that exclude lower-resolution detection technologies. The EU Industrial Emissions Directive and associated EN 1948 standards enforce continuous stack monitoring obligations that sustain replacement demand across European incineration infrastructure. Stakeholders must weigh capital deployment toward portable platforms against the enduring compliance pull of laboratory-grade systems as regulatory enforcement intensifies in emerging monitoring jurisdictions.
Market Dynamics
Magnetic-sector mass spectrometry platforms face displacement pressure from quadrupole time-of-flight architectures as municipal incinerators seek faster turnaround times without sacrificing EPA Method 23 compliance. This technology tension is compressing replacement cycles and forcing vendors to reconfigure service contract structures.
Growth Catalysts
- Stockholm Convention enforcement:National emission ceilings in Japan and Germany mandate continuous stack monitoring, forcing incinerator operators to expand analyzer fleets and upgrade to isomer-specific detection capabilities.
- Food safety protocols:Automated sample preparation systems reduce labor intensity for high-throughput laboratories processing imported agricultural commodities under tightening residue limits.
- East Asian municipal procurement:Localized application support centers in China and South Korea accelerate installation timelines and reduce operator certification bottlenecks for new incineration infrastructure.
Market Restraints
- Helium supply volatility:Gas chromatography carrier gas costs fluctuate with semiconductor industry demand, squeezing operating margins for laboratories running continuous monitoring protocols.
- Technician certification scarcity:Magnetic-sector maintenance requires specialized training that fewer technical institutes provide, extending downtime windows for instrument failures.
- Portable sensitivity gap:Field-deployable units cannot achieve parts-per-trillion detection thresholds required for definitive regulatory enforcement, limiting their addressable market to screening applications.
Strategic Opportunities
- Indian environmental monitoring expansion:Central Pollution Control Board mandates for dioxin monitoring at medical waste incinerators create first-mover advantages for vendors establishing local service networks.
- Robotic sample prep convergence:Integration of automated extraction systems with high-resolution mass spectrometry enables overnight unattended operation, capturing demand from understaffed public laboratories.
- EU Industrial Emissions Directive:Continuous monitoring obligations across Eastern European incineration infrastructure sustain replacement demand as legacy systems age out of EN 1948 compliance windows.
Industry Challenges
- Chromatography technician shortage:Laboratory expansion timelines unwind across the environmental monitoring sector as certified personnel pools fail to match instrument deployment rates.
- Method validation complexity:EPA Method 23 and EN 1948 protocol updates require extensive recertification of existing installations, freezing procurement decisions during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dioxin Analyzer Market |
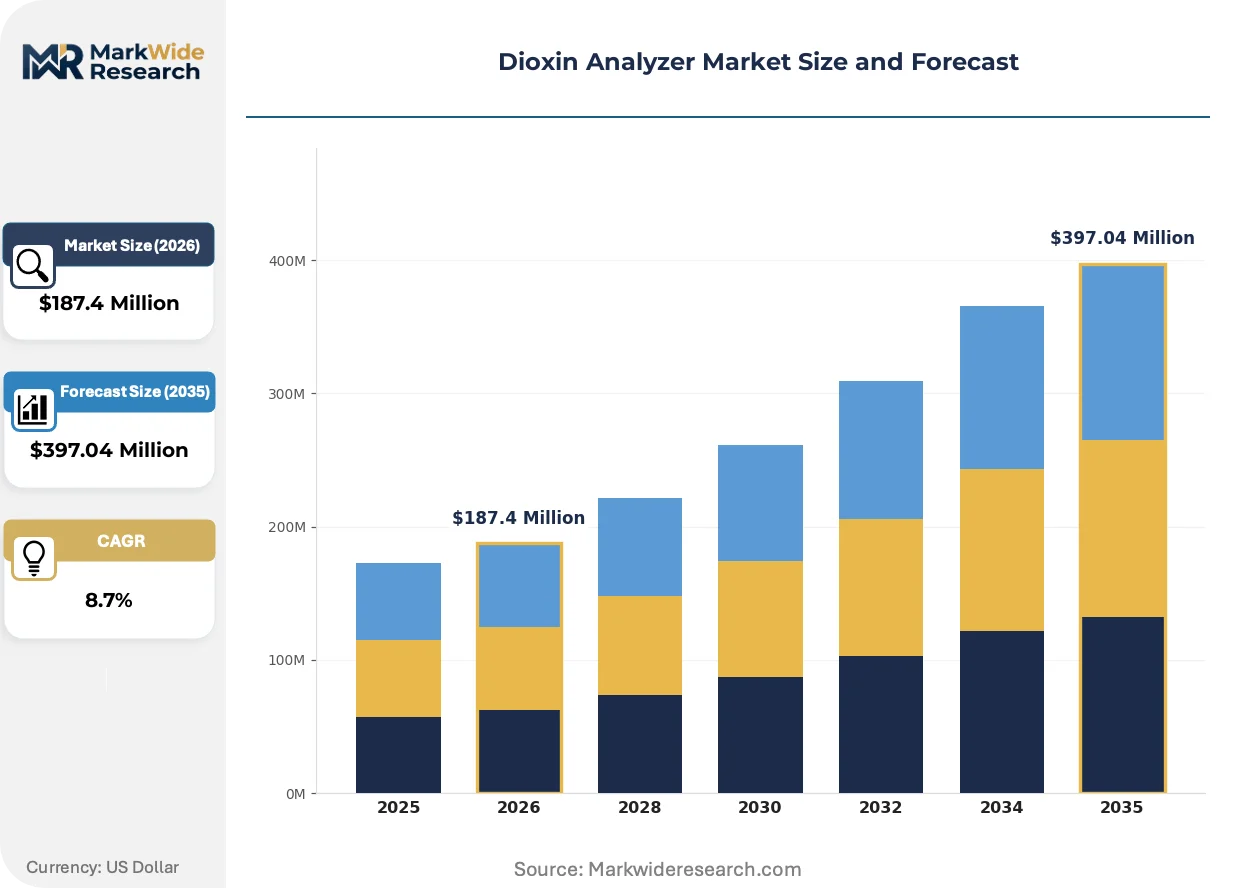
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Automated Systems, Lab Equipment Application: Environmental Testing, Food Safety, Water Quality, Industrial Waste Technology: Gas Chromatography, Mass Spectrometry, Immunoassays, HPLC End User: Government Agencies, Research Institutions, Environmental Organizations, Manufacturing Facilities |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Shimadzu Corporation, Bruker Corporation, Hitachi High-Tech Corporation, JEOL Ltd., AB Sciex, Gasmet Technologies, Analytik Jena AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dioxin Analyzer Market Emerging Trajectories
Analyzer architectures are splitting into two distinct performance tiers as buyer requirements diverge between regulatory enforcement and rapid field screening. This bifurcation is reshaping vendor R&D allocation and service model design across the supply base.
Benchtop magnetic-sector systems is bifurcating the installed base into high-sensitivity permanent laboratories and portable screening units with degraded detection thresholds. Municipal incinerators in Germany and Japan prioritize the former for definitive compliance documentation, while emergency response teams in the United States adopt the latter for rapid deployment scenarios. This split is compressing mid-range product development budgets as vendors commit to distinct technical roadmaps.
EPA Method 23 revisions are tightening quality assurance protocols for isomer-specific quantification, excluding lower-resolution detection technologies from definitive enforcement applications. The industrial consequence is accelerated replacement of aging quadrupole systems in United States environmental laboratories. Food safety testing facilities face the steepest compliance recertification burdens as they simultaneously process imports under multiple national residue limits.
After-sales service unbundling is separating hardware warranties from consumables and preventive maintenance contracts, allowing cash-constrained municipal laboratories to phase investment commitments. Direct manufacturer channels are displacing traditional distribution intermediaries for high-end installations requiring specialized field engineering. This pattern is most visible in Japanese municipal procurement, where METI procurement guidelines favor transparent lifecycle cost accounting over upfront capital minimization.
Dioxin Analyzer Market Segmentation
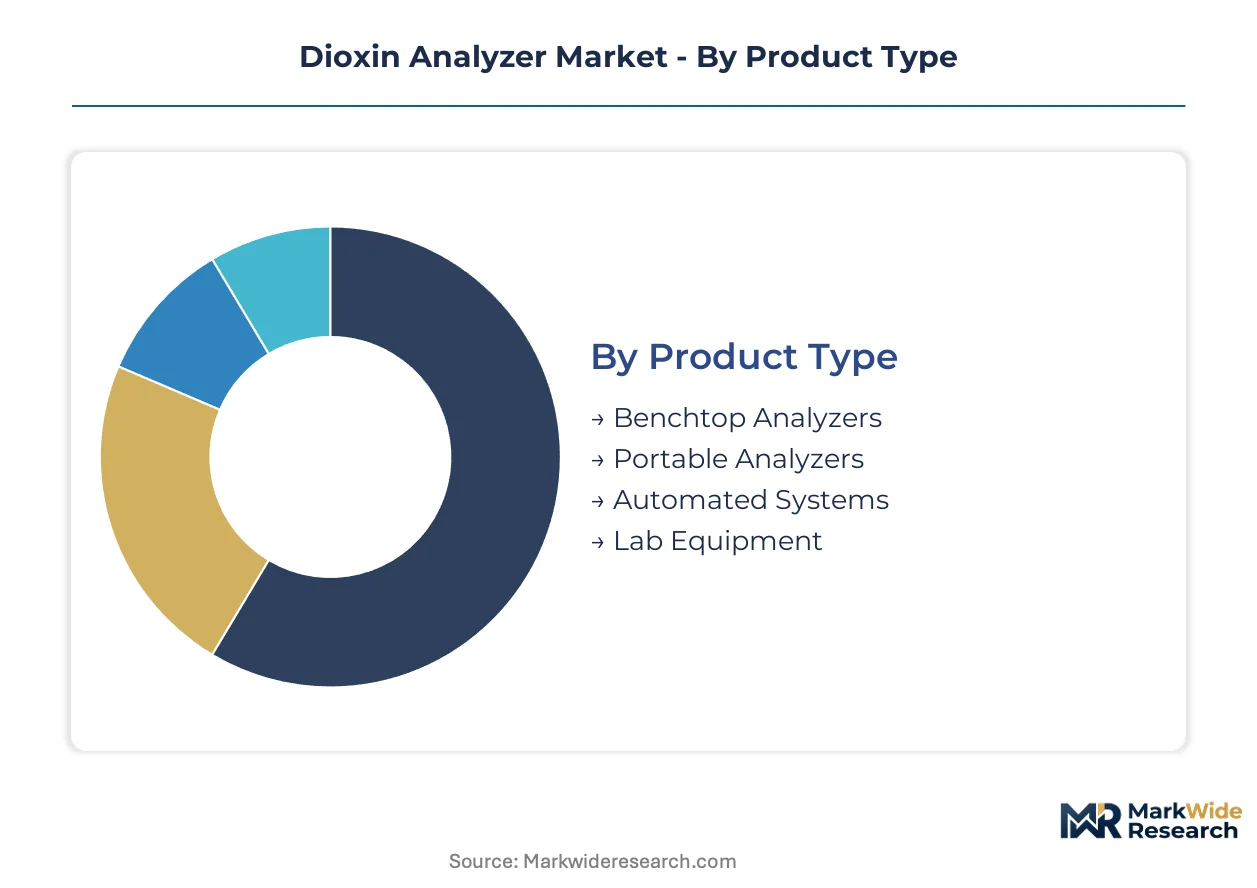
Dioxin analyzer procurement patterns diverge sharply between permanent laboratory installations and mobile screening units, with technology choices further stratified by regulatory compliance tier. Understanding these segment boundaries clarifies why vendor R&D budgets concentrate on magnetic-sector platforms while portable units serve adjacent screening markets.
Product Type:
Domestic procurement dominates benchtop and automated system sales in Japan and Germany, while portable analyzers see stronger export-led demand from emergency response agencies across multiple jurisdictions.
- Benchtop Analyzers:Magnetic-sector mass spectrometry platforms deliver parts-per-trillion detection thresholds required for EPA Method 23 and EN 1948 definitive compliance documentation. Municipal incinerator operators in Germany and Japan anchor procurement volumes as national emission ceilings tighten under Stockholm Convention enforcement timelines.
- Automated Systems:Robotic sample preparation modules integrate with high-resolution mass spectrometry for unattended overnight operation, reducing labor intensity for understaffed public laboratories. Food safety facilities processing imported agricultural commodities under tightening residue limits drive replacement cycles in this segment.
- Portable Analyzers:Field-deployable units sacrifice absolute sensitivity for rapid deployment capability, serving emergency response teams and preliminary screening applications where speed outweighs regulatory defensibility.
- Lab Equipment:Ancillary chromatography infrastructure and sample handling systems support permanent installation bases, with procurement tied to expansion timelines rather than replacement cycles.
Benchtop analyzers hold the largest share; momentum sits with automated systems as labor scarcity intensifies across environmental monitoring laboratories.
Application:
Cost tier differentiation separates high-throughput commercial testing from capital-constrained municipal monitoring programs.
- Environmental Testing:Continuous stack monitoring at municipal incinerators demands isomer-specific quantification capabilities that exclude lower-resolution detection technologies. EPA Method 23 compliance mandates in the United States and EN 1948 obligations across European Union member states sustain replacement demand.
- Food Safety:Automated extraction systems reduce technician burden for laboratories processing imported commodities under multiple national residue limit regimes. The steepest compliance recertification burdens fall on facilities simultaneously meeting FDA, EFSA, and Japan Ministry of Health standards.
- Water Quality:Drinking water and wastewater surveillance programs require detection thresholds below regulatory action limits, favoring permanent laboratory installations over field screening approaches.
- Industrial Waste:Hazardous waste characterization and disposal facility compliance monitoring generate intermittent high-value contracts rather than continuous procurement streams.
Environmental testing commands the dominant revenue pool; food safety applications are climbing the fastest as import surveillance regimes expand.
Technology:
Volume concentration favors mature chromatography platforms, while emerging methods challenge incumbent positioning in specific screening niches.
- Gas Chromatography:Capillary column separation coupled with high-resolution detection remains the analytical backbone for regulatory enforcement applications. Helium carrier gas supply volatility tied to semiconductor industry demand creates operating margin pressure for continuous monitoring protocols.
- Mass Spectrometry:Magnetic-sector platforms face displacement pressure from quadrupole time-of-flight architectures as municipal operators seek faster turnaround times without sacrificing compliance defensibility.
- Immunoassays:Antibody-based screening methods offer cost advantages for preliminary field assessment where definitive quantification is not required.
- HPLC:Liquid chromatography approaches serve specialized applications where thermal lability of target compounds precludes gas-phase separation.
Mass spectrometry anchors the technology mix; quadrupole time-of-flight configurations are gaining share fastest as replacement cycles compress.
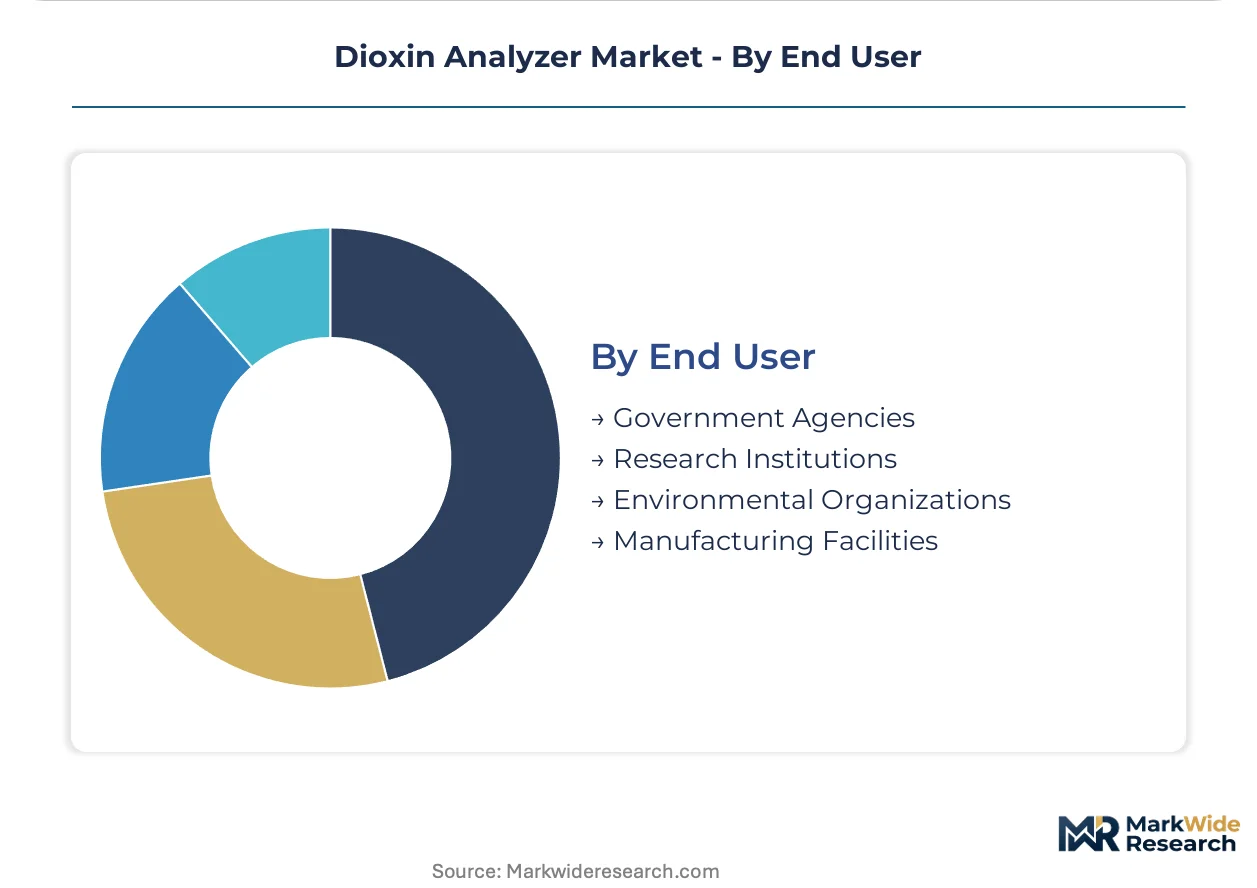
End User:
Customer type stratification separates procurement authority between regulatory enforcement agencies and commercial testing enterprises.
- Government Agencies:Central Pollution Control Board mandates for dioxin monitoring at medical waste incinerators in India create first-mover advantages for vendors establishing local service networks. METI procurement guidelines in Japan favor transparent lifecycle cost accounting over upfront capital minimization.
- Research Institutions:Academic and government laboratory procurement emphasizes methodological flexibility and publication-grade data quality rather than high-throughput processing.
- Environmental Organizations:Non-governmental monitoring programs operate with constrained budgets, favoring service contract unbundling and phased investment commitments.
- Manufacturing Facilities:Industrial self-monitoring programs prioritize rapid turnaround for process control over definitive regulatory documentation.
Government agencies represent the largest installed base; research institutions show the steepest expansion trajectory as environmental toxicology funding increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German procurement channels where METI and federal emission ceilings mandate premium-tier compliance systems, while Indian medical waste monitoring programs operate under tighter capital constraints that favor phased service contract structures.
United States
EPA Method 23 compliance mandates drive replacement cycles for aging quadrupole systems in environmental laboratories. The EPA's quality assurance protocol revisions exclude lower-resolution detection technologies from definitive enforcement applications. Houston and Detroit industrial corridors sustain demand for continuous stack monitoring infrastructure at hazardous waste facilities.
Germany
Federal emission ceilings under Stockholm Convention enforcement compel municipal incinerator operators to expand analyzer fleets. The Industrial Emissions Directive and EN 1948 standards enforce continuous monitoring obligations across aging incineration infrastructure. The Ruhr industrial cluster and Bavarian waste-to-energy facilities anchor procurement volumes for high-resolution magnetic-sector platforms.
Japan
METI procurement guidelines favor transparent lifecycle cost accounting over upfront capital minimization for municipal installations. National emission ceilings tighten analyzer replacement timelines for incinerator operators in Tokyo and Osaka metropolitan areas. Localized application support centers accelerate installation timelines and reduce operator certification bottlenecks.
India
Central Pollution Control Board mandates for dioxin monitoring at medical waste incinerators create first-mover advantages for vendors establishing local service networks. The country's environmental regulator enforces new compliance windows for healthcare waste disposal facilities. Delhi-NCR and Maharashtra medical waste clusters drive initial procurement waves for benchtop systems.
China
Municipal incineration infrastructure expansion in Yangtze River Delta and Pearl River Delta regions generates demand for automated sample preparation systems. The Ministry of Ecology and Environment tightens emission surveillance protocols for waste-to-energy facilities. Localized service networks from East Asian vendors capture procurement share through reduced installation timelines.
Dioxin Analyzer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where magnetic-sector specialists command premium positioning while modular benchtop vendors compete on operator training efficiency. The installed base splits between high-sensitivity permanent laboratory systems and portable screening units with degraded detection thresholds. Two strategic archetypes dominate: integrated analytical platform providers with deep service contract penetration, and specialized chromatography houses with regional application support density. Competitive moves concentrate on geographic service network expansion and robotic sample preparation integration partnerships.
Among integrated platform providers, Thermo Fisher Scientific and Agilent Technologies occupy positions at opposite ends of the service-model spectrum. Thermo Fisher leverages its installed base of high-resolution mass spectrometry platforms to sustain above-norm service contract renewal rates. Agilent competes through modular architectures that reduce operator training burdens for understaffed municipal laboratories. Shimadzu Corporation anchors the East Asian procurement channel through localized application support centers in China and South Korea.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Shimadzu Corporation |
| Bruker Corporation |
| Hitachi High-Tech Corporation |
| JEOL Ltd. |
| AB Sciex |
| Gasmet Technologies |
| Analytik Jena AG |
| Others |
Supply Flow & Price Mechanics
Helium-to-hydrogen carrier gas substitution in gas chromatography systems is simultaneously redrawing procurement geography toward hydrogen infrastructure clusters and compressing operating cost differentials between high-throughput laboratories and constrained municipal facilities. This input shift feeds back into vendor pricing strategies as service contract structures absorb fuel volatility risk.
Pricing Analysis
Configured-to-order magnetic-sector systems command spreads exceeding standard benchtop configurations by integrating robotic sample preparation modules and extended warranty terms. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection threshold capability and EN 1948 certification grade. Pricing pressure stems from quadrupole time-of-flight displacement as municipal incinerators prioritize faster turnaround over absolute sensitivity. Government agencies exhibit lowest price sensitivity due to METI lifecycle cost accounting mandates, while environmental organizations face acute budget constraints favoring unbundled service contracts.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing of magnetic-sector mass spectrometry components, while the United States concentrates high-resolution detection electronics production. Critical inputs encompass superconducting magnets, specialized capillary columns, and helium carrier gas reserves. Single-source vulnerability in superconducting magnet fabrication creates procurement risk for laboratories facing Stockholm Convention compliance deadlines. Distribution runs through direct manufacturer channels for high-end installations requiring specialized field engineering, displacing traditional distribution intermediaries in Japanese municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dioxin analyzer market sits at a platform-economics inflection where robotic sample preparation convergence with high-resolution mass spectrometry creates ecosystem lock-in effects, rewarding vendors who integrate unattended operation workflows before competitors achieve interoperability scale.
For Market Incumbents: Secure service contract renewal rates through predictive maintenance telemetry integration, countering quadrupole time-of-flight displacement pressure from Agilent's modular architectures. Deepen backward integration into superconducting magnet supply to insulate against single-source fabrication bottlenecks extending downtime windows for magnetic-sector failures. For New Entrants and Emerging Players: Differentiate on portable screening unit sensitivity gaps, targeting emergency response agencies in the United States where rapid deployment outweighs regulatory defensibility. Penetrate India's medical waste incinerator monitoring wave through localized service network partnerships with Central Pollution Control Board mandate timelines, leveraging phased investment commitments to bypass incumbent installed base advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated analytical platform providers with deep service contract penetration over specialized chromatography houses lacking geographic density. Long-term viability hinges on robotic sample prep integration capabilities and EN 1948 recertification navigation expertise. Watch quadrupole time-of-flight share gains in German municipal procurement as inflection signal for magnetic-sector displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Sample Prep Integration | Unattended overnight operation captures demand from understaffed public laboratories facing technician certification scarcity. |
| Localized Service Network Expansion | Application support centers in China and South Korea accelerate installation timelines for East Asian municipal procurement. |
| Quadrupole Time-of-Flight Platform Development | Faster turnaround times without EPA Method 23 compliance sacrifice compress replacement cycles against magnetic-sector incumbents. |
| Helium Independence Investment | Hydrogen carrier gas compatibility insulates operating margins from semiconductor industry demand volatility. |
| Service Contract Unbundling | Separating hardware warranties from preventive maintenance allows cash-constrained municipal laboratories to phase commitments. |
Methodological Framework
Cross-validation between regulatory filing analysis and instrument procurement database tracking anchors the qualitative findings in this study. Primary interviews with environmental laboratory directors, chromatography technicians, municipal incinerator operators, and EPA compliance officers combined with secondary validation from EPA Method 23 protocol documentation, EN 1948 standard revisions, Stockholm Convention national implementation reports, and municipal procurement records. Bottom-up installation base enumeration triangulates against top-down market size estimates from trade association disclosures.
Sensitivity analysis across helium price volatility scenarios and technician certification pipeline constraints shapes the analytical framework. Segmentation dimensions encompass product type, application tier, detection technology, and end-user procurement authority across the projection horizon. CAGRs derive from replacement cycle compression rates tied to regulatory protocol updates and emerging jurisdiction enforcement intensity. Industry-specific forecast inputs incorporate magnetic-sector maintenance downtime distributions and quadrupole time-of-flight validation timeline acceleration.
Material uncertainties — Stockholm Convention ratification delays, helium supply disruption severity, chromatography technician training program expansion — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and technology substitution elasticities. Recalibration cycles align with material shifts in EPA Method 23 protocol revisions and EN 1948 standard update schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market